
 Poultry Processing Product Market | 2026-2036
Poultry Processing Product Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Processing Product Market Insights
Foodservice distribution channels serving quick-service restaurants is narrowing as Tyson Foods leverages captive supply networks to secure volume commitments. JBS S.A. anchors South American processing capacity through integrated feed-to-fork operations. Marel competes on automation intensity, deploying robotics that reduce line labor by half in European facilities.
Poultry processing products encompass mechanical systems, thermal equipment, and packaging infrastructure designed to convert live birds into chilled, frozen, or further-processed consumer items, typically operating at line speeds exceeding 140 birds per minute under USDA-inspected conditions. Processing machinery commands the largest installed base due to mandatory evisceration and cut-up operations, while IoT solutions represent the fastest-expanding technology segment as plants retrofit legacy lines with sensor-driven yield optimization. Slaughter equipment remains mature with replacement-driven demand, though margin pools concentrate in robotics where Meyn and Baader Food Processing Machinery specialize in vision-guided deboning systems.
USDA-FSIS pathogen reduction standards and FDA Food Safety Modernization Act traceability rules shape equipment specifications across U.S. facilities, forcing upgrades to antimicrobial intervention systems. E.U. hygiene regulations under EFSA guidance mandate daily clean-in-place validation, driving aftermarket service demand for Marel and CTB maintenance contracts. Stakeholders must weigh automation capex against labor availability curves as wage pressures and immigration policy uncertainty reshape facility economics.
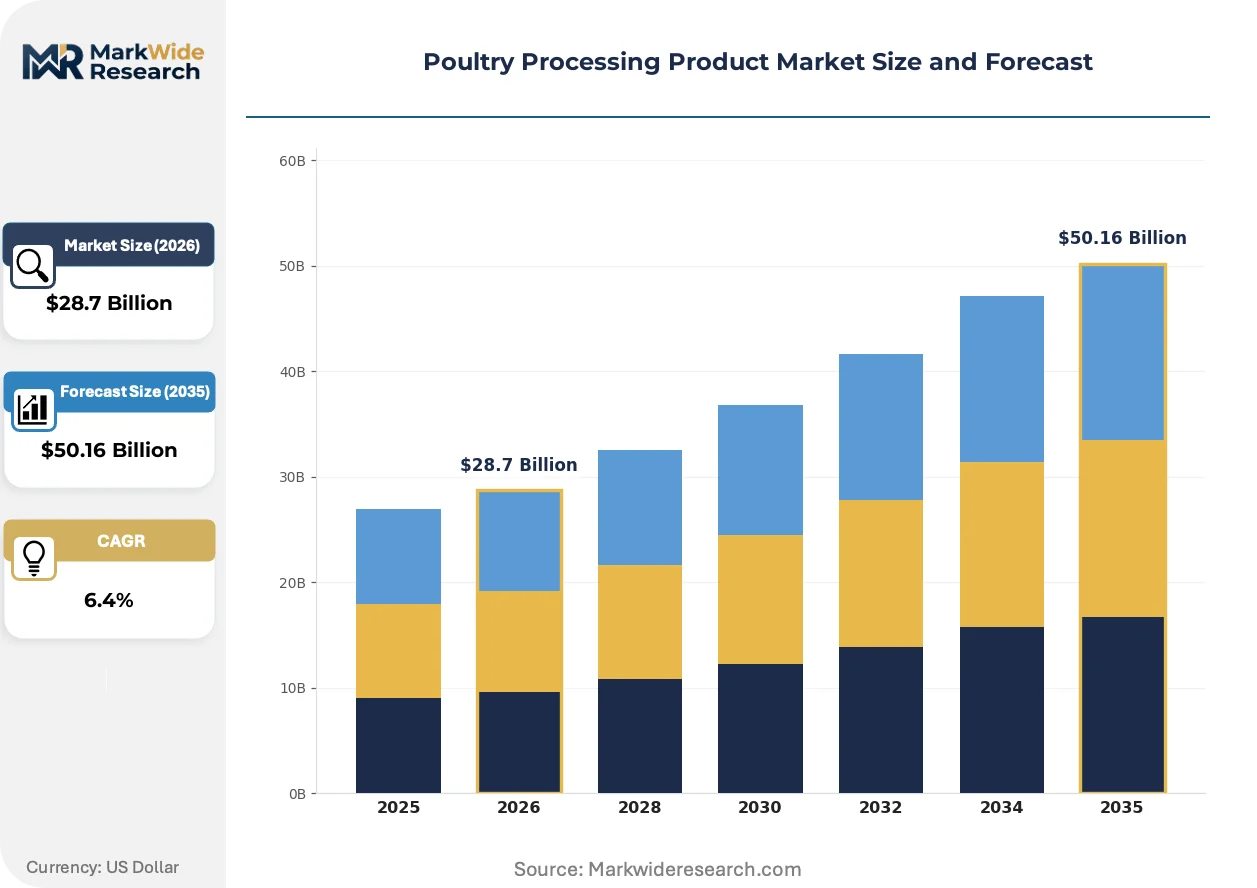
Market Dynamics
Automation capex is compressing facility economics as USDA-FSIS pathogen standards force antimicrobial intervention upgrades across North American plants, while Brazilian integrated processors expand value-added export capacity.
Growth Catalysts
- USDA-FSIS Pathogen Reduction Standards:Mandatory HACCP-based process controls are accelerating equipment replacement cycles in U.S. facilities, driving demand for validated antimicrobial intervention systems.
- Robotics Integration:Vision-guided deboning and cut-up automation is halving line labor requirements in European plants, enabling processors to offset wage inflation and immigration policy uncertainty.
- Brazilian Export Expansion:Integrated feed-to-fork operations in São Paulo and Paraná states are scaling value-added poultry output for Middle Eastern and Asian markets.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 stainless price swings compress margins for equipment fabricators, forcing pass-through delays that strain OEM-processor contracting relationships.
- European Supplier Concentration:Marel, Meyn, and Baader Food Processing Machinery control critical robotics IP, limiting second-source alternatives for North American and Asian buyers.
- Clean-in-Place Validation Burden:EFSA hygiene mandates require daily CIP verification documentation, extending commissioning timelines and inflating aftermarket service contract values.
Strategic Opportunities
- IoT Retrofit Penetration:Legacy line sensor integration for yield optimization represents underdeveloped white space in mid-tier U.S. and Canadian facilities operating sub-100 birds per minute.
- Cell-Cultured Poultry Adjacent Equipment:Bioreactor-scale processing infrastructure for cultivated meat applications is emerging as a parallel R&D investment category for incumbent OEMs.
- India Cold Chain Expansion:FSSAI enforcement of end-to-end temperature monitoring is creating first-mover advantage for packaged poultry equipment vendors in Maharashtra and Karnataka processing clusters.
Industry Challenges
- Mechatronics Talent Scarcity:Vision system calibration and robotic line integration require specialized technicians that outpace vocational training output in U.S. Midwest processing corridors.
- Legacy System Interoperability:Proprietary SCADA architectures from 1990s-era installations block seamless IoT sensor deployment, forcing costly middleware development or full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Processing Product Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slaughter Equipment, Processing Machinery, Packaging Solutions, Refrigeration Systems End User: Poultry Farms, Processing Plants, Retail Outlets, Food Services Technology: Automation, Robotics, IoT Solutions, Thermal Processing Service Type: Maintenance, Consulting, Installation, Training |
| Companies Covered | Tyson Foods, JBS S.A., Pilgrim's Pride, Perdue Farms, Cargill, Marel, CTB, Baader Food Processing Machinery, Meyn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Processing Product Market Trends and Innovations
Processing technology is bifurcating between greenfield automation intensity and brownfield retrofit economics, with regulatory traceability mandates accelerating digital infrastructure investment regardless of facility vintage.
Vision-guided robotic deboning systems are migrating from experimental pilot installations to standard configuration in European and North American greenfield plants. JBS S.A. and Tyson Foods procurement specifications now require vendor demonstration of sub-2% yield loss rates before volume commitments. This technology compression is eliminating manual cone-line labor pools while concentrating margin capture among Meyn and Baader Food Processing Machinery.
EU Green Deal Farm-to-Fork strategy and CSRD reporting obligations are mandating Scope 3 emissions disclosure across poultry supply chains. EFSA guidance on environmental footprint labeling is forcing processors to demand energy consumption data from equipment vendors. German and Dutch facilities are responding by specifying heat-recovery evisceration systems and renewable-powered refrigeration compressors.
Foodservice procurement is consolidating around captive supply networks that bypass traditional distribution intermediaries. Quick-service restaurant chains are negotiating direct volume commitments with Tyson Foods and JBS S.A. processing divisions, compressing independent distributor margins. This channel disintermediation is most advanced in the U.S. Southeast, where Chick-fil-A and Popeyes procurement teams maintain embedded staff at supplier facilities.
Poultry Processing Product Market Segmentation
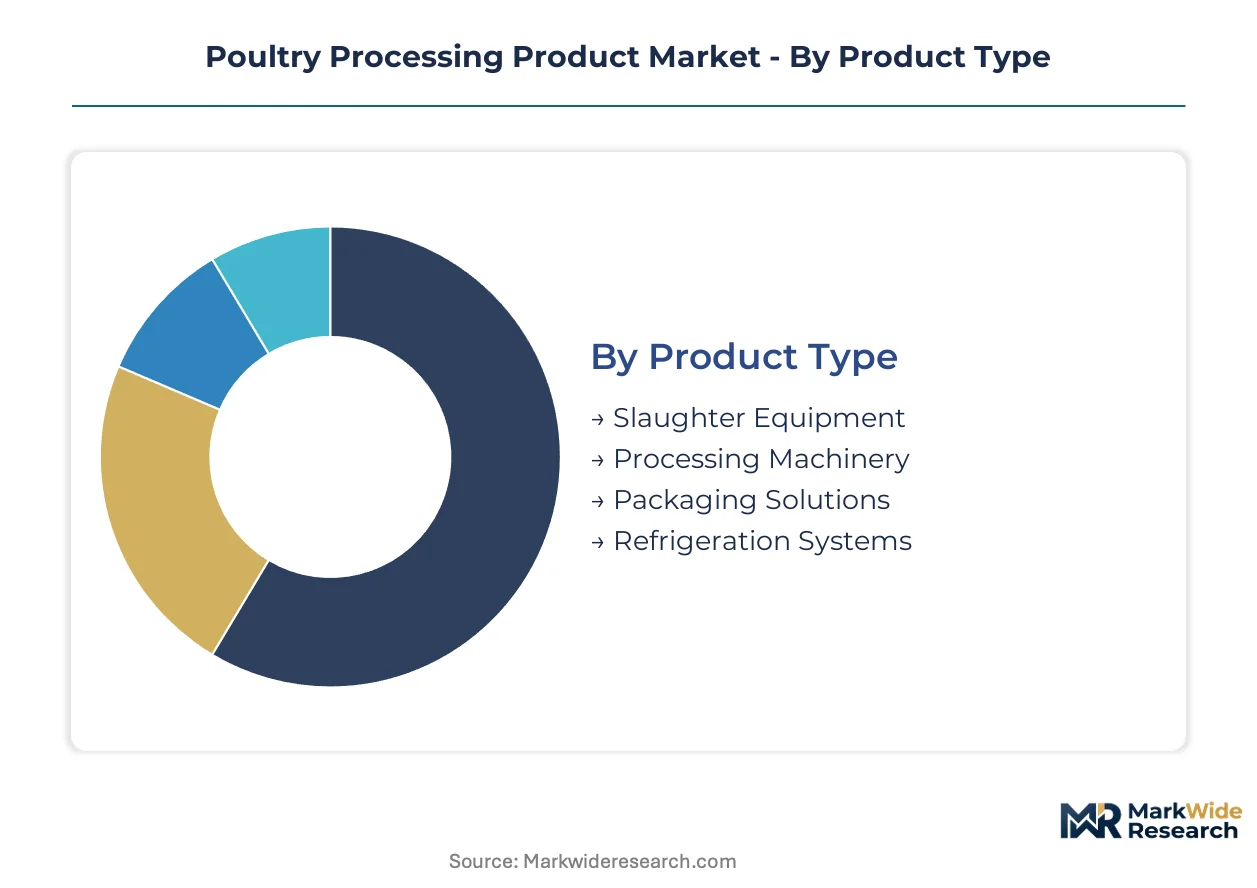
Poultry processing equipment segments reflect divergent capex cycles and regulatory pressures. Equipment categories span mature replacement markets to emerging automation frontiers, while service and technology layers capture recurring revenue streams.
Product Type:
Equipment categories span live bird handling through final packaging, with automation intensity and pathogen control mandates reshaping procurement priorities across facility vintages.
- Slaughter Equipment:Stun-kill-scald systems operating at line speeds exceeding 140 birds per minute under USDA-FSIS inspection protocols. Replacement demand dominates in U.S. Midwest corridors where facilities face mandatory antimicrobial intervention upgrades; margin pools concentrate in stunner calibration and scalder temperature control subsystems.
- Processing Machinery:Evisceration, cut-up, and deboning systems commanding the largest installed base due to mandatory post-slaughter operations. Brazilian integrated processors in São Paulo and Paraná states are scaling value-added output for Middle Eastern and Asian export markets, driving specification for vision-guided yield optimization.
- Packaging Solutions:Modified-atmosphere and vacuum-sealing systems for retail and foodservice distribution formats.
- Refrigeration Systems:Blast chillers and cold storage infrastructure maintaining HACCP temperature corridors.
Established volume favors Processing Machinery; emerging adoption favors IoT-enabled Refrigeration Systems with integrated monitoring.
End User:
Customer types range from captive integrated operations to independent facilities with divergent technical capabilities and vendor relationship structures.
- Processing Plants:USDA-inspected facilities operating at industrial scale with dedicated engineering staff and multi-year vendor contracts. Tyson Foods and JBS S.A. procurement specifications now require sub-2% yield loss demonstrations before volume commitments, concentrating supplier leverage among robotics specialists.
- Food Services:Quick-service restaurant chains and institutional buyers procuring through direct supplier relationships rather than distribution intermediaries. Chick-fil-A and Popeyes maintain embedded procurement staff at supplier facilities in the U.S. Southeast, compressing independent distributor margins.
- Poultry Farms:Live production operations requiring minimal processing equipment beyond on-farm slaughter for niche markets.
- Retail Outlets:Supermarket chains and independent grocers with limited in-house processing capabilities.
Processing Plants capture the dominant equipment spend; Food Services are expanding fastest as direct procurement bypasses traditional channels.
Technology:
Technology layers stratify between proven mechanical systems and emerging digital infrastructure with divergent deployment timelines and talent requirements.
- Robotics:Vision-guided deboning and cut-up automation halving line labor requirements in European facilities. Meyn and Baader Food Processing Machinery control critical IP, limiting second-source alternatives for North American buyers facing wage inflation and immigration policy uncertainty.
- IoT Solutions:Sensor-driven yield optimization and predictive maintenance representing the steepest expansion trajectory as plants retrofit legacy lines. Mid-tier U.S. and Canadian facilities operating sub-100 birds per minute present underdeveloped white space for retrofit penetration.
- Automation:Programmable logic controllers and conveyor integration for standard cut-up and packaging operations.
- Thermal Processing:Cooking, smoking, and pasteurization systems for further-processed poultry categories.
Robotics commands premium pricing in greenfield installations; IoT Solutions are gaining share fastest in brownfield retrofit economics.
Service Type:
Recurring revenue streams scale with equipment complexity and regulatory documentation burdens, shifting vendor relationships from transactional to contractual.
- Maintenance:Preventive and corrective service contracts covering antimicrobial intervention systems and robotics calibration. EFSA hygiene mandates require daily clean-in-place validation documentation, extending commissioning timelines and inflating aftermarket contract values for Marel and CTB.
- Installation:Line commissioning and regulatory compliance verification for new equipment deployments.
- Consulting:Process optimization and HACCP system design for facility upgrades.
- Training:Technician certification for vision system calibration and robotic line integration, addressing mechatronics talent scarcity in U.S. Midwest processing corridors.
Maintenance contracts anchor recurring revenue; Training is expanding as mechatronics talent scarcity outpaces vocational output.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA-FSIS pathogen reduction standards anchor North American equipment procurement cycles, while Brazilian integrated processors and European automation mandates reshape regional competitive dynamics across distinct regulatory environments.
United States
Midwest processing corridors in Iowa and Arkansas drive antimicrobial intervention system upgrades as Tyson Foods and Pilgrim's Pride consolidate captive supply networks. USDA-FSIS HACCP-based process controls mandate validated equipment specifications, accelerating replacement cycles in facilities exceeding 140 birds per minute. Chicago and Springdale processing clusters concentrate engineering talent for robotics integration.
Brazil
São Paulo and Paraná states scale value-added poultry output for Middle Eastern and Asian export markets through JBS S.A. integrated feed-to-fork operations. ANVISA hygiene regulations align with destination market standards, forcing equipment harmonization across processing lines. Santa Catarina emerging as secondary automation investment corridor for deboning system deployment.
Germany
Bavaria and Lower Saxony facilities respond to EU Green Deal Farm-to-Fork strategy with heat-recovery evisceration specifications and renewable-powered refrigeration mandates. EFSA hygiene regulations require daily clean-in-place validation documentation, extending commissioning timelines for Marel and Meyn maintenance contracts. Cologne processing engineering corridor anchors robotics calibration expertise.
China
Shandong and Guangdong provinces expand automated cut-up capacity as domestic quick-service restaurant chains consolidate procurement through direct supplier relationships. SAMR food safety traceability rules under GB standards force digital infrastructure retrofit in legacy facilities. Qingdao processing cluster concentrates domestic equipment fabricator capacity for mid-tier plant upgrades.
India
Maharashtra and Karnataka processing clusters attract first-mover equipment vendors as FSSAI enforces end-to-end cold chain temperature monitoring for packaged poultry distribution. PLI scheme incentives for food processing infrastructure accelerate greenfield automation investment around Mumbai and Bangalore. Hyderabad emerging as secondary hub for technician training programs addressing mechatronics talent scarcity.
Poultry Processing Product Market Competitive Landscape
Integrated protein conglomerates and specialized automation fabricators split the market into divergent capability tiers. Tyson Foods and JBS S.A. leverage captive supply networks to secure volume commitments and compress independent distributor margins. Equipment vendors stratify between European robotics specialists controlling critical IP and Asian fabricators competing on stainless steel fabrication scale. Dominant competitive moves include backward integration into feed-to-fork operations and strategic partnerships for IoT retrofit deployment.
Within the European robotics tier, Marel, Meyn, and Baader Food Processing Machinery occupy positions defined by vision-guided deboning system specialization. These Netherlands-based and German fabricators exemplify the premium-equipment archetype where proprietary IP limits second-source alternatives for North American buyers. Tyson Foods and JBS S.A. represent the integrated-processor archetype, anchoring demand concentration through direct procurement specifications that require sub-2% yield loss demonstrations before volume commitments.
| Leading Market Players |
|---|
| Tyson Foods |
| JBS S.A. |
| Pilgrim's Pride |
| Perdue Farms |
| Cargill |
| Marel |
| CTB |
| Baader Food Processing Machinery |
| Meyn |
| Others |
Pricing and Supply Chain Analysis
Grade 304 and 316 stainless steel price volatility compresses equipment fabricator margins and forces pass-through delays that strain OEM-processor contracting relationships, simultaneously widening pricing tier spreads between captive integrated buyers and independent facilities while concentrating supply chain leverage among European robotics specialists with proprietary IP.
Pricing Analysis
Configured-to-order pricing for vision-guided deboning systems commands substantial premiums over standard cut-up equipment, with three-tier pricing structure across premium, standard, and economy levels anchored by robotics IP concentration, USDA-FSIS certification grade, and after-sales service bundling. Price differentiation stems from automation intensity and vendor technical support depth. Pricing pressure intensifies in mid-tier segments as Brazilian integrated processors scale volume commitments. Independent facilities operating sub-100 birds per minute exhibit highest price sensitivity; Tyson Foods and JBS S.A. procurement teams leverage captive volume for standard-tier discounts.
Supply Chain Analysis
Upstream feedstock dependency on specialty-grade stainless steel draws from German, Dutch, and Chinese metallurgical suppliers, with fabrication capacity clustering in Denmark, Germany, and the Netherlands for European OEMs and Shandong province for domestic Chinese equipment. Critical components include precision servo motors, machine vision cameras, and antimicrobial intervention nozzles. Single-source vulnerability concentrates in robotics IP held by Netherlands-based and German fabricators. Distribution runs through direct vendor-processor contracts for large integrated operators and regional equipment distributors serving independent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against cell-cultured poultry processing equipment as parallel R&D investment by incumbent OEMs signals long-term displacement risk for traditional slaughter and deboning infrastructure.
For Market Incumbents:Harden defensive positioning through backward integration into proprietary robotics calibration services and captive maintenance contract structures that lock in processor switching costs. Deepen technical support moats around vision system IP to offset emerging competition from Asian fabricators. Prioritize certification investment for USDA-FSIS antimicrobial intervention validation to maintain specification compliance.
For New Entrants and Emerging Players:Pursue IoT retrofit penetration in mid-tier U.S. and Canadian facilities operating legacy lines below 100 birds per minute, where sensor-driven yield optimization remains underdeveloped white space. Target Maharashtra and Karnataka processing clusters in India as FSSAI cold chain enforcement creates first-mover advantage for packaged poultry equipment vendors. Deploy direct sales teams with embedded technical consultants rather than distributor intermediaries.
For Investors and Strategic Acquirers:EU Green Deal Farm-to-Fork strategy and CSRD Scope 3 disclosure mandates reshape the acquisition landscape by elevating energy-efficient equipment vendors with heat-recovery and renewable-powered refrigeration capabilities. Long-term viability favors OEMs with service contract recurring revenue streams and robotics IP portfolios. Monitor ANVISA-Brazil alignment with destination market standards as signal for Brazilian export capacity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotics IP Acquisition | Vision-guided deboning patents from Meyn or Baader consolidate automation leverage against Asian competitors. |
| IoT Platform Integration | Sensor-driven yield optimization retrofits capture recurring SaaS revenue from mid-tier U.S. facilities. |
| Backward Integration into Maintenance | Captive service contracts for EFSA-mandated CIP validation extend commissioning timelines and inflate aftermarket values. |
| Geographic Expansion to India | FSSAI cold chain enforcement in Maharashtra and Karnataka creates first-mover equipment deployment opportunity. |
| Cell-Cultured Adjacent R&D | Bioreactor-scale processing infrastructure investment hedges against long-term substitution of traditional poultry lines. |
Research Methodology
Desk research of USDA-FSIS regulatory filings, ANVISA hygiene protocols, EFSA guidance documents, and equipment vendor technical specifications preceded structured interviews with plant engineering directors at integrated processors, procurement managers at quick-service restaurant chains, aftermarket service heads at Marel and CTB, and robotics calibration technicians in European facilities. Secondary validation drew from SEC 10-K disclosures, customs trade data for stainless steel equipment imports, and industry association capacity surveys. Bottom-up facility-level equipment spend estimates triangulated against top-down market value reconstructions.
Assumption sets held regulatory enforcement timelines and labor cost inflation curves fixed while varying automation adoption rates and Brazilian export volume growth across sensitivity scenarios. Segmentation dimensions modeled encompassed equipment category, end-user type, technology layer, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and greenfield capacity addition pipelines. Industry-specific inputs included USDA-FSIS pathogen reduction compliance costs and E.U. Green Deal energy efficiency specifications.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, immigration policy uncertainty affecting labor availability, or trade tariff structures would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and processor capex commitment levels. Cross-checking against equipment vendor order backlog disclosures and processor earnings call commentary is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Forage Feed Market