
 Aquaculture Healthcare Market | 2026-2036
Aquaculture Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Healthcare Market Analysis
Pharmaceutical-grade formulation standards are unwinding cost-competitive dynamics across aquaculture healthcare as producers absorb higher compliance burdens for residue testing and withdrawal protocols. Zoetis Inc. leverages its biologicals portfolio to dominate vaccine development for salmonid rhabdoviruses, while Merck & Co., Inc. anchors its position through R&D intensity in parasiticide formulations for warm-water species. Virbac S.A. specializes in bath treatment delivery systems that reduce labor intensity for Mediterranean sea bream and sea bass operations.
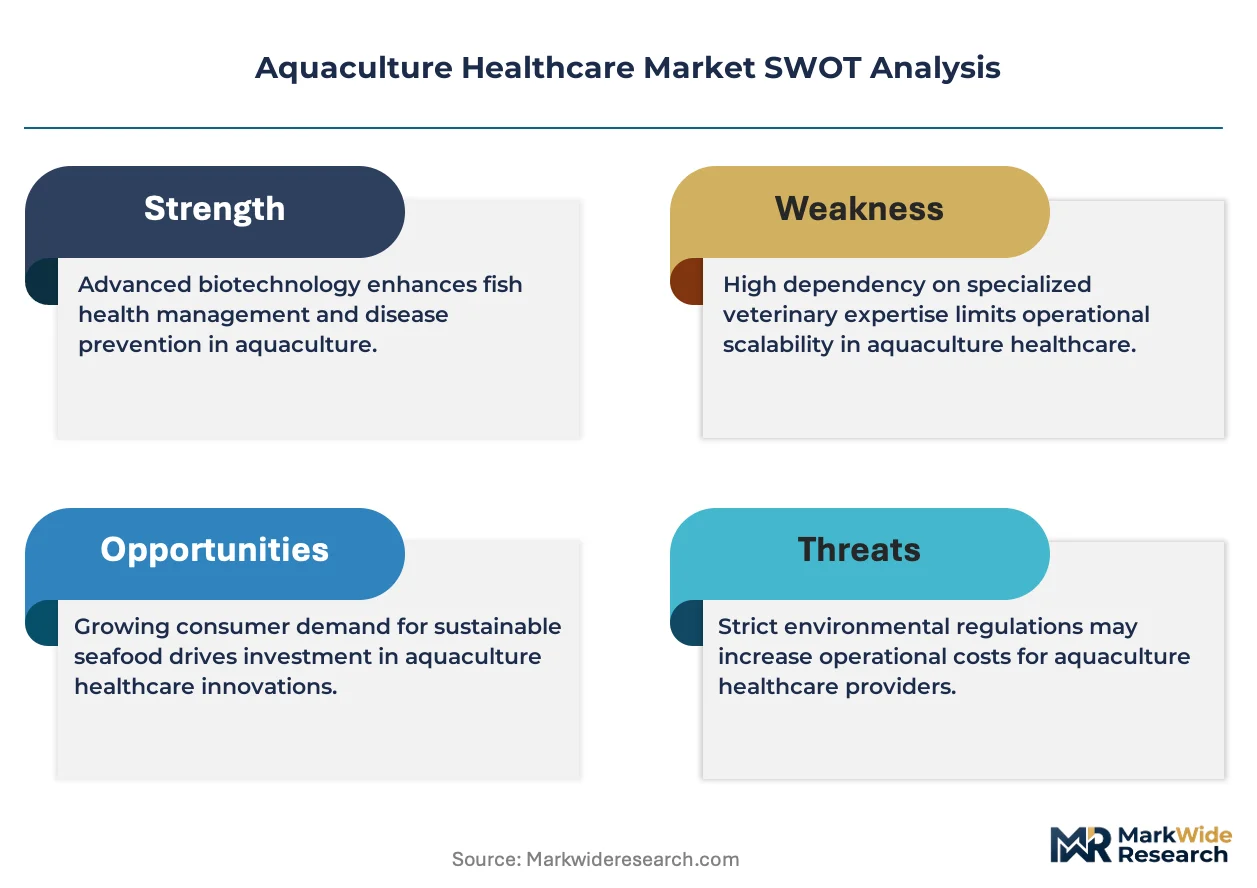
Aquaculture healthcare encompasses disease prevention, diagnosis, and treatment interventions administered to farmed finfish, shellfish, and crustaceans, encompassing active pharmaceutical ingredients with specified purity thresholds exceeding ninety-eight percent for injectable therapeutics, formulated to maintain stock health in intensive production systems. Biologicals and vaccines command structural priority within product type segmentation as regulatory pressure on antibiotic residues redirects investment toward immunoprophylaxis platforms. Feed additives represent the fastest-expanding delivery mode category, integrating functional ingredients directly into ration formulations to reduce handling stress and improve bioavailability across salmonid and shrimp production cycles.
EMA residue limit frameworks and FDA aquaculture drug approval pathways jointly constrain market access for novel therapeutics, compelling manufacturers to navigate parallel regulatory dossier requirements across Atlantic and Pacific supply basins. EU Green Deal sustainable aquaculture provisions and REACH chemical authorization standards further elevate documentation burdens for chemical-based treatments entering European supply chains. Stakeholders must monitor evolving bacteriophage therapy regulatory classifications and determine whether to allocate development resources toward live biotherapeutic platforms or reinforced conventional vaccine adjuvant systems.
Market Dynamics
EMA residue limit frameworks and FDA aquaculture drug approval pathways are compressing development timelines for novel therapeutics, forcing manufacturers to front-load regulatory dossier costs while producers absorb extended withdrawal periods and testing burdens.
Growth Catalysts
- EU Green Deal sustainable aquaculture provisions:These mandates redirect investment toward immunoprophylaxis platforms and away from antibiotic-dependent treatment protocols across Mediterranean sea bream and sea bass operations.
- Intensive pangasius production in Vietnam's Mekong Delta:Parasitic infection pressure and water quality degradation drive feed additive demand for preventive health integration directly into ration formulations.
- Salmonid rhabdovirus vaccine platforms:Biologicals command structural priority as Norwegian Atlantic salmon producers accelerate adoption following stricter residue enforcement.
Market Restraints
- Parallel regulatory dossier requirements:EMA and FDA pathways compel manufacturers to duplicate documentation burdens across Atlantic and Pacific supply basins, elevating fixed costs for market entry.
- Active pharmaceutical ingredient purity thresholds:Injectable therapeutics must exceed ninety-eight percent purity, constraining formulation flexibility and compressing margins for cost-competitive producers.
- Chemical-based treatment authorization:REACH chemical authorization standards elevate documentation burdens for treatments entering European supply chains, disadvantaging conventional parasiticide developers.
Strategic Opportunities
- Bacteriophage therapy regulatory classifications:Evolving frameworks for live biotherapeutic platforms create white space for manufacturers allocating R&D resources away from conventional vaccine adjuvant systems.
- Bath treatment delivery systems:Labor intensity reduction for Mediterranean producers opens channel for specialized equipment integration alongside pharmaceutical formulations.
- Functional ingredient integration:Feed additive delivery modes that reduce handling stress represent underpenetrated positioning for bioavailability enhancement across shrimp production cycles in Southeast Asia.
Industry Challenges
- Veterinary aquatic pathology specialization:Diagnostic capability scarcity constrains disease outbreak response times for intensive operations across multiple production systems.
- Withdrawal protocol compliance timing:Extended residue clearance periods disrupt harvest scheduling and inventory rotation for producers serving export-certified supply chains.
- Biologicals cold chain integrity:Vaccine potency maintenance requires capital-intensive infrastructure investment that fragments competitive positioning between integrated and non-integrated operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Healthcare Market |
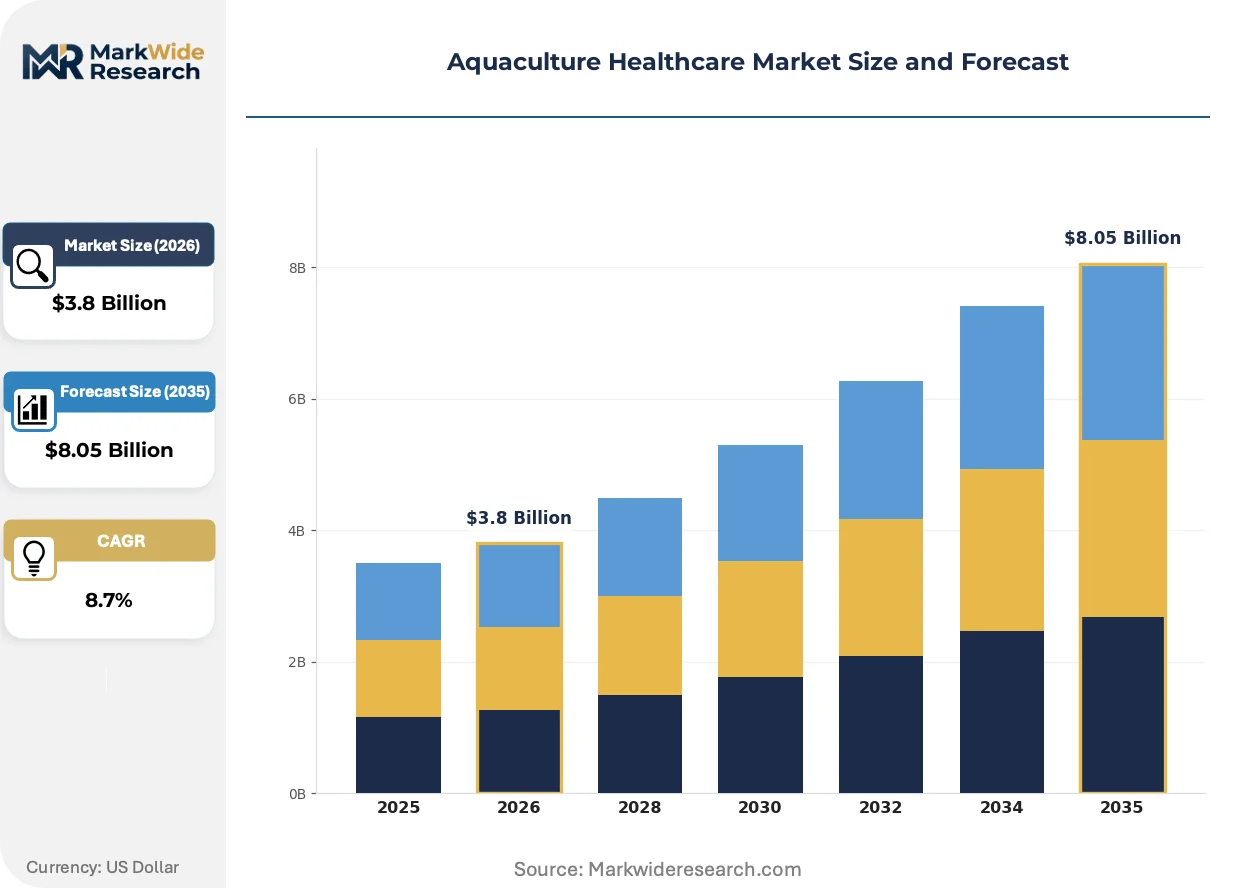
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologicals, Chemicals, Vaccines, Pharmaceuticals Therapy Area: Infectious Diseases, Nutritional Disorders, Parasitic Infections, Environmental Stress Delivery Mode: Injectables, Feed Additives, Bath Treatments, Oral Medications End User: Fish Farms, Shellfish Farms, Research Institutions, Aquaculture Service Providers |
| Companies Covered | Zoetis Inc., Merck & Co., Inc., Elanco Animal Health, Xylem Inc., Archer Daniels Midland Company, Virbac S.A., Alltech Inc., Benchmark Holdings Plc., Pentair plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Healthcare Market Emerging Trajectories
Biological delivery mechanisms and regulatory compliance architectures are actively restructuring competitive positioning in aquaculture healthcare, with technology convergence and procurement model evolution creating divergent pathways for market participants.
Recombinant subunit vaccines targeting salmonid rhabdoviruses are supplanting traditional inactivated whole-cell formulations among Norwegian and Chilean Atlantic salmon producers. These platforms reduce adjuvant-related tissue reactions and shorten withdrawal intervals. The structural consequence is compressing market access for conventional vaccine developers unable to pivot toward precision antigen design.
REACH chemical authorization standards and EU Green Deal sustainable aquaculture provisions are tightening entry criteria for novel parasiticides and antibacterials across European supply chains. Manufacturers must now submit extended environmental fate dossiers before receiving market authorization. Warm-water species operations in Mediterranean zones face the most acute reformulation pressure, accelerating partnership activity between chemical developers and biologicals specialists.
Certification-driven procurement is consolidating buyer power among export-oriented producers serving EU and North American retail channels. Third-party aquaculture stewardship council accreditation now functions as a de facto gatekeeper for feed additive and vaccine supplier selection. This behavioral shift is most visible across Vietnam's pangasius sector, where integrated processors are unbundling after-sales technical service from product supply contracts to reduce vendor dependency.
Aquaculture Healthcare Market Segmentation
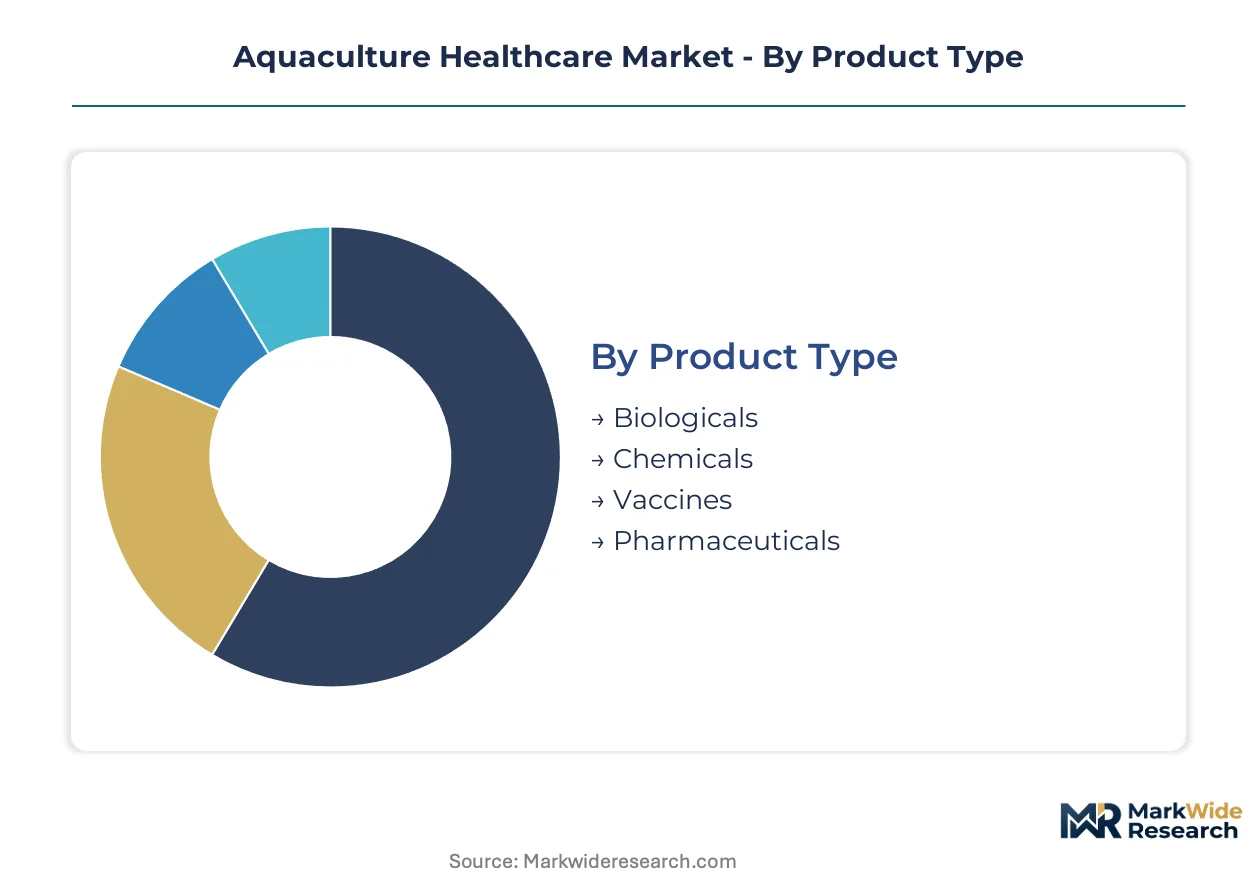
Segmentation in aquaculture healthcare reveals divergent commercial logics across species biology, regulatory tolerance, and production intensity. Each category maps distinct investment priorities for manufacturers navigating residue limits and delivery innovation.
Product Type:
Domestic consumption in Norway and Chile concentrates biologicals demand, while export-dependent producers in Vietnam and Thailand absorb chemical treatments for cost-sensitive shrimp cycles.
- Biologicals:Recombinant subunit vaccines and immunostimulants engineered for salmonid rhabdoviruses command premium positioning among Norwegian Atlantic salmon producers facing EMA residue enforcement. Chilean operations mirror this trajectory as export certification tightens.
- Vaccines:Inactivated whole-cell formulations retain installed base across Mediterranean sea bream and sea bass operations, though adjuvant-related tissue reactions accelerate displacement by precision antigen platforms in high-value supply chains.
- Chemicals:Parasiticides and antibacterials face REACH authorization pressure across European supply chains; Vietnamese pangasius farms absorb residual volume for cost-competitive preventive programs.
- Pharmaceuticals:Injectable therapeutics exceeding ninety-eight percent API purity serve certified export producers in Scotland and Canada with extended withdrawal protocols.
Biologicals holds the largest share; momentum sits with vaccines.
Therapy Area:
Cost tiers separate emergency intervention from preventive integration, with premium pricing attaching to rapid-response infectious disease solutions versus commoditized environmental stress management.
- Infectious Diseases:Bacterial and viral outbreak response commands immediate procurement authority across intensive operations; Norwegian salmon farms prioritize Vibrio and rhabdovirus coverage within biologicals budgets.
- Parasitic Infections:Sea lice and gill parasite treatments concentrate R&D investment among North Atlantic producers; chemical resistance patterns in Chilean waters accelerate biological alternative development.
- Nutritional Disorders:Feed-integrated mineral and vitamin supplementation penetrates Southeast Asian shrimp ponds facing intensification stress; Vietnamese Mekong Delta operations embed these into standard ration formulations.
- Environmental Stress:Water quality degradation mitigation represents lowest-margin category, with generic antioxidant and osmoregulatory additives serving fragmented smallholder bases across Indonesian and Bangladeshi coastal zones.
Infectious diseases commands premium pricing; parasitic infections is climbing the fastest.
Delivery Mode:
Application method determines labor intensity and bioavailability trade-offs, with automated systems gaining share in capital-intensive Atlantic salmon operations versus manual protocols in small-scale warm-water production.
- Feed Additives:Functional ingredients integrated directly into ration formulations reduce handling stress and improve uptake consistency; Vietnamese pangasius processors specify these for ASC certification compliance.
- Injectables:Precision dosing for high-value broodstock and vaccination programs dominates Norwegian and Scottish salmonid operations; cold chain requirements fragment competitive positioning.
- Bath Treatments:Labor-reducing delivery systems specialized by Virbac S.A. serve Mediterranean sea bream and sea bass producers with reduced workforce dependency.
- Oral Medications:Cost-competitive antibacterials retain foothold in Indonesian tilapia and Bangladeshi carp polyculture systems with limited diagnostic infrastructure.
Feed additives holds the largest share; injectables is gaining share fastest.
End User:
Customer scale and integration level determine procurement sophistication, with consolidated processors exercising vendor consolidation power versus fragmented service provider intermediation.
- Fish Farms:Atlantic salmon producers in Norway and Chile drive biologicals volume; Vietnamese pangasius integrators unbundle technical service from product supply to reduce vendor dependency.
- Shellfish Farms:Mussel and oyster operations in Scotland and New Zealand concentrate preventive health spending on hatchery-stage pathogen exclusion with limited therapeutic intervention.
- Aquaculture Service Providers:Diagnostic and treatment outsourcing intermediates fragmented smallholder access across Indonesian and Thai coastal provinces; capability scarcity constrains outbreak response velocity.
- Research Institutions:Bacteriophage therapy and live biotherapeutic development partnerships concentrate among Norwegian veterinary institutes and Chilean university laboratories.
Fish farms holds the largest share; aquaculture service providers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among Atlantic salmon producers facing EMA residue enforcement and Southeast Asian shrimp operations managing intensification stress. Norwegian and Chilean farms drive biologicals volume. Vietnamese pangasius integrators absorb preventive health spending.
Norway
Atlantic salmon rhabdovirus vaccine demand accelerates as EMA residue limits tighten antibiotic alternatives. The Norwegian Medicines Agency enforces extended withdrawal protocols for chemical treatments. Bergen-based producers consolidate procurement power through integrated processing control.
Vietnam
Pangasius intensive operations in the Mekong Delta drive feed additive integration for parasitic infection management. The Ministry of Agriculture and Rural Development implements aquaculture stewardship certification requirements. Can Tho processing clusters unbundle technical service contracts to reduce supplier dependency.
Chile
Salmonid export certification redirects investment toward recombinant subunit vaccine platforms. The National Fisheries Service aligns sanitary protocols with EU import standards. Puerto Montt aquaculture zones experience biologicals cold chain infrastructure expansion.
Thailand
Shrimp farming preventive health programs intensify amid bacterial disease outbreak pressure. The Department of Fisheries mandates residue testing for export-certified supply chains. Samut Sakhon processing districts concentrate feed additive specification authority among integrated exporters.
Spain
Mediterranean sea bream and sea bass operations absorb REACH chemical authorization burdens for parasiticide reformulation. EU Green Deal sustainable aquaculture provisions redirect investment toward bath treatment delivery systems. Murcia aquaculture clusters specialize in labor-reducing pharmaceutical application equipment.
Aquaculture Healthcare Market Vendor Landscape
Concentration sits with diversified animal health conglomerates commanding biologicals portfolios and regional specialists anchoring delivery system innovation. The market structure tiers between scale-driven vaccine developers and formulation-focused warm-water species experts. Three archetypes dominate: integrated pharmaceutical-biologicals platforms, parasiticide specialists with bath treatment capabilities, and feed additive integrators serving certification-driven procurement. Competitive moves center on regulatory dossier consolidation across Atlantic and Pacific pathways and cold chain infrastructure partnerships.
Within the integrated pharmaceutical tier, Zoetis Inc. and Merck & Co., Inc. exemplify scale-driven biologicals development archetypes, while Virbac S.A. occupies a specialist position in delivery system innovation for Mediterranean producers. These three entities represent divergent strategic postures: conglomerate-backed vaccine platforms, diversified parasiticide portfolios, and equipment-integrated formulation services.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck & Co., Inc. |
| Elanco Animal Health |
| Xylem Inc. |
| Archer Daniels Midland Company |
| Virbac S.A. |
| Alltech Inc. |
| Benchmark Holdings Plc. |
| Pentair plc. |
| Others |
Supply Flow & Price Mechanics
Cold chain infrastructure scale economies among Norwegian Atlantic salmon producers compress unit biologicals costs while elevating price floors for non-integrated operators across Vietnam and Thailand. Capacity utilization at Bergen-based vaccine formulation facilities shapes supply concentration and pricing power distribution across export-certified supply chains.
Pricing Analysis
EMA residue limit frameworks dictate the pricing tier structure across European supply chains, separating premium-grade recombinant subunit vaccines from standard inactivated formulations and economy-tier chemical parasiticides. Price differentiation hinges on ASC certification compliance and cold chain integrity guarantees, with Vietnamese pangasius integrators exhibiting highest sensitivity due to unbundled technical service contracts. Pricing pressure intensifies downward among chemical-based treatments as REACH authorization burdens accumulate.
Supply Chain Analysis
Container availability constraints on Rotterdam-Singapore trade lanes elevate inbound logistics costs for temperature-sensitive biologicals shipments from European formulation sites to Southeast Asian distribution hubs. Supply concentrates in Norway, Chile, and Vietnam, with active pharmaceutical ingredient purity testing and adjuvant sourcing drawing from Swiss and German specialty chemical producers. Single-source vulnerability sits with concentrated salmonid rhabdovirus vaccine production. Distribution runs through integrated processor procurement channels and aquaculture service provider intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among integrated Atlantic salmon processors and Vietnamese pangasius exporters, fragmenting vendor relationships and compressing margins for non-differentiated suppliers.
For Market Incumbents: Fortify cold chain partnerships with Puerto Montt and Bergen logistics operators to defend biologicals potency guarantees against emerging bath treatment delivery specialists. Deepen backward integration into adjuvant formulation capabilities to offset REACH-driven chemical authorization cost inflation.
For New Entrants and Emerging Players: Lead with bacteriophage therapy platforms targeting Chilean sea lice resistance patterns, the most penetrable white space beneath incumbent parasiticide portfolios. Pursue ASC certification co-development agreements with Can Tho processing clusters to bypass established feed additive supplier relationships.
For Investors and Strategic Acquirers: Delivery-integrated pharmaceutical specialists serving Mediterranean sea bream operations present acquisition exposure to EU Green Deal compliance spending acceleration. Long-term viability centers on regulatory dossier consolidation capabilities across EMA and FDA pathways. Watch for bacteriophage therapy regulatory classification clarity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Partnership | Bergen-based biologicals potency maintenance secures Norwegian salmon farm procurement loyalty. |
| Regulatory Dossier Consolidation | Parallel EMA-FDA pathway navigation reduces fixed cost burdens for transatlantic market entry. |
| ASC Certification Co-Development | Vietnamese pangasius processor compliance integration opens feed additive specification authority. |
| Recombinant Subunit Vaccine Pipeline | Precision antigen design displaces adjuvant-heavy formulations among export-certified Chilean producers. |
| Bath Treatment Delivery System Integration | Murcia equipment specialization reduces Mediterranean sea bream labor intensity and workforce dependency. |
Methodological Framework
A spread of perspectives from biologicals manufacturing executives, regulatory affairs specialists at EMA-notified bodies, Vietnamese pangasius procurement directors, and Mediterranean aquaculture veterinarians converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA aquaculture drug approval databases, EMA veterinary medicines registration records, and customs trade flow analysis. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Segmentation dimensions modeled span product type, therapy area, delivery mode, and end user across the projection horizon. CAGRs derive from biologicals adoption trajectories in Norwegian salmon operations, feed additive penetration rates in Vietnamese pangasius cycles, and chemical treatment displacement curves under REACH authorization pressure. Industry-specific inputs include cold chain infrastructure expansion timelines and ASC certification rollout velocity.
The analysis sits within stated boundaries; outcomes outside EMA residue enforcement intensity, FDA approval pathway duration, or bacteriophage therapy regulatory classification would require recalibration. Forecasts reflect assumptions on certification-driven procurement consolidation and biologicals cold chain integrity maintenance. Disease outbreak frequency and chemical resistance pattern evolution represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Aquaculture Pumps Market