
 Bus Rapid Transit System (BRT) Market | 2026-2036
Bus Rapid Transit System (BRT) Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Rapid Transit System (BRT) Market Outlook
Market Context
Bus procurement channels across emerging economies is fragmenting as municipal authorities bypass national distributors and contract directly with manufacturers. Volvo Group leverages its electric chassis platform to secure corridor-specific contracts in Latin America and Southeast Asia. BYD Company Limited anchors its position through integrated battery production and localized assembly partnerships. Tata Motors competes aggressively on total cost of ownership for diesel and CNG fleets serving high-volume South Asian corridors.
Technical Definition and Segment Structure
A Bus Rapid Transit System constitutes a high-capacity urban transport mode combining dedicated right-of-way lanes, level-boarding platforms, off-vehicle fare collection, and signal priority to achieve rail-like performance at bus-based capital cost. Systems typically operate at 20–35 km/h commercial speeds with headways below five minutes during peak periods. Electric buses within the vehicle type segment command expanding capital allocation as battery energy density improvements and charging infrastructure standardization reduce lifecycle cost gaps versus diesel equivalents. Smart ticketing technology generates disproportionate margin pools through platform licensing and data monetization, while dedicated lanes represent the most mature infrastructure category with established engineering templates.
Regulatory Environment and Outlook
Environmental regulators including the EPA in the United States, MEE in China, and the EU Green Deal framework in Europe enforce progressively tighter fleet emission standards that compel electrification or alternative fuel adoption. National transport ministries in Brazil, India, and Indonesia couple these environmental mandates with domestic content requirements that shape supplier qualification criteria. Stakeholders must monitor how subsidy phase-out schedules and local battery supply chain development alter total cost of ownership calculations across corridor development pipelines.
Market Dynamics
Electrification mandates from environmental regulators are compressing fleet replacement cycles and reshaping supplier qualification criteria across corridor development pipelines. Municipal authorities now prioritize battery-electric chassis platforms that deliver rail-like performance metrics at reduced lifecycle cost.
Growth Catalysts
- EU Green Deal framework:Binding emission reduction targets for urban transport fleets accelerate diesel phase-out schedules across European metropolitan areas. Cities must achieve 55% CO2 reduction by 2030.
- Brazil federal infrastructure programs:Dedicated funding corridors in São Paulo, Curitiba, and Belo Horizonte expand network mileage and vehicle procurement volumes. ANVISA safety certification streamlines import approvals.
- Level-boarding platform standardization:Universal dock height specifications reduce vehicle-platform integration costs and accelerate manufacturer qualification processes for new corridor entrants.
Market Restraints
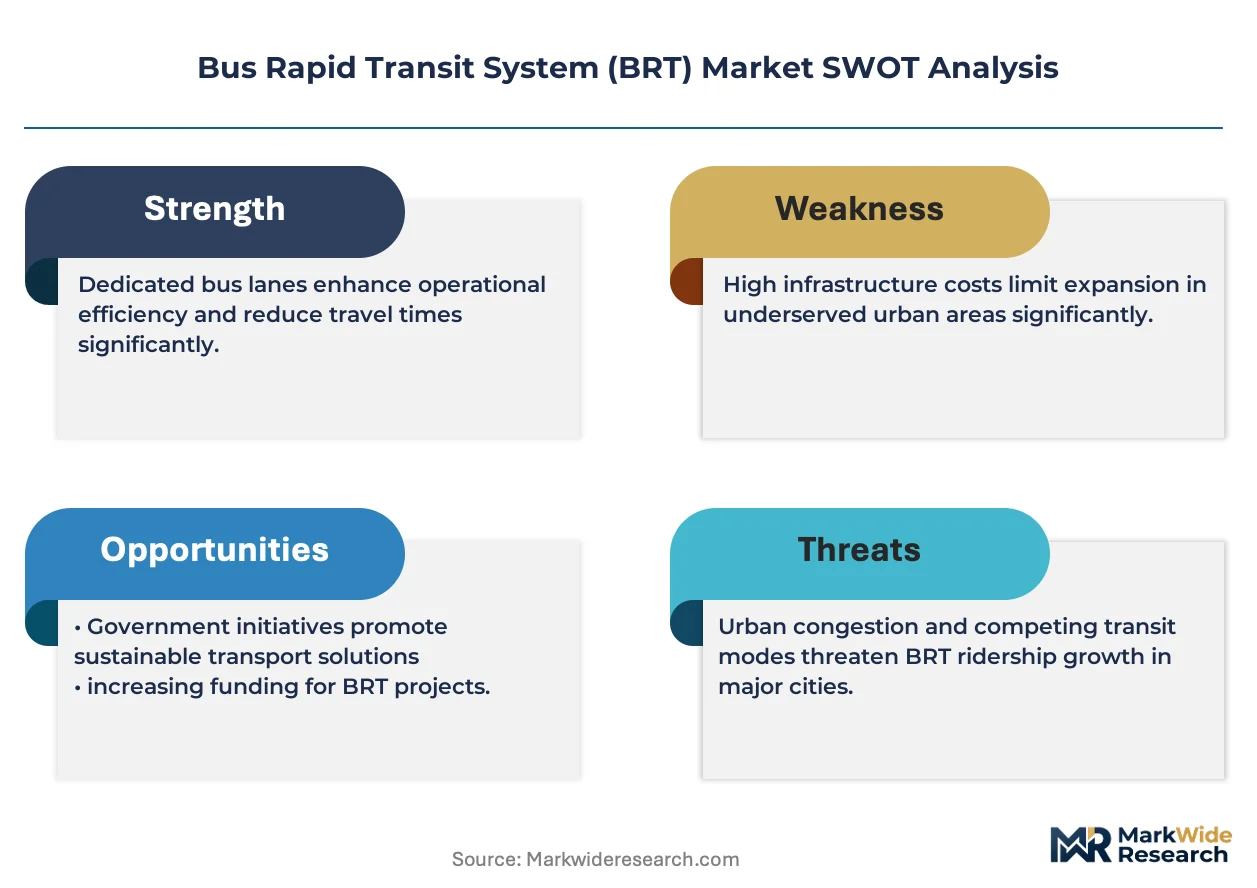
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in China creates input cost volatility and geopolitical exposure for fleet operators planning 10-year electrification roadmaps.
- Domestic content requirements:India's PLI scheme and Indonesia's local assembly mandates force foreign chassis suppliers to establish regional manufacturing partnerships, extending time-to-market by 18-24 months.
- Right-of-way acquisition costs:Dense urban land values in megacities like Mexico City and Jakarta inflate corridor infrastructure budgets beyond original feasibility projections.
Strategic Opportunities
- Smart ticketing data monetization:Platform licensing revenue from aggregated passenger flow analytics creates recurring income streams independent of vehicle sales or maintenance contracts.
- Colombia corridor expansion:Bogotá's TransMilenio network plans 50 km of additional dedicated lanes by 2028, opening procurement windows for articulated electric fleets with opportunity charging infrastructure.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet operators to sell grid stabilization services, offsetting capital costs through ancillary revenue participation.
Industry Challenges
- High-voltage technician certification:Maintenance workforce gaps for 800V battery systems delay depot readiness and inflate training budgets for municipal transit authorities transitioning from diesel.
- Interoperability with legacy fare collection:Smart card migration from closed-loop to account-based systems requires middleware development that fragments vendor ecosystems and extends integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Rapid Transit System (BRT) Market |
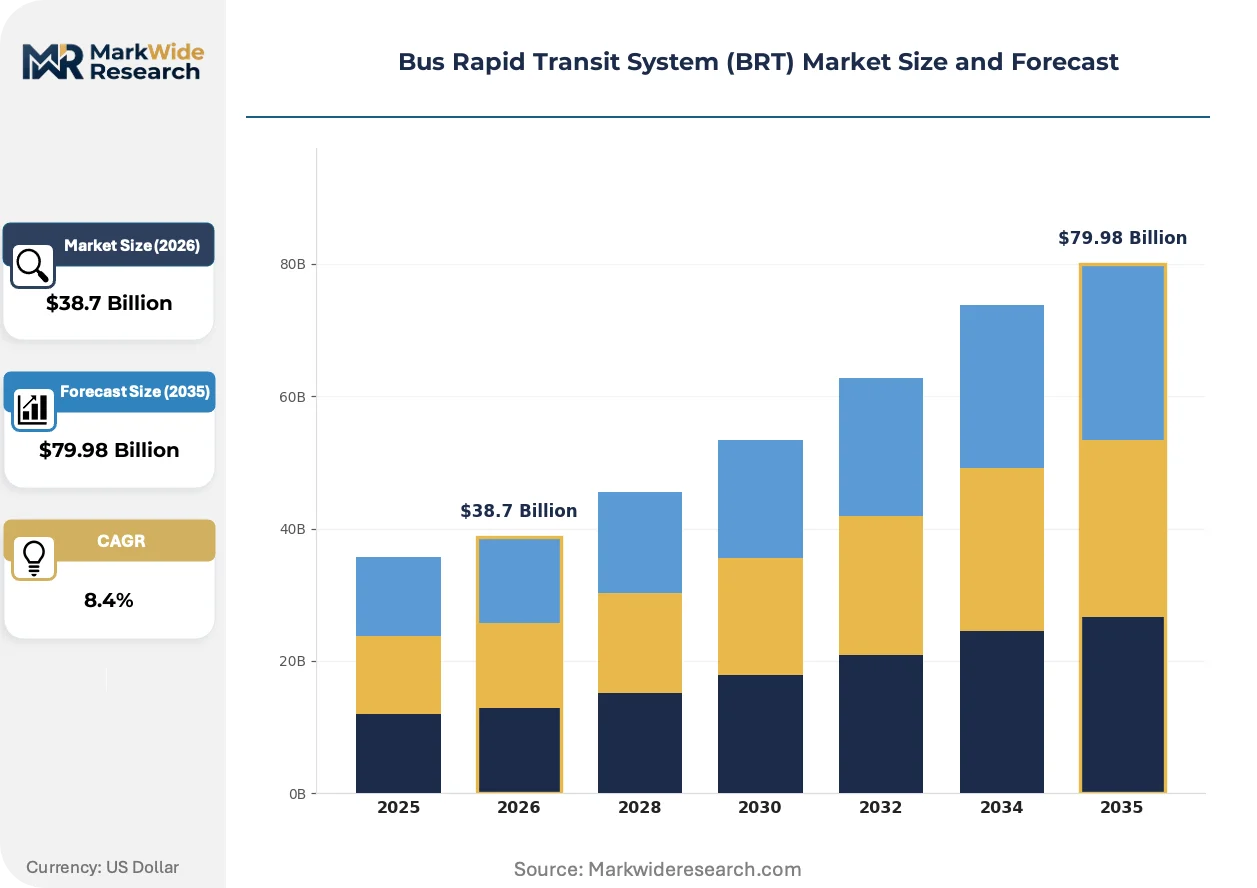
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Operators, Public Sector, Hybrid Models, Community Services Technology: Dedicated Lanes, Smart Ticketing, Real-Time Tracking, Automated Systems End User: Commuters, Tourists, Local Residents, Business Travelers Vehicle Type: Low-Floor Buses, Articulated Buses, Electric Buses, Standard Buses |
| Companies Covered | Marcopolo, Ashok Leyland, Volvo Group, Xiamen King Long Motor Group, MAN, Daimler, Tata Motors, BYD Company Limited, Zhengzhou Yutong Bus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Rapid Transit System (BRT) Market Strategic Shifts
Digital twin technology is virtualizing corridor design and fleet deployment workflows, compressing planning cycles and reducing capital risk for municipal sponsors. Three interconnected developments define the current innovation trajectory.
Digital twin simulation software is virtualizing infrastructure planning by modeling traffic flow, passenger demand, and energy consumption before physical construction begins. Transit authorities in Santiago and Quito deploy these tools to optimize station spacing and charging depot locations. The technology compresses feasibility study durations from 24 months to 8 months while reducing cost estimation variance.
China's MEE enforcement of Stage VI emission standards for heavy-duty vehicles eliminates diesel bus registrations in key metropolitan zones from 2025. Domestic manufacturers accelerate battery-electric platform development to maintain market access. The regulation forces technology transfer partnerships as foreign suppliers seek local assembly qualification.
Direct manufacturer contracting is displacing national distributor networks as procurement authority consolidates within municipal technical departments. Brazilian and Indonesian transit authorities now issue corridor-specific tenders that specify performance metrics rather than brand preferences. This channel disintermediation rewards chassis producers with localized engineering support capabilities.
Bus Rapid Transit System (BRT) Market Segmentation
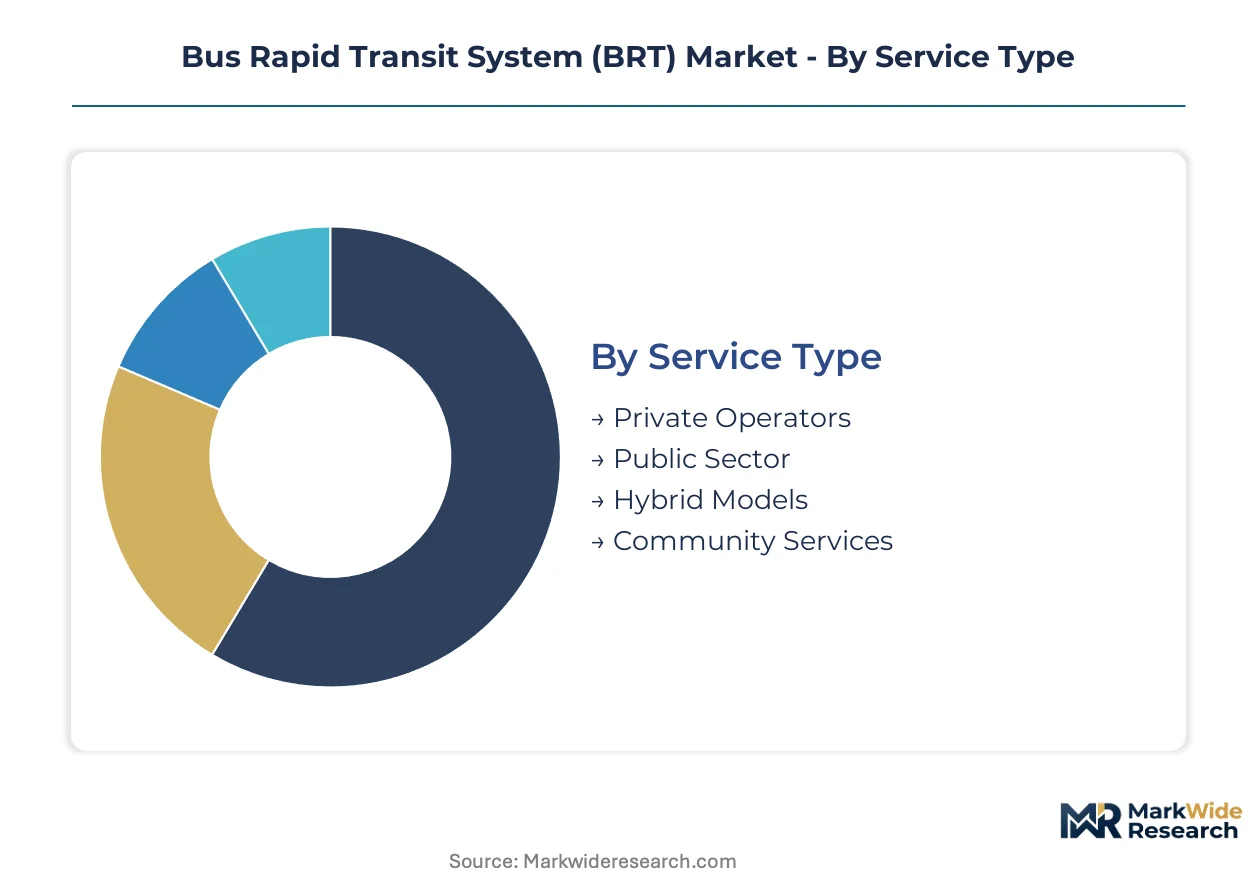
Segmentation reveals how capital allocation, operational risk, and maintenance intensity vary across BRT system configurations. Procurement patterns diverge sharply between electrified corridors requiring specialized depot infrastructure and legacy diesel networks with established service ecosystems.
Service Type:
After-sales-service intensity escalates dramatically under private contracting models where operators bear full lifecycle cost risk.
- Private Operators:Full-cost-responsibility contracts demand integrated fleet management platforms with predictive maintenance modules. São Paulo's corridor concessions require 99.5% availability guarantees that drive premium service tier adoption.
- Public Sector:Municipal authorities retain maintenance control through centralized depots with unionized workforces. Procurement emphasizes standardized parts availability over technology differentiation.
- Hybrid Models:Risk-sharing arrangements split capital expenditure from operational responsibility. Curitiba's PPP structures illustrate blended accountability frameworks.
- Community Services:Federally subsidized routes in peripheral districts operate simplified vehicle specifications with extended service intervals.
Public Sector holds the largest share; momentum sits with Hybrid Models.
Technology:
Cost tier stratification separates proven infrastructure from emerging digital platforms requiring continuous software expenditure.
- Dedicated Lanes:Concrete-separated corridors with physical enforcement represent the baseline capital allocation. Bogotá's TransMilenio network demonstrates mature engineering templates with established maintenance protocols.
- Smart Ticketing:Account-based fare collection systems generate recurring platform licensing revenue. Contactless payment migration in Jakarta and Mexico City accelerates vendor consolidation around interoperable standards.
- Real-Time Tracking:GPS-based passenger information systems improve perceived reliability without dedicated lane investment. Deployment concentrates in retrofit corridors with constrained right-of-way expansion budgets.
- Automated Systems:Driver-assist and platooning technologies remain pilot-phase with limited commercial deployment. Regulatory frameworks for autonomous bus operation remain undefined across Latin American markets.
Dedicated Lanes retains dominant deployment volumes; Smart Ticketing climbs the fastest on margin expansion.
End User:
Application context determines peak-load capacity requirements and amenity specifications across corridor design.
- Commuters:Predictable demand patterns enable optimized fleet sizing against peak-hour headway targets. São Paulo's radial corridors prioritize standing capacity over seated comfort.
- Tourists:Premium service tiers with multilingual wayfinding and luggage accommodation command fare multiples on airport and heritage routes.
- Local Residents:Off-peak service frequency and first-last-mile connectivity shape corridor planning in peripheral districts.
- Business Travelers:Express corridor segments with limited stops and guaranteed seating attract corporate shuttle contracts.
Commuters anchor ridership volumes; Tourists represent the steepest expansion trajectory on experience-based pricing.
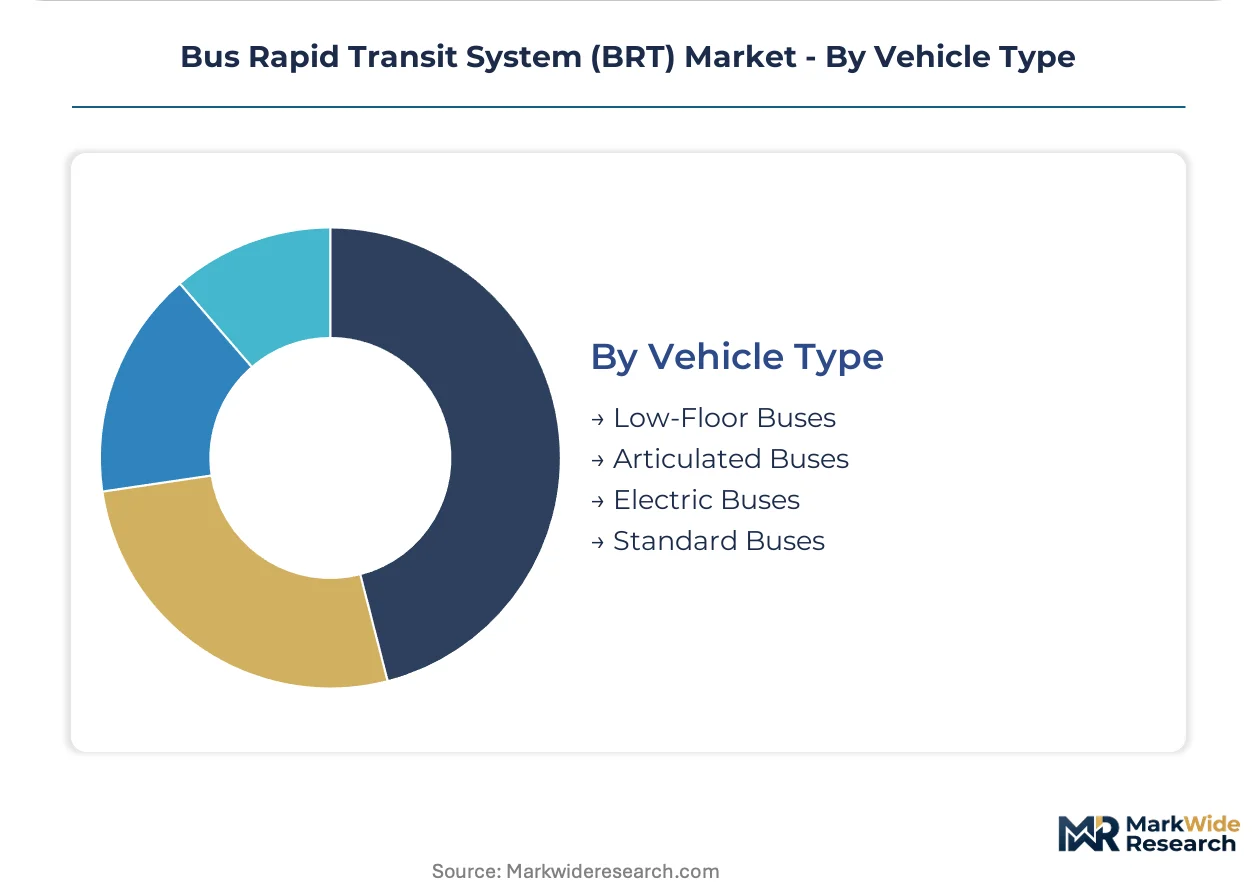
Vehicle Type:
Supply concentration clusters around chassis platforms with localized assembly qualification and battery supply chain proximity.
- Electric Buses:Battery-electric platforms with opportunity charging infrastructure achieve total cost parity against diesel on high-frequency corridors. Brazil's federal electrification mandates accelerate fleet replacement timelines.
- Articulated Buses:18-meter bi-articulated configurations maximize passenger throughput on constrained right-of-way. Curitiba's original corridor design established global engineering benchmarks.
- Low-Floor Buses:Level-boarding compatibility reduces dwell times and improves accessibility compliance. Universal dock height standardization enables multi-supplier procurement.
- Standard Buses:Conventional diesel and CNG platforms retain residual demand in secondary cities with limited electrification infrastructure.
Standard Buses maintains installed base dominance; Electric Buses gains share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands superior pricing power in corridor infrastructure contracts compared to Indonesia, where domestic assembly mandates compress supplier margins. Electrification timelines diverge sharply across metropolitan regulatory environments.
Brazil
Federal infrastructure programs in São Paulo, Curitiba, and Belo Horizonte accelerate dedicated lane construction and fleet procurement. ANVISA safety certification streamlines import approvals for electric chassis platforms. The Southeast corridor cluster concentrates manufacturing partnerships around battery-electric platform localization.
China
MEE enforcement of Stage VI emission standards eliminates diesel bus registrations in key metropolitan zones from 2025. Domestic battery supply chain proximity reduces cathode material input costs for fleet operators. The Yangtze River Delta corridor network expands charging depot infrastructure at scale.
India
The PLI scheme for automotive manufacturing forces foreign chassis suppliers into regional assembly partnerships. Delhi-NCR and Maharashtra transit authorities issue corridor-specific tenders specifying performance metrics over brand preferences. High-volume South Asian corridors prioritize total cost of ownership optimization for CNG and electric fleets.
Indonesia
Jakarta's dense urban land values inflate right-of-way acquisition budgets beyond original feasibility projections. Local assembly mandates extend foreign supplier time-to-market by 18-24 months. The TransJakarta corridor network pilots account-based fare collection systems with contactless payment migration.
Germany
The EU Green Deal framework mandates 55% CO2 reduction for urban transport fleets by 2030. KBA type-approval processes govern electric bus platform certification for corridor deployment. Bavaria and North Rhine-Westphalia metropolitan regions retrofit existing corridors with opportunity charging infrastructure.
Bus Rapid Transit System (BRT) Market Competitive Environment
Integrated platform specialists and regional assembly partners split the market based on electrification readiness and localization depth. The vendor base concentrates around chassis producers with captive battery supply or established distributor bypass capabilities. Two archetypes dominate: full-stack electric platform providers and diesel-to-electric transition specialists. Competitive moves center on corridor-specific engineering support deployment and joint venture formation to satisfy domestic content requirements.
Within the full-stack electric tier, BYD Company Limited and Volvo Group anchor positions through integrated battery production and localized assembly partnerships. Zhengzhou Yutong Bus exemplifies the scale-driven regional specialist archetype, occupying a position based on manufacturing proximity to expanding Asian corridor networks. Tata Motors and Ashok Leyland sit within the emerging market transition specialist category, representing cost-optimized platform approaches for high-volume diesel and CNG fleet replacement cycles.
| Leading Market Players |
|---|
| Marcopolo |
| Ashok Leyland |
| Volvo Group |
| Xiamen King Long Motor Group |
| MAN |
| Daimler |
| Tata Motors |
| BYD Company Limited |
| Zhengzhou Yutong Bus |
| Others |
Value Chain & Pricing Dynamics
Foshan's battery cell manufacturing cluster anchors global cathode material processing capacity, concentrating input cost leverage for chassis producers bidding on Latin American corridor contracts. Municipal transit authorities in São Paulo and Bogotá exploit this supplier density to negotiate volume-tiered procurement terms, while freight differentials from Chinese ports to Brazilian Atlantic terminals compress margin buffers for European competitors.
Pricing Analysis
Configured-to-order chassis specifications command 15-25% premiums over standard platform configurations due to corridor-specific dock height and charging infrastructure integration requirements. Price differentiation hinges on battery energy density certification tiers and localized assembly qualification status under Brazil's ANVISA and India's PLI frameworks. Cost compression in standard diesel replacement fleets is intensifying because Tata Motors and Ashok Leyland compete aggressively on total cost of ownership metrics. Public sector municipal authorities exhibit highest price sensitivity through centralized depot procurement, while private concession operators in São Paulo absorb premium service tiers for 99.5% availability guarantees.
Supply Chain Analysis
Supplier-financing facilities from Chinese battery producers extend payment terms to 180 days for qualified chassis assemblers, easing working capital constraints on corridor-specific production runs. Manufacturing concentration clusters in China, South Korea, and Germany for lithium-ion cell production, cathode material processing, and precision axle assemblies respectively. Raw material dependencies center on lithium carbonate from Chilean salares, nickel laterite from Indonesian islands, and copper busbar from Zambian-Congolese supply corridors. Single-source vulnerability in cathode precursor processing creates geopolitical exposure for fleet operators planning decade-long electrification roadmaps. Distribution runs through direct manufacturer contracting channels that displace national distributor networks as municipal technical departments consolidate procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BRT market represents a high-growth electrification disruption as regulatory mandates from China's MEE and the EU Green Deal framework eliminate diesel platform viability across metropolitan fleet registrations. Battery-electric chassis procurement now dominates corridor development pipelines, compressing supplier qualification timelines and rewarding localized engineering support capabilities.
For Market Incumbents: Insulate core revenue streams by securing captive battery supply partnerships in Foshan and Ningbo manufacturing clusters, while accelerating ANVISA certification pathways to defend against Chinese platform entrants. Vertical integration into opportunity charging infrastructure deployment protects margin pools as hardware commoditization pressures intensify across standardized chassis specifications. For New Entrants and Emerging Players: Secondary city corridors in Indonesia's Surabaya and Medan present underpenetrated procurement windows where local assembly mandates have delayed established supplier market entry. Target hybrid model concessions in Colombian secondary municipalities where risk-sharing arrangements split capital expenditure from operational responsibility, enabling platform-as-a-service positioning without full fleet ownership exposure. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive conglomerates divesting legacy diesel bus divisions under portfolio carbon neutrality commitments, particularly European manufacturers with stranded ICE engineering capabilities. Mid-cap specialists with captive battery supply and Brazilian assembly qualification represent priority acquisition archetypes. Monitor MEE enforcement intensity in Yangtze River Delta metropolitan zones as inflection indicator for accelerated technology transfer partnership formation.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Localized assembly partnerships satisfy India's PLI domestic content requirements and compress time-to-market. |
| Platform Standardization | Universal dock height specifications reduce vehicle-platform integration costs across multi-supplier corridors. |
| Backward Integration | Captive cathode material processing insulates margin pools from lithium carbonate price volatility. |
| Smart Ticketing Licensing | Account-based fare collection platforms generate recurring revenue independent of vehicle sales cycles. |
| Charging Infrastructure Partnership | Opportunity charging depot networks enable electric bus range extension on high-frequency corridor segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of municipal transit authority procurement databases, ANVISA import registration filings, and EU Green Deal implementation progress reports. Primary interviews engaged fleet procurement directors at São Paulo and Curitiba transit authorities, platform engineering leads at BYD and Volvo Group, and charging infrastructure specialists at Siemens Energy. Secondary validation drew from Brazil's federal infrastructure program disbursement records, China's MEE Stage VI enforcement notices, and India PLI scheme beneficiary disclosures. Bottom-up corridor deployment pipelines triangulate against top-down metropolitan electrification mandate schedules.
Forecast inputs incorporate vehicle procurement volume trajectories, battery cost degradation curves, and right-of-way acquisition timelines across the projection horizon. Segmentation dimensions model service type contracting structures, vehicle propulsion architecture, technology deployment maturity, and regional regulatory cluster intensity. CAGRs derive from corridor mileage expansion schedules and fleet replacement cycle compression under environmental mandate deadlines. Industry-specific inputs include lithium-ion cell supply concentration indices and domestic content requirement phase-in schedules.
Practitioners should monitor subsidy phase-out calendars, local battery supply chain development milestones, and cathode material processing capacity expansion for early signals of total cost of ownership inflection. Forecasts reflect documented assumptions regarding electrification mandate enforcement consistency and corridor infrastructure funding continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
City Bus Low-Floor Axle Systems Market
Buses
Luxury Bus Market
Buses
Airport Shuttle Bus Market
Buses
Bus Flooring Market
Buses
Fuel Cell Electric Bus Market
Buses
Trolley Bus Market
Buses
Global Bus Market
Buses
Electric Intercity Bus Market
Buses
Bus Charter Services Market
Buses
School Bus Market
Buses
Hydrogen Buses Market
Buses
Intelligent Bus Shelter Market
Buses
Intercity Bus Travel Market
Buses
Canada Transit Buses Market
Buses
Hydrogen CNG Bus Market
Buses
Europe Trolley Bus Market