
 Europe Trolley Bus Market | 2026-2036
Europe Trolley Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Trolley Bus Market Analysis
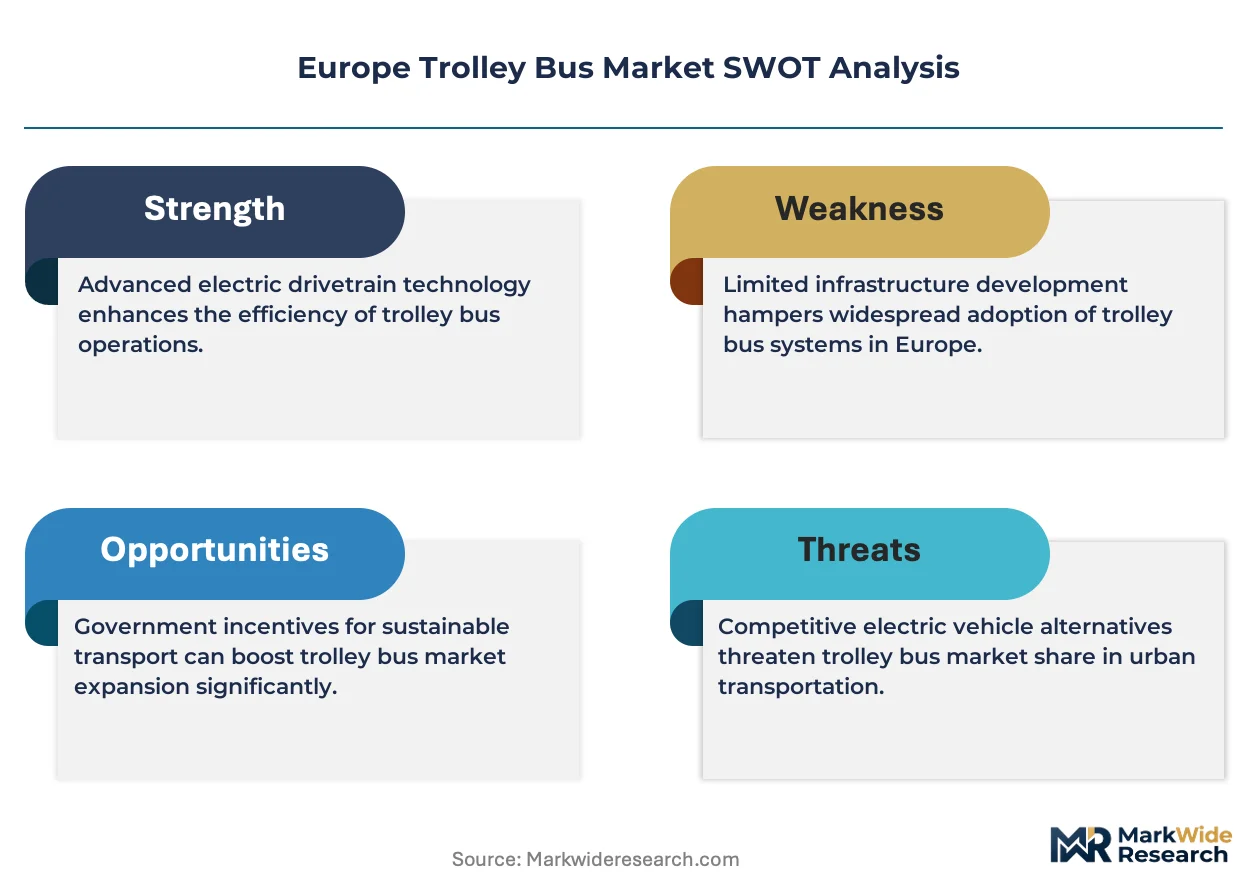
Low-floor accessibility specifications is bifurcating the competitive landscape between premium European OEMs and cost-optimized Eastern European suppliers. Solaris Bus & Coach leverages its Polish manufacturing base to dominate Central European procurement tenders. ŠKODA Electric anchors Czech and Slovak fleet renewals through captive rail-electrification expertise. Van Hool NV differentiates via bespoke body configurations for Alpine municipal operators requiring gradient-rated powertrains.
A trolley bus is a rubber-tired electric transit vehicle drawing continuous power from overhead twin wires via spring-loaded trolley poles or pantographs, typically operating at 600–750 V DC with regenerative braking capability and auxiliary battery packs for off-wire maneuvering. Low-floor configurations command the largest installed base across aging European city centers where platform-height standardization accelerates accessibility compliance. Articulated variants represent the fastest-expanding type segment as Bordeaux, Lyon, and Zurich deploy 24-meter bi-articulated units on high-frequency trunk corridors. Hybrid power systems integrating onboard batteries with traditional catenary feed are capturing margin pools where operators demand operational flexibility without full infrastructure rebuild.
EU Green Deal emission targets and the F-Gas Regulation on insulating gases shape power system design requirements across member state procurement rules. ECHA REACH compliance governs traction motor magnet materials and flame-retardant interior composites, while CE marking mandates interoperability with legacy catenary standards. Stakeholders must monitor whether upcoming EU battery passport rules will impose traceability burdens on hybrid trolley bus supply chains before committing to multi-year fleet contracts.
Market Dynamics
EU Green Deal diesel phase-out mandates are forcing municipal transit authorities to accelerate fleet electrification, creating a structural pull for catenary-dependent solutions where full battery-electric range remains operationally constrained. This regulatory pressure concentrates procurement timing and technical specifications across Eastern and Central European markets.
Growth Catalysts
- F-Gas Regulation compliance:The EU F-Gas Regulation on insulating gases in traction equipment is accelerating replacement cycles for aging fleets across Germany and Switzerland, where operators must retire non-compliant vehicles before mandated deadlines.
- Battery-trolley hybrid technology:Hybrid configurations integrating onboard lithium-ion storage with traditional overhead feed are resolving operational gaps in Polish and Romanian networks where incomplete catenary coverage previously blocked pure electric adoption.
- Platform-height standardization:Low-floor accessibility mandates under EU-wide disability transport directives are standardizing procurement specifications, favoring dedicated trolley bus architectures over retrofitted diesel chassis.
Market Restraints
- Copper conductor cost volatility:Overhead catenary infrastructure requires substantial copper and aluminum conductor deployment, exposing municipal budgets to commodity price swings that distort multi-year capital planning.
- Eastern European supply concentration:Traction motor and power electronics manufacturing clusters heavily concentrate in Poland and the Czech Republic, creating geographic single-point-of-failure risks for fleet operators outside these hubs.
- Fixed-route inflexibility:Pure catenary-dependent operation cannot deviate from wired corridors, limiting route planning flexibility compared to battery-electric alternatives with expanding range capabilities.
Strategic Opportunities
- Romania underpenetration:Bucharest and Cluj-Napoca retain substantial diesel bus fleets with minimal existing trolley infrastructure, presenting greenfield deployment opportunities for battery-trolley hybrid systems without legacy asset stranding.
- EU battery passport traceability:Upcoming EU battery passport rules will impose supply chain documentation requirements that favor established OEMs with integrated cell-to-vehicle traceability systems, creating competitive moats for compliant manufacturers.
- Bi-articulated corridor expansion:High-frequency trunk routes in Lyon, Bordeaux, and Zurich are validating 24-meter bi-articulated configurations, opening specification expansion for capacity-constrained Alpine and dense urban networks.
Industry Challenges
- Traction power electronics skill scarcity:Maintenance of 600–750 V DC power conversion systems requires specialized electrical engineering expertise that municipal workshops struggle to recruit and retain against automotive and renewable energy sector competition.
- Legacy catenary interoperability certification:CE marking mandates compatibility with heterogeneous legacy overhead standards across member states, forcing manufacturers to maintain multiple pantograph and trolley pole configurations that fragment production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Trolley Bus Market |
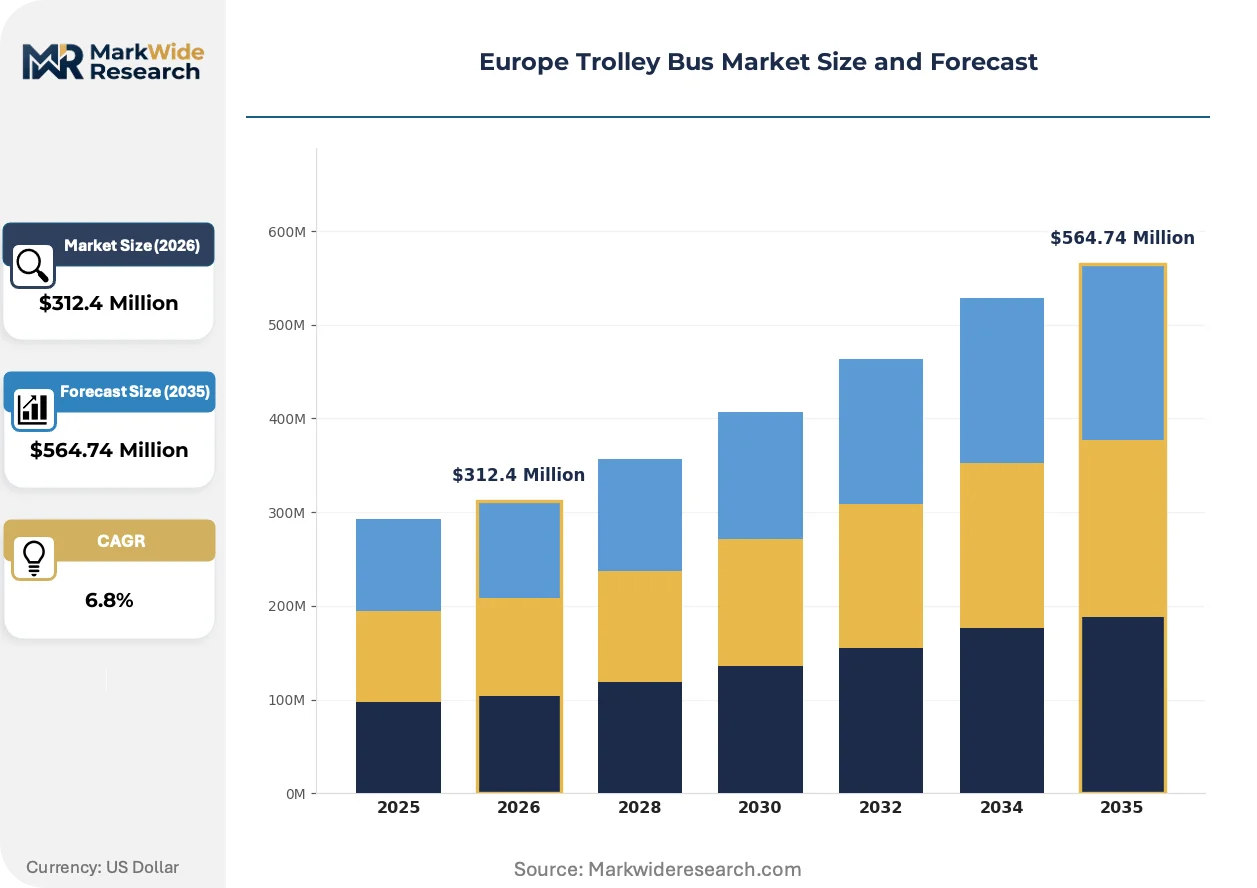
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Low-Floor, Articulated, Double-Deck, Rigid Application: Urban Transport, Suburban Transport, Tourist Services, Shuttle Services End User: Public Transport Authorities, Private Operators, Municipalities, Transportation Agencies Power System: DC Electrification, AC Electrification, Hybrid Systems, Battery Systems |
| Companies Covered | Solaris Bus & Coach, Van Hool NV, ŠKODA Electric, Hess AG, Kiepe Electric GmbH, Iveco Bus, SOR, CAF, Belkommunmash, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Trolley Bus Market Emerging Trajectories
Power electronics integration and energy storage density improvements are compressing vehicle architecture constraints, enabling operational models that were technically infeasible under previous generation hardware. These shifts are redefining competitive differentiation around energy management rather than chassis manufacturing.
Solid-state traction inverters are replacing conventional silicon IGBT modules in next-generation trolley bus powertrains, delivering higher switching frequencies with reduced thermal losses. Alpine municipal operators in Switzerland and Austria are piloting these systems for gradient-rated corridors where power density constraints previously limited vehicle performance. The technology is miniaturizing onboard power conversion equipment, freeing chassis space for expanded battery storage or passenger capacity.
REACH compliance protocols from ECHA are mandating substitution of rare-earth magnet materials in traction motors, forcing redesigns of permanent magnet synchronous motor architectures. Manufacturers must now document full material substance inventories through supply chain tiers, adding documentation overhead but creating competitive separation for OEMs with captive magnet recycling programs. Czech and Slovak fleet renewals are particularly affected given ŠKODA Electric's deep integration with regional rare-earth processing.
Lifecycle service contracting is displacing traditional capital purchase models in German and Swiss municipal procurement, with operators demanding guaranteed availability and energy consumption performance rather than discrete vehicle transactions. This unbundling of hardware from operational risk is concentrating vendor relationships around integrated fleet management platforms. The shift is most visible in Zurich and Basel, where transport authorities have transferred energy optimization liability to OEM consortia.
Europe Trolley Bus Market Segmentation
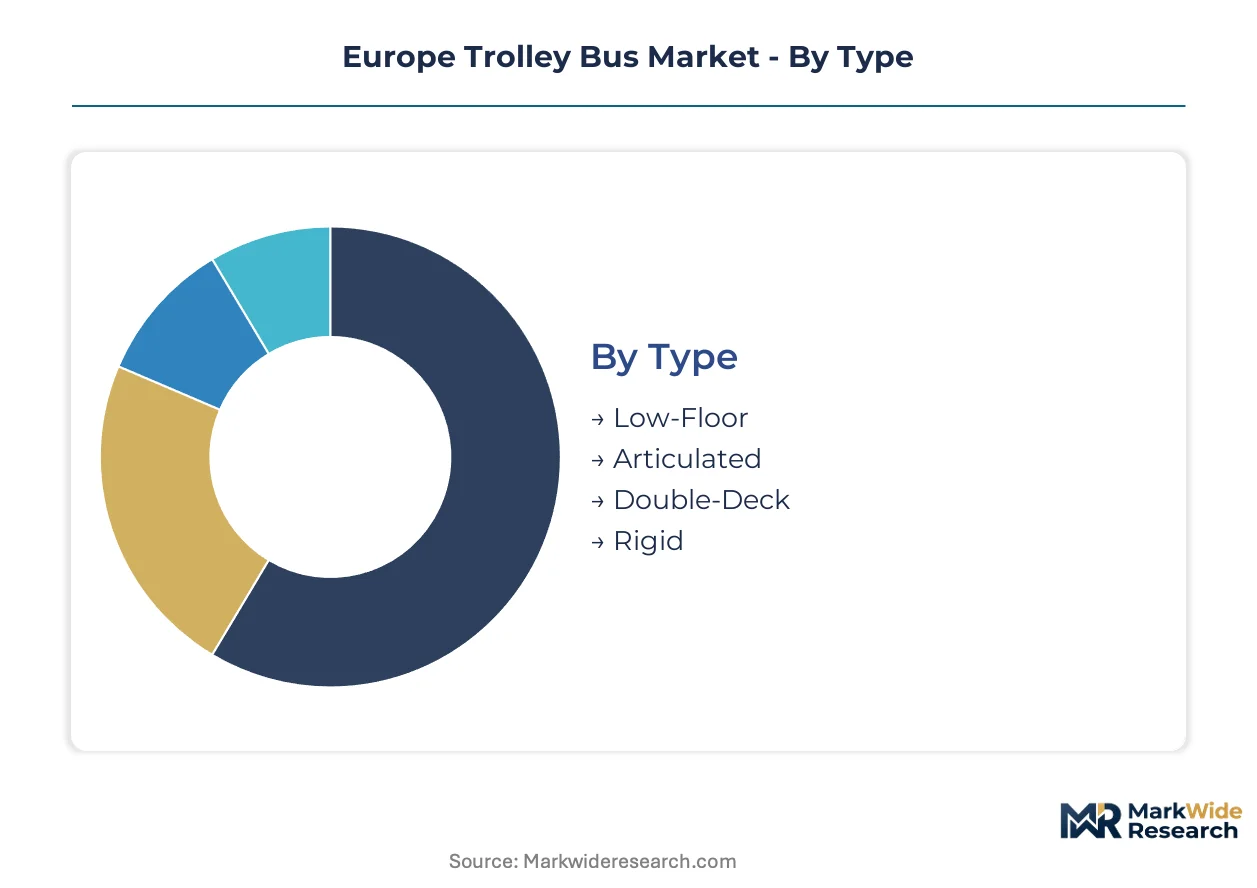
Segmentation in the Europe trolley bus market reveals how procurement specifications diverge between established catenary networks and emerging hybrid deployments. Technical architecture choices directly determine operational flexibility and infrastructure investment requirements across municipal tendering processes.
Type:
Margin pools concentrate in configurations that balance accessibility compliance with passenger capacity optimization for constrained urban corridors.
- Low-Floor:These vehicles feature continuous flat flooring from front to rear at platform height, eliminating steps for wheelchair and stroller access. German and Swiss operators prioritize this specification for fleet renewal programs where EU disability transport directives mandate full accessibility compliance by statutory deadlines.
- Articulated:Bi-articulated 24-meter variants are expanding most quickly across Lyon, Bordeaux, and Zurich high-frequency trunk corridors where passenger volumes exceed rigid chassis capacity. Alpine gradient requirements and dense urban stop spacing favor these configurations for capacity-constrained networks.
- Double-Deck:Two-level passenger compartments maximize seating density for tourist corridors and heritage route operations in British and Irish markets with height clearance allowances.
- Rigid:Fixed-length chassis serve secondary routes and depot shuttle functions where maneuverability in narrow historic streetscapes outweighs capacity requirements.
Low-floor configurations hold installed capacity across aging European city centers. Articulated variants are rotating up the share rankings as trunk corridor electrification accelerates.
Application:
Procurement volume clusters where operational models demand catenary-dependent energy economics rather than full battery-electric autonomy.
- Urban Transport:High-frequency scheduled services on dense corridor networks constitute the core deployment model for trolley bus technology. Bucharest and Cluj-Napoca municipal authorities are evaluating greenfield catenary installation where diesel phase-out mandates converge with route density economics.
- Suburban Transport:Extended-radius services connecting peripheral districts to city centers require hybrid power architectures bridging overhead line gaps. Polish operators around Kraków and Wrocław specify battery-trolley configurations for radial routes with incomplete infrastructure coverage.
- Tourist Services:Heritage route circuits in Alpine municipalities leverage gradient-rated powertrains for scenic corridor operations with seasonal demand patterns.
- Shuttle Services:Closed-loop airport and campus circulators utilize auxiliary battery packs for off-wire terminal maneuvering without full route electrification.
Urban transport dominates current fleet orders. Suburban transport is climbing the fastest as hybrid systems resolve infrastructure coverage limitations.
End User:
Tendering authority structures shape contract risk allocation between capital purchase and lifecycle service models.
- Public Transport Authorities:Integrated regional operators in Germany and Switzerland consolidate fleet procurement across multiple municipal jurisdictions, achieving scale economies in specification standardization.
- Private Operators:Contracted service providers in Eastern European markets favor leasing arrangements and availability-based agreements over direct asset ownership.
- Municipalities:City governments with direct service provision responsibility specify bespoke configurations for historic center penetration and tourism integration.
- Transportation Agencies:National and regional coordinating bodies influence interoperability standards and cross-border fleet compatibility requirements.
Public transport authorities hold installed capacity. Private operators are gaining share fastest as service contracting models displace direct municipal provision.
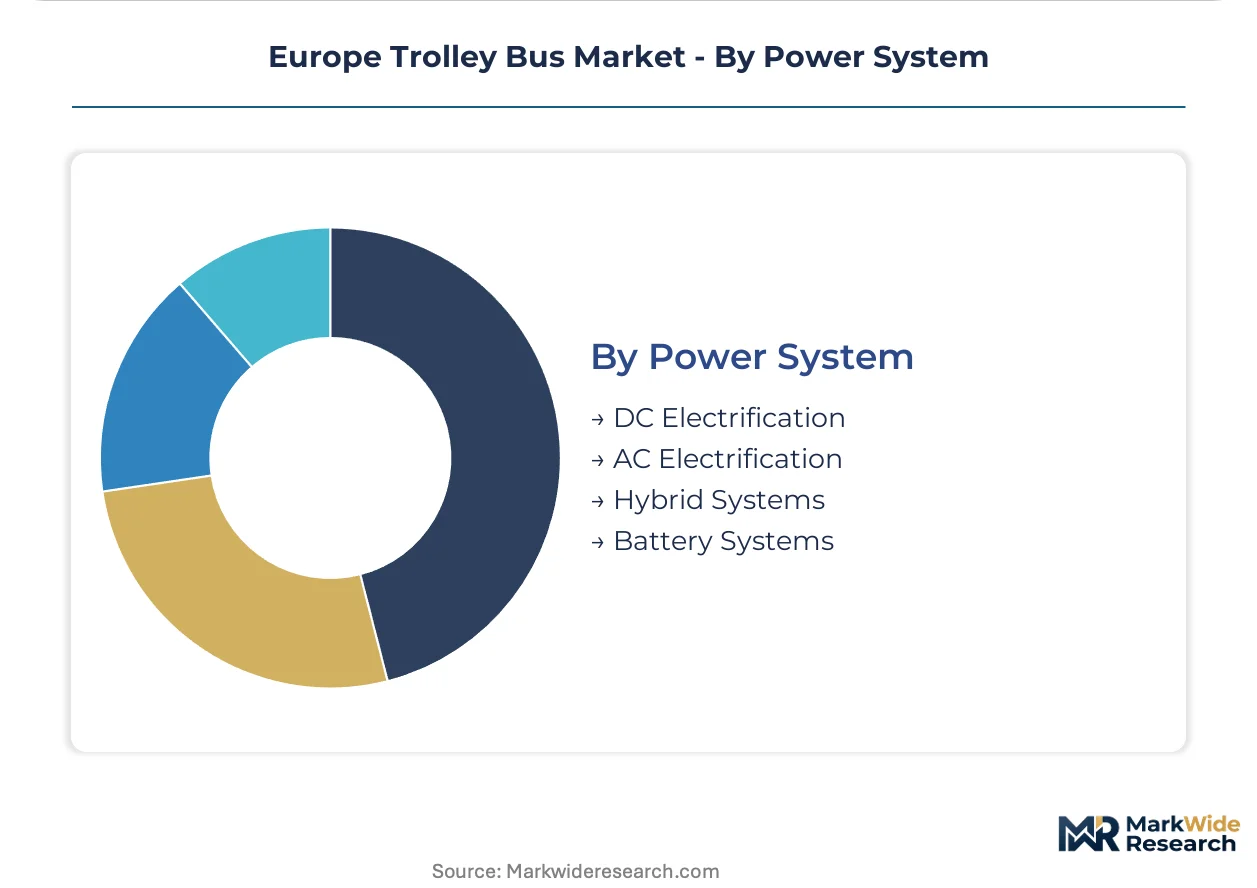
Power System:
Technology selection determines infrastructure lock-in versus operational flexibility trade-offs that persist across 15-year asset lifecycles.
- DC Electrification:Traditional 600–750 V DC overhead feed remains the dominant architecture in Czech, Slovak, and Romanian networks with legacy catenary assets. ŠKODA Electric anchors fleet renewals through captive rail-electrification expertise and regional maintenance infrastructure.
- Hybrid Systems:Battery-trolley configurations integrating onboard lithium-ion storage with overhead feed are capturing margin pools where operators demand operational flexibility without full infrastructure rebuild. Polish and Romanian procurement tenders increasingly specify this architecture for incomplete network coverage.
- AC Electrification:Alternating current architectures appear in specific municipal networks with historical infrastructure choices requiring specialized pantograph compatibility.
- Battery Systems:Pure onboard storage without catenary dependence operates in limited demonstration deployments where route characteristics permit, though this configuration technically exits the trolley bus category definition.
DC electrification holds installed capacity. Hybrid systems are rotating up the share rankings as battery density improvements resolve operational gap constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the continent. Swiss and German buyers prioritize performance specifications over unit cost, while Romanian and Polish procurement authorities face acute capital constraints that favor hybrid configurations over full infrastructure builds.
Germany
Municipal transport associations in North Rhine-Westphalia and Bavaria are consolidating fleet orders to achieve specification standardization across multi-city networks. The EU Green Deal diesel phase-out mandates are compressing replacement timelines for aging diesel fleets in Cologne, Bonn, and Munich. Solaris Bus & Coach has secured multiple framework agreements with Verkehrsverbund Rhein-Ruhr for low-floor articulated units.
Switzerland
Alpine gradient requirements in Zurich and Basel are driving demand for power-dense traction systems capable of sustained incline operation. The F-Gas Regulation on insulating gases is accelerating retirement of pre-2020 fleets that fail compliance deadlines. Bi-articulated 24-meter configurations are expanding on high-frequency trunk corridors where passenger volumes exceed rigid chassis capacity.
Poland
Incomplete catenary coverage in Kraków and Wrocław suburban networks is pushing procurement toward battery-trolley hybrid architectures. EU cohesion fund allocations are subsidizing greenfield electrification projects that bypass legacy diesel infrastructure. Solaris Bus & Coach leverages its Bolechowo manufacturing base to dominate Central European tendering processes with shortened delivery timelines.
Czech Republic
Legacy 600–750 V DC catenary assets in Prague and Brno are anchoring fleet renewal programs around captive maintenance expertise. ŠKODA Electric draws on regional rail-electrification supply chains to integrate traction power systems with existing infrastructure. The concentration of rare-earth magnet processing in the region is shaping REACH compliance protocols for traction motor redesigns.
Romania
Bucharest and Cluj-Napoca retain substantial diesel bus fleets with minimal existing trolley infrastructure, presenting greenfield deployment opportunities. Battery-trolley hybrid systems are gaining traction where full route electrification would strain municipal capital budgets. EU Green Deal funding mechanisms are bridging the cost gap between diesel replacement and zero-emission alternatives.
Europe Trolley Bus Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the European trolley bus market. Premium-tier OEMs dominate specification-intensive tenders in Germany and Switzerland where gradient-rated powertrains and bespoke body configurations command price premiums. Cost-optimized Eastern European suppliers capture volume in Polish and Romanian markets where procurement authorities prioritize capital efficiency over performance differentiation. The competitive landscape organizes around three strategic archetypes: integrated chassis-electronics manufacturers, specialized traction system suppliers, and municipal service contractors. Consolidation pressure is intensifying through framework agreement consolidation and lifecycle service contracting models that transfer operational risk from transport authorities to vendor consortia.
Among Central European integrated manufacturers, Solaris Bus & Coach and ŠKODA Electric exemplify divergent competitive positions. Solaris occupies the scale-driven tier with manufacturing concentration in Poland serving price-sensitive procurement markets across Eastern Europe. ŠKODA Electric sits within the captive-infrastructure archetype, leveraging deep integration with Czech and Slovak rail-electrification ecosystems. Van Hool NV represents the premium-specialist position, serving Alpine municipal operators with gradient-rated configurations. These three anchors illustrate how geographic manufacturing concentration and technical specialization are bifurcating competitive outcomes across the continent.
| Leading Market Players |
|---|
| Solaris Bus & Coach |
| Van Hool NV |
| ŠKODA Electric |
| Hess AG |
| Kiepe Electric GmbH |
| Iveco Bus |
| SOR |
| CAF |
| Belkommunmash |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emission mandates and CE marking interoperability requirements gate both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb certification overhead while municipal buyers segment procurement across performance tiers.
Pricing Analysis
Lifecycle service contracts and guaranteed availability agreements drive lifetime value beyond discrete vehicle transactions. Three-tier pricing structure across premium, standard, and economy levels separates Swiss Alpine operators demanding gradient-rated powertrains from Polish authorities prioritizing capital efficiency. Cost compression in Eastern European tenders is intensifying because EU cohesion fund allocations compress procurement timelines. Municipal transport authorities in Germany and Switzerland exhibit lowest price sensitivity, while Romanian and Polish procurement teams face acute capital constraints.
Supply Chain Analysis
Poland and the Czech Republic anchor traction motor and power electronics manufacturing for Central European fleet operators. Copper conductor and rare-earth magnet materials draw from regional processing clusters concentrated in Eastern Europe. Single-source vulnerability runs through Poland's manufacturing concentration for battery-trolley hybrid systems. Distribution runs through municipal transport association framework agreements and direct OEM consortia partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around catenary infrastructure standards creates defensive moats for established OEMs, as switching costs for municipal operators span 15-year asset lifecycles and heterogeneous legacy overhead systems.
For Market Incumbents: Secure captive maintenance infrastructure in Czech and Slovak networks where ŠKODA Electric's rail-electrification expertise anchors fleet renewal dependencies. Deepen backward integration into rare-earth magnet recycling programs before REACH compliance deadlines tighten material documentation requirements. Battery-electric bus substitutes threaten pure catenary-dependent product lines. For New Entrants and Emerging Players: Lead with battery-trolley hybrid architectures in Romanian greenfield deployments where Bucharest and Cluj-Napoca lack legacy infrastructure stranding. Target suburban transport applications bridging overhead line gaps in Polish networks around Kraków and Wrocław. Partner with EU cohesion fund administrators for subsidized electrification project access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across lifecycle service contracting models as operational risk transfers from municipal authorities to vendor consortia. Long-term viability favors integrated chassis-electronics manufacturers with captive traction system capabilities over pure assembly operations. Monitor EU battery passport rule finalization as inflection indicator for supply chain documentation burden concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Power System Integration | Resolves infrastructure coverage gaps for Polish and Romanian operators with incomplete catenary networks. |
| Lifecycle Service Contracting | Transfers energy optimization liability to OEM consortia in Zurich and Basel municipal frameworks. |
| Rare-Earth Magnet Recycling Investment | Creates competitive separation under ECHA REACH compliance protocols for traction motor redesigns. |
| Bi-Articulated Capacity Expansion | Captures high-frequency trunk corridor demand in Lyon, Bordeaux, and Alpine networks. |
| CE Marking Interoperability Certification | Ensures compatibility with heterogeneous legacy overhead standards across EU member states. |
Methodological Framework
A spread of perspectives from municipal transport planners, fleet procurement officers, traction system engineers, and aftermarket service directors converged on the working assumptions. Primary fieldwork combined with secondary validation from EU tendering databases, national statistical offices, and transport association annual reports. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include vehicle type configuration, power system architecture, application use case, and end-user tendering authority structure. CAGRs derived from installed base replacement cycles and greenfield deployment pipelines. Forecast inputs incorporated EU Green Deal diesel phase-out timelines and F-Gas Regulation compliance deadlines.
The analysis sits within stated boundaries; outcomes outside sustained EU funding allocation or copper price stability would require recalibration. Forecasts reflect documented assumptions on infrastructure investment continuity and hybrid technology cost curves. Recalibration cycles align with material shifts in EU battery passport implementation and REACH substance restriction updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intelligent Bus Shelter Market
Buses
Canada School Bus Market
Buses
Electric Intercity Bus Market
Buses
Trolley Bus Market
Buses
Bus Chassis Market
Buses
Global Bus Market
Buses
Bus Flooring Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Hydrogen CNG Bus Market
Buses
Bus Rental Market
Buses
Solar Bus Market
Buses
Africa Electric Bus Market
Buses
Canada Transit Buses Market
Buses
Buses & Coaches Market
Buses
Global Luxury Shuttle Bus Market
Buses
Bus Seat Market