
 Intercity Bus Travel Market | 2026-2036
Intercity Bus Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Intercity Bus Travel Market Foresight
Capital-intensity divergence between asset-light platform operators and fleet-owning incumbents is redrawing competitive boundaries in intercity bus travel. FlixBus leverages partnership-based network expansion across Europe without owning depots or vehicles. Greyhound Lines sustains its position through owned terminal infrastructure and fixed-route density across North America. National Express anchors British intercity connectivity through regulated concession contracts and airport link specialization.
Intercity bus travel denotes scheduled or chartered road passenger transport between urban centers, typically covering distances from 100 to 800 kilometers using single-deck or double-deck coaches with seating capacities of 40 to 80 passengers. The primary commercial purpose is to provide cost-efficient mobility alternatives to rail and air for price-sensitive travelers, students, and regional commuters. Scheduled service dominates volume flows on trunk corridors, while charter operations capture higher-margin demand from tourism agencies and corporate event planners. Express ticketing models through mobile platforms are displacing walk-up purchases as the default booking behavior among younger customer segments.
The US Department of Transportation enforces hours-of-service limits and vehicle inspection protocols through the Federal Motor Carrier Safety Administration, directly shaping fleet utilization rates and driver staffing costs. European operators face CO2 emission targets under the EU Green Deal and vehicle safety mandates through the EU General Safety Regulation, accelerating electric and hydrogen coach trials. India's Ministry of Road Transport mandates fitness certification and speed governor installation through state transport authorities, conditioning market access for private fleet owners. Stakeholders must monitor how carbon border adjustments and digital platform liability frameworks reshape cost structures and partnership economics in cross-border corridor development.
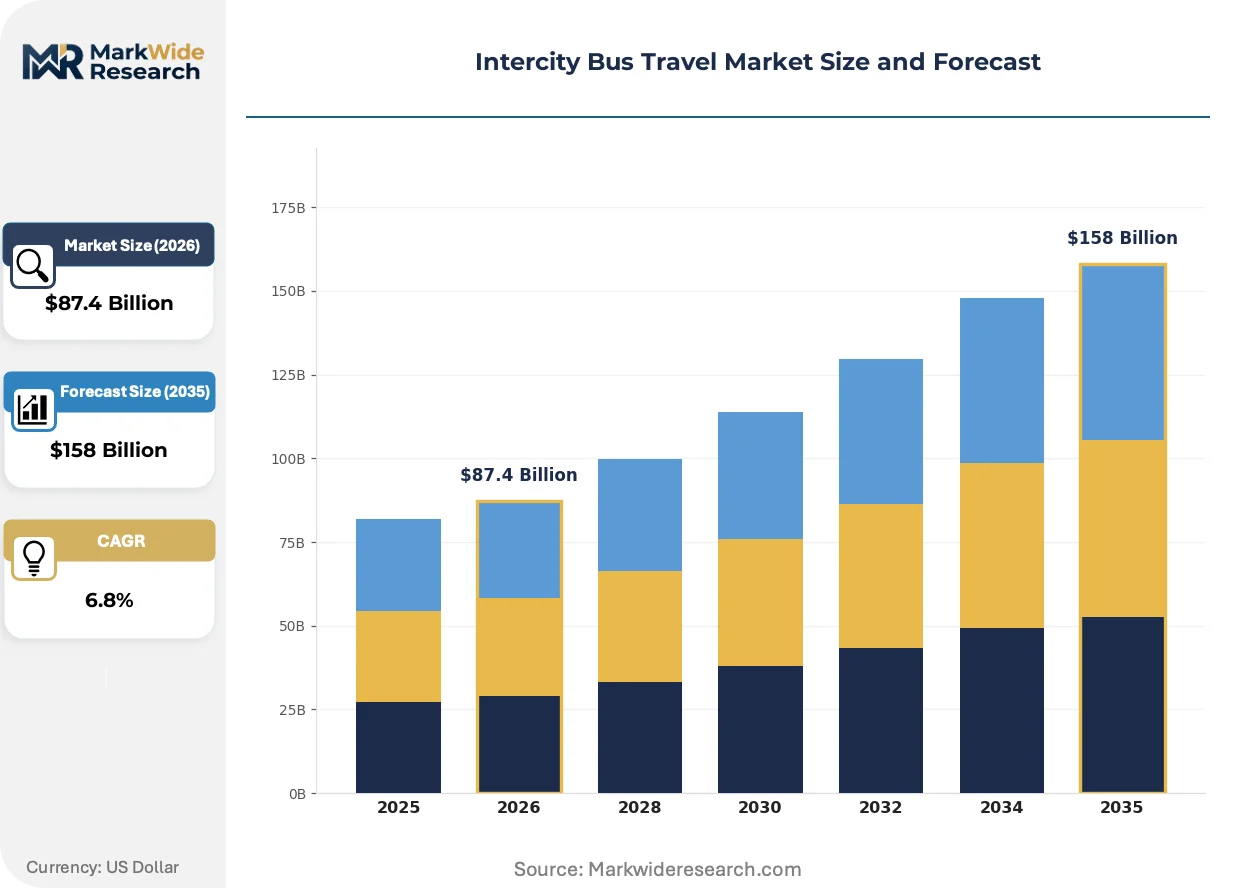
Market Dynamics
Fleet electrification mandates and platform-based aggregation are restructuring intercity bus economics, forcing asset-heavy operators to cede corridor control to technology intermediaries that monetize demand forecasting rather than seat-miles.
Growth Catalysts
- EU Green Deal CO2 targets:Emission reduction mandates accelerate operator trials of battery-electric and hydrogen fuel-cell coaches, creating procurement pull for zero-emission drivetrain suppliers.
- Last-mile connectivity gaps:Rail trunk lines terminate at peripheral stations, generating feeder demand for scheduled bus services that complete door-to-door journeys in secondary cities.
- Dynamic yield algorithms:Machine learning models optimize load factors by adjusting fares in real-time, compressing revenue leakage from empty seats on off-peak departures.
Market Restraints
- Terminal access concentration:Privately owned city-center depots in legacy markets extract concession rents that erode margins for new entrants lacking integrated real estate.
- Driver hour limits:FMCSA regulations cap daily driving time, constraining fleet utilization and forcing redundant crew rotations on overnight corridors.
- Intercity rail substitution:High-speed rail expansions in France, Spain, and China capture premium passengers on trunk routes under 500 kilometers.
Strategic Opportunities
- Cross-border ASEAN corridors:Fragmented bilateral permits currently throttle vehicle utilization; harmonized customs protocols would unlock through-running between Vietnam, Cambodia, and Thailand.
- Corporate shuttle contracting:Tech campuses and manufacturing parks seek dedicated commuter fleets, shifting revenue from per-seat retail to guaranteed monthly payments.
- Carbon credit monetization:Verified emission reductions from electric coach deployments qualify for compliance markets under EU ETS linkage mechanisms.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain maintenance requires certified specialists that vocational programs have not yet scaled to match fleet conversion timelines.
- Interoperable payment fragmentation:National ticketing standards prevent seamless cross-operator journeys, forcing passengers to maintain multiple app accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intercity Bus Travel Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Scheduled, Charter, Express, Luxury Ticketing Model: Advance Booking, On-Demand, Subscription, Walk-Up Vehicle Type: Standard Coach, Double-Decker, Sleeper Bus, Minibus Customer Type: Tourists, Commuters, Students, Business Travelers |
| Companies Covered | ALSA, Greyhound Lines, FlixBus, RedBus, Peter Pan Bus Lines, National Express, BlaBlaCar Bus, Keolis, Stagecoach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intercity Bus Travel Market Shifts & Advancements
Digital intermediation is unbundling the traditional operator-passenger relationship, with platform algorithms now controlling pricing, inventory, and customer data while fleet owners compete for dispatch slots.
Modular battery-swapping architectures for heavy-duty coaches are decomposing the capital barrier to fleet electrification. State transport corporations in Gujarat and Karnataka pilot exchange stations that eliminate overnight depot charging infrastructure. This decouples vehicle procurement from charging real estate, compressing the payback period for electric conversion.
The EU General Safety Regulation mandates intelligent speed assistance and automated emergency braking on all new coaches. Vehicle manufacturers must recalibrate supply chains to source lidar and camera systems compliant with UN ECE standards. Long-distance operators in Germany and Poland face compressed procurement cycles as legacy coach models lose type approval.
Younger travelers now book intercity journeys through super-app interfaces that aggregate bus, rail, and ride-hail options. This behavior fragments loyalty toward individual operators and concentrates it on comparison platforms. India and Indonesia exhibit the most pronounced shift, where RedBus and Traveloka have become default search layers above carrier brands.
Intercity Bus Travel Market Segmentation
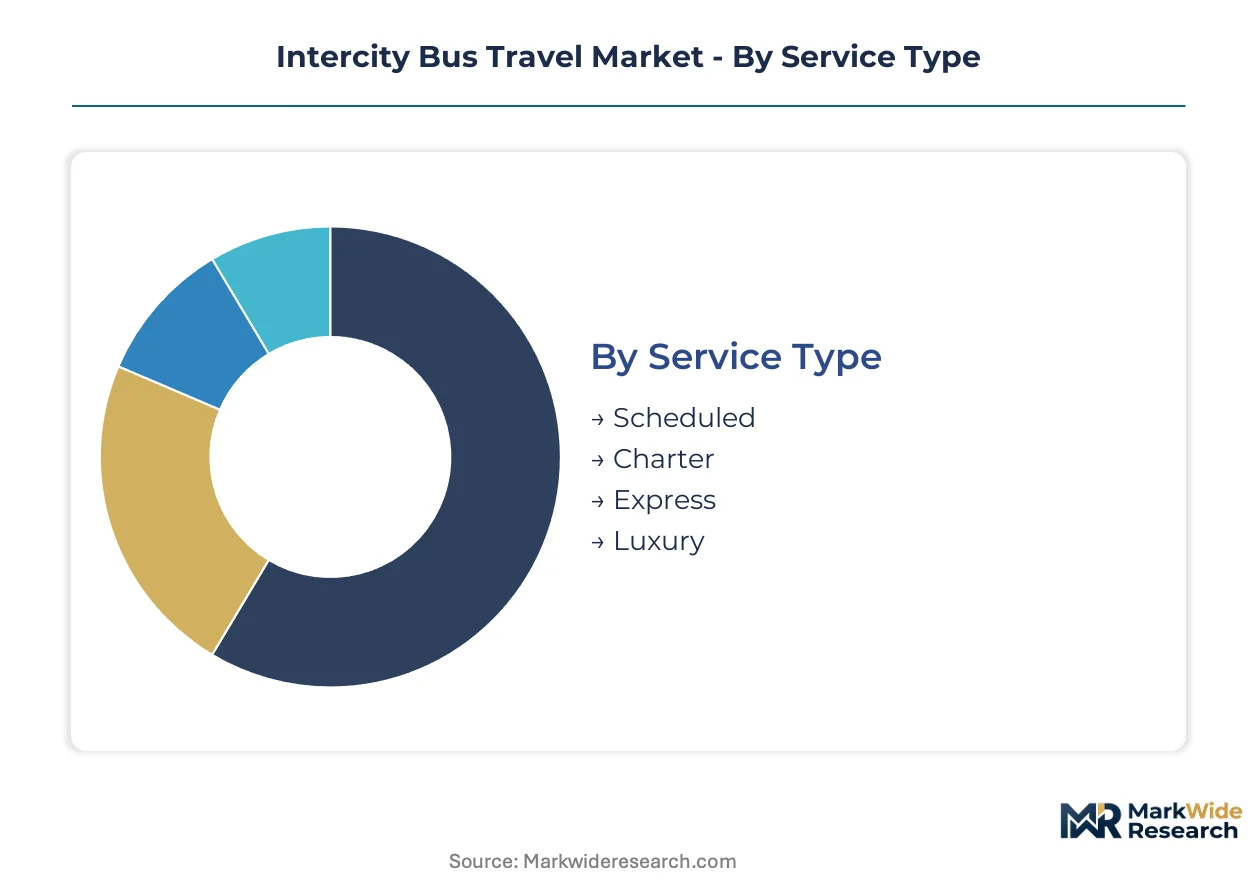
Intercity bus operators calibrate fleet configuration and revenue management to distinct demand profiles across service tiers. Segmentation discipline determines which corridors justify premium sleeper deployments versus high-frequency commuter shuttles.
Service Type:
Margin pools concentrate in charter operations where corporate event planners and tourism agencies absorb premium pricing, while scheduled services compete on volume efficiency.
- Scheduled:Fixed-route departures on trunk corridors with published timetables. Demand clusters in India and Southeast Asia where RedBus aggregates fragmented private operators into unified digital marketplaces, compressing revenue leakage through dynamic yield algorithms.
- Charter:Dedicated vehicle deployment for tourism agencies, corporate events, and wedding parties. Operators in Germany and Poland command premium day-rates during summer festival seasons, offsetting winter utilization troughs.
- Express:Non-stop corridor services between major urban centers with limited intermediate stops. Indian state transport corporations deploy these on Golden Quadrilateral routes to compete with budget rail.
- Luxury:Reclining sleeper berths, onboard entertainment, and meal service on overnight routes. Brazilian operators running São Paulo-Rio de Janeiro overnights extract 3x per-kilometer revenue versus standard coaches.
The dominant share belongs to Scheduled, while Express is closing the gap fastest through platform-based aggregation and real-time inventory optimization.
Ticketing Model:
Customer acquisition economics vary sharply by booking behavior, with subscription models locking in predictable cash flows against the volatility of walk-up demand.
- Advance Booking:Reservations made hours to weeks before departure through mobile apps or agent networks. European FlixBus passengers exhibit 72-hour median booking windows, enabling load-factor optimization.
- On-Demand:Real-time seat purchase through super-app interfaces. Indonesian Traveloka users increasingly book intercity bus seats within two hours of departure, compressing operator forecasting horizons.
- Subscription:Monthly or quarterly passes for recurring commuters. National Express in Britain structures these around airport link corridors, guaranteeing revenue on thin-margin routes.
- Walk-Up:Terminal-based purchases without prior reservation. Legacy Greyhound infrastructure in the United States still processes material walk-up volume at owned city-center depots.
Advance Booking commands the revenue base, though Subscription is climbing the fastest as employers fund employee commuter benefits.
Vehicle Type:
Capital deployment intensity separates fleet strategies, with sleeper configurations requiring 2.5x per-unit investment against standard coaches.
- Standard Coach:Single-deck configuration with 45-55 seats and underfloor luggage compartments. Indian private operators favor Ashok Leyland and Volvo chassis for 300-500 kilometer corridor density.
- Double-Decker:Two-level seating for 70-85 passengers on high-volume trunk routes. Megabus in Britain and FlixBus in Germany deploy these on London-Paris and Berlin-Munich corridors where terminal height clearances permit.
- Sleeper Bus:Reclining berths replacing seats for overnight journeys. Operators in Vietnam and Thailand run these on 10-14 hour corridors where rail alternatives lack frequency.
- Minibus:16-30 seat configurations for thin-density secondary routes. Spanish regional cooperatives deploy these on Pyrenees feeder services connecting villages to high-speed rail stations.
Standard Coach retains volume leadership, yet Sleeper Bus is gaining share fastest through rising demand for overnight tourism corridors.
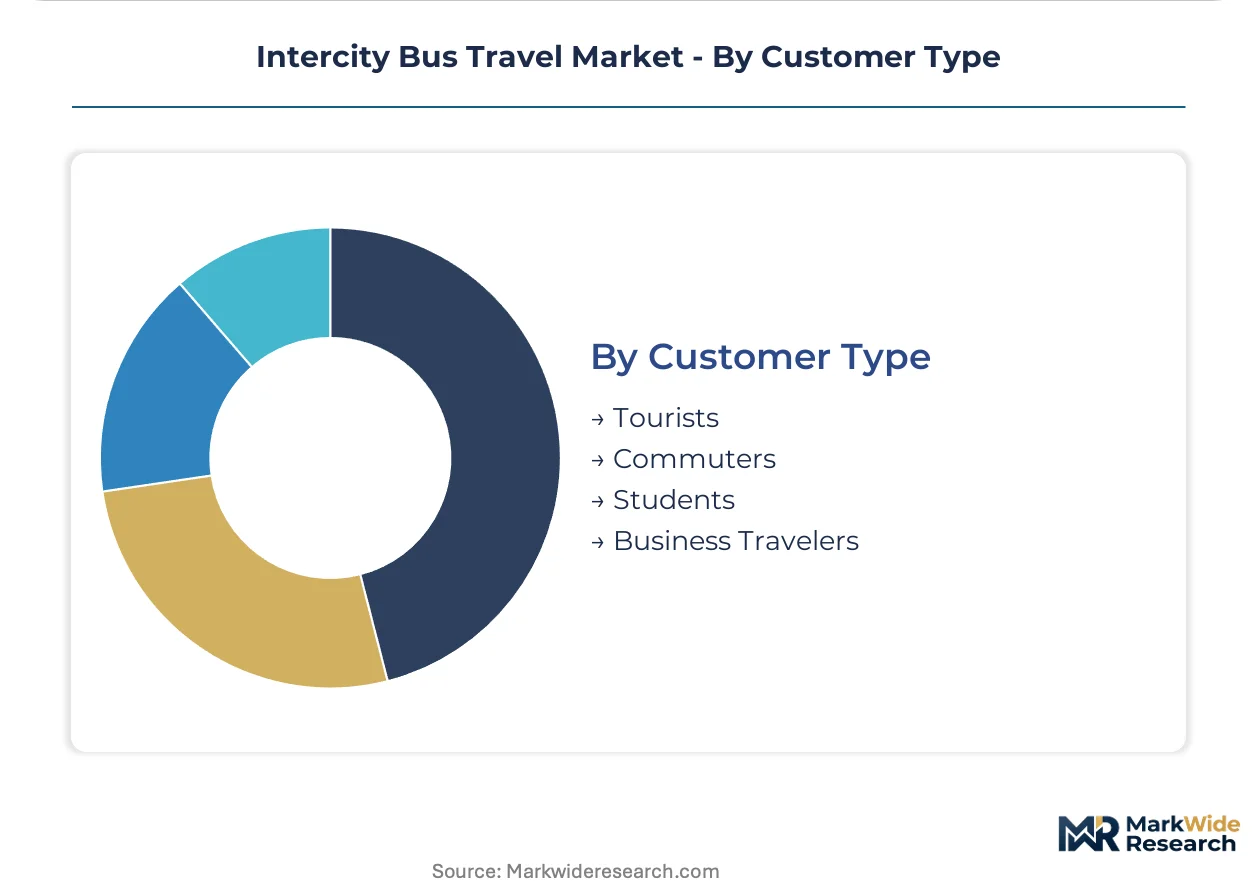
Customer Type:
Price sensitivity gradients across traveler categories determine ancillary revenue potential and loyalty program design.
- Tourists:Leisure travelers booking packaged itineraries or independent exploration. European city-hopper routes from Prague to Budapest concentrate demand in summer months.
- Commuters:Regular travelers between residence and workplace across metropolitan exurbs. Mexico City-Puebla corridor sustains 15-minute headcounts through dedicated commuter lanes.
- Students:University-term travel with extreme price elasticity. Indian RedBus issues verified student discounts capturing 18-24 year old loyalty before income growth shifts modal preference.
- Business Travelers:Corporate account passengers requiring flexibility and receipt documentation. Airport link specialization by National Express targets this segment with guaranteed connection times.
Commuters anchor the revenue base, while Business Travelers are expanding most quickly through corporate shuttle contracting and guaranteed monthly payment structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian commuters exhibit extreme price sensitivity, squeezing margins on trunk corridors. German passengers accept premium fares for carbon-neutral services. Brazilian tourists absorb sleeper-bus premiums on overnight leisure routes.
India
RedBus aggregates fragmented private operators into unified digital marketplaces, compressing revenue leakage through dynamic yield algorithms. The Ministry of Road Transport mandates fitness certification and speed governor installation through state transport authorities, conditioning market access. State transport corporations in Gujarat and Karnataka pilot modular battery-swapping exchange stations for electric coach trials.
Germany
FlixBus leverages partnership-based network expansion without owning depots or vehicles, capturing price-sensitive corridor demand. The EU General Safety Regulation mandates intelligent speed assistance and automated emergency braking on all new coaches, forcing compressed procurement cycles. Berlin-Munich trunk routes concentrate double-decker deployments where terminal height clearances permit.
United States
Greyhound Lines sustains position through owned terminal infrastructure and fixed-route density, processing material walk-up volume at city-center depots. The Federal Motor Carrier Safety Administration enforces hours-of-service limits and vehicle inspection protocols, constraining fleet utilization and forcing redundant crew rotations. Northeast Corridor express services compete with budget air on routes under 500 kilometers.
Brazil
Operators running São Paulo-Rio de Janeiro overnights extract premium per-kilometer revenue through reclining sleeper berths with onboard entertainment and meal service. ANVISA regulates passenger transport safety standards alongside state-level environmental licensing. Southeast corridor density concentrates luxury coach manufacturing demand around São Paulo industrial clusters.
United Kingdom
National Express anchors intercity connectivity through regulated concession contracts and airport link specialization, targeting business travelers with guaranteed connection times. The Department for Transport oversees bus service registration and public service obligation frameworks. London-Paris international routes deploy double-decker configurations through Channel Tunnel shuttle compatibility.
Intercity Bus Travel Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Asset-light platform operators monetize demand forecasting and dynamic pricing algorithms while fleet-owning incumbents compete on terminal real estate and fixed-route density. Three archetypes dominate: technology intermediaries controlling customer data, integrated operators with captive infrastructure, and regional specialists serving thin-density secondary corridors. Competitive moves concentrate on strategic partnerships for network expansion and fleet electrification procurement coalitions.
Among European-based mobility platforms, FlixBus and BlaBlaCar Bus exemplify the asset-light intermediary archetype, while ALSA represents the integrated operator model with captive terminal infrastructure. RedBus occupies a distinctive position as a technology aggregator in fragmented emerging markets, converting thousands of independent fleet owners into dispatch-compliant network participants without direct vehicle ownership.
| Leading Market Players |
|---|
| ALSA |
| Greyhound Lines |
| FlixBus |
| RedBus |
| Peter Pan Bus Lines |
| National Express |
| BlaBlaCar Bus |
| Keolis |
| Stagecoach |
| Others |
Supply & Pricing Matrix
Take-or-pay contracts between state transport corporations and fleet operators lock in corridor access and price visibility across Indian trunk routes, insulating procurement budgets from diesel volatility while committing operators to minimum kilometer guarantees.
Pricing Analysis
Ancillary revenue from onboard Wi-Fi, meal service, and seat selection drives lifetime value per passenger. Three-tier pricing structure across luxury sleeper, express standard, and economy non-AC levels captures differential willingness-to-pay. Cost compression in economy tiers intensifies because platform commission rates squeeze operator margins. Students and daily commuters exhibit extreme price sensitivity, while corporate shuttle contracting absorbs premium pricing for guaranteed availability.
Supply Chain Analysis
Strategic stockpiling of chassis and powertrain components dominates fleet procurement, with operators pre-ordering diesel and electric coach platforms to secure manufacturing slots. Coach assembly draws from Germany, China, and India, with Volvo and Scania anchoring premium segments. Lithium-ion battery cells, steel hulls, and HVAC systems constitute critical input dependencies. Single-source vulnerability for semiconductor-based telematics modules threatens dispatch reliability. Distribution runs through authorized dealer networks and direct OEM contracts to fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
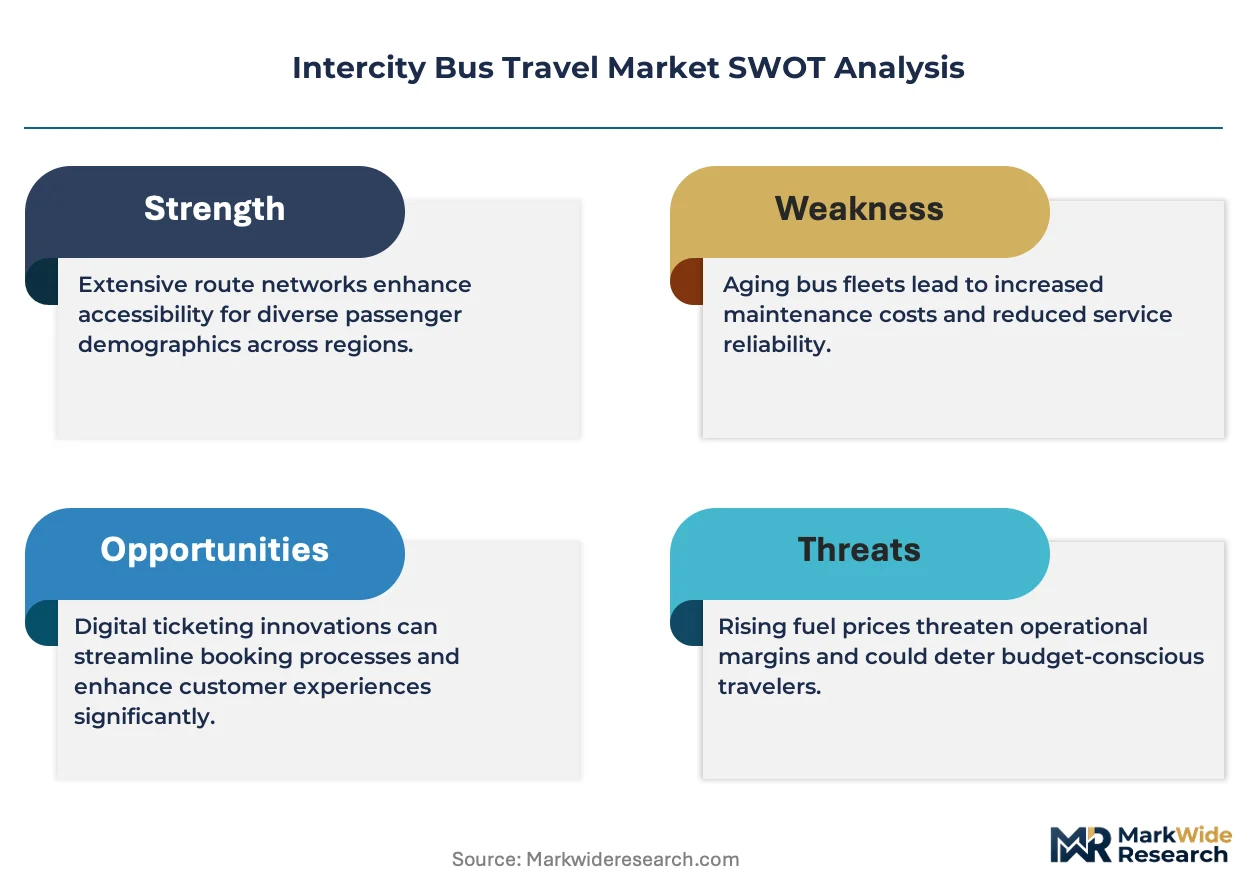
Intercity bus incumbents face substitution defense against high-speed rail expansions and mobility-as-a-service platforms that aggregate multimodal alternatives into unified booking interfaces.
For Market Incumbents: Compound terminal real estate control with fleet electrification procurement coalitions to deflect platform disintermediation. Secure long-term concession contracts at city-center depots before asset-light intermediaries negotiate access. Prioritize backward integration into charging infrastructure to capture carbon credit monetization streams. For New Entrants and Emerging Players: Anchor in corporate shuttle contracting for tech campuses and manufacturing parks where guaranteed monthly payments replace volatile per-seat retail. Target thin-density secondary corridors in ASEAN markets where fragmented bilateral permits currently throttle competition. Deploy super-app integration as the primary go-to-market angle to bypass legacy terminal dependencies. For Investors and Strategic Acquirers: Asset-light platform operators with proven demand-forecasting algorithms present the strongest acquisition profile for portfolio exposure to mobility digitization. Long-term viability hinges on corridor control duration and platform commission rate sustainability. Watch for harmonized customs protocols across Vietnam, Cambodia, and Thailand as the inflection indicator for Southeast Asian network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Procurement Coalition | Pooled purchasing power accelerates zero-emission coach trials under EU Green Deal compliance timelines. |
| Terminal Concession Contract Renewal | City-center depot access locks in walk-up revenue streams against platform intermediation. |
| Dynamic Yield Algorithm Deployment | Machine learning load-factor optimization compresses revenue leakage from empty seats. |
| Cross-Border ASEAN Permit Harmonization | Bilateral customs protocol alignment unlocks through-running between Vietnam, Cambodia, and Thailand. |
| Corporate Shuttle Contracting Expansion | Guaranteed monthly payments from tech campuses shift revenue from volatile retail to predictable subscriptions. |
Research Methodology
Operator-level perspectives from fleet managers, platform algorithm engineers, state transport authority planners, and terminal concession administrators anchored the qualitative base. These primary insights combined with secondary validation from Ministry of Road Transport circulars, Federal Motor Carrier Safety Administration enforcement data, EU General Safety Regulation implementation notices, and customs trade records. Bottom-up corridor-level demand modeling triangulated against top-down mobility expenditure forecasts.
Sensitivity analysis tested forecast robustness across diesel price volatility scenarios, platform commission rate shifts, and high-speed rail completion timelines throughout the projection horizon. Segmentation dimensions modeled include service type, ticketing model, vehicle configuration, and customer category alongside corridor density tier and regulatory framework cluster. CAGRs derived from historical fleet deployment trajectories, passenger-kilometer elasticity coefficients, and modal substitution rates. Electric coach adoption curves and battery-swapping infrastructure rollout schedules served as industry-specific forecast inputs.
Material uncertainties — carbon border adjustment implementation, digital platform liability rulings, and vocational technician training pipeline scaling — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and technology cost curves. Revision becomes warranted when EU ETS linkage mechanisms or ASEAN customs harmonization crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
City Bus Low-Floor Axle Systems Market
Buses
United States School Bus Market
Buses
Africa Electric Bus Market
Buses
Bus Seat Market
Buses
United States Electric Bus Market
Buses
Electric Intercity Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Airport Bus Market
Buses
School Bus Market
Buses
Solar Bus Market
Buses
Luxury Coaches Market
Buses
Bus Transmission System Market
Buses
Hydrogen CNG Bus Market
Buses
Buses & Coaches Market
Buses
Bus Rental Market
Buses
Europe Trolley Bus Market