
 Airport Shuttle Bus Market | 2026-2036
Airport Shuttle Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Shuttle Bus Market Outlook
Aluminum-intensive body structures is expanding across airport shuttle manufacturing as OEMs reduce vehicle weight to extend electric range. BYD Company Limited leverages its integrated battery-cell-to-chassis capability to dominate the electric shuttle segment in Asia-Pacific airports. Volvo Group anchors its position through proprietary autonomous-ready platforms designed for constrained airside environments. Solaris Bus & Coach differentiates via modular floor heights that accommodate both apron-level and elevated-jetway boarding configurations.
An airport shuttle bus is a purpose-built ground transportation vehicle, typically measuring 9 to 14 meters in length, designed to operate on fixed routes between terminal facilities, remote parking structures, rental car centers, and aircraft hardstands. Its primary commercial function is to maximize passenger throughput per vehicle-hour while conforming to airside dimensional and turning-radius constraints. Shared shuttle services represent the mature volume base, though luxury shuttle and executive shuttle categories are capturing disproportionate margin pools as premium travelers seek predictable transit times. Coach-type vehicles lead the fleet mix at hub airports, while minivan configurations are gaining share at secondary facilities with lower peak-demand requirements.
The EPA and FAA jointly influence airport shuttle specifications in the United States, with the EPA setting tailpipe emissions thresholds and the FAA governing airside vehicle dimensions and safety systems. In Europe, the EU Green Deal and F-Gas Regulation are compressing diesel fleet retention timelines while mandating low-global-warming-potential refrigerants in climate-control systems. Stakeholders must monitor how pending airside electrification infrastructure grants reshape capital deployment priorities between vehicle procurement and charging hardware.
Market Dynamics
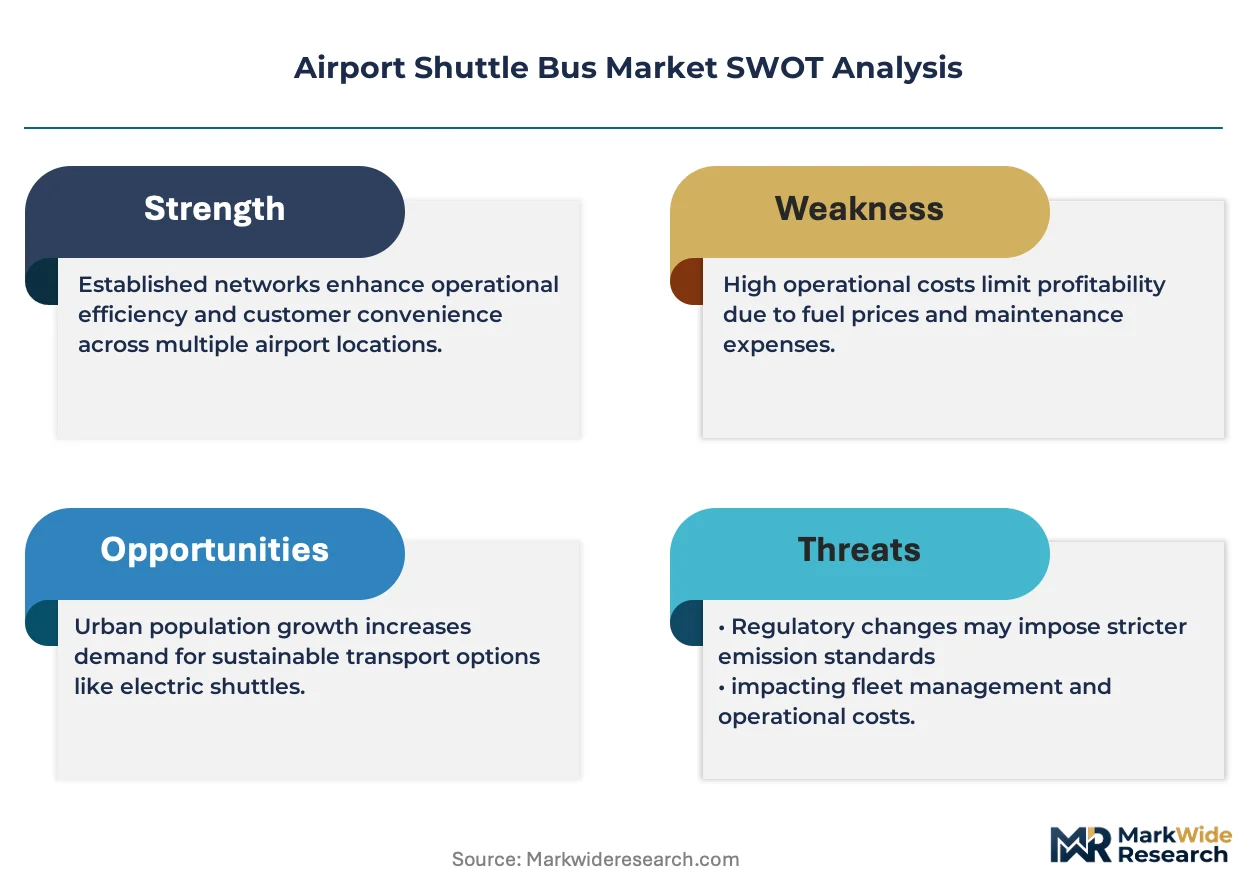
Fleet electrification timelines are compressing across major airport authorities as battery energy density improvements and airside charging infrastructure investments converge to enable operational parity with diesel equivalents.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation are accelerating diesel fleet phaseouts while mandating low-global-warming-potential refrigerants in climate-control systems, forcing procurement shifts toward zero-emission platforms.
- Aluminum-intensive architectures:OEMs are reducing vehicle weight through aluminum-intensive body structures to extend electric range, enabling longer routes between charging cycles at hub airports.
- Atlanta and Dallas-Fort Worth demand concentration:United States airport authorities at these facilities are consolidating shuttle procurement under single-vendor frameworks to standardize maintenance protocols and reduce parts inventory complexity.
Market Restraints
- Lithium supply concentration:Battery cell production concentrates in China and South Korea, exposing fleet operators to raw material price volatility and geopolitical supply disruption risks.
- Airside charging infrastructure capex:High-voltage charging hardware deployment requires extensive electrical grid upgrades and fire suppression systems, stretching capital deployment timelines.
- FAA dimensional constraints:The FAA's strict turning-radius and height specifications limit platform flexibility, preventing economies of scale from cross-industry bus designs.
Strategic Opportunities
- Autonomous-ready platform adoption:Constrained airside environments with predictable routes and controlled speeds create ideal deployment conditions for autonomous shuttle pilots before urban road certification.
- Modular floor height configurations:Dual-level boarding systems that accommodate both apron-level and elevated-jetway access enable single-fleet deployment across mixed infrastructure airports.
- IRA clean vehicle tax credits:The Inflation Reduction Act's commercial clean vehicle credits reduce effective procurement costs for United States airport authorities electrifying legacy diesel fleets.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack sufficient electricians certified for megawatt-class battery systems, forcing reliance on OEM service contracts.
- Airside certification timelines:FAA airworthiness-style safety approvals for new electric platforms extend 18-24 months, delaying revenue service entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Shuttle Bus Market |
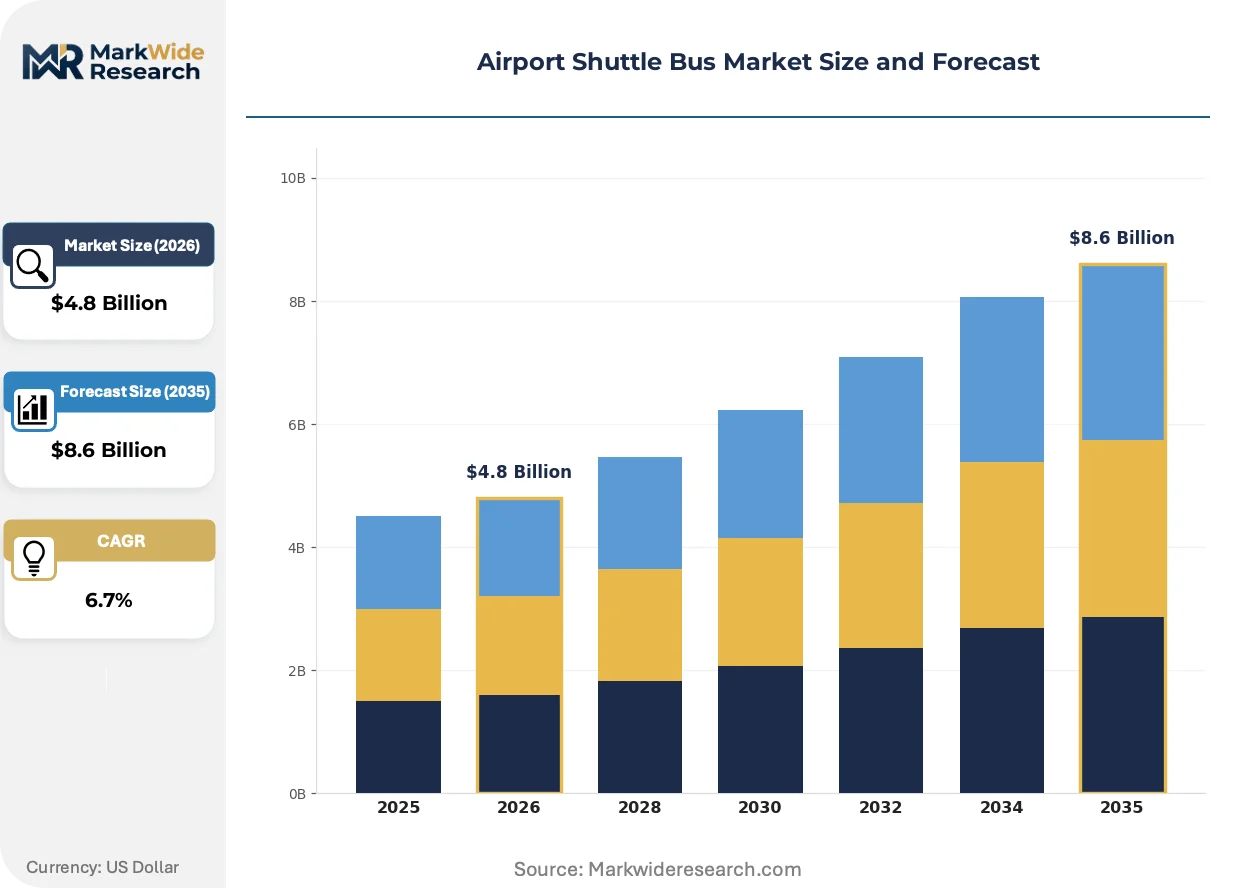
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Shared Shuttle, Private Shuttle, Luxury Shuttle, Executive Shuttle Vehicle Type: Minivan, Coach, SUV, Standard Bus Booking Channel: Online Booking, Travel Agency, Mobile App, Direct Call Customer Type: Business Travelers, Tourists, Airport Staff, Event Attendees |
| Companies Covered | BYD Company Limited, Volvo Group, Yutong Bus Co. Ltd., MAN Truck & Bus, Daimler Truck AG, New Flyer Industries, Proterra Inc., Solaris Bus & Coach, Traton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Shuttle Bus Market Strategic Shifts
Battery-electric drivetrains are overtaking diesel-electric hybrids as the dominant propulsion architecture, reshaping supplier relationships and maintenance skill requirements across airport ground transportation.
Cell-to-chassis battery integration is overtaking modular pack designs by eliminating redundant structural housings and improving volumetric energy density. Tier 1 suppliers are embedding thermal management directly into floor pans, reducing component count. This architecture is compressing vehicle weight and extending range without increasing battery mass, enabling compliance with FAA axle-load limits.
The EPA's tailpipe emissions thresholds are tightening commercial vehicle standards in coordination with state-level zero-emission mandates. California Air Resources Board rules are cascading into neighboring states through regulatory harmonization. Hub airports in the United States are responding by consolidating procurement specifications to ensure multi-state fleet interoperability.
Service contracting is fragmenting from bundled vehicle-plus-maintenance packages toward unbundled hardware procurement with separate uptime-guarantee agreements. Large hub operators are negotiating availability-based payments rather than capital purchases. This shift is most visible at major United States international airports where fleet sizes justify dedicated on-site technician deployment.
Airport Shuttle Bus Market Segmentation
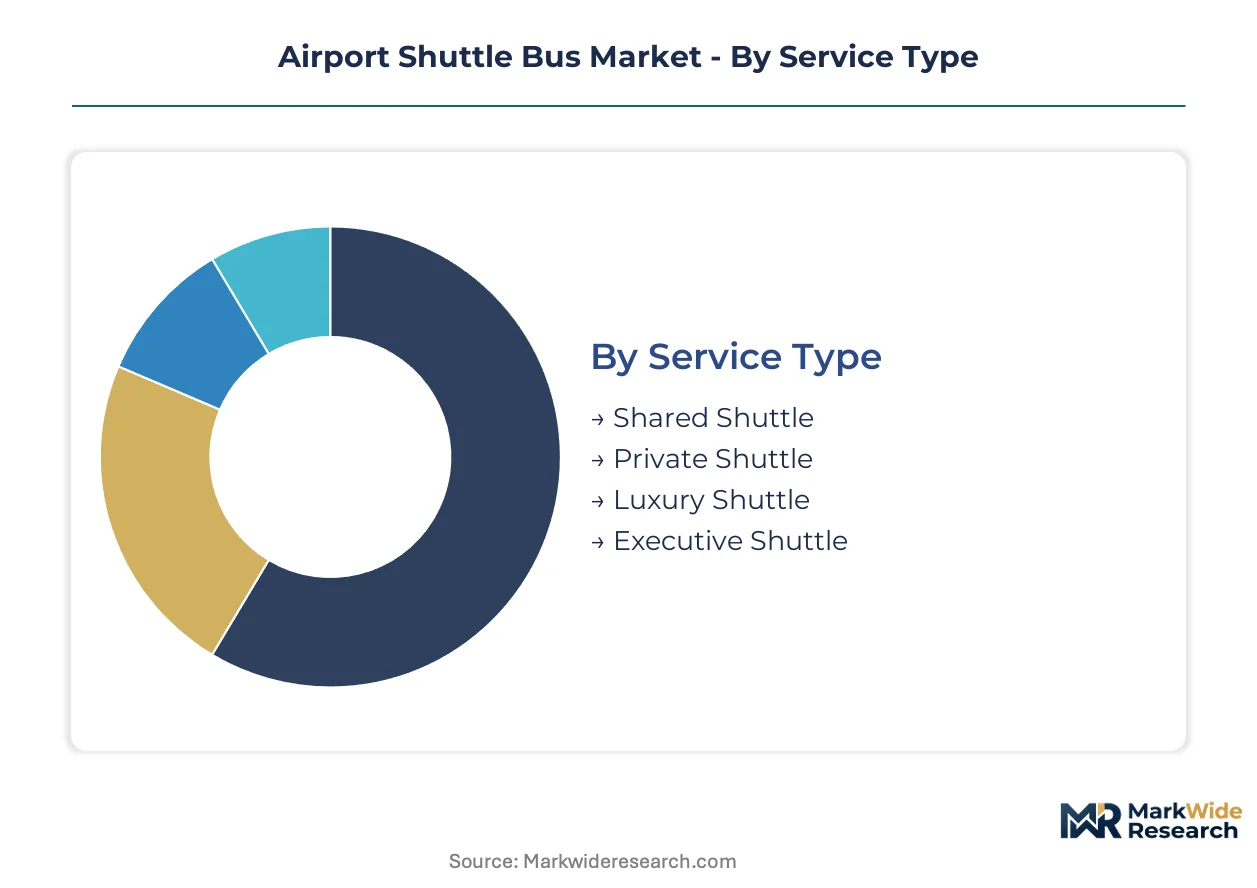
Airport shuttle bus segmentation reveals how procurement patterns concentrate around operational constraints and passenger throughput economics. Fleet managers prioritize vehicle configurations that maximize passenger density while satisfying airside dimensional limits.
Service Type:
Supply concentration favors high-frequency shared operations at hub airports, though margin pools are migrating toward differentiated service tiers.
- Shared Shuttle:High-capacity vehicles operating fixed routes between terminals, parking structures, and rental car centers. Demand concentrates at Atlanta Hartsfield-Jackson and Dallas-Fort Worth International Airport where consolidated procurement frameworks reduce parts inventory complexity.
- Luxury Shuttle:Leather-appointed interiors with guaranteed seating and expedited routing for premium travelers. Business travelers at major international hubs drive disproportionate margin capture as predictable transit times command fare premiums.
- Private Shuttle:Dedicated vehicles for corporate contracts and group charters with flexible scheduling.
- Executive Shuttle:Curbside-to-gate service with luggage assistance and priority security lane coordination.
Today's leader: Shared Shuttle. Tomorrow's challenger: Luxury Shuttle.
Vehicle Type:
Procurement patterns track directly to passenger volume thresholds and infrastructure constraints at specific airport tiers.
- Coach:12-14 meter length with standing capacity exceeding 80 passengers. Hub airports deploy these as the fleet backbone where FAA turning-radius specifications and axle-load limits govern platform selection.
- Minivan:9-10 meter configurations with 12-15 passenger capacity. Secondary facilities with lower peak-demand requirements favor these for operational flexibility and reduced curb footprint.
- SUV:Premium configurations for executive and private shuttle tiers with luggage capacity tradeoffs.
- Standard Bus:Mid-length platforms bridging coach and minivan economics for medium-hub deployment.
Coach configurations anchor current fleet economics. Minivan platforms are expanding most quickly at secondary airports.
Booking Channel:
Customer acquisition cost structures diverge sharply between digital-first and traditional intermediation.
- Online Booking:Web-based reservation systems with real-time capacity visibility. Corporate travel managers at United States hub airports favor these for centralized expense tracking and policy compliance.
- Mobile App:Location-aware dispatch with push notifications for gate changes and delays. Younger business travelers and tourists drive adoption where integrated payment reduces friction.
- Travel Agency:Bundled ground transportation with flight and hotel packages for international arrivals.
- Direct Call:Voice reservations for accessibility requirements and last-minute schedule changes.
Online Booking captures the volume base. Mobile App shows steepest expansion trajectory among tech-forward traveler segments.
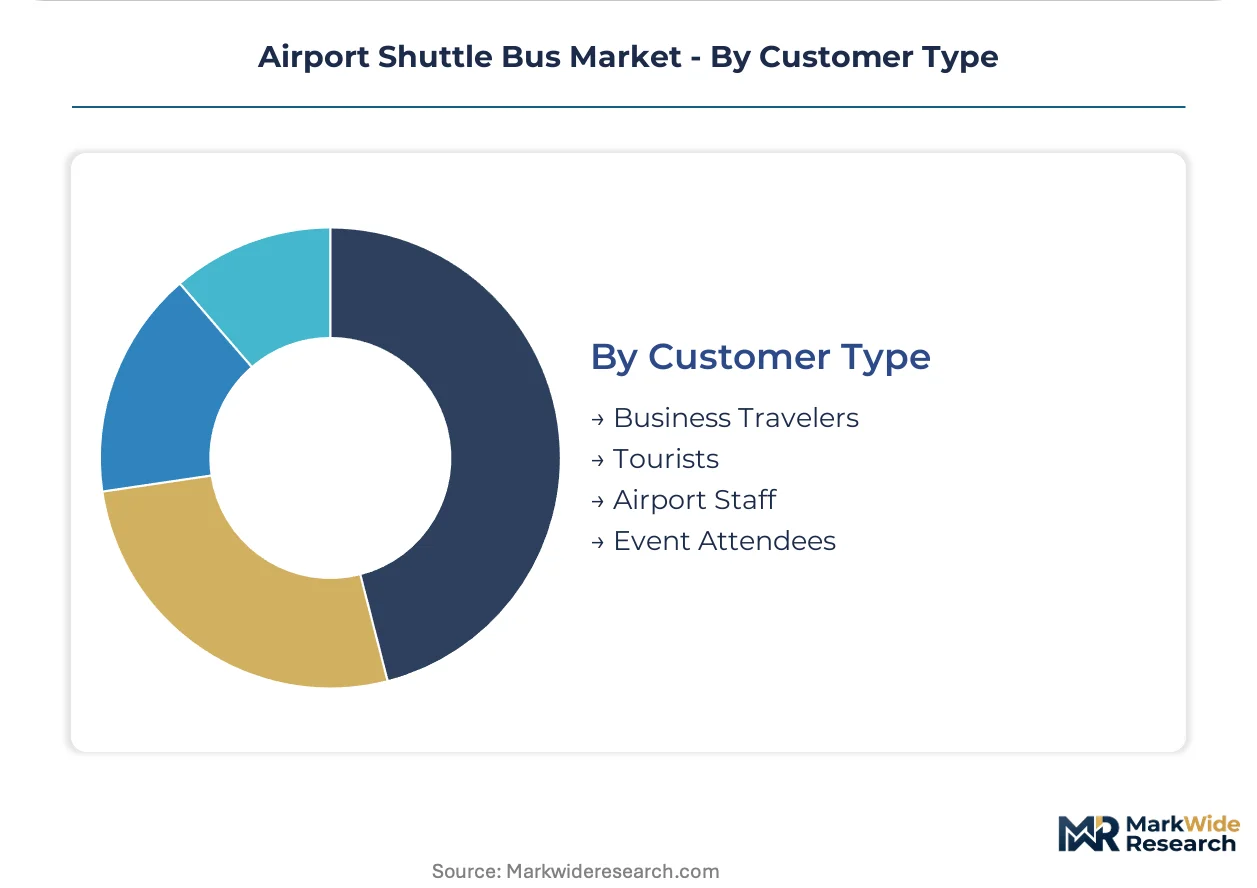
Customer Type:
Revenue per passenger-mile varies by an order of magnitude across these segments, reshaping fleet deployment priorities.
- Business Travelers:Time-sensitive passengers prioritizing schedule reliability over fare minimization. This segment commands premium pricing at Atlanta and Dallas-Fort Worth where consolidated procurement ensures service standardization.
- Tourists:Price-elastic leisure travelers with luggage volume requirements and variable group sizes. Demand concentrates at international gateway airports with multi-terminal configurations.
- Airport Staff:Contracted employee transportation with fixed schedules and high trip frequency.
- Event Attendees:Surge demand tied to convention calendars and sports schedules requiring temporary fleet augmentation.
Business Travelers dominate margin capture. Tourists represent the volume foundation with highest trip frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta Hartsfield-Jackson anchors global airport shuttle procurement volume, with fleet standardization programs reshaping vendor relationships across major hub airports. Regulatory divergence between the EPA's tailpipe thresholds and EU Green Deal mandates is fragmenting procurement specifications by geography. Fleet operators in the United States, Germany, China, and the United Arab Emirates face distinct compliance timelines and infrastructure investment requirements.
United States
Atlanta Hartsfield-Jackson and Dallas-Fort Worth International Airport drive consolidated procurement frameworks that reduce parts inventory complexity. The FAA governs airside vehicle dimensions and safety systems while the EPA sets commercial tailpipe emissions thresholds. California Air Resources Board rules cascade into neighboring states, forcing hub airports to harmonize specifications for multi-state fleet interoperability.
Germany
Frankfurt and Munich airports compress diesel fleet retention timelines under EU Green Deal mandates. The F-Gas Regulation mandates low-global-warming-potential refrigerants in climate-control systems, eliminating legacy procurement options. Baden-Württemberg and Bavaria host OEM engineering centers developing autonomous-ready platforms for constrained airside environments.
China
Beijing Capital and Shanghai Pudong International Airport expand electric shuttle deployment as battery energy density improvements enable operational parity with diesel. MIIT commercial vehicle standards and dual carbon goals accelerate fleet electrification timelines. BYD leverages integrated battery-cell-to-chassis capability to dominate procurement at Asia-Pacific hub airports.
United Arab Emirates
Dubai International Airport concentrates luxury shuttle demand as premium travelers seek predictable transit times. MOHAP and local aviation authorities coordinate airside electrification infrastructure grants that reshape capital deployment priorities. Abu Dhabi deploys high-voltage charging hardware with integrated fire suppression systems for desert climate operations.
United Kingdom
Heathrow Airport consolidates shuttle procurement under availability-based payment structures rather than capital purchases. The UK Environment Agency enforces emissions standards that compress diesel fleet phaseout timelines. London's hub operators negotiate uptime-guarantee agreements with dedicated on-site technician deployment.
Airport Shuttle Bus Market Competitive Environment
Global majors compete with regional champions across electrification capability and airside certification expertise. The vendor base clusters around three tiers: integrated battery-to-vehicle specialists, autonomous-ready platform developers, and modular configuration specialists. Strategic archetypes include cell-to-chassis integrators, aluminum-intensive architecture pioneers, and dual-level boarding system innovators. Competitive moves concentrate on M&A for charging infrastructure capabilities and strategic partnerships for airside certification acceleration.
Within the integrated drivetrain tier, BYD Company Limited and Proterra Inc. represent cell-to-chassis architecture approaches that eliminate redundant structural housings. Volvo Group anchors Scandinavian engineering positions through autonomous-ready platform development. Solaris Bus & Coach exemplifies modular configuration specialists serving mixed-infrastructure airports with dual-level boarding systems. Yutong Bus Co. Ltd. occupies scale-driven positions in Asia-Pacific procurement frameworks. MAN Truck & Bus and Daimler Truck AG sit within European commercial vehicle conglomerates diversifying into zero-emission airport applications.
| Leading Market Players |
|---|
| BYD Company Limited |
| Volvo Group |
| Yutong Bus Co. Ltd. |
| MAN Truck & Bus |
| Daimler Truck AG |
| New Flyer Industries |
| Proterra Inc. |
| Solaris Bus & Coach |
| Traton |
| Others |
Value Chain & Pricing Dynamics
Hub airport authorities in the United States operating consolidated procurement frameworks command substantial volume leverage, compressing supplier margins through availability-based contracting rather than capital purchases. This buyer concentration shapes a pricing model where fleet standardization incentives override unit-cost minimization, embedding long-term service obligations into upfront vehicle negotiations.
Pricing Analysis
Aluminum sheet and lithium carbonate cost pass-through clauses dominate contract structures, with OEMs indexing base vehicle prices to London Metal Exchange benchmarks. Three-tier pricing structure across premium, standard, and economy levels segments by after-sales service bundling and charging infrastructure inclusion. Cost compression in the minivan configuration tier is intensifying because secondary airports lack procurement scale to negotiate uptime guarantees. Tourists and price-sensitive leisure travelers exhibit highest price sensitivity, while business travelers purchasing luxury shuttle access show minimal elasticity.
Supply Chain Analysis
FAA airworthiness certification and EU type-approval gating restrict supplier participation to established commercial vehicle manufacturers with dedicated airside engineering teams. Cell production concentrates in China and South Korea, while aluminum extrusion and chassis fabrication centers on Germany and the United States. Battery cell supply draws from concentrated Asian manufacturing, exposing fleet operators to lithium hydroxide price volatility and geopolitical disruption risk. Distribution runs through OEM-direct sales organizations with embedded field service engineering, bypassing traditional commercial vehicle dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance timelines compress fleet replacement cycles faster than EPA thresholds, creating procurement timing advantages for operators with multi-continental footprints.
For Market Incumbents: Lock in cell-to-chassis architecture advantages through exclusive supply agreements with battery manufacturers possessing integrated mining-to-cell capabilities. Defend against autonomous-ready platform disruption by accelerating FAA certification timelines for pilot programs at Atlanta Hartsfield-Jackson. Prioritize vertical integration into high-voltage technician training programs to reduce OEM service contract dependency. For New Entrants and Emerging Players: The gap between luxury shuttle premiums and shared shuttle economy fares creates entry space for mid-tier configurations with guaranteed seating but without curbside-to-gate service. Secondary airports in the United States with aging diesel fleets represent the most penetrable geography. Pursue unbundled hardware procurement with separate uptime-guarantee agreements to bypass incumbent maintenance bundling advantages. For Investors and Strategic Acquirers: Battery-electric commercial vehicle specialists are the most active acquirer in this space, seeking airside certification expertise to accelerate urban autonomy deployment. Five-to-ten year viability hinges on charging infrastructure ownership positions rather than vehicle manufacturing scale. Acquisition targets should display FAA airside approval track records and established relationships with major hub authorities. Monitor Inflation Reduction Act clean vehicle credit renewal negotiations as the critical inflection signal for United States electrification capex timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium cell allocation from CATL or BYD for fleet electrification programs at major hubs. |
| Charging Infrastructure Partnership | Deploys megawatt-class hardware with integrated fire suppression for desert climate operations in UAE. |
| Platform Standardization | Enables single-fleet deployment across mixed apron-level and elevated-jetway boarding configurations. |
| Geographic Manufacturing Footprint | Establishes final assembly proximity to Atlanta and Dallas-Fort Worth procurement concentration. |
| Software-Defined Vehicle Investment | Builds autonomous-ready control systems for constrained airside environments before urban certification. |
Study Parameters
Multiple input streams — fleet manager interviews, OEM engineering director discussions, airport authority procurement officer consultations, and regulatory affairs specialist engagements — were reconciled against secondary validation. Primary fieldwork engaged maintenance directors at hub airports, Tier 1 supplier battery platform engineers, aftermarket service heads for charging infrastructure, and FAA certification specialists. Secondary sources encompassed EPA tailpipe emissions filings, EU Green Deal implementation progress reports, FAA airside vehicle dimension standards, and airport authority fleet procurement disclosures. Bottom-up vehicle deployment counts and top-down airport ground transportation expenditure estimates were triangulated to establish market sizing.
Data-stream reconciliation across supply-side production forecasts and demand-side fleet replacement schedules anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include service tier differentiation, vehicle length classification, propulsion architecture, and regional regulatory cluster. CAGRs were derived from fitted adoption curves for battery-electric platforms against diesel fleet retirement timelines. Forecast inputs incorporated battery energy density improvement trajectories and airside charging infrastructure deployment schedules at named hub airports.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook by compressing electrification timelines and reshaping supplier competitive positions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and raw material supply continuity. A model refresh is warranted upon material change in IRA clean vehicle credit eligibility criteria or FAA autonomous vehicle certification pathway announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intelligent Bus Shelter Market
Buses
Intercity Bus Travel Market
Buses
Bus Bellows Market
Buses
Airport Bus Market
Buses
Electric Intercity Bus Market
Buses
Canada School Bus Market
Buses
United States Electric Bus Market
Buses
Bus Flooring Market
Buses
Luxury Bus Market
Buses
Solar Bus Market
Buses
Europe Bus Market
Buses
Buses & Coaches Market
Buses
Trolley Bus Market
Buses
Bus Chassis Market
Buses
Hydrogen Buses Market
Buses
Hydrogen CNG Bus Market