
 Global Bus Market | 2026-2036
Global Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bus Market Analysis
The capital-intensity divergence between battery-electric specialists and legacy diesel manufacturers is rotating competitive advantage toward integrated cell-pack producers. BYD Company Ltd. leverages in-house lithium iron phosphate cell production to sustain margin structures that pure assemblers cannot match. Yutong Bus Co., Ltd. anchors its position through vertical control over electric drivetrain manufacturing in Zhengzhou. AB Volvo competes by specializing in premium coach electrification for European long-haul routes.
A bus is a large road vehicle designed to carry multiple passengers, typically featuring a gross vehicle weight exceeding 5,000 kilograms and constructed with a self-supporting or frame-based chassis with fixed seating for 16 or more occupants. Manufacturers produce buses through monocoque or body-on-frame construction methods, with powertrain integration varying by fuel type from internal combustion engines to battery-electric or fuel-cell systems. Electric platforms within the fuel-type taxonomy are capturing the fastest expansion as municipal procurement rules tighten. Coach buses command premium pricing due to longer duty cycles and higher comfort specifications. School buses represent a mature segment with replacement-driven demand tied to fleet-age regulations.
China's MIIT enforces new-energy vehicle production quotas that direct manufacturer capacity toward electric buses. Europe's F-Gas Regulation and EU Green Deal emissions targets compel fleet operators to accelerate zero-emission procurement timelines. India's FAME subsidy framework and PLI scheme for advanced chemistry cells reshape total cost of ownership calculations for public transport authorities. Stakeholders must monitor how battery raw-material sourcing policies in producing jurisdictions affect cell availability and contract pricing.
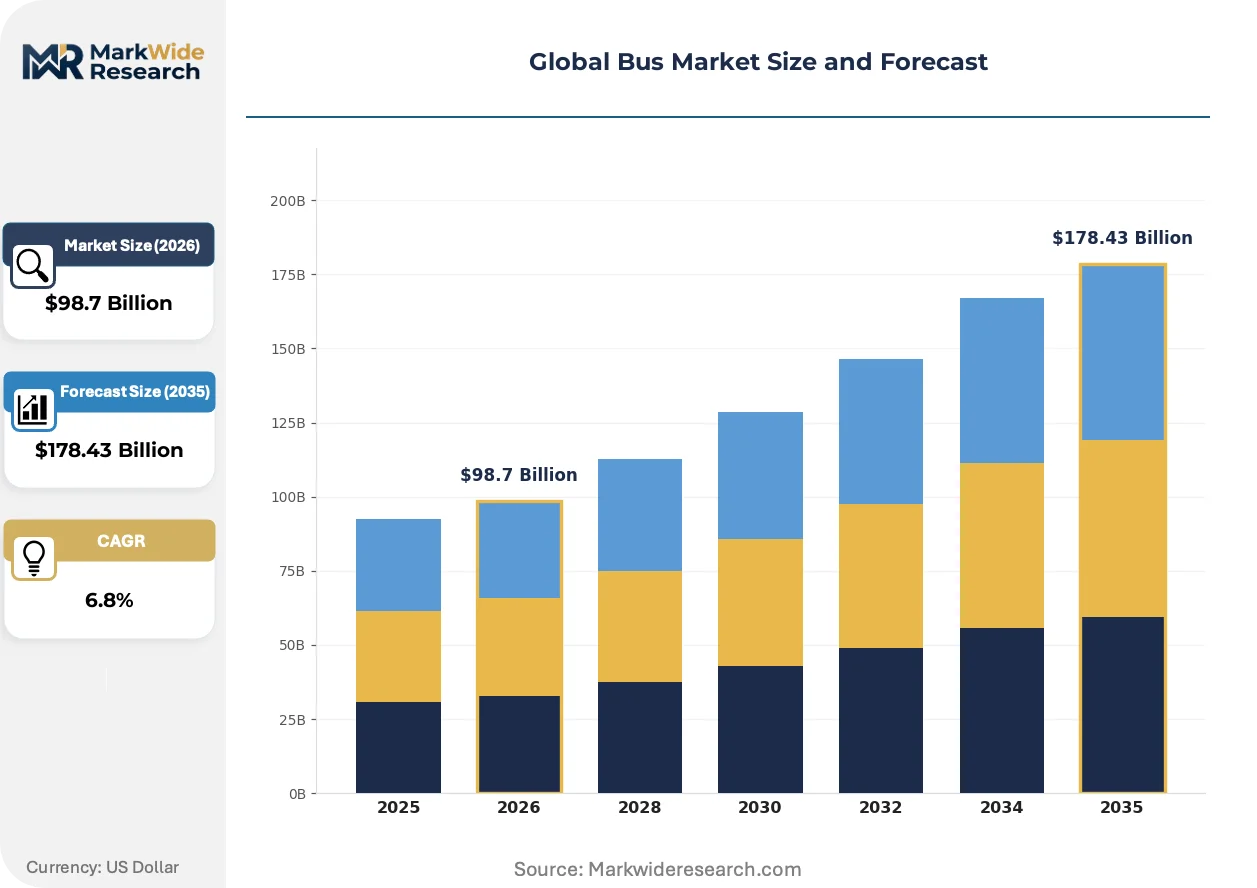
Market Dynamics
The electrification of municipal fleets is compressing replacement cycles and rewiring supplier-buyer power dynamics as battery-electric platforms achieve total cost of ownership parity with diesel alternatives across major procurement jurisdictions.
Growth Catalysts
- FAME subsidy framework:India's PLI scheme for advanced chemistry cells and purchase incentives under Phase II of the FAME program are accelerating fleet electrification commitments by state transport undertakings in Maharashtra, Karnataka, and Delhi.
- Cell chemistry advances:Lithium iron phosphate battery formulations are extending cycle life and reducing thermal management overhead, enabling electric bus operators to sustain higher daily duty cycles without midday charging infrastructure.
- China's MIIT production quotas:Mandatory new-energy vehicle credit requirements are directing domestic manufacturer capacity overwhelmingly toward electric bus platforms, saturating procurement pipelines for municipal operators.
Market Restraints
- Critical mineral concentration:Cobalt and lithium refining capacity clusters in the Democratic Republic of Congo and Chile, exposing cell manufacturers to geopolitical supply interruptions and export restriction risk.
- Charging infrastructure capital intensity:Depot electrification requires grid reinforcement, substation upgrades, and high-capacity charging hardware that strains municipal capital budgets and extends deployment timelines.
- Residual value uncertainty:Secondary markets for retired electric bus battery packs remain underdeveloped, complicating asset depreciation schedules and total cost of ownership modeling for fleet managers.
Strategic Opportunities
- Brazil's urban corridor electrification:São Paulo and Rio de Janeiro municipal authorities are issuing inaugural electric bus tenders, creating first-mover positioning for manufacturers with established tropical climate validation.
- V2G integration with grid services:Bidirectional charging hardware and aggregation software are converging to enable electric bus fleets as distributed energy storage assets, unlocking ancillary revenue streams for operators.
- Leasing and mobility-as-a-service:Asset-light procurement models are displacing traditional capital purchase structures, opening channel access for financial intermediaries and technology-integrated fleet managers.
Industry Challenges
- High-voltage technician scarcity:Maintenance of 600V+ battery systems and power electronics requires specialized certification programs that vocational training institutions have not yet scaled to match fleet deployment rates.
- Homologation timeline compression:Type approval processes for novel electric platforms under UN ECE R100 and local variants are extending 18-24 months, delaying market entry for updated vehicle generations.
- Software-hardware integration complexity:Over-the-air update architectures, battery management systems, and telematics platforms require cross-functional engineering coordination that legacy chassis manufacturers are building through partnership rather than organic capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bus Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Bus, School Bus, Coach Bus, Shuttle Bus Fuel Type: Diesel, CNG, Electric, Hybrid End User: Public Transport Authorities, Private Operators, Schools, Tourism Companies Size: Standard, Mini, Double Decker, Articulated |
| Companies Covered | Yutong Bus Co., Ltd., BYD Company Ltd., Xiamen King Long, CRRC Corporation Limited, AB Volvo, Tata Motors Limited, Ashok Leyland, Daimler Truck AG, NFI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bus Market Emerging Trajectories
Silicon carbide power electronics and solid-state thermal management are converging to extend electric bus range and reduce charging downtime, while procurement digitization is compressing supplier qualification timelines.
Solid-state battery architectures with ceramic electrolyte separators are supplanting conventional liquid-electrolyte lithium-ion packs in premium coach applications. European long-haul operators in Germany and the Netherlands are piloting these platforms for 500+ kilometer daily routes. The technology is supplanting overnight depot charging requirements and enabling interoperable opportunity charging at highway corridor stops.
The EU Green Deal's 90% emissions reduction target for urban buses by 2030 is mandating zero-emission procurement quotas that cascade through member state transposition. Fleet operators in France, Spain, and Italy are accelerating tender schedules to secure manufacturing slots ahead of compliance deadlines. Coach segments with intercity duty cycles face compressed technology transition timelines compared to urban transit applications.
Municipal transport authorities are consolidating procurement through framework agreements and joint purchasing consortia, aggregating demand across multiple cities to extract volume pricing and standardize vehicle specifications. Germany's Verkehrsverbünde and Netherlands' OV-bureau Groningen Drenthe exemplify this concentration. Brazil's metropolitan regions are adopting similar structures as federal infrastructure financing requires coordinated fleet planning.
Global Bus Market Segmentation
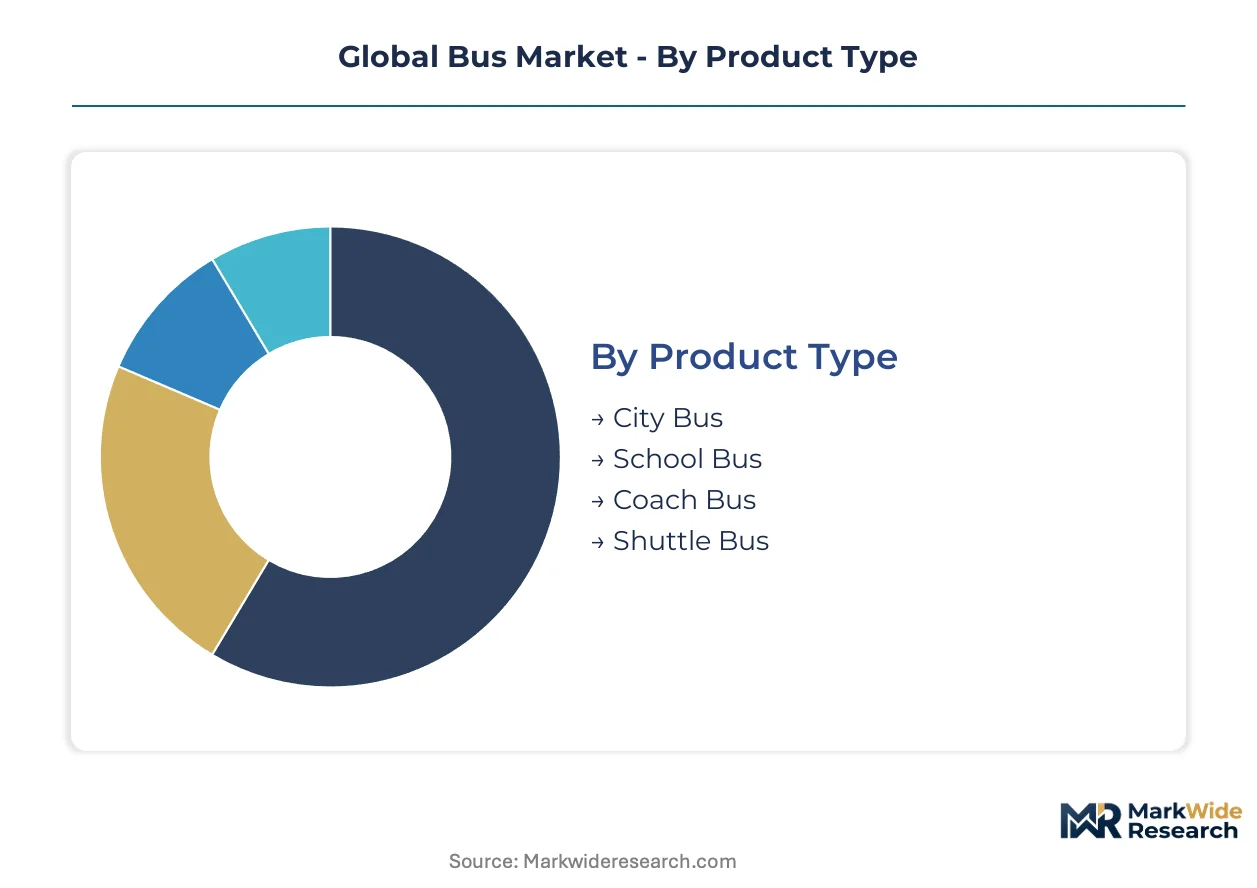
Bus market segmentation reveals divergent procurement patterns across municipal, commercial, and institutional buyers. Technology transitions and regulatory mandates are fragmenting traditional category boundaries as electrification redefines platform economics.
Product Type:
City buses dominate domestic procurement pipelines in China and India, while coach and school bus demand concentrates in North American and European export markets.
- City Bus:These vehicles feature low-floor accessibility, frequent-stop duty cycles, and modular passenger capacity configurations from 35 to 120 occupants. Demand clusters in Chinese megacities where MIIT production quotas mandate electric platform procurement, compressing diesel replacement timelines in Beijing, Shanghai, and Shenzhen municipal fleets.
- School Bus:Purpose-built designs incorporate reinforced side panels, integrated stop-arm signaling, and compartmentalized seating for pupil safety. Procurement concentrates in the United States where NHTSA Federal Motor Vehicle Safety Standards 131 and 222 govern construction specifications, with replacement cycles tied to state-level fleet age limits in Texas, California, and Florida.
- Coach Bus:Long-haul configurations prioritize reclining seats, luggage bays, and climate control systems for intercity routes.
- Shuttle Bus:Compact footprints serve airport circuits, corporate campuses, and last-mile connectivity in urban peripheries.
City buses command the established base. The steepest expansion runs through coach electrification for European long-haul corridors.
Fuel Type:
Cost tier differentiation separates capital-intensive electric platforms from operational-expense-optimized diesel and CNG alternatives across procurement budgets.
- Electric:Battery-electric platforms integrate lithium iron phosphate or nickel manganese cobalt cell packs with regenerative braking and silicon carbide inverters. Demand accelerates in the Netherlands where EU Green Deal targets compel Rotterdam and Amsterdam operators to deploy zero-emission fleets on 500-kilometer daily routes.
- Diesel:Compression-ignition engines with selective catalytic reduction dominate residual fleet composition in markets with limited charging infrastructure. Procurement persists in Brazilian municipal systems where Petrobras refining capacity and established maintenance networks sustain total cost advantages.
- CNG:Compressed natural gas powertrains offer interim emissions reductions through spark-ignited combustion of methane.
- Hybrid:Parallel and series-hybrid architectures combine downsized combustion engines with electric traction motors.
Diesel retains volume leadership in installed base. Electric platforms are climbing the fastest as battery costs compress procurement premiums.
End User:
Customer type determines specification complexity, with public authorities driving standardization and private operators demanding customization.
- Public Transport Authorities:State-owned undertakings in Maharashtra, Karnataka, and Delhi aggregate demand through framework agreements, standardizing vehicle specifications to extract volume pricing. India's FAME Phase II subsidies reshape total cost of ownership calculations, directing procurement toward electric platforms with 250-kilometer minimum range requirements.
- Private Operators:Intercity charter and tour services in Germany prioritize premium coach configurations with sleeper berths and onboard amenities. KBA type approval processes and EU F-Gas Regulation compliance add homologation complexity for cross-border service operators.
- Schools:District-level procurement in North American jurisdictions follows state-specific safety mandates and replacement schedules.
- Tourism Companies:Seasonal demand patterns in Mediterranean and Southeast Asian markets favor convertible-top double-decker configurations.
Public transport authorities anchor procurement volume. Private operators are gaining share fastest through mobility-as-a-service fleet restructuring.
Size:
Application-driven dimensional requirements separate high-capacity articulated platforms from maneuverability-optimized mini configurations.
- Standard:Single-deck 12-meter configurations with 80-100 passenger capacity represent the procurement default for dense urban corridors. Manufacturing concentrates in Zhengzhou and Xiamen production clusters serving domestic Chinese operators and Belt and Road export markets.
- Articulated:18-meter pivot-joint designs with 150-plus capacity serve high-frequency trunk routes in Bogotá TransMilenio and Istanbul Metrobus systems. Brazilian ANVISA certification requirements and tropical climate validation standards create regional specialization barriers for new market entrants.
- Mini:Sub-8-meter footprints navigate restricted road widths in historic European city centers and Japanese residential districts.
- Double Decker:Two-level passenger compartments maximize capacity within road space constraints on London Transport and Hong Kong franchised routes.
Standard configurations command the established base. Articulated platforms are expanding most quickly through bus rapid transit corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese manufacturing clusters where MIIT production quotas compress procurement timelines, while European operators absorb premium costs under EU Green Deal compliance mandates.
China
MIIT new-energy vehicle credit requirements direct manufacturer capacity overwhelmingly toward electric bus platforms. State-owned operators in Beijing, Shanghai, and Shenzhen mandate clean-energy procurement, saturating municipal pipelines. Production gravity centers on Zhengzhou and Xiamen clusters serving domestic demand and Belt and Road export corridors.
India
FAME Phase II subsidies and PLI schemes for advanced chemistry cells reshape total cost of ownership for state transport undertakings. Public authorities in Maharashtra, Karnataka, and Delhi aggregate demand through framework agreements. Fleet electrification accelerates as lithium iron phosphate cell costs fall below diesel parity thresholds.
Germany
KBA type approval processes and EU F-Gas Regulation compliance add homologation complexity for cross-border service operators. Verkehrsverbünde consortium structures aggregate procurement across multiple cities to extract volume pricing. Manufacturing concentrates in Baden-Württemberg and Bavaria for premium coach electrification serving long-haul routes.
United States
NHTSA Federal Motor Vehicle Safety Standards 131 and 222 govern school bus construction specifications, with replacement cycles tied to state-level fleet age limits in Texas, California, and Florida. NFI Group anchors production in North American jurisdictions where depot electrification strains municipal capital budgets.
Brazil
São Paulo and Rio de Janeiro municipal authorities issue inaugural electric bus tenders, creating first-mover positioning for manufacturers with tropical climate validation. ANVISA certification requirements and Petrobras refining capacity sustain diesel total cost advantages in residual fleet composition. Brazilian metropolitan regions adopt joint purchasing consortia as federal infrastructure financing requires coordinated fleet planning.
Global Bus Market Vendor Landscape
Concentration sits with integrated cell-pack producers who control upstream lithium iron phosphate supply. The vendor base stratifies across three tiers: captive battery manufacturers, legacy chassis assemblers building partnership networks, and regional specialists serving tropical or premium coach niches. Dominant competitive moves include backward integration into cell chemistry and geographic expansion through tropical climate validation programs.
Within the integrated-manufacturer tier, BYD Company Ltd. and Yutong Bus Co., Ltd. exemplify archetypes that anchor competitive positioning through in-house production of battery systems. AB Volvo occupies a position on the premium-tier vector for European long-haul electrification. These three entities represent the structural divergence between battery-electric specialists and legacy platforms.
| Leading Market Players |
|---|
| Yutong Bus Co., Ltd. |
| BYD Company Ltd. |
| Xiamen King Long |
| CRRC Corporation Limited |
| AB Volvo |
| Tata Motors Limited |
| Ashok Leyland |
| Daimler Truck AG |
| NFI Group |
| Others |
Supply Flow & Price Mechanics
MIIT new-energy vehicle credit requirements in China gate both supplier qualification and price differentiation simultaneously, compressing procurement timelines for domestic manufacturers while foreign entrants absorb compliance premiums through extended homologation cycles. The interaction between cell chemistry standardization and fleet electrification mandates is collapsing price spreads between battery-electric platforms and residual diesel alternatives across major procurement jurisdictions.
Pricing Analysis
The customization-premium spread separates configured-to-order coach platforms from standardized city bus specifications, with European long-haul operators absorbing design premiums for sleeper berths and climate systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, while cost compression in the standard tier intensifies because lithium iron phosphate cell costs fall below diesel parity thresholds. Public transport authorities in Maharashtra and Karnataka exhibit highest price sensitivity through framework agreement aggregation, whereas German private charter operators demonstrate lowest sensitivity due to EU Green Deal compliance mandates.
Supply Chain Analysis
Cobalt and lithium refining capacity clustering in the Democratic Republic of Congo and Chile exposes cell manufacturers to geopolitical supply interruptions and export restriction risk. The bus manufacturing ecosystem draws from lithium iron phosphate cathode materials, silicon carbide power semiconductors, and high-tensile steel chassis components. Single-source vulnerability concentrates in tropical climate validation testing facilities for Brazilian market entry. Distribution runs through state-owned operator procurement consortia in China and India, with aftermarket service networks anchoring European and North American channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification mandates fragment procurement patterns across municipal, intercity, and institutional buyers, creating specialization niches for battery chemistry integrators and climate-validation specialists.
For Market Incumbents: Consolidate backward integration into lithium iron phosphate cell production to defend margin structures against pure-assembler competition from emerging Chinese manufacturers. Prioritize captive supply of battery management systems and thermal management hardware as the priority lever against software-hardware integration complexity threatening legacy chassis platforms. For New Entrants and Emerging Players: After-sales service networks for high-voltage battery systems represent the most penetrable white-space target, given vocational training institutions have not scaled certification programs to match fleet deployment rates. Target São Paulo and Rio de Janeiro municipal authorities through tropical climate validation partnerships as the inaugural go-to-market angle, leveraging first-mover positioning before framework agreement consolidation accelerates. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy diesel manufacturers divesting electric platform divisions under MIIT quota pressure and capital-intensity divergence. Long-term viability favors integrated cell-pack producers with upstream lithium iron phosphate supply control. Watch homologation timeline compression under UN ECE R100 as the inflection signal indicating regulatory acceleration or bottleneck relief.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell allocation from Zhengzhou production clusters under MIIT quota constraints. |
| Charging Infrastructure Partnership | Enables depot electrification for Delhi and Amsterdam operators facing grid reinforcement capital intensity. |
| Platform Standardization | Reduces homologation timeline compression for UN ECE R100 type approval across European long-haul configurations. |
| Software-Defined Vehicle Investment | Addresses battery management system and over-the-air update architecture gaps in legacy chassis manufacturers. |
| Geographic Manufacturing Footprint | Establishes tropical climate validation capacity for São Paulo and Rio de Janeiro inaugural electric bus tenders. |
Methodological Framework
The analysis maps city bus, coach, school bus, and shuttle configurations, each validated through fleet procurement managers, battery system engineers, and regulatory compliance officers. Primary interviews with state transport undertaking directors, OEM platform engineers, and charging infrastructure developers combined with secondary validation against MIIT production filings, EU Green Deal transposition documents, and FAME Phase II subsidy disbursement records. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates across the projection horizon.
Consistency checks validated outputs against IHS Markit vehicle registration databases, Belt and Road export corridor manifests, and municipal tender aggregation patterns. The analytical framework segments by product type, fuel architecture, end-user category, and dimensional class throughout the forecast period. CAGRs derive from battery cost compression curves, electrification mandate compliance timelines, and replacement cycle acceleration in diesel residual fleets. Cell chemistry transition rates and charging infrastructure deployment schedules serve as primary forecast inputs.
Underlying assumptions cover lithium iron phosphate cost parity achievement, FAME subsidy continuity, and EU Green Deal 90% emissions target enforcement, with deviation risk concentrated in critical mineral export restrictions and high-voltage technician training scalability. Practitioners should keep alternative scenarios live as MIIT quota adjustments and ANVISA certification pathway modifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Global Luxury Shuttle Bus Market
Buses
Bus Bellows Market
Buses
Europe Trolley Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Fuel Cell Electric Bus Market
Buses
Electric Intercity Bus Market
Buses
Africa Electric Bus Market
Buses
United States School Bus Market
Buses
Intercity Bus Travel Market
Buses
Airport Shuttle Bus Market
Buses
School Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Flooring Market
Buses
Bus Chassis Market
Buses
Buses & Coaches Market
Buses
Luxury Coaches Market