
 Solar Bus Market | 2026-2036
Solar Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Bus Market Analysis
Public transit procurement channels is rewriting how solar bus manufacturers access fleet operators. New Flyer leverages its North American dealer network to anchor municipal contract flows. Solaris Bus & Coach sustains competitive positioning through in-house photovoltaic integration capabilities. Yutong dominates volume deployment across Asia-Pacific through direct state-enterprise partnerships.
A solar bus integrates photovoltaic cells mounted on roof surfaces with lithium-ion battery packs and regenerative braking systems to capture, store, and deploy solar energy for propulsion. Typical configurations achieve 15-30% of daily energy requirements from onboard generation, with supplementary grid charging sustaining extended route operations. Full-solar buses occupy premium positioning where route profiles maximize sun exposure, while hybrid buses extend market reach into temperate climates with intermittent irradiance. Municipalities represent the dominant end-user segment given fleet-scale procurement power and dedicated depot infrastructure.
The US EPA tailpipe emission standards and FERC interconnection rules for solar depot charging shape product certification pathways and grid integration requirements. India's CEA technical standards for electric bus charging infrastructure and BIS photovoltaic module certifications govern component eligibility for subsidized procurement. China's MIIT new energy vehicle catalog determines manufacturer access to purchase-tax exemptions. Stakeholders must monitor evolving battery recycling mandates and solar panel end-of-life regulations as fleet scales compound material recovery obligations.
Market Dynamics
Photovoltaic roof integration maturity is compressing the cost gap between solar-hybrid and conventional electric buses, forcing fleet operators to recalculate total cost of ownership around energy autonomy rather than upfront capital expenditure.
Growth Catalysts
- India's PLI scheme for advanced chemistry cell batteries:Domestic cell manufacturing scale is reducing battery pack costs for integrated solar-electric drivetrains. Subsidized gigafactory output reaches bus OEMs faster than import channels.
- Grid-tied solar charging depots:China's MIIT new energy vehicle catalog eligibility unlocks purchase-tax exemptions for buses paired with photovoltaic depot infrastructure. Fleet operators optimize around combined vehicle-station incentives.
- Municipal zero-emission mandates:Transit authorities in tier-one cities are embedding solar bus procurement into climate action plans. Dedicated depot land and route planning authority accelerates deployment velocity.
Market Restraints
- Polysilicon supply concentration:Photovoltaic cell production clusters in specific manufacturing geographies, exposing module costs to raw material volatility and trade policy friction.
- Lithium-ion cell chemistry limitations:Energy density constraints in current battery architectures limit onboard storage capacity, capping solar energy utilization rates during low-irradiance periods.
- FERC interconnection queue delays:US solar depot projects face grid connection backlogs that extend commissioning timelines and compress project returns for municipal fleet operators.
Strategic Opportunities
- Perovskite-silicon tandem cell convergence:Next-generation photovoltaic efficiency gains would extend daily solar yield capture, opening temperate climate markets currently marginal for pure solar configurations.
- Vehicle-to-grid integration protocols:Bidirectional charging standards enable solar buses to function as distributed storage assets, creating new revenue streams for fleet operators during peak demand periods.
- Secondary battery applications:Retired bus battery packs retain residual capacity for stationary solar storage, closing material loops and reducing lifecycle environmental compliance costs.
Industry Challenges
- Photovoltaic module certification timelines:BIS and IEC testing protocols for vehicle-integrated solar surfaces extend product development cycles, delaying market entry for new roof system designs.
- Cross-functional workforce gaps:Fleet maintenance organizations lack technicians trained simultaneously in high-voltage electrical systems, battery thermal management, and solar array diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Bus Market |
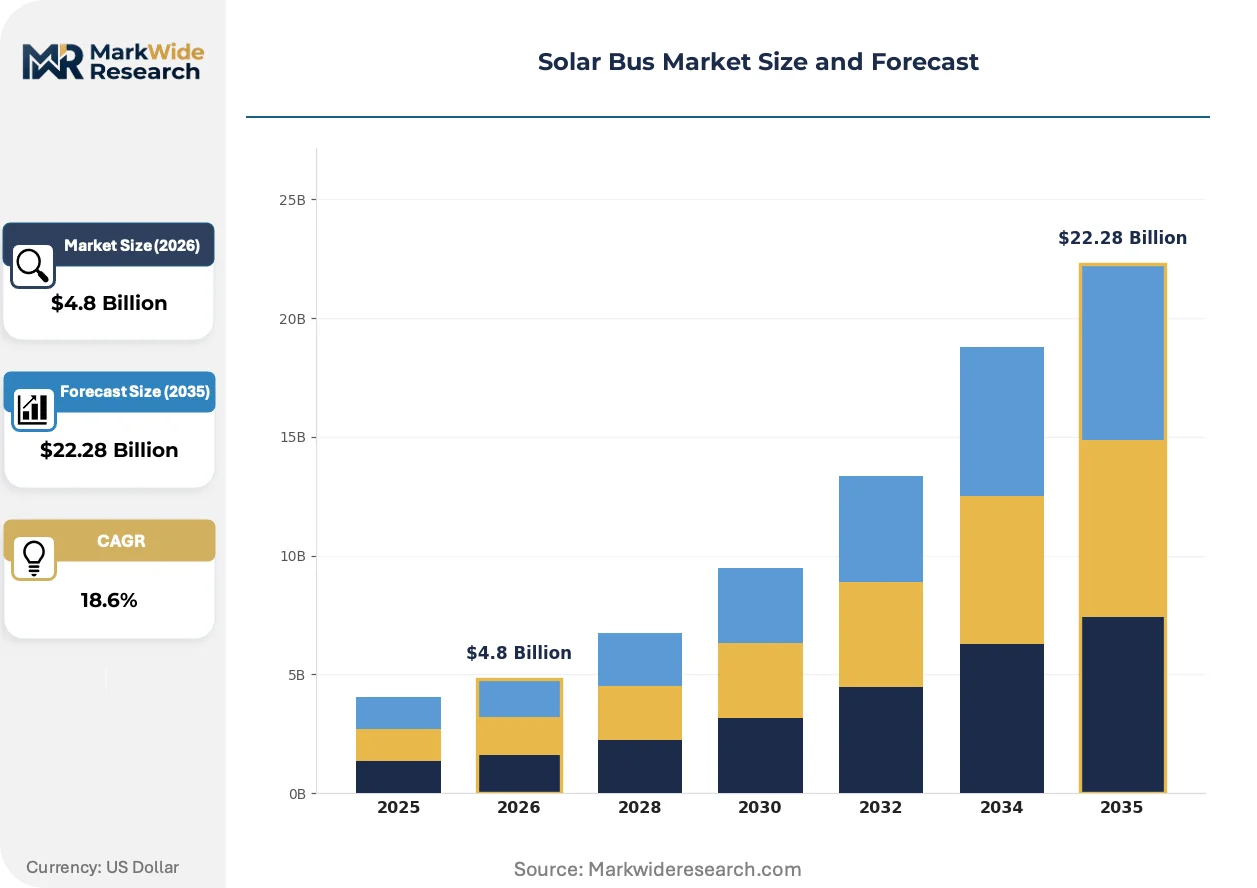
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Solar Buses, Hybrid Buses, Retrofit Buses, Electric Buses End User: Municipalities, Private Operators, Educational Institutions, Corporate Fleets Technology: Photovoltaic Cells, Lithium-Ion Batteries, Energy Storage Systems, Charging Stations Application: Public Transit, Campus Transportation, Airport Shuttles, Tour Services |
| Companies Covered | New Flyer, VDL Bus & Coach, Yutong, AMZ-Kutno, Ursus Bus, Solaris Bus & Coach, Ebusco, Kiira Motors Corporation, Foton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Bus Market Emerging Trajectories
Active roof surface engineering is redefining how solar buses capture and convert energy, with material science advances and digital integration creating new performance benchmarks for transit electrification.
Perovskite-enhanced photovoltaic laminates are achieving higher conversion efficiency in variable light conditions than conventional silicon alternatives. European bus manufacturers are piloting these materials on demonstration fleets ahead of volume certification. The technology is rendering obsolete the fixed-tilt rigid panel designs that dominated early solar bus prototypes.
The EU Green Deal's Fit for 55 package is tightening CO2 intensity thresholds for public procurement vehicles. Member state transit authorities must now document embedded carbon and operational emissions across fleet lifecycles. Solar-electric configurations gain preference in tender scoring systems that weight renewable energy integration.
Leasing structures are displacing direct capital purchase for municipal solar bus deployments. Fleet operators in China's Yangtze River Delta are contracting with energy service companies that bundle vehicle, charging infrastructure, and photovoltaic generation into unified per-kilometer agreements. This model transfers technology risk and aligns vendor incentives around uptime performance rather than equipment delivery.
Solar Bus Market Segmentation
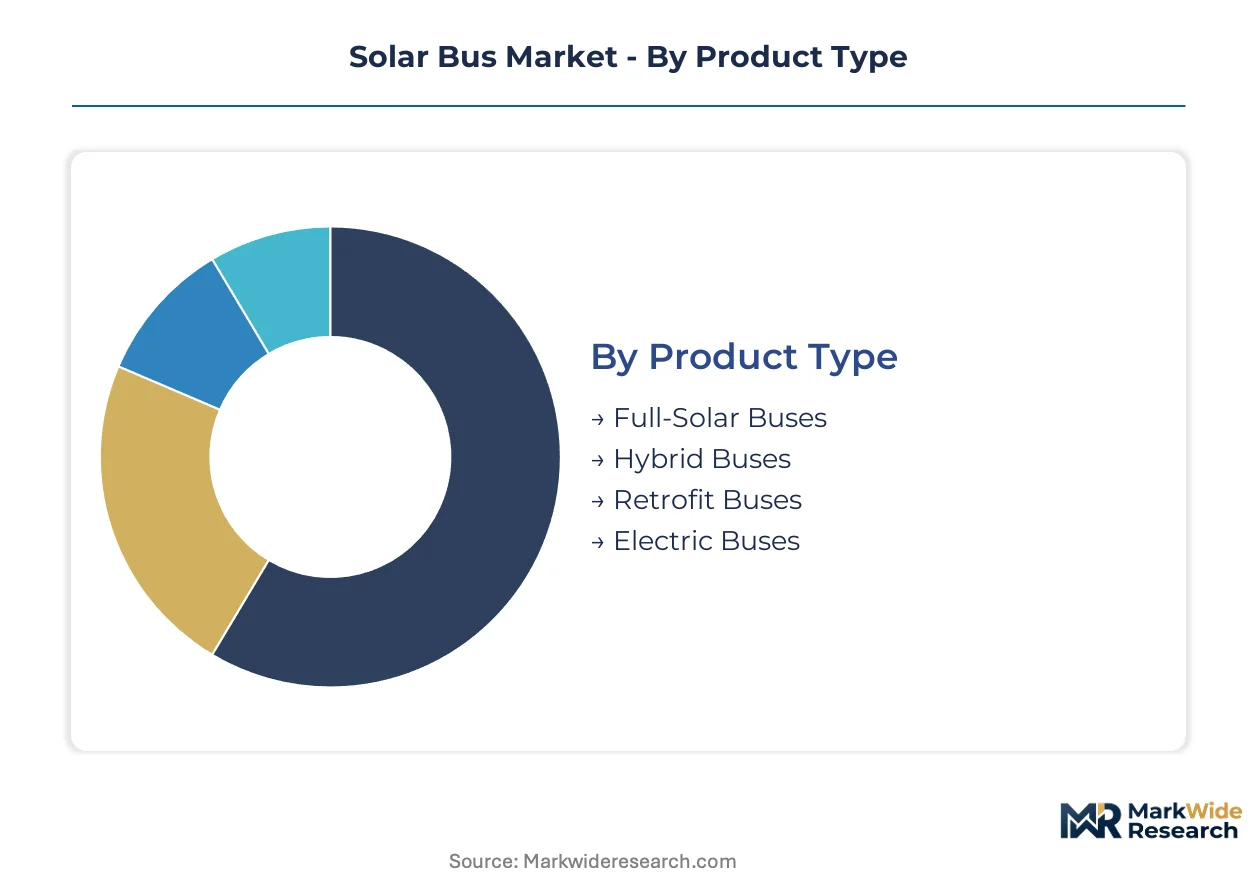
Solar bus procurement cycles vary dramatically across product configurations and operator types. Fleet operators align capital planning horizons with technology refresh rates, depot infrastructure lifecycles, and subsidy program windows. Understanding these replacement dynamics shapes vendor go-to-market timing and contract structuring.
Product Type:
Full-solar buses turn over slowest due to premium positioning and specialized route requirements, while retrofit buses cycle fastest as operators test solar integration on existing assets before committing to full fleet replacement.
- Full-Solar Buses:These vehicles integrate high-efficiency photovoltaic laminates across the entire roof surface with oversized battery packs sized for complete solar autonomy. Demand concentrates in China's tier-one cities where MIIT catalog eligibility unlocks purchase-tax exemptions and dedicated solar charging depots anchor route planning. The extended payback period limits deployment to municipalities with 10-year fleet planning horizons.
- Hybrid Buses:Configurations blend onboard solar generation with conventional grid charging, achieving 15-30% energy autonomy while maintaining operational flexibility. India's state transport undertakings favor this architecture under PLI-subsidized battery procurement, balancing energy cost reduction against infrastructure minimization. The compromise positioning expands addressable market into temperate climates with intermittent irradiance.
- Retrofit Buses:Aftermarket photovoltaic roof systems installed on existing electric bus platforms. European pilot programs test validation protocols before volume deployment.
- Electric Buses:Baseline battery-electric configurations without solar integration, serving as reference point for total cost of ownership calculations and technology migration pathways.
Hybrid buses anchor the volume base while retrofit buses gain share at the steepest rate.
End User:
Municipal transit authorities command the largest fleet scales and longest contract tenors, while corporate fleets operate on compressed decision cycles driven by sustainability reporting deadlines.
- Municipalities:City transport departments with dedicated depot land, route planning authority, and climate mandate alignment. China's tier-one cities embed solar bus procurement into carbon neutrality action plans with 15-year fleet transition timelines. The concentrated procurement power enables integrated vehicle-infrastructure bundling.
- Private Operators:Contracted transit service providers operating on municipal concessions or intercity routes. India's private fleet aggregators leverage PLI scheme benefits through bulk battery purchasing.
- Educational Institutions:University and school district fleets with predictable route profiles and sustainability commitment visibility. Campus microgrids enable solar charging integration.
- Corporate Fleets:Employee shuttle services and logistics operators with ESG reporting obligations. Shorter procurement cycles align with annual sustainability target setting.
Municipalities dominate installed capacity while corporate fleets are expanding most quickly.
Technology:
Photovoltaic cell technologies refresh on semiconductor innovation cycles, while charging station infrastructure depreciates over civil engineering timelines.
- Photovoltaic Cells:Silicon and emerging perovskite-silicon tandem architectures converting solar irradiance to electrical current. European manufacturers pilot perovskite-enhanced laminates ahead of IEC certification for vehicle integration.
- Lithium-Ion Batteries:Advanced chemistry cell packs storing onboard generation and grid-supplied power. India's PLI scheme accelerates domestic gigafactory output reaching bus OEMs faster than import channels.
- Energy Storage Systems:Thermal management and power electronics optimizing battery performance across charge-discharge cycles. Critical for solar yield variability absorption.
- Charging Stations:Grid-tied and solar-integrated depot infrastructure enabling fleet-scale electrification. China's MIIT catalog ties vehicle incentives to paired photovoltaic depot deployment.
Lithium-ion batteries anchor the volume base while photovoltaic cells climb the fastest on efficiency improvement trajectories.
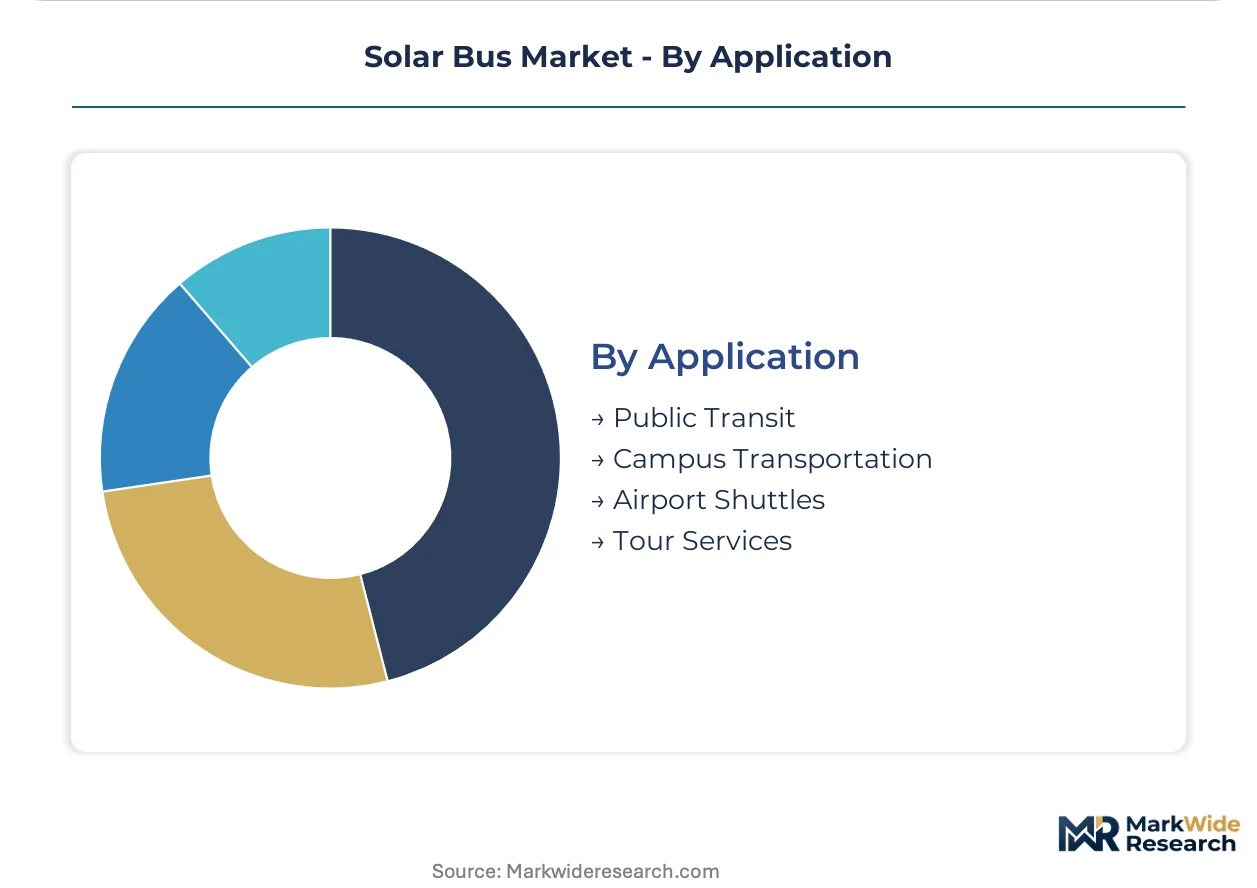
Application:
Public transit applications run on municipal budget cycles and political mandate periods, while tour services operate on seasonal revenue patterns with accelerated equipment turnover.
- Public Transit:Urban fixed-route services with high daily utilization and dedicated infrastructure. China's tier-one cities optimize route profiles for maximum solar exposure in fleet electrification planning.
- Campus Transportation:Controlled-environment shuttles with predictable loops and onsite charging. Universities leverage microgrid solar generation for energy cost stabilization.
- Airport Shuttles:High-frequency short-haul services with premium uptime requirements. Ground transportation operators balance passenger volume against charging window constraints.
- Tour Services:Seasonal and scenic route operators with flexible scheduling and high sun exposure. Compressed depreciation schedules align with tourism revenue cycles.
Public transit anchors the volume base while campus transportation gains share fastest on microgrid integration economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through integrated photovoltaic supply chains, while European manufacturers absorb premium module costs from concentrated Asian polysilicon sourcing. This asymmetry shapes regional deployment velocity and fleet procurement economics.
China
Municipal transit authorities in Beijing, Shanghai, and Shenzhen anchor procurement volume for tier-one fleet electrification. MIIT catalog eligibility unlocks purchase-tax exemptions for buses paired with photovoltaic depot infrastructure. The Yangtze River Delta clusters solar charging depot deployment with state-enterprise vehicle procurement.
India
State transport undertakings in Maharashtra, Karnataka, and Tamil Nadu expand zero-emission fleet mandates under national climate commitments. The PLI scheme for advanced chemistry cell batteries accelerates domestic gigafactory output reaching bus OEMs faster than import channels. Delhi-NCR pilots integrated solar-bus procurement with CEA technical standards for charging infrastructure.
Germany
Transit operators in Berlin, Hamburg, and Munich face EU Green Deal Fit for 55 CO2 intensity thresholds for public procurement vehicles. KBA certification requirements govern vehicle-integrated photovoltaic system approval. Bavaria anchors demonstration fleets testing perovskite-enhanced laminates ahead of IEC volume certification.
United States
Municipalities in California, Texas, and the Northeast Corridor navigate FERC interconnection queue delays for solar depot projects. EPA tailpipe emission standards shape product certification pathways for zero-emission bus procurement. The Pacific Northwest clusters early adopters optimizing route profiles for maximum solar exposure.
Japan
Transit authorities in Tokyo, Osaka, and Nagoya integrate solar bus pilots into METI-funded hydrogen and electrification demonstration programs. JIS standards for photovoltaic modules govern component eligibility for subsidized municipal procurement. Kanto region manufacturers pilot vehicle-to-grid integration protocols for bidirectional charging revenue streams.
Solar Bus Market Vendor Landscape
Integrated photovoltaic specialists and conventional bus OEMs split the market between technology-first and scale-first positioning. The vendor base concentrates around manufacturers with captive solar engineering capabilities or established municipal dealer networks. Two strategic archetypes dominate: roof-system integrators optimizing energy yield per surface area, and fleet-scale assemblers leveraging procurement channel access. Competitive moves center on backward integration into photovoltaic laminates and strategic partnerships with energy service companies for unified per-kilometer contracting.
Among European roof-system integrators, Solaris Bus & Coach and VDL Bus & Coach exemplify the photovoltaic-specialist archetype through in-house laminating capabilities. New Flyer anchors North American positioning through municipal dealer network density. Yutong occupies the scale-driven tier with direct state-enterprise partnerships across China's tier-one cities. These three manufacturers represent divergent pathways to fleet procurement access: technology integration, channel control, and government relationship depth.
| Leading Market Players |
|---|
| New Flyer |
| VDL Bus & Coach |
| Yutong |
| AMZ-Kutno |
| Ursus Bus |
| Solaris Bus & Coach |
| Ebusco |
| Kiira Motors Corporation |
| Foton |
| Others |
Supply Flow & Price Mechanics
Polysilicon supply concentration in Xinjiang and Inner Mongolia exposes module costs to tariff volatility and trade policy friction, compressing pricing tier spreads between premium European laminates and standard Asian imports while forcing manufacturers toward captive ingot production or diversified sourcing strategies.
Pricing Analysis
The customization-premium spread separates configured-to-order full-solar buses from standard hybrid configurations. Pricing stratifies across premium, standard, and economy tiers based on photovoltaic efficiency ratings and MIIT catalog certification status. Cost compression in the standard tier is intensifying because India's PLI-subsidized battery cells flood downstream markets. Municipal transit authorities exhibit highest price sensitivity, while corporate shuttle operators absorbing ESG premiums show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates procurement risk calculus for North American fleet operators. Polysilicon refining clusters in China, Malaysia, and Germany; lithium-ion cell production centers on China, South Korea, and Japan. The solar bus supply chain rests on high-purity silicon ingots, advanced chemistry cell packs, and vehicle-integrated laminate substrates. Single-source vulnerability in photovoltaic wafer supply threatens module availability. Distribution runs through state-enterprise procurement channels in Asia-Pacific and municipal dealer networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar bus incumbents face substitution pressure from hydrogen fuel cell transit platforms gaining traction in Japan and South Korea, requiring defensive positioning around total cost of ownership advantages and charging infrastructure lock-in.
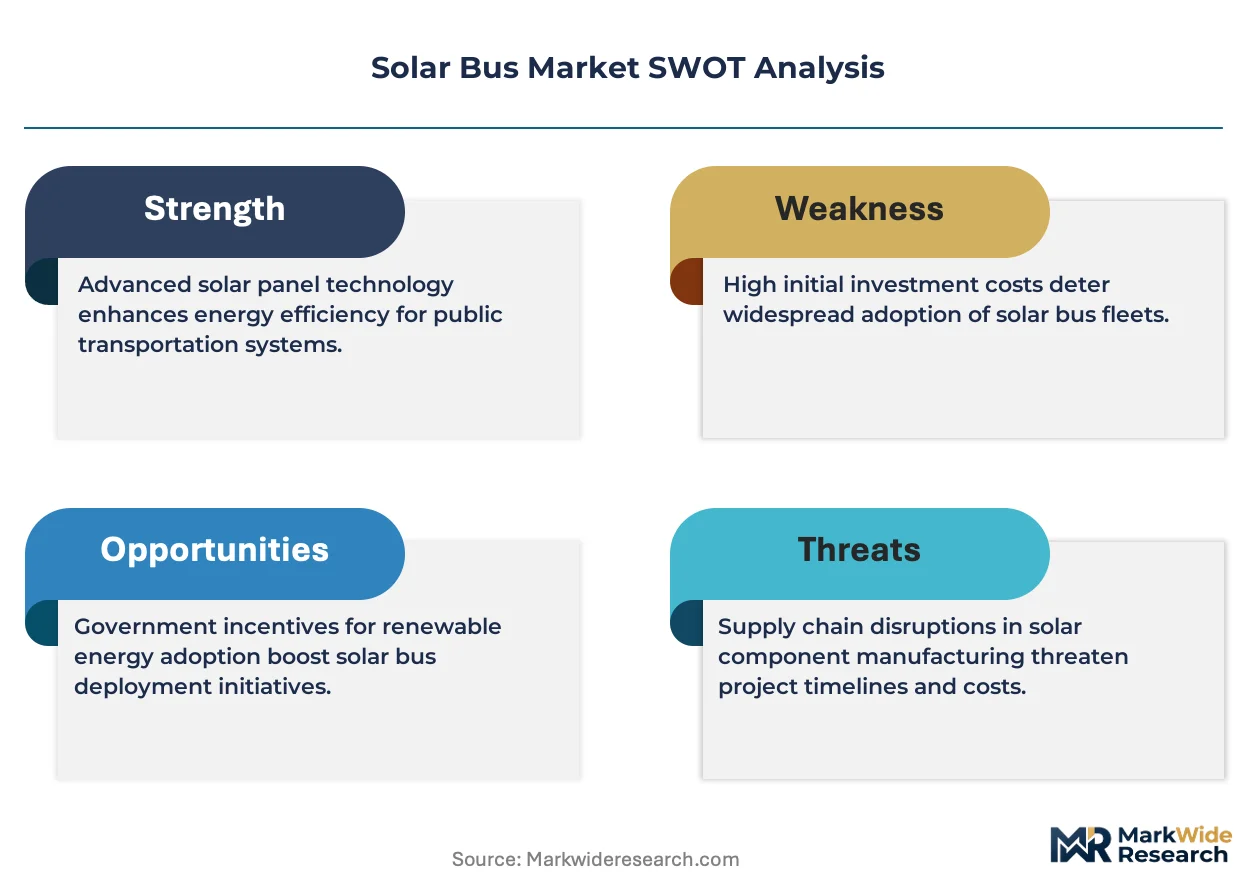
For Market Incumbents: Harden competitive moats through backward integration into perovskite-silicon tandem cell development and captive photovoltaic laminate production. Secure MIIT catalog eligibility in China to maintain access to purchase-tax exemptions. Counter hydrogen fuel cell substitution threats by emphasizing grid-tied depot economics and existing infrastructure utilization.
For New Entrants and Emerging Players: Retrofit bus aftermarket programs in European municipal fleets represent the most penetrable entry point, with pilot validation protocols creating certification pathways before volume deployment. India's state transport undertakings offer second-mover opportunity under PLI-subsidized battery procurement. Partner with energy service companies for unified per-kilometer contracting to transfer technology risk.
For Investors and Strategic Acquirers: The EU Green Deal Fit for 55 CO2 intensity thresholds reshape the acquisition landscape toward photovoltaic-integrated specialists with in-house laminating capabilities. Long-term viability favors manufacturers with state-enterprise channel depth and depot infrastructure bundling competence. Watch FERC interconnection queue clearance rates as signal for US market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Cell Development | European manufacturers piloting Bavaria demonstration fleets gain efficiency advantages ahead of IEC certification. |
| Backward Integration into Photovoltaic Laminates | Solaris and VDL Bus & Coach reduce module cost exposure through in-house laminating capabilities. |
| Unified Per-Kilometer Service Contracting | Yangtze River Delta energy service companies align vendor incentives with uptime performance rather than equipment delivery. |
| Vehicle-to-Grid Integration Protocol Deployment | Kanto region manufacturers unlock bidirectional charging revenue streams through METI-funded demonstration programs. |
| Secondary Battery Application Infrastructure | Retired bus packs entering stationary solar storage reduce lifecycle compliance costs and close material loops. |
Methodological Framework
A spread of perspectives from municipal transit procurement officers, photovoltaic system engineers, battery supply chain managers, and fleet operations directors converged on the working assumptions underpinning this analysis. Primary interviews with OEM platform engineers and energy service company executives combined with secondary validation from MIIT new energy vehicle catalog filings, CEA technical standards documentation, and FERC interconnection queue data. Bottom-up route-level deployment modeling triangulated against top-down national fleet electrification targets.
Demand-supply-balance framing anchored the forecast framework across the analysis window. Segmentation dimensions included product configuration type, end-user procurement authority, photovoltaic cell technology tier, and regional regulatory incentive structure. CAGRs derived from trajectory fitting to announced fleet procurement pipelines and subsidy program windows. Key inputs encompassed polysilicon spot price indices, lithium-ion cell capacity expansion schedules, and municipal budget cycle timing.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, polysilicon trade policy, or battery raw material costs would shift the trajectory. Forecasts reflect documented assumptions about subsidy continuity and certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intelligent Bus Shelter Market
Buses
Intercity Bus Travel Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Seat Market
Buses
School Bus Market
Buses
Bus Bellows Market
Buses
Bus Chassis Market
Buses
Bus Charter Services Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Rental Market
Buses
Airport Bus Market
Buses
Canada Transit Buses Market
Buses
Europe Trolley Bus Market
Buses
Hydrogen Buses Market
Buses
Buses & Coaches Market
Buses
Canada School Bus Market