
 Hydrogen CNG Bus Market | 2026-2036
Hydrogen CNG Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen CNG Bus Market Foresight
The hydrogen CNG bus market is restructuring around a sharp split between premium fuel-cell-dominant platforms and commodity compressed natural gas retrofits. Hyundai Motor Company leverages its integrated fuel cell stack production to dominate premium articulated configurations. Wrightbus sustains competitive positioning through specialized double-decker designs for high-density UK routes. Solaris Bus & Coach anchors Central European demand with standardized bus formats optimized for municipal procurement cycles.
Hydrogen CNG buses combine compressed natural gas or hydrogen-enriched CNG with dedicated fuel storage, injection, and combustion systems to reduce tailpipe emissions in heavy-duty transit applications. These vehicles typically operate at 200-250 bar storage pressure and employ sequential gas injection mapped to diesel-derived engine blocks, serving municipal fleets seeking incremental decarbonization without full electrification infrastructure. The fuel system dimension shows compressed hydrogen gaining fastest within hybrid configurations, while renewable natural gas occupies mature margin pools in Nordic markets. Technology segmentation reveals fuel cell systems commanding premium positioning against internal combustion adaptations, with battery-hybrid architectures filling intermediate duty cycles.
The EU Green Deal, F-Gas Regulation, and ECHA framework collectively mandate fleet emission ceilings that reshape municipal procurement specifications across member states. Germany's KBA enforces type-approval standards for hydrogen storage integrity that filter market access for non-compliant suppliers. Stakeholders must monitor how storage pressure standards and carbon intensity certification protocols evolve to determine which fuel system investments retain compliance value.
Market Dynamics
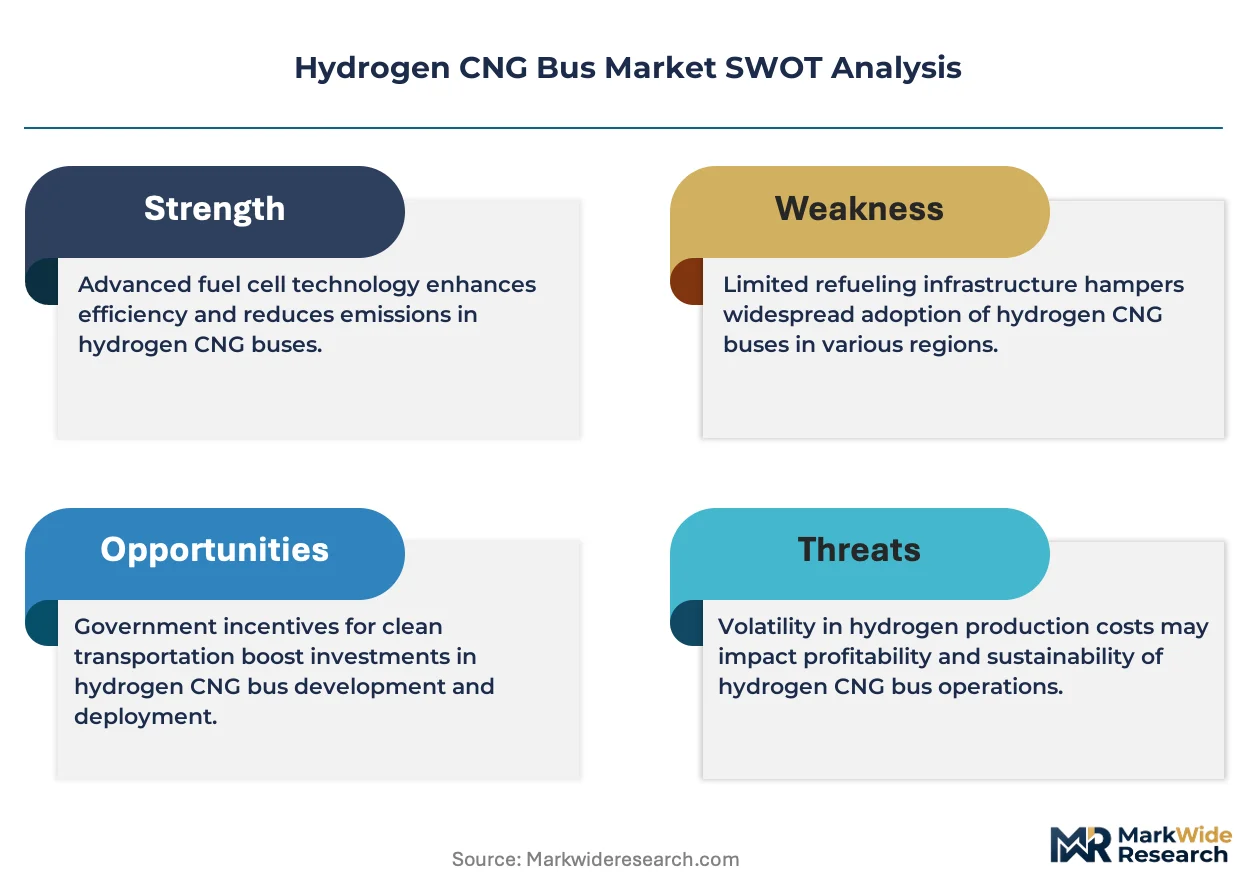
The hydrogen CNG bus market is bifurcating around storage pressure standards and carbon intensity certification, with Germany's KBA type-approval requirements filtering supplier access and reshaping investment priorities across European municipal procurement.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated gas emissions are accelerating fleet transitions toward dual-fuel hydrogen CNG architectures in heavy-duty transit applications.
- Municipal zero-emission procurement:Berlin and Hamburg pilot programs are establishing operational templates that neighboring transit authorities are replicating.
- Renewable natural gas infrastructure:Nordic biogas upgrading facilities are expanding feedstock availability for hydrogen-enriched CNG blending operations.
Market Restraints
- Storage pressure standard fragmentation:Divergent KBA certification requirements versus emerging ISO protocols create compliance duplication costs for system suppliers.
- Electrolyzer capacity concentration:Green hydrogen supply remains bottlenecked by limited European electrolyzer manufacturing scale.
- Battery-electric substitution:Falling lithium-ion pack costs and expanding depot charging infrastructure threaten hydrogen CNG's intermediate decarbonization niche.
Strategic Opportunities
- UK double-decker retrofit demand:High-density London route operators seek hydrogen CNG solutions for routes unsuited to battery-electric range constraints.
- CE marking harmonization:Unified EU safety standards for high-pressure hydrogen storage would unlock cross-border fleet procurement pooling.
- Hybrid fuel cell integration:Convergence of solid oxide fuel cells with CNG reformation is opening range-extended configurations for intercity coach segments.
Industry Challenges
- High-pressure vessel certification timelines:KBA and TÜV approval cycles for composite hydrogen storage tanks extend product launch schedules by months.
- Sequential gas injection calibration:Mapping CNG-hydrogen blends to legacy diesel engine blocks requires scarce combustion engineering expertise concentrated at German powertrain consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen CNG Bus Market |
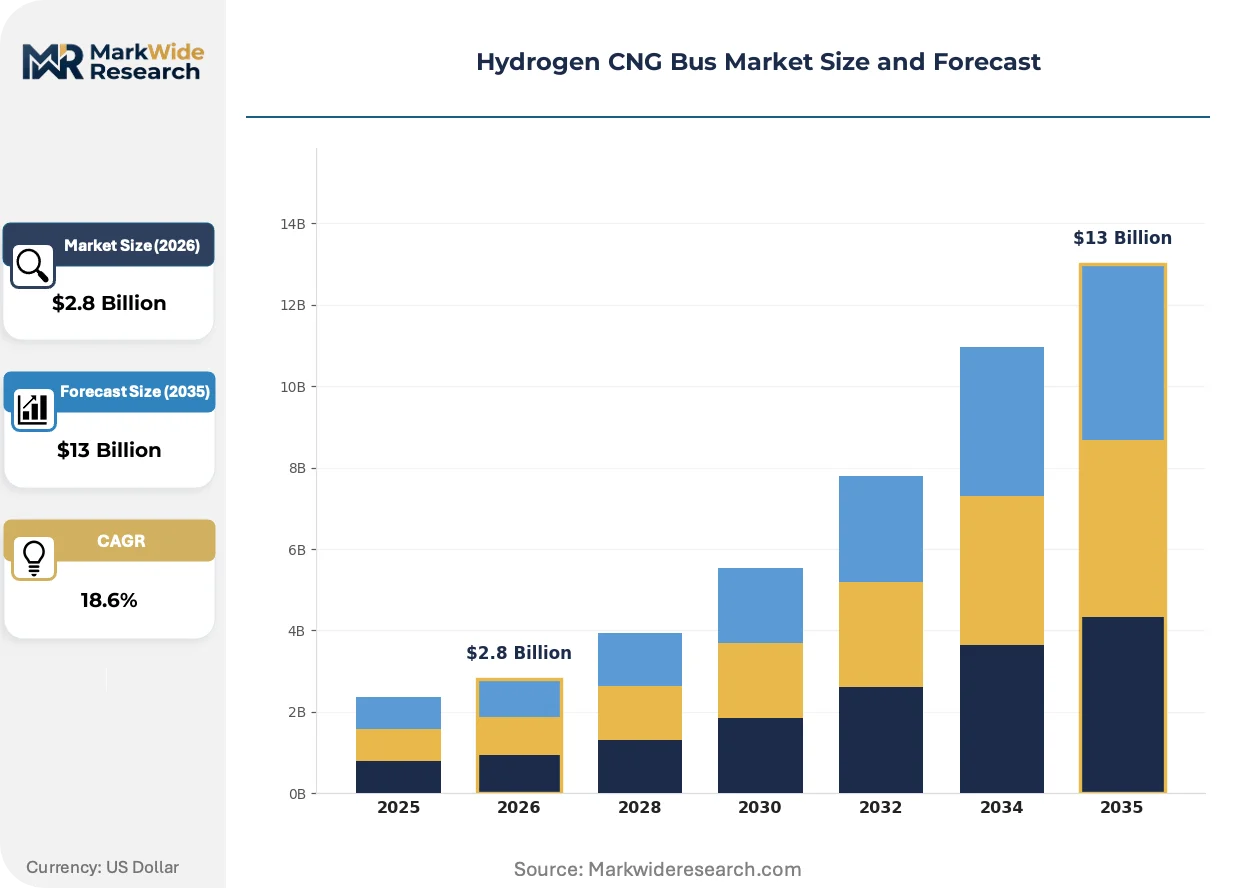
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Double-Decker, Articulated, Standard, Mini Fuel System: Hybrid, Compressed Hydrogen, Liquefied Hydrogen, Renewable Natural Gas End User: Public Transport, Private Operators, Government Fleets, Tour Operators Technology: Fuel Cell, Batteries, Internal Combustion, Hybrid Systems |
| Companies Covered | Hyundai Motor Company, Daimler Buses GmbH, Wrightbus, Solaris Bus & Coach, New Flyer, Yutong Bus Co., Ltd., Foton International, Toyota Motor Corporation, Van Hool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen CNG Bus Market Shifts & Advancements
Technology convergence and regulatory harmonization are compressing development cycles while procurement specifications harden around measurable carbon intensity metrics rather than fuel-type labels.
Solid oxide fuel cell systems paired with onboard CNG reformation are rewriting the economics of range-extended transit. Regional coach operators in Bavaria and Baden-Württemberg are piloting these configurations for 400-kilometer daily duty cycles. The technology is compressing the cost gap between battery-electric and hydrogen fuel cell platforms by eliminating hydrogen distribution infrastructure dependency.
REACH and the EU Green Deal are tightening embodied carbon disclosure requirements for municipal fleet procurement. Transit authorities in the Netherlands and Denmark now mandate well-to-wheel carbon intensity certification alongside tailpipe emissions data. German operators are responding by specifying renewable natural gas provenance in tender documentation.
Lifecycle service contracting is displacing capital purchase models for hydrogen CNG fleet deployment. Dutch transit authorities are unbundling vehicle acquisition from fuel supply and maintenance obligations, awarding ten-year performance contracts to integrated service providers. This shift concentrates risk with OEMs and fuel suppliers while transferring operational complexity away from municipal procurement departments.
Hydrogen CNG Bus Market Segmentation
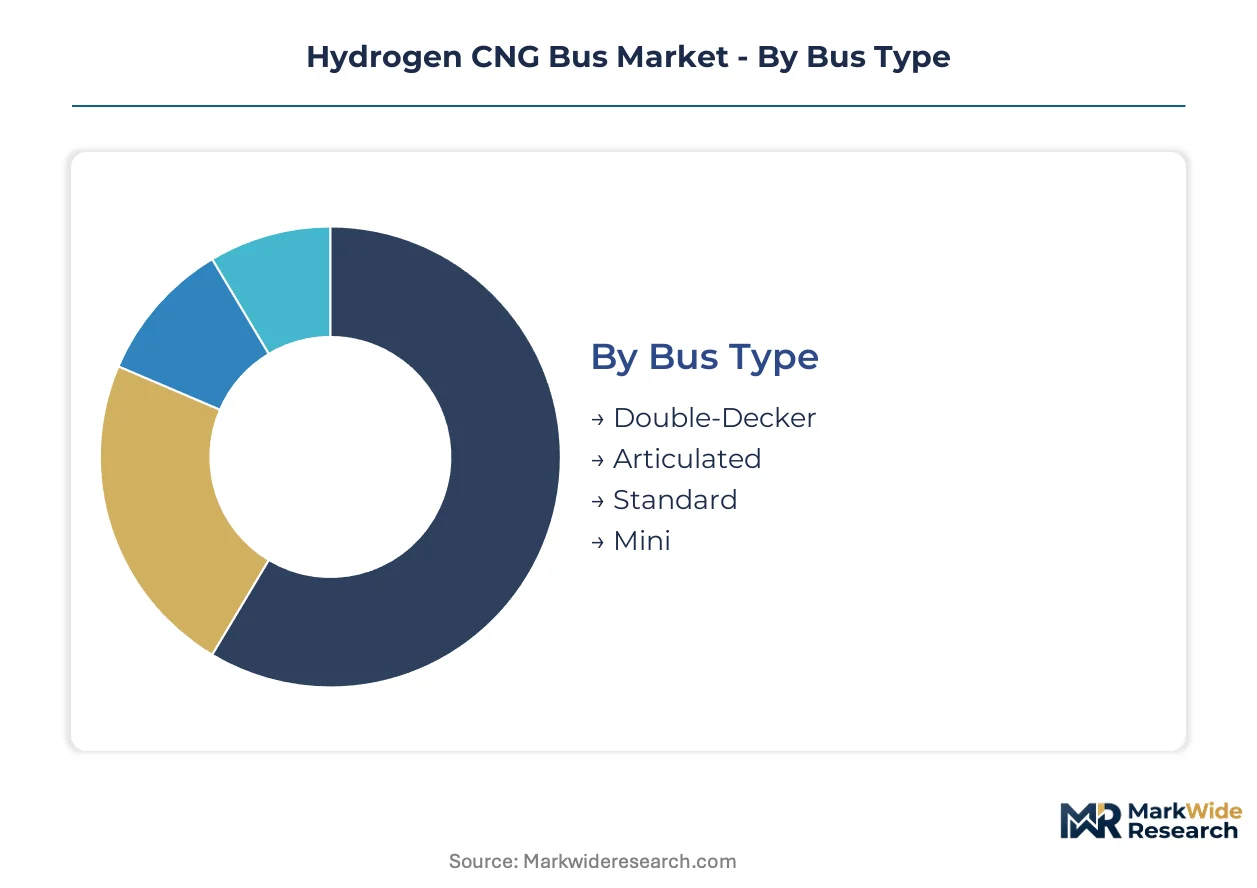
Segmentation in the hydrogen CNG bus market exposes how capital allocation and regulatory compliance diverge across vehicle configurations and powertrain architectures. Fleet operators must match fuel system investments to route density, duty cycle, and existing depot infrastructure.
Bus Type:
Capital intensity peaks with articulated platforms requiring extended fuel storage arrays and reinforced chassis modifications for high-pressure hydrogen containment.
- Double-Decker:Specialized roof-mounted hydrogen storage configurations preserve passenger capacity in high-density urban corridors. London Transport for London specifications dominate procurement demand, with Wrightbus configurations setting the technical benchmark for vertical space optimization.
- Articulated:Extended wheelbases accommodate larger composite hydrogen tanks at 350-bar pressure ratings. Berlin BVG and Hamburg HVV pilot fleets anchor European demand for 18-meter configurations serving high-frequency radial routes.
- Standard:12-meter single-deck formats optimize for municipal procurement standardization across mid-sized German cities.
- Mini:Compact 8-meter designs target feeder services and low-density suburban networks in Nordic municipalities.
Most installed capacity flows through Standard configurations. Expansion is steepest in Articulated segments serving high-ridership corridors.
Fuel System:
Application context determines which fuel system architectures justify infrastructure investment, with route length and refueling frequency dictating technology selection.
- Hybrid:Dual-fuel CNG-hydrogen blending enables incremental decarbonization using existing compressed natural gas infrastructure. German municipal operators in Bavaria and North Rhine-Westphalia favor this architecture for 200-kilometer daily duty cycles without dedicated hydrogen refueling stations.
- Compressed Hydrogen:700-bar gaseous storage delivers maximum energy density for zero-emission operations. Netherlands RET Rotterdam and Danish Movia specifications increasingly mandate this system for new fleet tenders under national carbon intensity protocols.
- Liquefied Hydrogen:Cryogenic storage at -253°C extends range for intercity coach applications where depot refueling is impractical.
- Renewable Natural Gas:Biomethane upgrading from agricultural and municipal waste streams occupies mature margin pools in Swedish and Finnish markets.
Hybrid systems retain the largest operational footprint. Compressed hydrogen is climbing the fastest as dedicated refueling networks expand.
End User:
Customer type segmentation reveals divergent procurement timelines, with public authorities leading fleet transitions through consolidated tender processes.
- Public Transport:Municipal transit authorities consolidate volume through multi-year framework agreements. Berlin, Hamburg, and Amsterdam specifications filter supplier access through KBA and CE marking requirements.
- Government Fleets:Federal and state vehicle pools prioritize domestic manufacturing content under German procurement law.
- Private Operators:Commercial bus companies in UK regional markets seek lease-based deployment models to transfer technology risk.
- Tour Operators:Long-distance coach segments in Alpine regions test liquefied hydrogen for extended range requirements.
Public Transport commands the dominant share of installed base. Government Fleets are expanding most quickly through national decarbonization mandates.
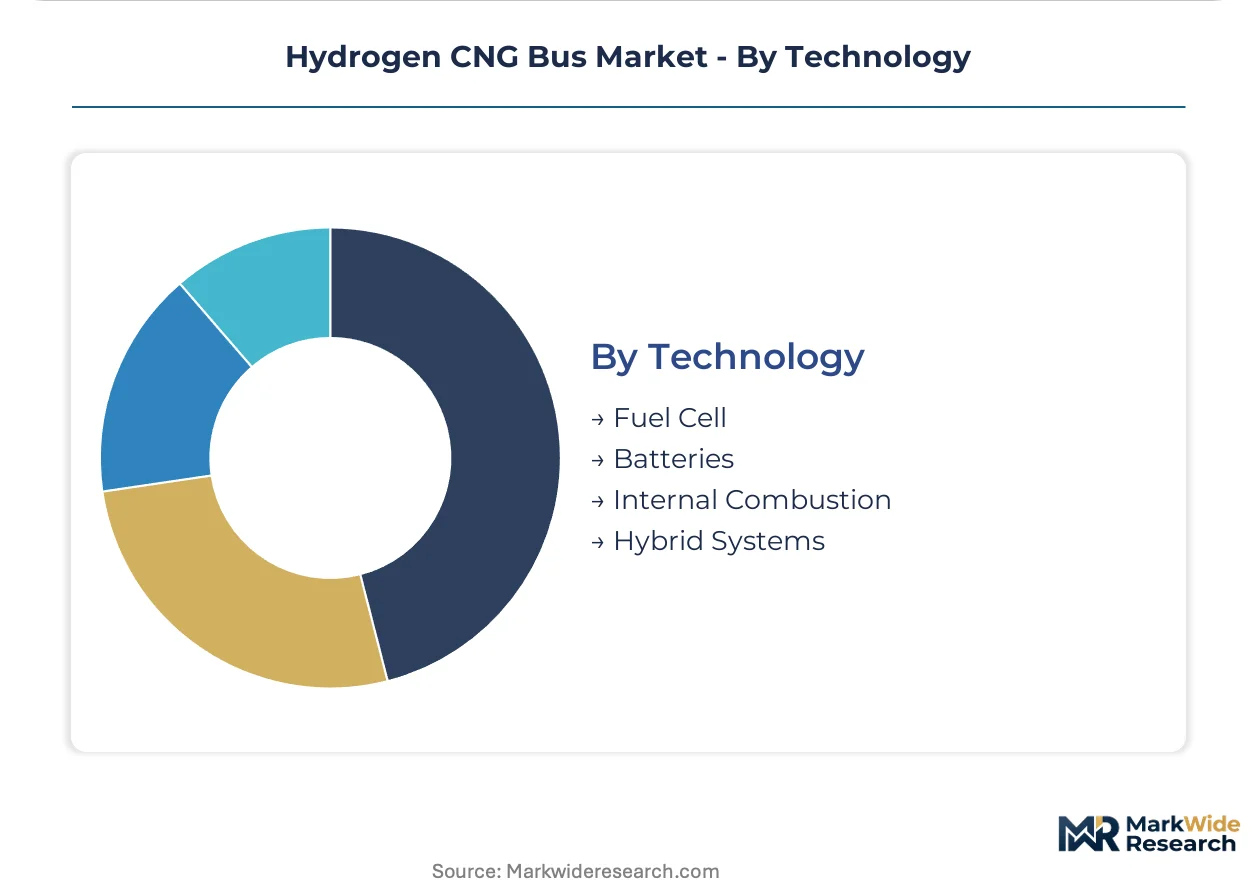
Technology:
Powertrain technology segmentation tracks the shift from combustion adaptations toward fuel cell dominance as stack costs decline and hydrogen supply matures.
- Fuel Cell:Proton exchange membrane systems deliver zero tailpipe emissions with 350-400 kilometer range capability. Hyundai's integrated stack production and Ballard Power Systems supply agreements anchor the technology roadmap for premium transit configurations.
- Hybrid Systems:Battery-fuel cell combinations optimize energy recovery and range extension. Solaris Bus & Coach configurations dominate Central European municipal specifications balancing capital cost against operational flexibility.
- Internal Combustion:Modified diesel blocks with sequential gas injection serve retrofit markets and cost-sensitive procurement in Eastern European municipalities.
- Batteries:Pure battery-electric platforms compete directly for depot-charged routes under 250 kilometers, pressuring hydrogen CNG's intermediate positioning.
Fuel Cell technology carries the steepest expansion trajectory. Hybrid Systems retain the broadest installed base across mixed-duty fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fuel cell engineering talent clusters in Stuttgart, Ulsan, and Toyota City anchor hydrogen CNG bus development across three continents. Municipal procurement mandates in Germany, South Korea, Japan, and the Netherlands concentrate pilot fleet demand. Each geography applies distinct regulatory pressure on storage certification and carbon intensity disclosure.
Germany
Berlin BVG and Hamburg HVV operate the largest articulated hydrogen CNG pilot fleets in Europe. KBA type-approval standards for 350-bar composite storage tanks filter supplier access and extend product launch timelines. The Baden-Württemberg industrial corridor hosts powertrain consultancies specializing in sequential gas injection calibration for CNG-hydrogen blends.
South Korea
Integrated fuel cell stack production capabilities in Ulsan supply domestic transit authorities and export markets. The country's national hydrogen roadmap mandates 40,000 hydrogen buses by 2040, with Seoul Metropolitan Government specifying dual-fuel architectures for intermediate decarbonization. Busan-Ulsan manufacturers dominate premium articulated configurations through captive component production.
Japan
Toyota City anchors fuel cell system development for heavy-duty transit applications. METI hydrogen supply chain subsidies reduce green hydrogen procurement costs for municipal operators in Tokyo and Osaka. The Chubu region around Nagoya hosts specialized composite vessel fabricators serving 700-bar storage requirements.
Netherlands
RET Rotterdam specifications mandate compressed hydrogen systems with well-to-wheel carbon intensity certification. The Randstad corridor connects biogas upgrading facilities in Brabant with hydrogen blending operations serving regional coach networks. Dutch transit authorities pioneered ten-year performance contracting models that unbundle vehicle acquisition from fuel supply obligations.
United Kingdom
Transport for London specifications drive demand for specialized double-decker hydrogen CNG configurations. Wrightbus designs set technical benchmarks for roof-mounted hydrogen storage preserving passenger capacity on high-density routes. The Midlands manufacturing base supplies retrofit solutions for regional operators seeking lease-based deployment models.
Hydrogen CNG Bus Market Competitive Landscape
Top-tier vendors anchor integrated fuel cell production, while mid-tier specialists compete on regional customization and retrofit expertise. The market structures around three strategic archetypes: captive stack producers, modular system integrators, and combustion adaptation specialists. Competitive moves concentrate on strategic partnerships for hydrogen distribution access and portfolio diversification into service contracting.
Among Asian manufacturers, Hyundai Motor Company and Toyota Motor Corporation exemplify the captive production archetype through integrated fuel cell stack operations. European competition centers on specialized fabricators, with Wrightbus occupying a position in high-density urban configurations and Solaris Bus & Coach anchoring standardized municipal procurement formats. Daimler Buses GmbH sits within the modular integration tier, leveraging powertrain platform flexibility across multiple fuel system architectures.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Daimler Buses GmbH |
| Wrightbus |
| Solaris Bus & Coach |
| New Flyer |
| Yutong Bus Co., Ltd. |
| Foton International |
| Toyota Motor Corporation |
| Van Hool |
| Others |
Supply & Pricing Matrix
Fuel-cell-dominant premium platforms versus commodity CNG retrofits split the hydrogen CNG bus market into divergent pricing strata that reshape supply chain configurations around certification tiers and infrastructure dependencies. German KBA type-approval requirements for 350-bar composite storage anchor premium pricing, while unbundled service contracting in Dutch markets compresses capital expenditure into performance-based obligations.
Pricing Analysis
Bundled lifecycle service contracts versus unbundled capital purchase models define the dominant pricing structure across European municipal procurement. Price differentiation rests on KBA certification grade and renewable natural gas provenance documentation, with Dutch transit authorities commanding carbon intensity certification premiums. Cost compression in hybrid CNG-hydrogen configurations intensifies as battery-electric alternatives erode intermediate-duty positioning. Private UK operators exhibit highest price sensitivity through lease-based deployment preferences, while German public authorities absorb premium fuel cell costs under national decarbonization mandates.
Supply Chain Analysis
German domestic-content rules under procurement law reshape sourcing patterns toward Baden-Württemberg powertrain consultancies and local composite vessel fabricators. Supply concentration centers on Germany, South Korea, and Japan for fuel cell stack production, with Ulsan and Toyota City anchoring captive manufacturing. The chain draws from platinum group metals for catalysts, carbon fiber for pressure vessels, and rare earth elements for electric drive motors. Single-source vulnerability in European electrolyzer manufacturing creates procurement risk. Distribution runs through municipal tender consortiums and ten-year performance contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen CNG bus market functions as a stable compounder, with EU Green Deal fleet mandates delivering predictable procurement volume expansion across municipal transit authorities.
For Market Incumbents: Hedge fuel cell stack cost exposure through backward integration into captive component production or binding long-term supply agreements with Ballard Power Systems. Battery-electric substitution threatens intermediate-duty hybrid positioning, necessitating accelerated solid oxide fuel cell integration for range-extended coach segments. Reinforced chassis engineering capabilities for 350-bar articulated platforms defend margin position against modular system integrators. For New Entrants and Emerging Players: Municipal service providers present the most penetrable channel partner type for white-space entry, particularly in UK regional markets seeking unbundled lease structures. Target Nordic biogas upgrading corridor feedstock agreements for hydrogen-enriched CNG blending operations. Specialist combustion calibration expertise concentrated at German powertrain consultancies offers acquisition pathways for Eastern European retrofit demand. For Investors and Strategic Acquirers: Consolidation pressure builds where lifecycle service contracting concentrates risk with integrated providers capable of spanning vehicle, fuel, and maintenance obligations. Long-term viability favors vertically integrated platforms with captive fuel cell production and hydrogen distribution access. Watch KBA-CE marking harmonization progress as the inflection signal for cross-border fleet procurement pooling and scaled platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contracting Unbundling | Dutch RET Rotterdam ten-year performance contracts transfer operational complexity from municipal procurement departments. |
| Fuel Cell Stack Integration | Hyundai's captive Ulsan production anchors premium articulated configuration economics against modular competitors. |
| Domestic Content Compliance | German procurement law filters supplier access toward Baden-Württemberg engineering clusters and local manufacturing. |
| Biogas Feedstock Securement | Nordic upgrading facilities in Sweden and Finland expand renewable natural gas availability for hydrogen blending. |
| Double-Decker Roof Storage Optimization | Wrightbus vertical space engineering preserves London Transport for London passenger capacity specifications. |
Research Methodology
Coverage spans Germany, South Korea, Japan, the Netherlands, and the United Kingdom, with primary inputs from each market cluster combining municipal transit authority procurement officers, fuel cell system engineers, powertrain calibration specialists, and composite pressure vessel manufacturers. Secondary validation draws from KBA type-approval databases, EU Green Deal implementation tracking, F-Gas Regulation compliance filings, and municipal tender documentation. Bottom-up fleet deployment counts triangulate against top-down powertrain production estimates.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon. The analytical framework models bus type segmentation, fuel system architecture, powertrain technology tier, and end-user procurement channel. CAGRs derive from installed base replacement cycles, pilot program expansion trajectories, and infrastructure buildout correlations. Industry-specific inputs include electrolyzer capacity deployment schedules and renewable natural gas upgrading facility commissioning.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric cost curves and hydrogen distribution network buildout. Projections reflect assumptions around KBA-ISO storage pressure standard convergence, green hydrogen supply cost trajectories, and municipal budget continuity under EU cohesion funding. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Fuel Cell Electric Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Global Luxury Shuttle Bus Market
Buses
United States Electric Bus Market
Buses
School Bus Market
Buses
Buses & Coaches Market
Buses
North America Bus Market
Buses
Electric Intercity Bus Market
Buses
Canada Transit Buses Market
Buses
Europe Bus Market
Buses
Bus Bellows Market
Buses
Bus Chassis Market
Buses
Trolley Bus Market
Buses
Luxury Coaches Market
Buses
Bus Charter Services Market
Buses
Solar Bus Market