
 United States School Bus Market | 2026-2036
United States School Bus Market Size, Share, and Industry Trends Forecast 2026-2036
United States School Bus Market Analytics
Electric powertrain integration is narrowing the technology gap between traditional diesel platforms and zero-emission alternatives. Blue Bird Corporation leverages its dedicated electric vehicle manufacturing facility in Fort Valley, Georgia to anchor domestic production capacity. Thomas Built Buses, a subsidiary of Daimler Truck North America, sustains engineering depth through its integration with the broader Mercedes-Benz commercial vehicle ecosystem. IC Bus, operating under Navistar Inc., competes aggressively on total cost of ownership metrics across propane, diesel, and battery-electric configurations.
A school bus constitutes a purpose-built passenger transport vehicle designed for student conveyance, typically featuring reinforced construction with gross vehicle weight ratings between 10,000 and 36,000 pounds, forward-engine or rear-engine layouts, and compliance with Federal Motor Vehicle Safety Standard 222 for rollover protection. The conventional bus type retains the largest installed base but carries the heaviest exposure to diesel phase-out pressures, while electric buses command premium positioning supported by federal incentive stacking. GPS Tracking and Digital Monitoring within the technology segment represent the fastest-expanding margin pools as districts prioritize fleet visibility, student accountability, and operational liability reduction alongside electrification capital outlays.
The EPA administers the Clean School Bus Program, which directs competitive rebate funding toward zero-emission and low-emission bus replacements, directly conditioning procurement timelines and technology selection across recipient districts. NHTSA enforces FMVSS 222 and related crashworthiness standards that govern body structure, seat integrity, and emergency egress specifications, creating compliance barriers for new market entrants. State-level regulators including the California Air Resources Board layer additional zero-emission mandates through Advanced Clean Trucks rule alignment. Fleet managers and school transportation directors must weigh federal incentive windows against charging infrastructure lead times and utility rate restructuring to sequence capital deployment effectively.
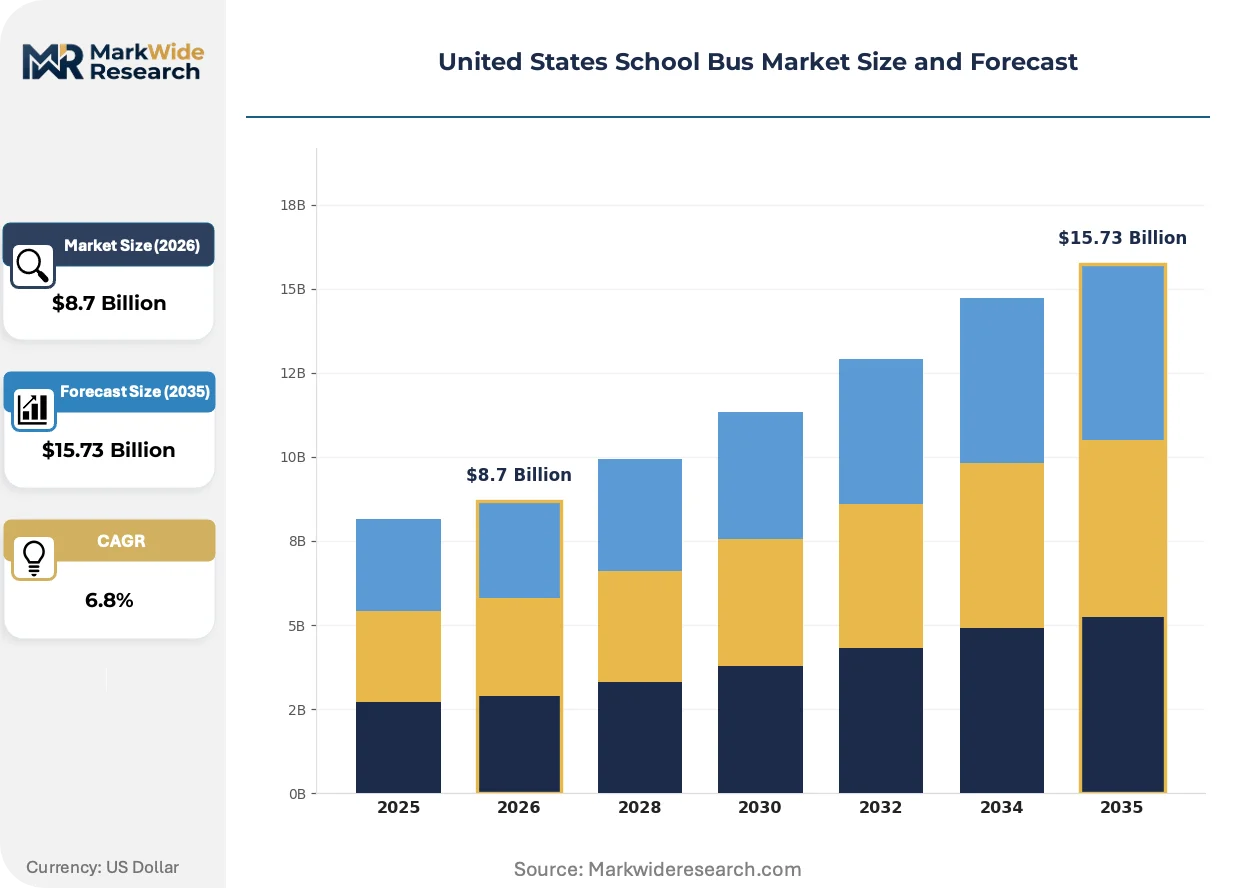
Market Dynamics
Electric powertrain conversion is compressing fleet replacement cycles across public school districts as the EPA Clean School Bus Program creates synchronized procurement windows that override traditional diesel longevity economics.
Growth Catalysts
- EPA Clean School Bus Program:Competitive rebate funding accelerates zero-emission procurement decisions among budget-constrained districts.
- Battery chemistry advances:Lithium iron phosphate configurations extend operational range while reducing thermal management complexity for route duty cycles.
- California Air Resources Board alignment:Advanced Clean Trucks rule adoption in multiple states creates regulatory momentum beyond federal incentive structures.
Market Restraints
- Charging infrastructure lead times:Utility interconnection queues and transformer upgrade requirements delay fleet deployment by 18-24 months in rural service territories.
- Steel and aluminum input volatility:Body structure materials expose manufacturers to commodity price swings that compress margin visibility on multi-year municipal contracts.
- FMVSS 222 certification barriers:Rollover protection and seat integrity testing requirements create extended validation timelines for new platform entrants.
Strategic Opportunities
- Texas fleet consolidation:Independent school district fragmentation creates white space for regional cooperative purchasing agreements that aggregate electric bus orders.
- V2G bidirectional integration:School bus parking patterns align with peak grid demand periods, enabling revenue-generating energy arbitrage for district budgets.
- Propane bridge technology:Lower capital outlays and existing fueling infrastructure support transitional fleet strategies in states without zero-emission mandates.
Industry Challenges
- Electrician and technician skill gaps:High-voltage system certification requirements outpace vocational training program throughput in rural counties.
- Legacy telematics integration:Proprietary fleet management platforms resist interoperability with new electric powertrain monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States School Bus Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Conventional, Electric, Low Floor, Mini Bus Fuel Type: Diesel, CNG, Propane, Hybrid End User: Public Schools, Private Schools, Charter Schools, Special Education Providers Technology: GPS Tracking, Safety Features, Connectivity Solutions, Digital Monitoring |
| Companies Covered | Blue Bird Corporation, Thomas Built Buses, IC Bus, Collins Bus Corporation, Lion Electric Company, Navistar Inc., GreenPower Motor Company, Forest River, REV Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States School Bus Market Evolving Landscape
Digital infrastructure is displacing mechanical reliability as the primary procurement evaluation criterion, with districts prioritizing real-time visibility over historical platform durability metrics.
Telematics platforms are virtualizing route optimization and predictive maintenance functions previously handled through driver experience and scheduled garage inspections. Large suburban districts in Georgia and Florida deploy these systems to reduce idle time and extend brake life. The technology is virtualizing traditional transportation director roles into data-driven operational centers that manage distributed charging loads alongside student tracking.
The EPA Clean School Bus Program rebate structure conditions award timing on zero-emission technology selection, compressing diesel procurement windows through 2026. Districts in New York and Washington state accelerate replacement schedules to capture funding before competitive pools deplete. This regulatory mechanism forces capital planning synchronization across otherwise autonomous school boards.
Fleet-as-a-service contracting is emerging as an alternative to municipal bond financing for electric bus acquisition. Third-party providers in Arizona and Colorado assume vehicle ownership and charging infrastructure responsibility while districts pay per-mile or per-student-transported rates. This arrangement transfers residual value risk and utility rate exposure away from school district balance sheets.
United States School Bus Market Segmentation
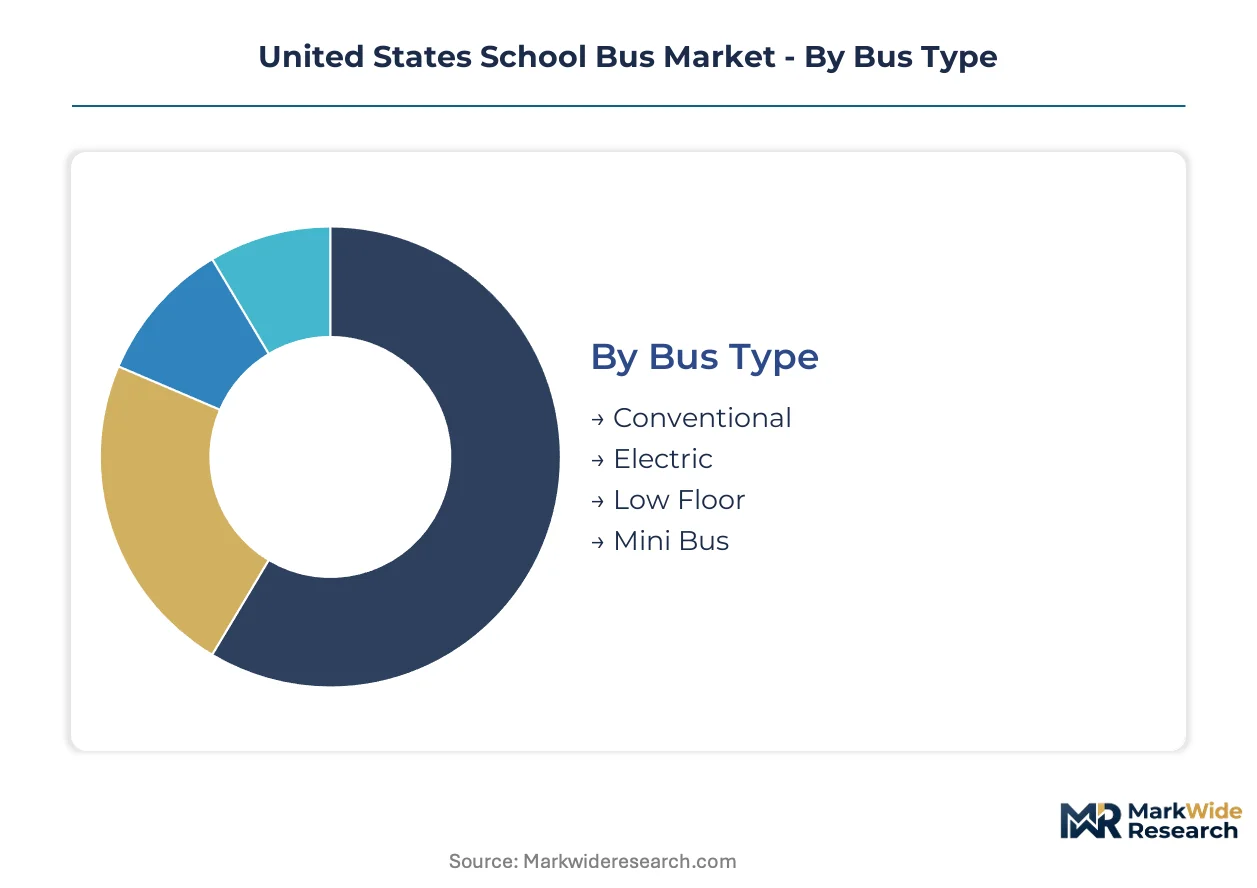
School bus procurement decisions cascade across multiple technical and operational dimensions. Fleet managers evaluate powertrain configurations against route profiles, while technology investments increasingly separate high-performance districts from baseline operators.
Bus Type:
After-sales service intensity varies dramatically across body configurations, with electric platforms demanding specialized high-voltage technician networks that conventional diesel fleets rarely require.
- Conventional:Retains the largest installed base with forward-engine hood design and body-on-frame construction. Texas and California districts continue diesel replacements here where charging infrastructure remains undeveloped, though EPA rebate eligibility pressures mount.
- Electric:Battery-electric configurations with lithium iron phosphate chemistry and regenerative braking systems. Georgia and New York districts cluster orders to capture Clean School Bus Program funding windows before competitive pools exhaust.
- Low Floor:Flat-floor accessibility design with wheelchair lift integration points. Special education routes in Florida and Illinois concentrate demand for ADA-compliant boarding.
- Mini Bus:Cutaway chassis with 10-30 passenger capacity for low-density rural routes. Montana and Wyoming independent districts favor this format where full-size bus utilization rates drop below threshold economics.
Conventional buses hold the largest share; momentum sits with Electric configurations.
Fuel Type:
Cost tier stratification separates capital-intensive electric conversions from operational-expense-optimized fossil alternatives, with propane occupying a transitional middle ground.
- Diesel:Compression-ignition engines with established parts distribution and technician training infrastructure. Rural districts in Mississippi and Alabama extend replacement cycles here where federal incentive access remains limited.
- CNG:Compressed natural gas spark-ignition systems requiring dedicated fueling stations. California Air Resources Board compliance deadlines drive Los Angeles and Sacramento fleet conversions.
- Propane:Autogas systems with 30% lower fuel costs versus diesel and existing infrastructure compatibility. Colorado and Arizona districts deploy this as a bridge technology pending electric grid upgrades.
- Hybrid:Parallel electric-assist diesel configurations capturing regenerative braking energy. Seattle and Portland metropolitan areas pilot these where full electrification charging loads exceed utility capacity.
Diesel retains dominant volume; propane is climbing the fastest as a transitional fuel.
End User:
Customer type determines procurement autonomy, with fragmented independent districts facing coordination challenges that consolidated county systems avoid.
- Public Schools:Municipal district fleets subject to board approval cycles and bond financing constraints. EPA Clean School Bus Program rebates synchronize timing across otherwise asynchronous budget calendars.
- Private Schools:Independent institutional operators with faster capital deployment authority. Northeast corridor academies in Massachusetts and Connecticut lead zero-emission adoption among non-public entities.
- Charter Schools:Network-managed transportation with centralized fleet purchasing. Arizona and Florida charter management organizations aggregate orders across multiple campuses.
- Special Education Providers:Contractors serving individualized education program transportation mandates. Wheelchair lift specifications and attendant seating configurations dominate technical requirements.
Public Schools command the largest share; Charter Schools are gaining share fastest through network consolidation.
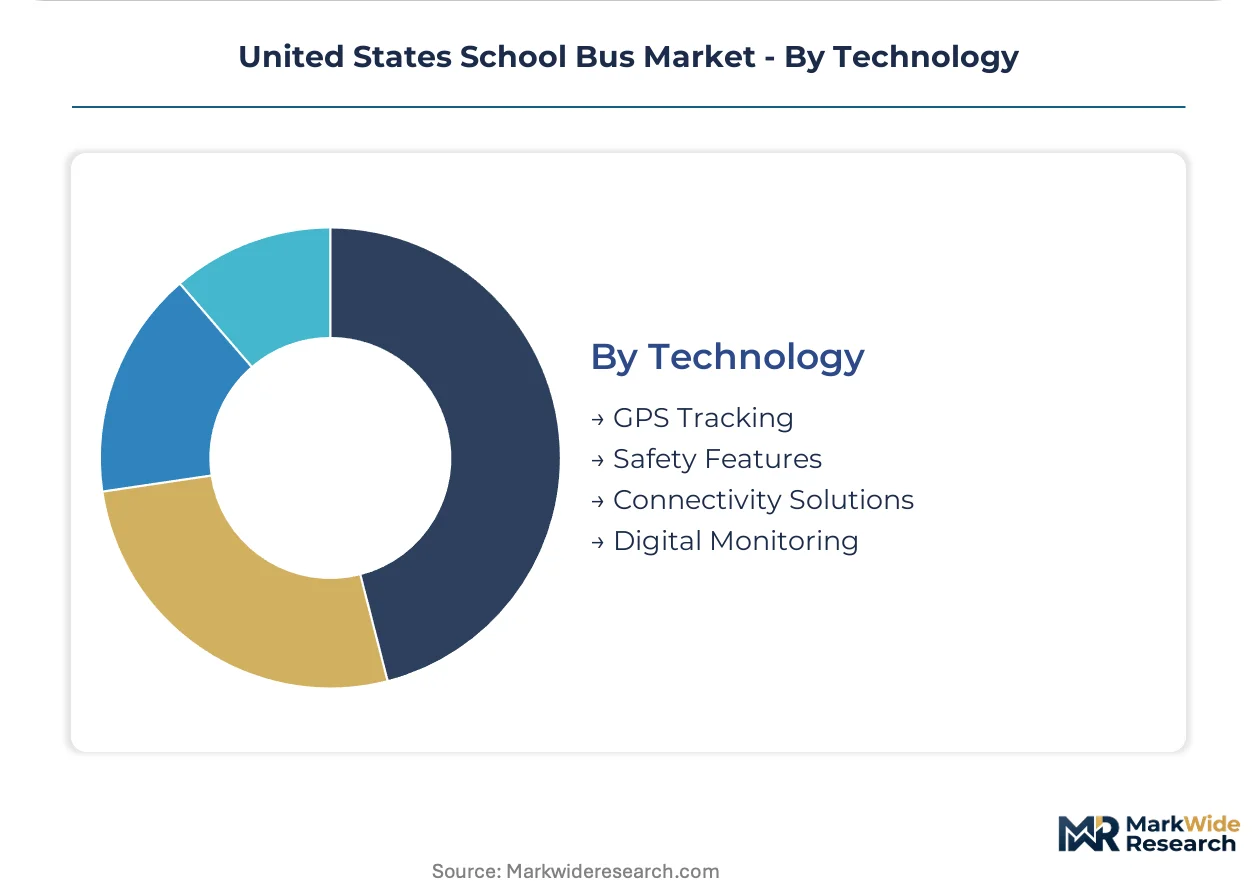
Technology:
Margin concentration tracks software-enabled recurring revenue models, with hardware-agnostic platforms displacing proprietary legacy systems.
- GPS Tracking:Real-time location telemetry with geofencing and route deviation alerts. Georgia and Florida suburban districts deploy these systems to reduce idle time and extend brake life.
- Safety Features:Collision avoidance, pedestrian detection, and automatic emergency braking hardware. NHTSA FMVSS 222 compliance testing validates new platform integrations.
- Connectivity Solutions:Wi-Fi hotspot and student device management for mobile learning extension. Digital equity mandates in California and Washington drive installation mandates.
- Digital Monitoring:Integrated video surveillance, student ridership tracking, and driver behavior analytics. Liability reduction priorities accelerate procurement faster than powertrain decisions in litigious jurisdictions.
GPS Tracking holds the largest share; Digital Monitoring shows the steepest expansion trajectory as liability concerns intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent school district fragmentation concentrates procurement authority in county-level transportation directors across the United States. California, Texas, and New York anchor the strongest zero-emission fleet replacement activity. EPA Clean School Bus Program rebate windows synchronize capital deployment timing across otherwise asynchronous municipal budget cycles.
California
California Air Resources Board Advanced Clean Trucks rule alignment drives Los Angeles and Sacramento metropolitan fleet conversions. The state's Hybrid and Zero-Emission Truck and Bus Voucher Incentive Project layers additional funding atop federal rebates. Southern California Edison and Pacific Gas & Electric coordinate utility infrastructure upgrades across San Diego and Bay Area school districts.
Texas
Independent school district fragmentation in Texas creates white space for regional cooperative purchasing agreements aggregating electric bus orders. Houston Independent School District and Dallas Independent School District pilot propane bridge technologies pending grid capacity expansion. The Texas Commission on Environmental Quality administers supplemental grants for alternative fuel conversions in non-attainment zones.
New York
New York State's zero-emission school bus mandate compels New York City Department of Education and suburban Westchester County districts to accelerate replacement schedules. The New York State Energy Research and Development Authority provides incentive stacking for battery-electric procurements. Buffalo and Rochester districts leverage Great Lakes industrial corridor manufacturing proximity for maintenance network access.
Georgia
Blue Bird Corporation's dedicated electric vehicle manufacturing facility in Fort Valley anchors southeastern production capacity. Atlanta Public Schools and suburban Cobb County districts deploy GPS tracking and digital monitoring systems to reduce idle time. The Georgia Environmental Finance Authority structures municipal bond instruments specifically for electric bus capital outlays.
Florida
Miami-Dade County Public Schools and Orange County Public Schools concentrate demand for low-floor accessibility configurations serving special education routes. Florida Power & Light coordinates demand-response programs aligning school bus charging with peak grid periods. The state's Department of Environmental Protection administers diesel emission reduction grants targeting pre-2010 engine retirements.
United States School Bus Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated chassis manufacturers and electric powertrain entrants. Three strategic archetypes dominate: legacy diesel platform incumbents with certified FMVSS 222 body structures, battery-electric pure-plays leveraging federal incentive timing, and diversified commercial vehicle conglomerates with captive distribution networks. Competitive moves concentrate on manufacturing capacity expansion in southeastern states and strategic partnerships with electric utility demand-response programs.
Within the legacy platform tier, Blue Bird Corporation and Thomas Built Buses exemplify established archetypes with dedicated electric vehicle production facilities and Mercedes-Benz commercial vehicle ecosystem integration respectively. IC Bus occupies a position representing Navistar Inc.'s aggressive total cost of ownership positioning across multiple fuel configurations. Among electric pure-plays, Lion Electric Company and GreenPower Motor Company represent the specialist entrant archetype capitalizing on synchronized EPA rebate windows.
| Leading Market Players |
|---|
| Blue Bird Corporation |
| Thomas Built Buses |
| IC Bus |
| Collins Bus Corporation |
| Lion Electric Company |
| Navistar Inc. |
| GreenPower Motor Company |
| Forest River |
| REV Group |
| Others |
Value Network & Pricing Analysis
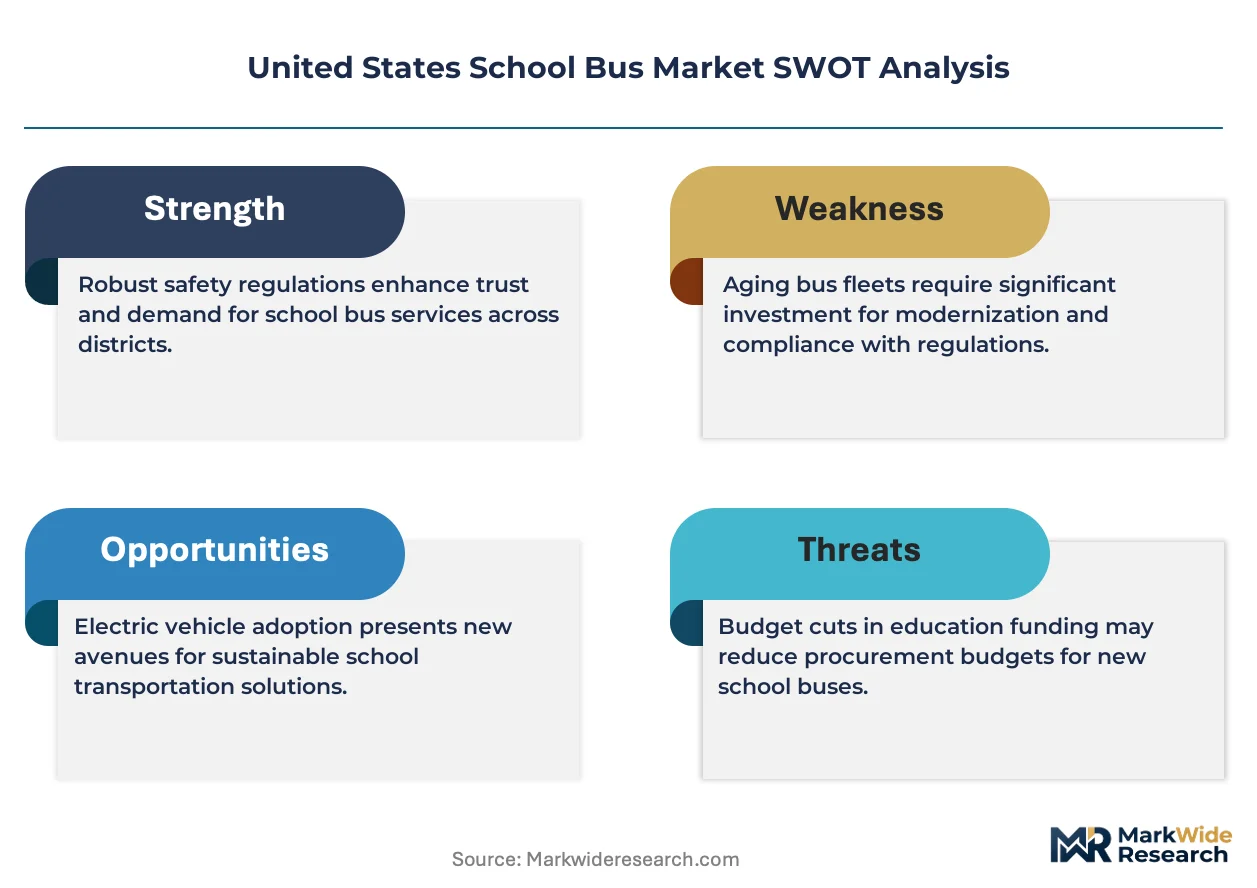
Steel and aluminum input volatility compresses margin visibility on multi-year municipal contracts and forces pricing tier spreads that separate bonded capital districts from cooperative purchasing aggregators. This commodity exposure simultaneously shapes supply chain geography toward southeastern manufacturing clusters and dictates contract indexation clauses that transfer raw material risk.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate municipal procurement, locking in base chassis costs while allowing fuel cell and battery pack pass-through adjustments. Price differentiation rests on EPA Clean School Bus Program certification tier and after-sales service bundling, with rebate-eligible electric configurations commanding premium positioning. Cost compression in conventional diesel segments is intensifying because rural districts extend replacement cycles and concentrate buying power through regional cooperatives. Charter school networks exhibit lowest price sensitivity due to centralized capital deployment, while fragmented independent districts in Texas and Montana face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on advanced battery cell manufacturing equipment limit technology transfer to domestic assembly operations and constrain capacity expansion timelines. Supply concentrates in China for lithium iron phosphate cells, South Korea for electrolyte formulations, and Mexico for chassis component stamping near final assembly points. Raw material dependencies span lithium carbonate, high-strength steel grades, and semiconductor power modules for motor control. Single-source vulnerability in battery management system chipsets creates procurement chokepoints. Distribution runs through OEM captive dealer networks and municipal cooperative purchasing agreements that aggregate fleet orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at an EPA funding cycle recovery phase that favors synchronized procurement timing over traditional replacement economics. Federal rebate window compression is accelerating capital deployment decisions across otherwise asynchronous district budget calendars.
For Market Incumbents: Insulate core diesel service revenue through captive parts distribution networks while accelerating high-voltage technician certification programs to capture electric platform aftermarket share. Threats from Lion Electric and GreenPower Motor concentrate in states with zero-emission mandates, requiring defensive capacity investments in Georgia and California manufacturing corridors. For New Entrants and Emerging Players: Pursue propane bridge technology positioning in Texas and Colorado districts awaiting grid infrastructure upgrades, where lower capital outlays and existing fueling infrastructure reduce competitive barriers. The most penetrable segment lies in mini-bus configurations for rural Montana and Wyoming independent districts. A fleet-as-a-service contracting model transfers residual value risk from district balance sheets and accelerates adoption velocity. For Investors and Strategic Acquirers: The market sits at a policy-driven replacement phase that favors vertically integrated chassis manufacturers with FMVSS 222 certification depth over pure-play electric entrants. Long-term viability across the projection horizon rests on charging infrastructure ecosystem control and utility partnership access. Acquisition targets should demonstrate NHTSA compliance validation capabilities and southeastern manufacturing proximity. The signal to watch is EPA rebate pool exhaustion rates as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Clean School Bus Program Certification | Unlocks federal rebate stacking that compresses electric bus payback periods for municipal districts. |
| High-Voltage Technician Network Expansion | Captures aftermarket service revenue pools as electric fleet penetration accelerates in Georgia and New York. |
| Utility Demand-Response Partnership | Enables V2G revenue arbitrage that improves total cost of ownership metrics against diesel alternatives. |
| Regional Cooperative Purchasing Aggregation | Consolidates fragmented Texas district demand into volume tiers that secure preferential OEM pricing. |
| Propane Bridge Technology Positioning | Addresses charging infrastructure lead times in rural service territories lacking transformer capacity. |
Research Methodology
The analysis maps electric powertrain configurations, conventional diesel platforms, and propane bridge technologies, each validated through fleet managers, school transportation directors, OEM platform engineers, and utility demand-response planners. Primary fieldwork combined structured interviews with secondary validation against EPA Clean School Bus Program award databases, NHTSA FMVSS 222 certification records, state environmental agency grant disclosures, and municipal bond prospectus filings. Bottom-up district-level procurement tracking triangulates against top-down manufacturer production disclosures.
Assumptions held fixed include EPA rebate funding continuity, lithium iron phosphate cell cost trajectories, and NHTSA rollover protection standards. Variables tested across the analysis window span utility interconnection queue lengths, steel futures volatility, and state-level zero-emission mandate adoption timing. Segmentation modeling incorporated bus type, fuel configuration, end-user governance structure, and technology adoption tier. CAGRs derived from unit shipment projections indexed to federal incentive windows and replacement cycle compression patterns.
Sensitivities concentrate around EPA funding pool exhaustion rates, battery supply chain export control tightening, and rural grid infrastructure upgrade delays. Forecasts reflect documented assumptions on incentive continuity and commodity input stability. Material shifts in federal appropriations levels or battery cell trade policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Bus Transmission System Market
Buses
Europe Bus Market
Buses
Luxury Coaches Market
Buses
Bus Bellows Market
Buses
Fuel Cell Electric Bus Market
Buses
Global Luxury Shuttle Bus Market
Buses
Airport Shuttle Bus Market
Buses
Bus Chassis Market
Buses
Global Bus Market
Buses
Bus Charter Services Market
Buses
Buses & Coaches Market
Buses
School Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Rental Market
Buses
Europe Trolley Bus Market
Buses
Bus Seat Market