
 Trolley Bus Market | 2026-2036
Trolley Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Trolley Bus Market Outlook
China's manufacturing base for electric transit vehicles is reshaping supply dynamics across the trolley bus sector. Solaris Bus & Coach leverages its Polish production footprint to anchor European demand for low-floor configurations. Škoda Electric sustains competitive positioning through in-house traction motor production. Yutong Bus dominates volume shipments to Latin American and Southeast Asian markets with standardized platform designs.
A trolley bus is an electrically propelled road vehicle drawing power from dual overhead wires via spring-loaded trolley poles or pantographs, typically operating at 600-750 V DC with onboard rectifiers or direct current motors. It serves urban mass transit corridors requiring zero tailpipe emissions without full battery dependency. Battery hybrid technology leads new procurements as operators seek wire-free operational flexibility for route extensions. Low-floor buses command premium positioning in accessibility-mandated tenders across Western European cities. Articulated configurations represent the fastest-expanding capacity class for high-density corridors in Istanbul and Mexico City.
China's MIIT enforces GB standards for new energy commercial vehicles that dictate motor efficiency thresholds and electromagnetic compatibility testing. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in HVAC systems fitted to European-bound trolley buses. Transit authorities must weigh overhead infrastructure maintenance liabilities against battery hybrid capital savings when drafting procurement specifications. Stakeholders should monitor how China's SAMR adjusts subsidy phase-out timelines for domestic manufacturers exporting to price-sensitive markets.
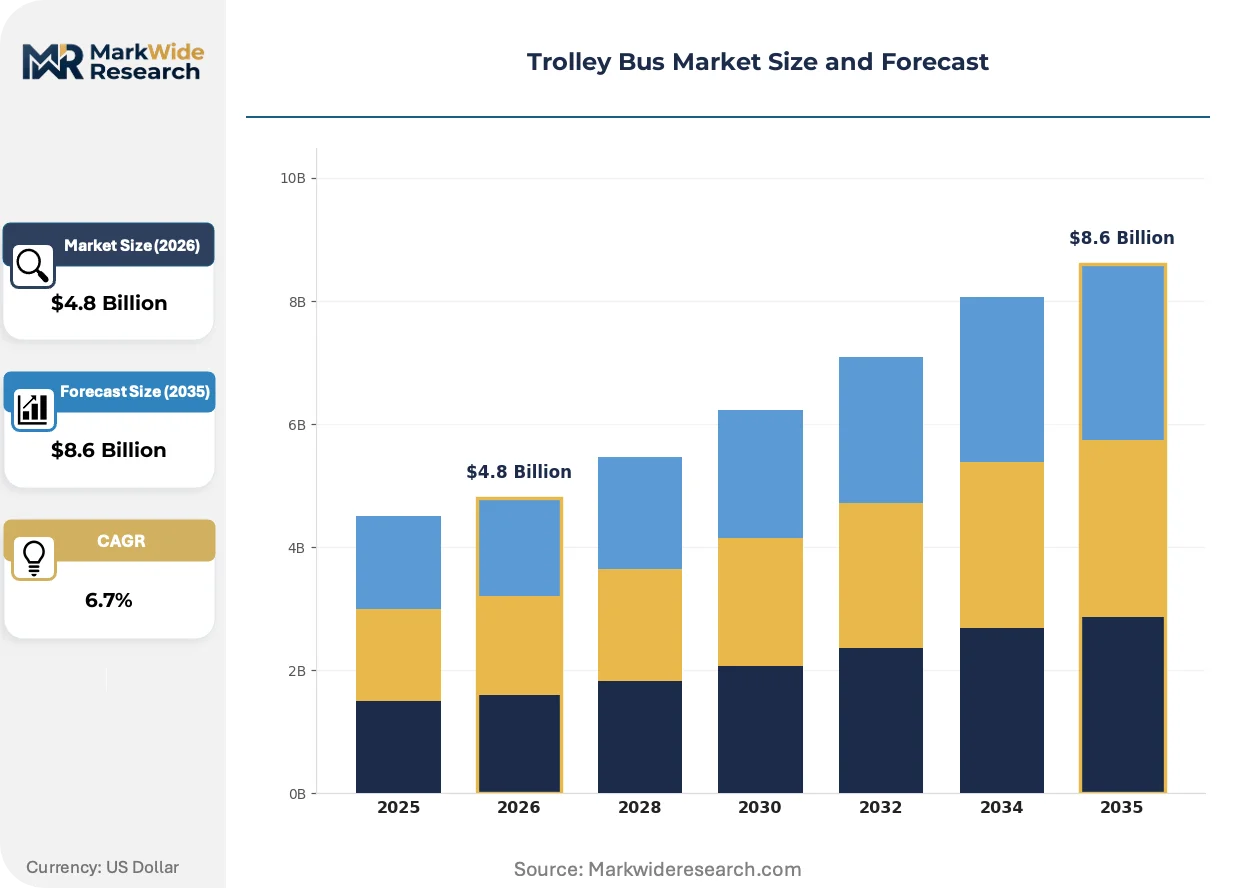
Market Dynamics
Dual-mode battery-trolley systems are compressing the traditional trade-off between overhead wire dependency and route flexibility, forcing procurement specifications to prioritize off-wire range over pure electric efficiency.
Growth Catalysts
- GB Standards Compliance:China's MIIT mandates for motor efficiency and electromagnetic compatibility in new energy commercial vehicles are accelerating traction system upgrades across domestic manufacturing bases.
- Urban Electrification Mandates:Municipal transit authorities in Latin American corridors are embedding wire-free operational requirements into fleet renewal tenders to extend service coverage without infrastructure expansion.
- Low-Floor Accessibility Directives:Western European city regulators are enforcing step-free boarding standards that favor modern trolley bus architectures over legacy high-floor alternatives in accessibility-mandated procurements.
Market Restraints
- Overhead Infrastructure Liability:Municipalities face escalating maintenance burdens for catenary networks, with wire replacement and pole rehabilitation consuming disproportionate shares of transit operating budgets.
- Copper Price Volatility:Traction power distribution systems depend on copper conductor materials, exposing fleet operators to commodity cost swings that complicate long-term capital planning.
- Dual Powertrain Complexity:Battery-trolley hybrid architectures introduce redundant energy systems that increase vehicle mass, reduce passenger capacity per axle, and complicate warranty coverage structures.
Strategic Opportunities
- Polish Manufacturing Corridor:Production facilities in Poland's urban industrial zones offer tariff-advantaged access to EU transit authorities seeking compliant low-floor configurations with shortened delivery timelines.
- Articulated Capacity Class:High-density corridors in Istanbul and Mexico City are generating demand for extended-length vehicles that trolley bus platforms can deliver without battery weight penalties affecting axle load limits.
- F-Gas Regulatory Tailwind:The EU F-Gas Regulation constrains refrigerant choices in HVAC systems, creating specification advantages for European-manufactured vehicles with compliant thermal management designs.
Industry Challenges
- Traction Motor Integration:In-house power electronics capabilities remain concentrated among established suppliers, limiting new entrants' ability to meet efficiency thresholds without captive motor production or licensed technology.
- Certification Timeline Compression:Electromagnetic compatibility testing under China's GB standards and European CE marking requirements creates sequential approval bottlenecks for manufacturers targeting multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trolley Bus Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Deck Buses, Double-Deck Buses, Articulated Buses, Low-Floor Buses Technology: Overhead Line System, Battery Hybrid, Diesel Hybrid, Fuel Cell End User: Public Transport Authorities, Private Operators, Government Agencies, Educational Institutions Capacity: 20-40 Passengers, 41-80 Passengers, 81-120 Passengers, Over 120 Passengers |
| Companies Covered | Solaris Bus & Coach, Škoda Electric, Iveco Group, Yutong Bus, Van Hool NV, BYD Company Limited, Hess AG, Bozankaya, New Flyer Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trolley Bus Market Strategic Shifts
Power electronics miniaturization and solid-state battery chemistry are converging to redefine trolley bus operational envelopes, compressing the performance gap between wired and wire-free modes.
Silicon carbide traction inverters are virtualizing the traditional motor control architecture by replacing silicon-based IGBT modules with wide-bandgap semiconductors that operate at higher switching frequencies and lower thermal losses. Transit operators in high-temperature climates are specifying these systems to reduce cooling system mass and extend component service intervals. The technology is virtualizing the conventional trade-off between power density and reliability that constrained earlier generation trolley bus designs.
The EU Green Deal's embedded carbon accounting requirements are reshaping supplier qualification protocols for vehicles entering European service. Manufacturers must now document lifecycle emissions from steel production through end-of-life recycling, with penalties for non-compliant bids in publicly tendered contracts. Polish and Czech production facilities are capturing disproportionate share of these tenders by leveraging regional grid decarbonization and proximate supply chains.
Service contracting is fragmenting from bundled procurement toward unbundled powertrain warranties and infrastructure maintenance agreements. Municipal buyers in Latin American markets are separating vehicle acquisition from overhead network operations, transferring catenary liability to specialized infrastructure concessionaires. This unbundling is most advanced in Brazilian and Colombian transit authorities seeking to isolate operational risk from capital deployment decisions.
Trolley Bus Market Segmentation
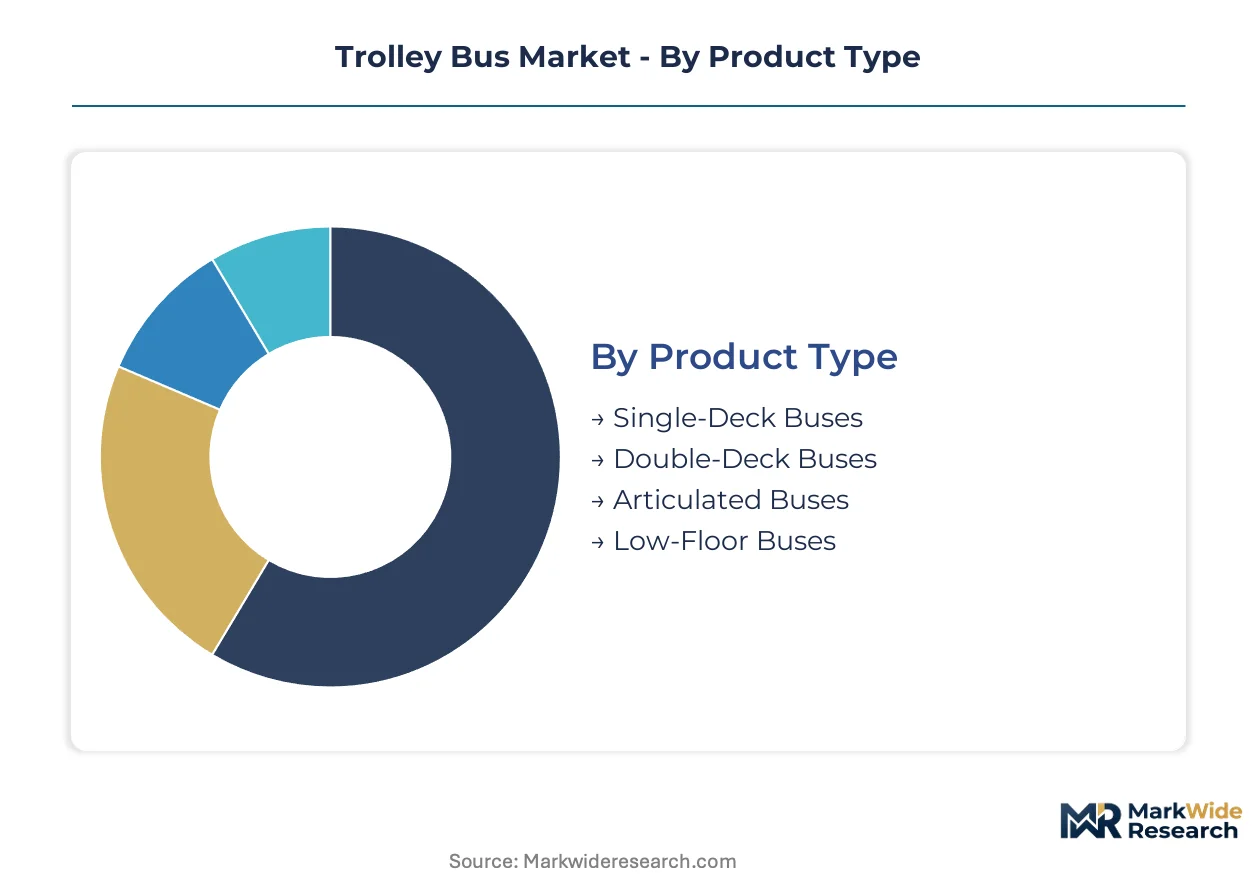
Trolley bus procurement specifications diverge sharply across municipal operating environments, with infrastructure legacy, passenger density, and accessibility mandates dictating platform selection. Manufacturers must align product architectures with these distinct requirement clusters to secure tender awards.
Product Type:
Urban corridors present varying platform demands based on passenger throughput, street geometry, and accessibility regulations.
- Single-Deck Buses:Standard 12-meter configurations serve medium-density routes with constrained turning radii. Polish and Czech manufacturers dominate European tenders for these platforms, leveraging CE marking efficiency and regional supply chain proximity to underbid distant competitors on delivery timelines.
- Articulated Buses:Extended 18-meter designs with pivoting midsections accommodate peak-hour loads exceeding 150 passengers. Istanbul's Metrobüs corridor and Mexico City's Eje Central route have standardized on these configurations, where trolley pole current collection eliminates battery weight penalties that compress passenger capacity on competing electric platforms.
- Double-Deck Buses:Two-level passenger compartments maximize seating density without extending vehicle footprint. Hong Kong's Kowloon Motor Bus and select UK operators maintain limited deployments where tunnel clearances permit.
- Low-Floor Buses:Step-free boarding platforms comply with EU accessibility directives and UN Convention mandates. These architectures command specification premiums in Western European tenders where regulators enforce level boarding for mobility-impaired passengers.
The dominant share belongs to single-deck buses, while articulated buses are closing the gap fastest.
Technology:
Powertrain selection hinges on the trade-off between infrastructure dependency and operational autonomy.
- Overhead Line System:Pure trolley configurations draw continuous 600-750V DC from dual overhead wires via spring-loaded poles or pantographs. These systems deliver lowest lifecycle cost per kilometer where catenary networks already exist, particularly in Eastern European cities with Soviet-era infrastructure inheritance.
- Battery Hybrid:Dual-mode architectures combine overhead current collection with onboard lithium-ion storage for wire-free segments. Latin American transit authorities in São Paulo and Bogotá are embedding minimum off-wire range requirements into fleet specifications to extend service coverage without infrastructure expansion.
- Diesel Hybrid:Trolley buses with auxiliary diesel generators provide emergency mobility during overhead network failures. These configurations face declining procurement interest as battery energy density improvements reduce reliance on combustion backup.
- Fuel Cell:Hydrogen fuel cell range extenders enable extended wire-free operation with rapid refueling. South Korean demonstration projects and select Chinese pilot fleets are testing these platforms, though electrolysis infrastructure scarcity constrains deployment scale.
Overhead line systems retain installed base dominance, though battery hybrid platforms are expanding most quickly in new procurement cycles.
End User:
Contracting structures and risk allocation preferences vary across purchaser categories.
- Public Transport Authorities:Municipal and regional transit agencies issue bundled fleet and infrastructure tenders. These entities prioritize total cost of ownership metrics and local content requirements in award criteria.
- Private Operators:Concession-holding transport companies favor unbundled procurement with separate vehicle and powertrain warranties. Brazilian and Colombian operators are advancing this fragmentation to isolate operational risk from capital deployment.
- Government Agencies:National ministries and development banks finance fleet electrification through sovereign lending facilities. These purchasers emphasize technology transfer provisions and domestic assembly requirements.
- Educational Institutions:University and corporate campus shuttle systems represent niche demand for compact trolley configurations with reduced infrastructure investment.
Public transport authorities command procurement volume leadership, while private operators are gaining share fastest through concession restructuring.
Capacity:
Passenger volume thresholds align with route density and peak load profiles.
- 20-40 Passengers:Compact shuttle configurations serve low-frequency feeder routes and specialized campus transport. These platforms face competitive displacement from battery electric minibuses in smaller deployment scales.
- 41-80 Passengers:Standard urban configurations balance maneuverability with throughput for medium-density corridors. This segment concentrates procurement volume across European and Latin American markets.
- 81-120 Passengers:High-capacity single-deck and articulated designs address peak congestion on trunk routes. Mexico City's Metrobús and Istanbul's corridor networks have standardized specifications in this range.
- Over 120 Passengers:Maximum-density articulated and bi-articulated platforms serve megacity corridors with passenger volumes exceeding 50,000 daily riders per direction.
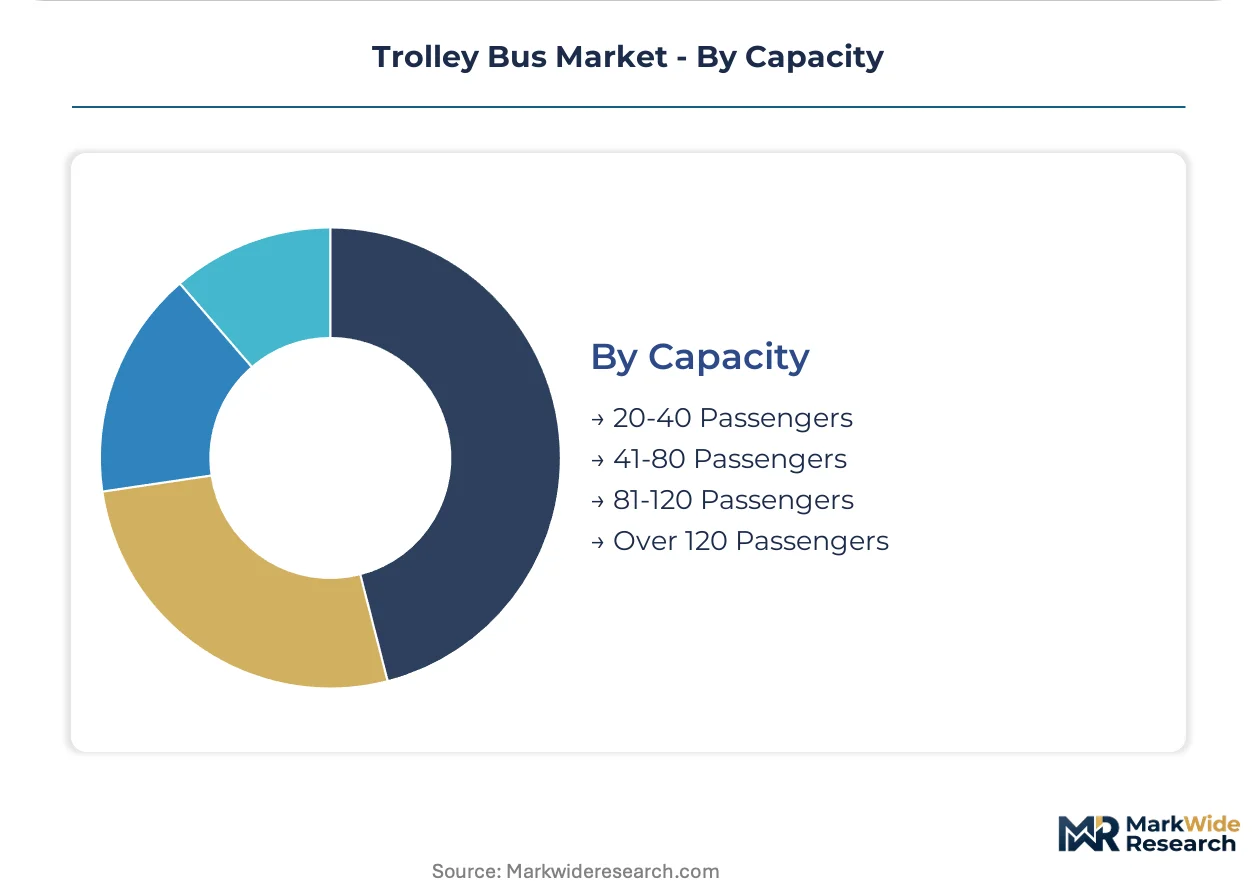
The 41-80 passenger segment holds dominant procurement share, while the 81-120 passenger category is climbing the fastest on high-density corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for trolley bus systems clusters in Poland, China, and the Czech Republic, with each hub serving distinct procurement geographies through specialized platform configurations and regulatory compliance pathways.
Poland
Solaris Bus & Coach anchors European demand through its Bolechowo facility, delivering low-floor configurations compliant with EU accessibility directives. The EU Green Deal's embedded carbon accounting requirements favor Polish production due to regional grid decarbonization. Warsaw and Kraków transit authorities are standardizing on articulated platforms for high-density corridors.
China
MIIT's GB standards for motor efficiency and electromagnetic compatibility dominate procurement specifications across domestic and export markets. Yutong Bus leverages Zhengzhou manufacturing scale to supply standardized platforms to Latin American and Southeast Asian operators. Shenzhen and Guangzhou are piloting solid-state battery integration for extended wire-free range.
Czech Republic
Škoda Electric sustains competitive positioning through in-house traction motor production at its Plzeň facility. CE marking efficiency and proximity to German technical standards enable penetration of Western European tenders. Prague's transit authority is retrofitting Soviet-era catenary infrastructure for dual-mode battery-trolley operation.
Turkey
Istanbul's Metrobüs corridor generates concentrated demand for articulated 18-meter configurations serving 50,000-plus daily riders per direction. Bozankaya supplies domestic transit authorities with platforms optimized for high-temperature climate operation. The country's national industrial strategy prioritizes local assembly requirements in publicly tendered contracts.
Brazil
São Paulo's municipal transit authority embeds minimum off-wire range requirements into fleet renewal specifications to extend service coverage without infrastructure expansion. ANVISA regulates commercial vehicle safety standards alongside environmental licensing from IBAMA. Curitiba's BRT legacy is transitioning toward trolley bus electrification for dedicated corridor segments.
Trolley Bus Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying traction motors, power electronics, and thermal management systems. Market structure tilts toward consolidation among established European and Chinese manufacturers with captive production of critical subsystems. Three archetypes dominate: vertically integrated platform builders, traction system specialists with licensed motor technology, and diversified commercial vehicle groups with trolley bus as a product line extension. Competitive moves concentrate on geographic expansion through localized assembly partnerships and technology licensing to circumvent tariff barriers.
Within the European platform tier, Solaris Bus & Coach and Škoda Electric exemplify vertically integrated specialists with regional manufacturing footprints. Yutong Bus represents the scale-driven Chinese archetype supplying standardized configurations to price-sensitive export markets. Among diversified commercial vehicle groups, Iveco Group occupies a position spanning multiple powertrain technologies across its bus and coach portfolio.
| Leading Market Players |
|---|
| Solaris Bus & Coach |
| Škoda Electric |
| Iveco Group |
| Yutong Bus |
| Van Hool NV |
| BYD Company Limited |
| Hess AG |
| Bozankaya |
| New Flyer Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Zhengzhou's manufacturing cluster capacity dynamics directly compress pricing power for export-bound trolley bus platforms, as Chinese producers leverage standardized designs to underbid European specialists on volume tenders while Polish facilities capture premium positioning through EU regulatory compliance.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European procurement markets, separating premium low-floor configurations with compliant HVAC systems from standard platforms facing specification penalties. Pricing stratifies across premium CE-marked articulated designs, standard single-deck configurations, and economy-tier battery hybrid conversions for legacy fleets. Cost compression in the economy tier is intensifying because Latin American operators prioritize off-wire range over traction motor efficiency. Municipal transit authorities in Brazil and Colombia demonstrate highest price sensitivity, while accessibility-mandated tenders in Western European cities show lowest elasticity.
Supply Chain Analysis
Export control regimes on wide-bandgap semiconductor technology constrain silicon carbide traction inverter flows from US and Japanese suppliers to Chinese platform integrators, fragmenting power electronics sourcing strategies. Manufacturing concentrates in Poland, China, and the Czech Republic, with traction motor production anchored in Plzeň and Bolechowo. Copper conductor materials, lithium-ion battery cells, and HVAC refrigerant systems constitute critical input dependencies. Single-source vulnerability in silicon carbide substrate supply creates procurement bottlenecks for high-efficiency traction systems. Distribution runs through municipal tender processes with bundled fleet and infrastructure awards, though Brazilian and Colombian operators are fragmenting toward unbundled vehicle procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trolley bus procurement cycles track municipal capital expenditure recovery patterns, with fleet electrification commitments accelerating as transit authorities rebuild ridership revenue bases post-pandemic.
For Market Incumbents: Insulate margin positions by deepening backward integration into traction motor production and capturing Polish manufacturing capacity for EU Green Deal compliance. Battery electric bus substitution threats from BYD and Yutong require defensive certification investments in dual-mode battery-trolley architectures. Channel control through localized assembly partnerships in Turkey and Brazil isolates tariff exposure. For New Entrants and Emerging Players: Pursue white-space opportunities in fuel cell range extender integration for South Korean and Chinese pilot fleets, where electrolysis infrastructure scarcity has delayed incumbent scale-up. Campus shuttle systems at North American universities represent the most penetrable niche, with compact platform demand unmet by volume-focused manufacturers. Go-to-market execution should emphasize unbundled powertrain warranties to match Latin American concession restructuring. For Investors and Strategic Acquirers: Long-term, this sits as a cyclical infrastructure play because trolley bus deployment correlates with catenary network rehabilitation cycles and municipal bond issuance windows. Acquisition targets should concentrate on traction system specialists with captive silicon carbide inverter capabilities and CE marking efficiency. The signal to watch is MIIT subsidy phase-out adjustments for Chinese exporters, which would reprice competitive dynamics across Latin American tender markets.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Hybrid Platform Development | Dual-mode architectures satisfy São Paulo's off-wire range mandates while preserving overhead infrastructure investments. |
| Silicon Carbide Traction Inverter Integration | Wide-bandgap semiconductors reduce cooling system mass for Bozankaya's high-temperature climate specifications in Istanbul. |
| Polish Manufacturing Footprint Expansion | Regional grid decarbonization supports EU Green Deal embedded carbon accounting for Solaris Bus & Coach tenders. |
| Articulated Capacity Class Scale-Up | Extended 18-meter designs capture Mexico City Eje Central corridor demand without battery weight penalties. |
| Unbundled Service Contracting | Separate infrastructure concessions transfer catenary liability from Brazilian operators to specialized maintenance providers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT GB standard filings, EU tender documentation, and municipal transit authority procurement records, with input from fleet managers at Latin American operators, traction motor procurement leads at Polish manufacturers, power electronics engineers at Czech facilities, and catenary infrastructure concessionaires in Brazil. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction from disclosed contract awards and production capacity utilization.
Forecast inputs span vehicle class segmentation, propulsion architecture categories, and regional regulatory framework clusters across the projection horizon. CAGRs derive from modeled fleet replacement cycles, infrastructure rehabilitation timelines, and subsidy phase-out trajectories. Industry-specific variables include copper price volatility coefficients, battery energy density improvement curves, and electromagnetic compatibility testing duration assumptions.
Sensitivities concentrate around MIIT subsidy adjustments, EU F-Gas Regulation enforcement intensity, and copper commodity price swings. Forecasts reflect documented assumptions on municipal capital expenditure recovery trajectories and battery cost decline rates. Material shifts in China's SAMR export credit policies or Brazil's ANVISA safety standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Europe Trolley Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Luxury Bus Market
Buses
Bus Seat Market
Buses
Hydrogen Buses Market
Buses
Airport Bus Market
Buses
Canada School Bus Market
Buses
Solar Bus Market
Buses
Canada Transit Buses Market
Buses
Bus Flooring Market
Buses
Intelligent Bus Shelter Market
Buses
United States School Bus Market
Buses
Africa Electric Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Rental Market
Buses
Electric Intercity Bus Market