
 Buses & Coaches Market | 2026-2036
Buses & Coaches Market Size, Share, and Industry Trends Forecast 2026-2036
Buses & Coaches Market Analytics
Urban transit authorities is broadening the addressable base for bus and coach manufacturers beyond traditional municipal operators into corporate shuttle services and airport ground transport. Volvo Group leverages its electric platform expertise to anchor premium contracts in Nordic cities. BYD Company Limited dominates battery supply integration through in-house cell production. Tata Motors competes on cost-engineered platforms tailored to high-volume Asian markets.
Buses and coaches are wheeled passenger vehicles engineered for scheduled or chartered mass transport, typically constructed on ladder-frame chassis with gross vehicle weights ranging from 5 to 18 tonnes and designed for 30 to over 100 occupants. The electric fuel type segment captures the fastest expansion as battery energy densities above 250 Wh per kilogram enable 300-kilometer daily duty cycles without midday charging. Intercity coach configurations retain the deepest margin pools due to premium seating, climate systems, and extended warranty packages. City bus demand concentrates in public transport service types where fleet turnover cycles compress to eight years under intensified emissions enforcement.
The EU Green Deal and F-Gas Regulation mandate carbon-neutral procurement criteria for municipal fleets across member states, while the EPA in the United States enforces greenhouse gas Phase 2 standards that compel powertrain diversification. China's MIIT administers dual carbon goals that accelerate NEV subsidy phase-outs and shift cost burdens to manufacturers. Stakeholders must monitor how regulator-driven total cost of ownership parity between electric and diesel platforms reshapes fleet replacement timing and financing structures.
Market Dynamics
Zero-emission powertrain mandates are compressing fleet replacement cycles as municipal operators face binding carbon-neutral procurement deadlines under the EU Green Deal and parallel EPA greenhouse gas standards.
Growth Catalysts
- Battery energy density thresholds:Cell chemistries exceeding 250 Wh per kilogram now support 300-kilometer daily duty cycles without midday charging, eliminating range anxiety for intercity operators.
- F-Gas Regulation phase-down:The European framework mandates low-global-warming-potential refrigerants in climate systems, forcing HVAC upgrades that favor integrated electric thermal management platforms.
- Corporate shuttle electrification:Technology campuses and airport ground transport operators are expanding contracted fleet volumes beyond traditional municipal procurement channels.
Market Restraints
- Lithium supply concentration:Spodumene processing capacity clusters in Western Australia and Chile's Salar de Atacama, exposing cell manufacturers to concentrate risk and freight volatility.
- Charging infrastructure gap:Depot electrification requires 1-2 megawatt grid connections that utilities in Germany and the Netherlands cannot provision within standard 18-month procurement windows.
- Residual value uncertainty:Secondary markets for retired electric buses lack standardized battery state-of-health certification protocols, depressing trade-in valuations.
Strategic Opportunities
- Intercity coach premiumization:Long-haul configurations with sleeper berths and galley facilities command margin pools 40-60% above city bus equivalents in France and Germany.
- Battery-as-a-service models:Decoupling cell ownership from vehicle purchase transfers degradation risk to financial intermediaries, lowering municipal capital barriers.
- India PLI scheme localization:Component manufacturing incentives under the Production Linked Incentive framework enable cost-engineered platform exports to Southeast Asian markets.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified personnel for 600-800V battery pack diagnostics and isolation fault remediation.
- Homologation timeline compression:Whole-vehicle type approval under UNECE R100 for electric powertrains now requires 14-18 months, misaligning with municipal tender schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buses & Coaches Market |
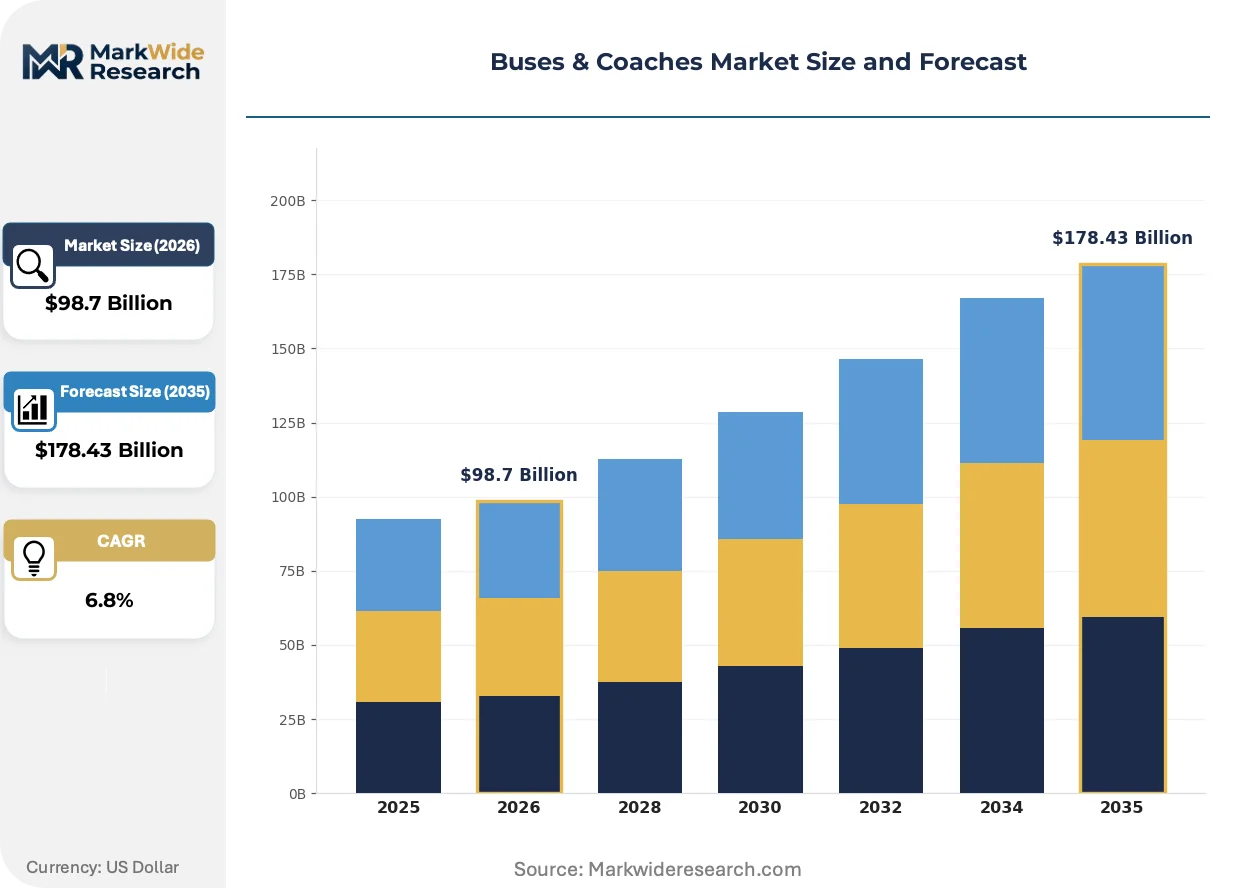
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: City Bus, Intercity Coach, School Bus, Shuttle Bus Fuel Type: Diesel, Electric, Hybrid, Compressed Natural Gas Passenger Capacity: Less than 30, 30-60, 61-100, More than 100 Service Type: Public Transport, Private Hire, Tour Services, Charter Services |
| Companies Covered | BYD Company Limited, Volvo Group, Yutong Group, Mercedes-Benz, Scania, MAN Truck & Bus, Tata Motors, Alexander Dennis Limited, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buses & Coaches Market Evolving Landscape
Powertrain architecture and procurement contracting are converging to reduce total cost of ownership parity gaps between electric and diesel platforms. Three developments are restructuring competitive positioning.
Cell-to-pack battery architecture is modularizing thermal management and structural enclosure functions into single integrated subassemblies. Nordic municipal operators are specifying these platforms for rapid swap compatibility. The design is modularizing supplier tier structures by collapsing separate battery management system vendors into consolidated subsystem integrators.
EPA greenhouse gas Phase 2 standards are tightening CO2 gram-per-mile thresholds for heavy-duty vehicles through 2027. Powertrain diversification into compressed natural gas and hydrogen fuel cells now qualifies for compliance credits. Intercity coach manufacturers serving California and New York corridors are responding with multi-fuel platform variants.
Performance-based service contracts are displacing traditional capital purchase with availability-guaranteed fee structures. Fleet operators in the Netherlands and Belgium are contracting kilometers-delivered rather than vehicle units. This shift concentrates working capital requirements onto OEM balance sheets while transferring operational risk to manufacturers.
Buses & Coaches Market Segmentation
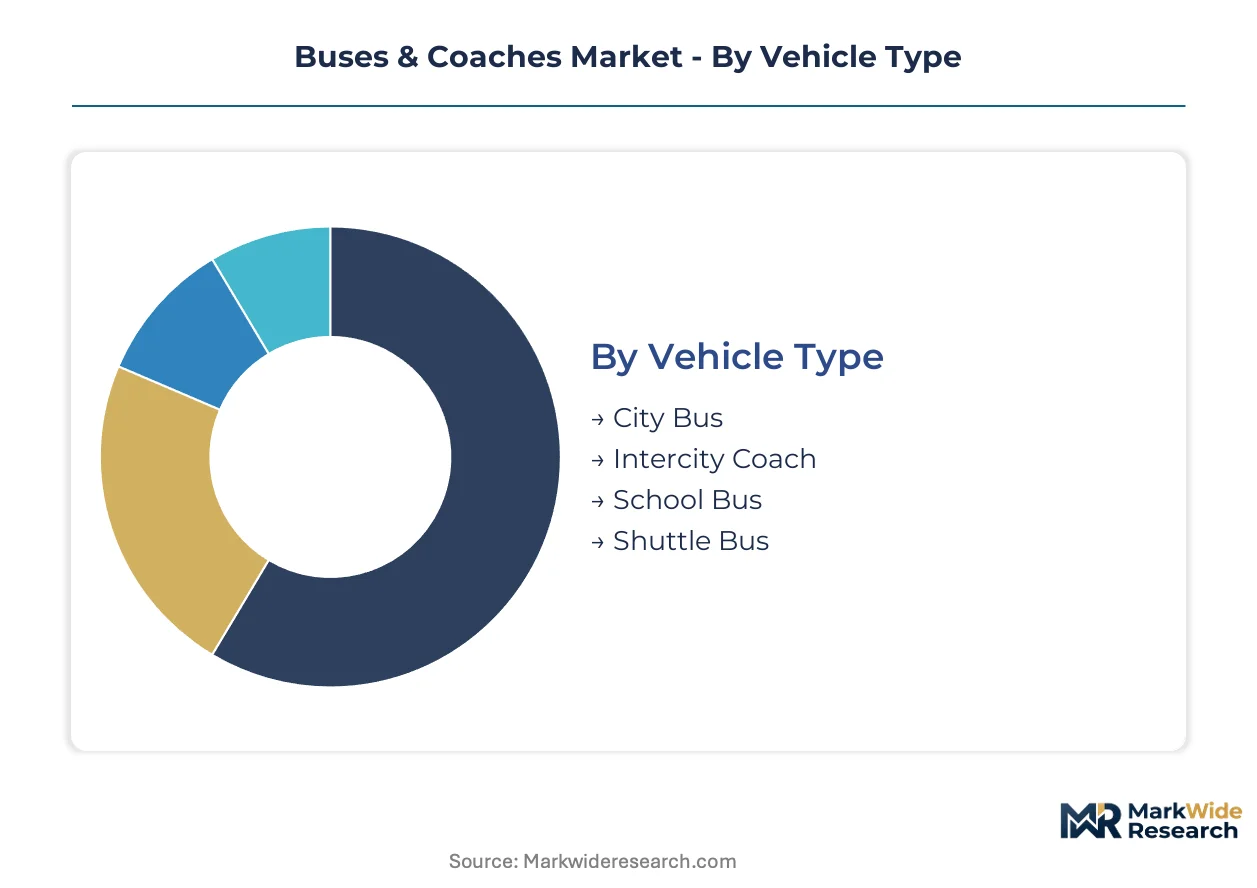
Segmentation in buses and coaches reveals divergent compliance burdens and margin architectures across vehicle configurations. Certification pathways under UNECE R100 for electric powertrains versus EPA greenhouse gas standards for combustion platforms create distinct supplier qualification requirements. Fleet procurement patterns cluster around these regulatory fault lines, with municipal tenders prioritizing zero-emission segments and intercity operators optimizing for duty-cycle flexibility.
Vehicle Type:
Certification intensity varies sharply across configurations, with electric city buses facing 14-18 month UNECE R100 homologation timelines while diesel intercity coaches navigate EPA Phase 2 CO2 gram-per-mile thresholds.
- City Bus:Low-floor designs with kneeling suspension systems accommodate 70-100 standing and seated passengers across frequent-stop urban routes. German and Dutch municipal operators are specifying cell-to-pack battery architectures with rapid-swap compatibility under EU Green Deal procurement mandates. Depot electrification requirements for 1-2 megawatt grid connections constrain fleet scaling in Berlin and Rotterdam.
- Intercity Coach:High-deck configurations with underfloor luggage bays and reclining seats serve 200-500 kilometer stage-carriage routes. Sleeper berths and galley facilities on premium French and German long-haul services command margin pools 40-60% above city bus equivalents. Multi-fuel platform variants now qualify for EPA greenhouse gas compliance credits in California and New York corridors.
- School Bus:Yellow-livery vehicles with flashing red lights and stop-sign arms operate under NHTSA Federal Motor Vehicle Safety Standard 131 in the United States. Type C conventional and Type D transit-style configurations dominate North American procurement.
- Shuttle Bus:Cutaway chassis with 16-30 passenger capacities serve airport ground transport and corporate campus circulation. Technology campuses in California and Texas are expanding contracted electric fleet volumes beyond traditional municipal channels.
City Bus sits at the top of the volume ranking, with Shuttle Bus climbing the fastest.
Fuel Type:
Cost tier stratification separates capital-intensive electric platforms with battery-as-a-service financing from lower-first-cost diesel and CNG alternatives.
- Electric:Battery-electric powertrains with 250+ Wh per kilogram cell densities enable 300-kilometer daily duty cycles without midday charging. Nordic cities are mandating zero-emission procurement under binding carbon-neutral deadlines. Residual value uncertainty persists due to absent standardized battery state-of-health certification protocols in secondary markets.
- Diesel:Compression-ignition engines with selective catalytic reduction and diesel particulate filters retain installed base dominance in high-mileage intercity applications. German operators face accelerating fleet turnover cycles as municipal authorities enforce EU Green Deal compliance timelines.
- Hybrid:Parallel and series-hybrid architectures combine downsized combustion engines with electric traction motors for stop-start urban duty cycles. These configurations serve as transition technologies where charging infrastructure remains inadequate.
- Compressed Natural Gas:Spark-ignition engines operating on stored methane qualify for EPA greenhouse gas Phase 2 compliance credits. Refueling infrastructure concentration limits deployment to depots with dedicated compressor stations.
Diesel retains the largest installed base, though Electric is gaining share fastest as total cost of ownership parity approaches.
Passenger Capacity:
Application-driven sizing separates high-frequency urban circulation from low-density suburban and charter services.
- Less than 30:Minibus and midibus configurations serve demand-responsive transport and paratransit services. These vehicles access narrower street networks in historic European city centers.
- 30-60:Standard single-deck city buses dominate high-frequency trunk routes in London, Paris, and Madrid. This bracket captures the deepest procurement volumes under municipal tender programs.
- 61-100:Articulated and double-deck configurations accommodate peak-hour loading on BRT corridors and suburban express routes. Three-door layouts enable sub-30-second dwell times at high-volume stops.
- More than 100:Bi-articulated and high-capacity double-deck vehicles serve dedicated busway systems in Curitiba, Bogotá, and Istanbul. These segments require specialized infrastructure and command premium unit pricing.
30-60 leads procurement volumes globally, with 61-100 expanding most quickly under BRT network investments.
Service Type:
Customer type fragmentation distinguishes publicly subsidized operations from commercial risk-bearing private contracts.
- Public Transport:Scheduled services operated under concession agreements with municipal or regional transport authorities. Netherlands and Belgian operators are shifting to performance-based contracts with availability-guaranteed fee structures.
- Private Hire:Contracted employee shuttle services for corporate campuses, hospitals, and universities. Technology and healthcare sectors in California and Massachusetts are accelerating electrification mandates.
- Tour Services:Sightseeing and excursion operations with seasonal demand patterns and premium seating configurations. Double-deck open-top vehicles dominate European heritage city circuits.
- Charter Services:On-demand group transport for schools, sports teams, and religious organizations. This segment retains diesel dominance due to irregular duty cycles and remote destination requirements.
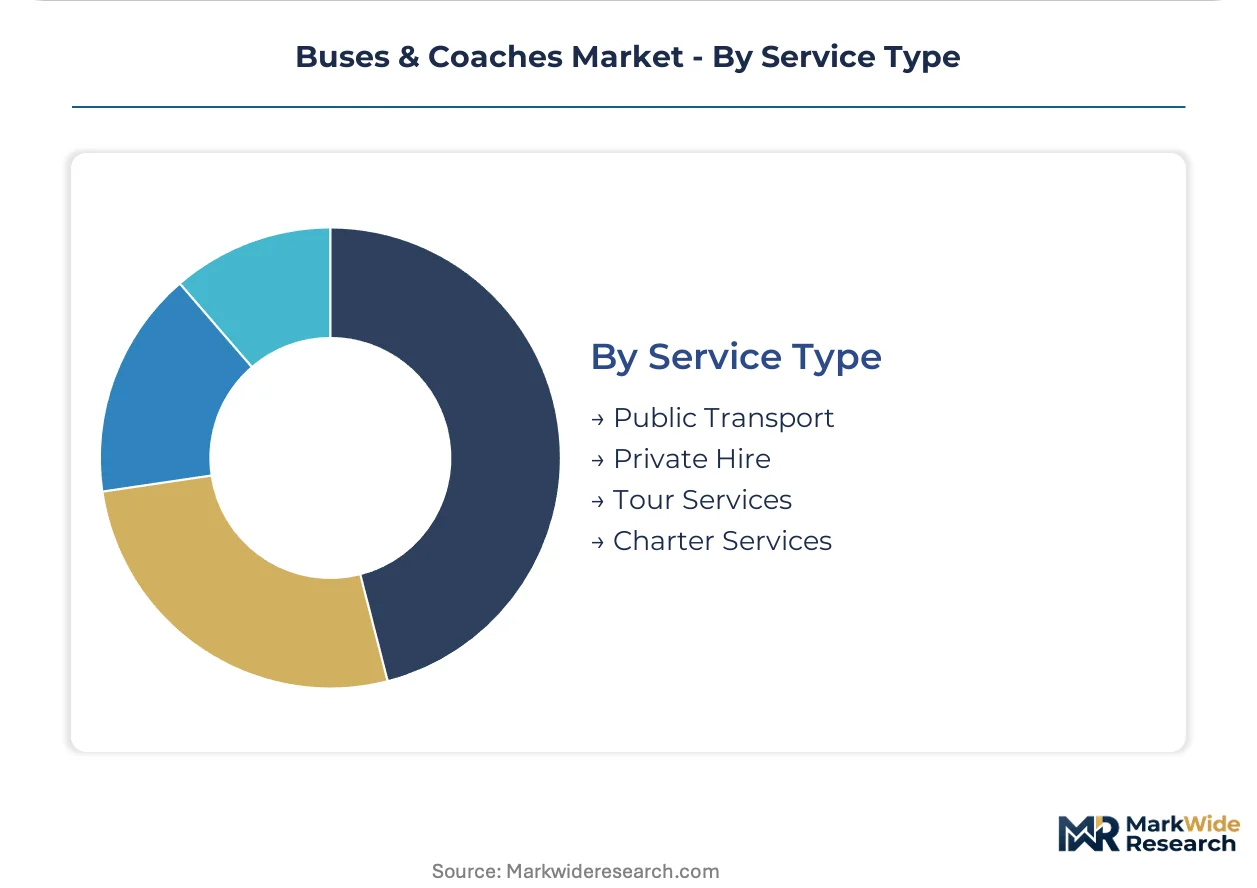
Public Transport commands the highest fleet turnover, with Private Hire recording the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production investment toward jurisdictions where compliance costs and subsidy structures favor electric platform manufacturing over legacy diesel assembly.
Germany
Municipal operators in Berlin and Hamburg are compressing fleet replacement cycles to eight years under binding EU Green Deal deadlines. The KBA enforces UNECE R100 homologation timelines of 14-18 months for electric powertrains. The North Rhine-Westphalia industrial corridor hosts depot electrification projects requiring 1-2 megawatt grid connections that utilities struggle to provision within standard procurement windows.
China
MIIT-administered dual carbon goals are accelerating NEV subsidy phase-outs and shifting cost burdens onto domestic manufacturers. Battery-electric city bus procurement dominates municipal tenders in Beijing and Shenzhen. The Yangtze River Delta cluster concentrates cell-to-pack architecture production for export markets.
United States
EPA greenhouse gas Phase 2 standards are tightening CO2 gram-per-mile thresholds through 2027, compelling powertrain diversification into compressed natural gas and hydrogen fuel cells. California and New York corridor operators are contracting multi-fuel platform variants. Technology campuses in the San Francisco Bay Area are expanding electric shuttle fleet volumes beyond traditional municipal channels.
India
The PLI scheme is localizing component manufacturing for cost-engineered platform exports to Southeast Asian markets. State transport undertakings in Maharashtra and Karnataka are piloting battery-as-a-service models to lower capital barriers. Tata Motors anchors domestic production with platforms tailored to high-volume Asian operating conditions.
Netherlands
Performance-based service contracts are displacing capital purchase with availability-guaranteed fee structures in Rotterdam and Amsterdam. The F-Gas Regulation mandates low-global-warming-potential refrigerants in climate systems, forcing HVAC upgrades. Depot electrification constraints in the Randstad region are compressing fleet scaling timelines.
Buses & Coaches Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium municipal contracts while regional fabricators serve cost-sensitive emerging markets. The vendor base clusters around three strategic archetypes: battery-integrated specialists leveraging in-house cell production, chassis-focused manufacturers partnering with tier-one subsystem suppliers, and diversified automotive conglomerates cross-leveraging commercial vehicle platforms. Consolidation pressure is intensifying through strategic partnerships for charging infrastructure deployment and geographic expansion into subsidy-rich procurement jurisdictions.
Within the battery-integrated tier, BYD Company Limited and Yutong Group exemplify the archetype of manufacturers controlling upstream cell supply. Volvo Group occupies a position among Nordic-based premium platform specialists, while Tata Motors sits within the cost-engineered volume tier serving high-growth Asian markets. These three anchors represent divergent competitive vectors: captive battery supply, regional brand equity, and localization-driven cost structures.
| Leading Market Players |
|---|
| BYD Company Limited |
| Volvo Group |
| Yutong Group |
| Mercedes-Benz |
| Scania |
| MAN Truck & Bus |
| Tata Motors |
| Alexander Dennis Limited |
| Daimler AG |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement mandates gate qualified supply and premium-tier pricing access for bus and coach manufacturers, as carbon-neutral fleet requirements restrict tender participation to OEMs with certified electric platforms and in-house battery integration. Municipal operators in Germany and the Netherlands now pay availability premiums for zero-emission vehicles with guaranteed uptime clauses, compressing margin pools for uncertified competitors while rewarding integrated suppliers with cell-to-pack architectures.
Pricing Analysis
Distributor margins in municipal procurement channels run 8-12 percent for electric city buses, with direct-to-OEM discounts compressing these spreads in volume tenders. Three-tier pricing structure across premium, standard, and economy levels separates Nordic-specification vehicles with rapid-swap compatibility from cost-engineered platforms for Asian markets. Pricing pressure stems from lithium carbonate volatility and F-Gas Regulation compliance costs for HVAC retrofits. Corporate shuttle operators exhibit lowest price sensitivity due to sustainability mandates, while state transport undertakings in India face acute capital constraints.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese producers, with cathode active material processing concentrated in the Yangtze River Delta and nickel sulfate refining anchored in Indonesia. Bus manufacturers draw from spodumene concentrate mines in Western Australia, Chilean Salar de Atacama brine operations, and synthetic graphite facilities in Heilongjiang. Single-source vulnerability in 600-800V power electronics creates procurement risk for European OEMs dependent on German and Austrian semiconductor packaging. Distribution runs through municipal tender channels, intercity coach fleet operators, and corporate campus procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the buses and coaches market hinges on battery-as-a-service financing models that transfer degradation risk to financial intermediaries while capturing recurring revenue streams from municipal operators.
For Market Incumbents: Deploy cell-to-pack architecture standardization to defend against Chinese OEMs with captive lithium supply. Consolidate aftermarket service networks in Germany and the Netherlands to capture depot electrification maintenance contracts. Certification investment in UNECE R100 homologation creates barriers against emerging entrants lacking 14-18 month approval timelines. For New Entrants and Emerging Players: Airport ground transport operators represent an underserved buyer archetype with electrification mandates outpacing incumbent capacity. Technology campuses in Texas and California offer white-space procurement channels outside municipal tender complexity. Battery-as-a-service partnerships with regional financial institutions provide go-to-market leverage against capital-constrained fleet managers. For Investors and Strategic Acquirers: Roll-up economics work for regional electric platform specialists because municipal procurement fragmentation across 27 EU member states prevents scale concentration. Mid-tier manufacturers with certified architectures in Poland, Czech Republic, and Romania offer acquisition targets with embedded regulatory compliance. Watch battery state-of-health certification protocol standardization as the inflection signal for residual value stabilization and secondary market liquidity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Model Deployment | Transfers degradation risk to financial intermediaries, lowering municipal capital barriers in Germany and the Netherlands. |
| Cell-to-Pack Architecture Standardization | Enables rapid-swap compatibility for Nordic operators while collapsing separate BMS vendor tiers. |
| Depot Electrification Partnership | Secures 1-2 megawatt grid connection priority with utilities in Berlin and Rotterdam procurement windows. |
| UNECE R100 Certification Investment | Creates 14-18 month homologation barriers against uncertified competitors in EU municipal tenders. |
| Multi-Fuel Platform Development | Qualifies for EPA greenhouse gas Phase 2 compliance credits in California and New York corridors. |
Research Methodology
Direct dialogue with municipal fleet managers, OEM platform engineers, Tier 1 battery subsystem suppliers, and charging infrastructure developers grounded qualitative findings in operational constraints. Secondary validation drew from KBA type-approval databases, EPA greenhouse gas compliance filings, MIIT NEV subsidy disclosures, and EU Green Deal procurement tender records. Bottom-up unit economics modeling triangulated against top-down market sizing from vehicle registration data.
Bottom-up segment modeling across vehicle type, fuel architecture, passenger capacity bracket, and service category generated volume and value outputs over the projection horizon. CAGRs derived from logistic diffusion curves for electric powertrain penetration, calibrated to municipal fleet replacement cycle compression under binding emissions deadlines. Industry-specific inputs included lithium carbonate price trajectories, depot electrification grid connection lead times, and UNECE R100 homologation queue lengths.
Underlying measurement precision varies by segment; electric city bus forecasts carry tighter precision than intercity coach projections due to standardized municipal tender data availability. Forecasts reflect assumptions on battery energy density improvement curves, F-Gas Regulation enforcement timelines, and utility infrastructure investment pacing. Policy subsidy phase-out schedules, raw material supply disruptions, and technician certification bottlenecks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Luxury Bus Market
Buses
Electric Intercity Bus Market
Buses
United States Electric Bus Market
Buses
North America Bus Market
Buses
Solar Bus Market
Buses
Global Luxury Shuttle Bus Market
Buses
Intelligent Bus Shelter Market
Buses
Bus Rental Market
Buses
School Bus Market
Buses
Bus Charter Services Market
Buses
Bus Flooring Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Hydrogen CNG Bus Market
Buses
Canada School Bus Market
Buses
Bus Seat Market
Buses
Bus Transmission System Market