
 Luxury Coaches Market | 2026-2036
Luxury Coaches Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Coaches Market Intelligence
Dealer networks for ultra-premium configurations is narrowing as direct-to-fleet contracts gain share among large-volume buyers. Prevost leverages its integrated chassis-body manufacturing to sustain premium positioning in the North American charter segment. Marathon Coach specializes in bespoke interior configurations that anchor its reputation among ultra-high-net-worth individual purchasers. Newell Coach competes on all-electric platform development, differentiating through in-house battery thermal management systems.
A luxury coach is a purpose-built, high-specification road vehicle typically exceeding twelve meters in length, constructed on a dedicated chassis with composite or aluminum body structures, and designed to transport passengers in premium comfort configurations with amenities such as lie-flat seating, galley facilities, and advanced climate control systems. The primary commercial purpose is to deliver differentiated mobility experiences for tour operators, corporate fleets, and private clients where rail or air alternatives prove impractical. Double-decker and articulated configurations command the highest margin pools in European touring applications due to per-passenger operating economics, while electric drive technology represents the fastest-growing segment as fleet operators face zero-emission zone mandates in urban departure points. Diesel engine platforms remain the largest installed base but are concentrating in long-haul charter routes where charging infrastructure remains sparse.
EPA heavy-duty emissions standards and NHTSA fuel economy regulations in the United States are tightening certification requirements for imported powertrains, while Euro VI Stage V and the EU Green Deal in Europe are accelerating powertrain electrification timelines across touring fleet renewals. The EU AI Act is additionally framing liability standards for autonomous systems integration in driver-assistance configurations. Stakeholders must monitor regulatory divergence between California's Advanced Clean Trucks framework and federal baseline standards, as this fragmentation threatens to bifurcate product development roadmaps and compliance costs.
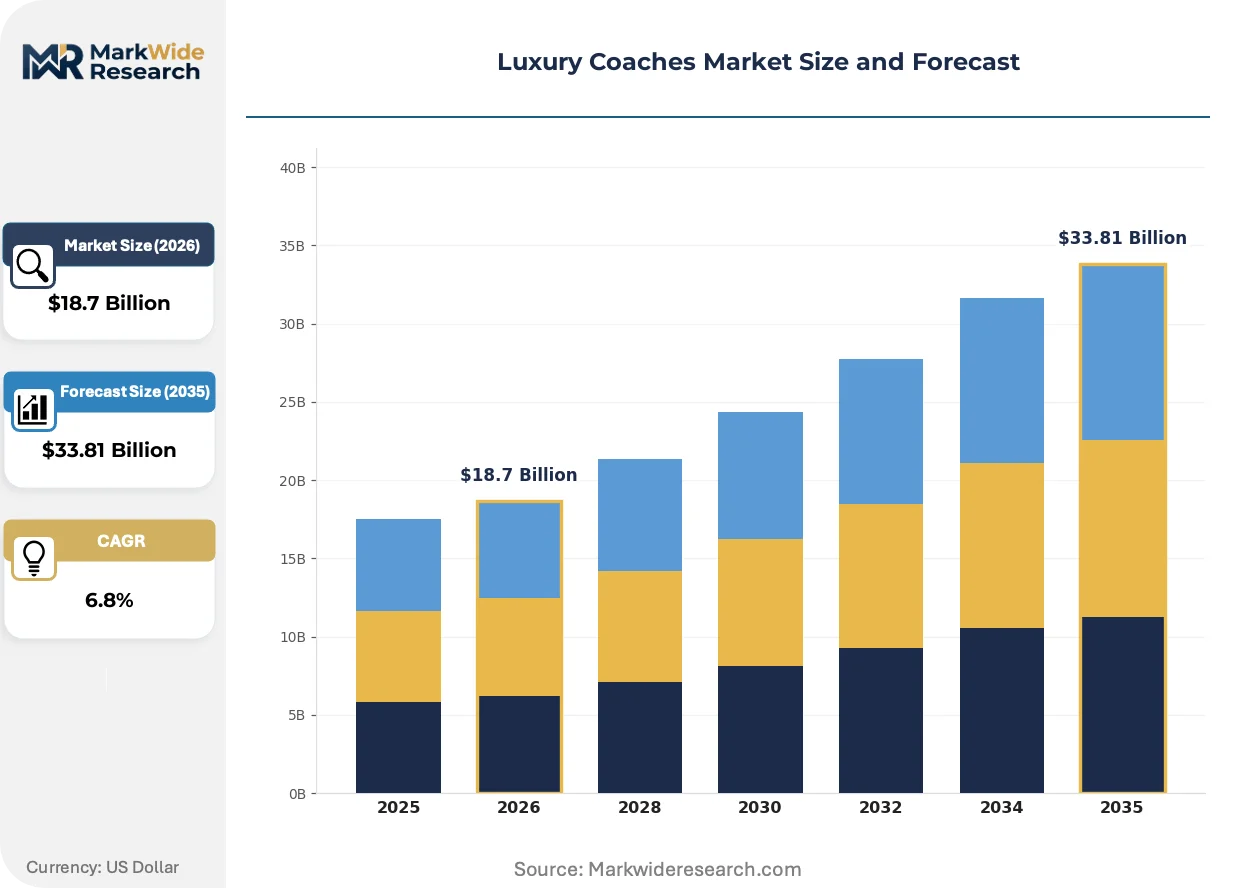
Market Dynamics
Fleet procurement patterns are concentrating around sovereign wealth-backed hospitality developments in Saudi Arabia, where giga-project timelines are compressing delivery windows and favoring direct manufacturer contracts over traditional dealer channels.
Growth Catalysts
- Euro VI Stage V mandates:European touring fleet operators face accelerated replacement cycles for diesel platforms, creating immediate demand for hybrid and hydrogen fuel cell configurations in long-haul applications.
- Saudi giga-project pipelines:NEOM, Red Sea Global, and Qiddiya developments are sustaining multi-year procurement programs for ultra-premium touring configurations with lie-flat seating and integrated galley systems.
- Zero-emission zone expansion:Urban departure points in Germany, France, and the Netherlands are banning diesel coach access, forcing charter operators to electrify depot fleets ahead of infrastructure readiness.
Market Restraints
- Chassis supply concentration:Integrated chassis-body manufacturing capabilities cluster with three European suppliers, creating bottleneck risk for bespoke aluminum composite body orders exceeding twelve-meter configurations.
- Hydrogen infrastructure gaps:Fuel cell platform adoption stalls on sparse H2 refueling networks along transcontinental touring corridors, particularly across the Alpine region and Nordic routes.
- EPA certification friction:Imported powertrains face tightening heavy-duty emissions validation timelines under NHTSA fuel economy regulations, delaying North American market entry for European hybrid platforms.
Strategic Opportunities
- Autonomous driver-assistance integration:The EU AI Act is establishing liability frameworks for Level 3+ highway pilot systems, enabling premium charter operators to market reduced driver fatigue on overnight routes.
- Battery thermal management specialization:In-house development of liquid-cooled pack architectures offers differentiation margin as fleet operators prioritize range consistency across temperature extremes.
- Direct-to-fleet contracting:Large-volume buyers in the Middle East are bypassing dealer networks, creating margin recovery opportunities for manufacturers willing to absorb aftermarket service obligations.
Industry Challenges
- Composite body repair certification:Aluminum-bonded panel damage requires specialized technician training that outpaces vocational program output in Germany and the Czech Republic.
- Dual regulatory compliance:Manufacturers must simultaneously satisfy California's Advanced Clean Trucks framework and federal EPA baselines, bifurcating powertrain validation roadmaps and engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Coaches Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Coaches, Double-Decker Coaches, Articulated Coaches, Standard Coaches, Convertible Coaches Technology: Hybrid Powertrain, Diesel Engine, Electric Drive, Hydrogen Fuel Cell, Autonomous Systems Application: Touring Services, Corporate Transportation, Airport Transfers, Charter Services, Luxury Travel End User: Travel Agencies, VIP Transport Providers, Event Organizers, Hospitality Groups, Rental Companies |
| Companies Covered | American Coach, Renegade RV, Prevost, Winnebago Industries, Newmar, Newell Coach, Marathon Coach, Thor Motor Coach, Entegra Coach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Coaches Market Strategic Shifts & Innovations
Powertrain architecture decisions are migrating toward platform flexibility, where modular battery-electric and fuel cell configurations share common chassis architectures to hedge against infrastructure uncertainty and regulatory divergence.
Composite-intensive body construction is migrating from traditional riveted aluminum panels toward adhesive-bonded carbon-fiber-reinforced structures. Premium touring operators in Switzerland and Austria are specifying these configurations for weight reduction on mountain routes. This shift is compressing service life expectations while enabling larger panoramic glazing areas that differentiate luxury positioning.
California's Advanced Clean Trucks regulation is mandating zero-emission sales quotas for heavy-duty vehicle classes, with compliance obligations beginning for 2024 model years. Fleet operators serving Los Angeles and San Francisco departure points must electrify depot capacity or forfeit terminal access. Charter companies are responding with depot-based fast-charging infrastructure partnerships and route truncation strategies.
Large-volume buyers are consolidating procurement decisions at the holding-company level, displacing decentralized fleet manager autonomy. VIP transport providers in the UAE and Saudi Arabia now centralize specification authority with sovereign wealth investment offices. This concentration is visible in standardized interior configurations across hotel shuttle and corporate executive fleets in Riyadh and Dubai.
Luxury Coaches Market Segmentation
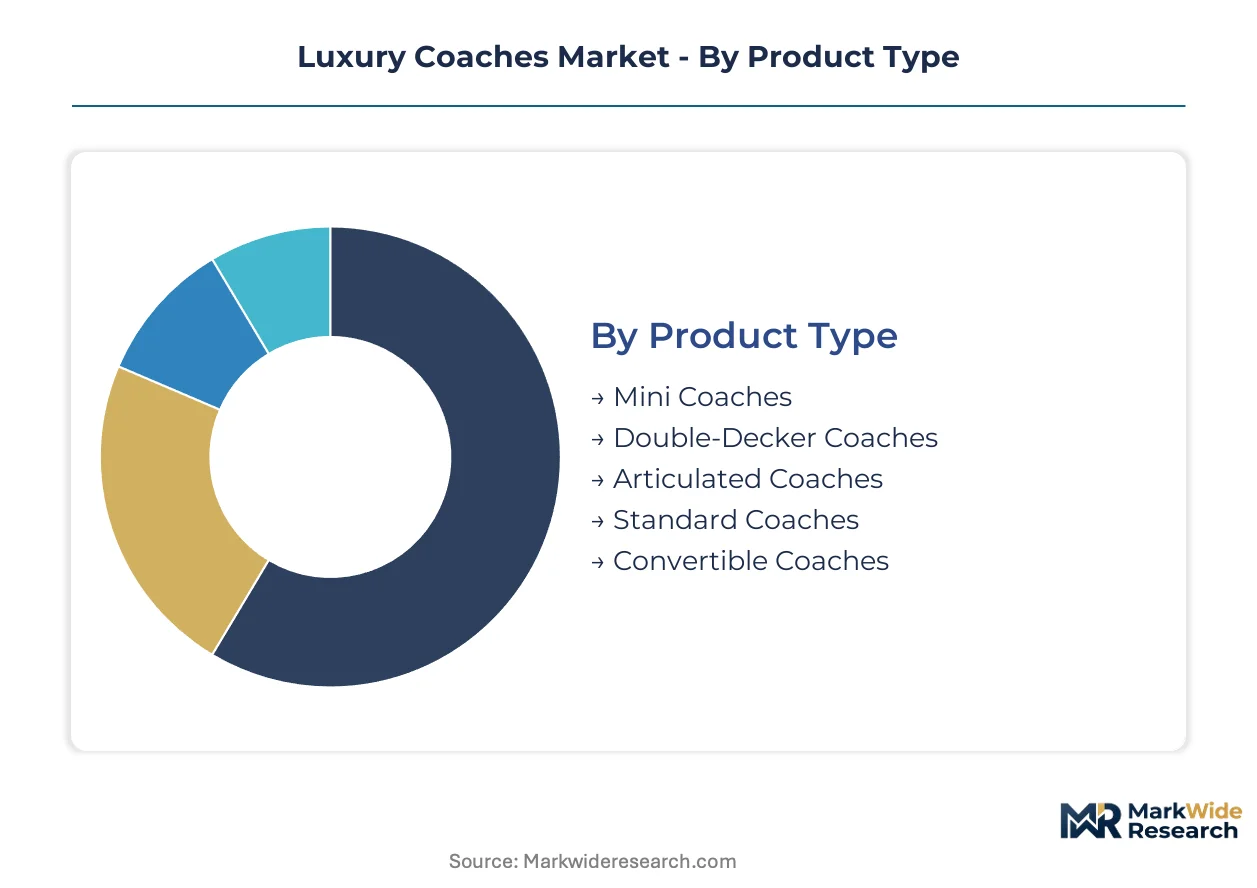
Segmentation in luxury coaches reveals how procurement authority concentrates among sovereign wealth-backed buyers while powertrain decisions fragment across regulatory jurisdictions. Product configuration and technology choices increasingly diverge between European zero-emission mandates and Middle Eastern long-haul touring requirements.
Product Type:
Mature double-decker platforms anchor European touring economics while emerging convertible configurations respond to experiential hospitality demands in desert climates.
- Double-Decker Coaches:Composite aluminum body structures maximize passenger density per axle for Alpine and Nordic touring routes. Swiss and Austrian operators specify these for panoramic glazing on mountain corridors where per-passenger operating economics determine fleet viability. Euro VI Stage V mandates compress replacement cycles for aging diesel double-deckers in German charter fleets.
- Articulated Coaches:Extended wheelbase configurations with dual-axle steering systems serve high-volume airport transfer contracts. Demand concentrates in Saudi Arabia where NEOM and Red Sea Global developments require 60+ passenger capacity for staff logistics. Chassis supply bottlenecks from integrated European manufacturers constrain order fulfillment timelines.
- Mini Coaches:Sub-nine-meter configurations with premium interior fit-outs serve executive shuttle contracts in urban zero-emission zones.
- Standard Coaches:Twelve-meter single-deck platforms remain the default specification for mid-market charter operators.
- Convertible Coaches:Open-top or partially retractable roof designs target hospitality and event segments in warm-climate tourism markets.
Double-decker configurations retain volume leadership; articulated coaches hold the steepest expansion curve.
Technology:
Cost tier stratification separates established diesel platforms from capital-intensive hydrogen fuel cell development programs.
- Electric Drive:Liquid-cooled battery architectures with 400+ kWh pack capacities enable depot-based overnight charging for urban charter operators. California's Advanced Clean Trucks framework mandates zero-emission sales quotas that force Los Angeles and San Francisco fleet electrification ahead of charging infrastructure readiness. Battery thermal management specialization differentiates manufacturers competing for range consistency contracts.
- Hydrogen Fuel Cell:Proton-exchange membrane systems with 700-bar storage tanks target transcontinental touring corridors where battery weight compromises payload. Sparse H2 refueling networks across the Alpine region and Nordic routes stall adoption despite EU Green Deal funding eligibility. Fuel cell platforms share chassis architectures with battery-electric variants to hedge infrastructure uncertainty.
- Diesel Engine:Euro VI Stage V compliant powertrains concentrate in long-haul applications where charging infrastructure remains sparse.
- Hybrid Powertrain:Diesel-electric parallel systems offer transitional compliance for operators serving mixed urban and intercity routes.
- Autonomous Systems:Level 3+ highway pilot configurations face liability framework development under the EU AI Act.
Diesel engine platforms retain volume leadership; electric drive systems hold the steepest expansion curve.
Application:
Customer type concentration distinguishes volume-driven corporate contracts from margin-rich luxury experiential segments.
- Touring Services:Multi-day itinerary configurations with lie-flat seating and integrated galley systems serve premium European charter operators. Demand concentrates in Switzerland and Austria where panoramic glazing and weight-optimized composite bodies differentiate mountain route positioning. Euro VI mandates accelerate fleet renewal timelines for diesel-dependent touring fleets.
- Luxury Travel:Bespoke interior specifications with dedicated cabin attendants and entertainment systems target ultra-high-net-worth individual purchasers. Saudi giga-project developments sustain procurement pipelines for sovereign wealth-backed hospitality investments in Riyadh and Dubai. Direct-to-fleet contracting displaces traditional dealer channels for large-volume buyers.
- Corporate Transportation:Standardized shuttle configurations serve employee mobility and executive transfer contracts.
- Airport Transfers:High-frequency rotation schedules prioritize reliability and rapid turnaround capacity.
- Charter Services:Flexible specification platforms accommodate seasonal demand variation and event-driven deployment.
Touring services retain volume leadership; luxury travel holds the steepest expansion curve.
End User:
Supply concentration among integrated chassis-body manufacturers shapes procurement leverage across buyer categories.
- VIP Transport Providers:UAE and Saudi Arabian operators centralize specification authority with sovereign wealth investment offices, standardizing interior configurations across hotel shuttle and corporate executive fleets. Direct manufacturer contracts bypass dealer networks to compress delivery windows for giga-project timelines. Fleet procurement patterns favor ultra-premium configurations with integrated climate and entertainment systems.
- Hospitality Groups:Integrated resort developments in the Red Sea and Qiddiya require dedicated staff and guest logistics capacity with 24-hour operational availability. Lie-flat seating and galley specifications anchor competitive positioning for luxury hospitality procurement. Aftermarket service obligations increasingly transfer to manufacturers under direct contracting arrangements.
- Travel Agencies:Tour packaging intermediaries negotiate seasonal fleet access with priority on cost-per-passenger metrics.
- Event Organizers:Temporary deployment contracts prioritize rapid configuration flexibility and geographic mobility.
- Rental Companies:Asset utilization optimization drives specification standardization across mixed-use fleet portfolios.
VIP transport providers retain volume leadership; hospitality groups hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium pricing power through sovereign wealth-backed giga-project procurement, while European operators absorb compliance costs from accelerated Euro VI Stage V replacement cycles without equivalent price recovery mechanisms.
United States
Charter operators serving Los Angeles and San Francisco face California's Advanced Clean Trucks framework mandating zero-emission sales quotas from 2024 model years. EPA heavy-duty emissions standards and NHTSA fuel economy regulations tighten certification timelines for imported powertrains. Fleet electrification concentrates in depot-based charging partnerships across the Pacific Northwest corridor.
Germany
Alpine touring routes drive demand for weight-optimized composite body structures with panoramic glazing configurations. KBA enforces Euro VI Stage V compliance deadlines that compress diesel fleet replacement cycles. Manufacturing clusters in Bavaria and Baden-Württemberg anchor integrated chassis-body production for twelve-meter-plus configurations.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya developments sustain multi-year procurement programs for ultra-premium touring configurations with lie-flat seating. SFDA and sovereign wealth investment offices centralize specification authority across hotel shuttle and corporate executive fleets. Riyadh-based VIP transport providers bypass dealer networks for direct manufacturer contracts.
Switzerland
Mountain corridor operators prioritize carbon-fiber-reinforced adhesive-bonded bodies for weight reduction on high-altitude routes. Swissmedic and federal transport authorities coordinate zero-emission zone mandates affecting urban departure points. Zurich and Geneva charter companies electrify depot capacity ahead of transalpine infrastructure readiness.
United Arab Emirates
Dubai and Abu Dhabi hospitality groups require dedicated staff logistics capacity with 24-hour operational availability for integrated resort developments. MOHAP and sovereign wealth offices standardize interior configurations across corporate executive fleets. Direct-to-fleet contracting displaces traditional dealer channels for large-volume buyers in the Emirates.
Luxury Coaches Market Key Industry Players
Integrated chassis-body manufacturers and specialized interior configurators split the market between scale efficiency and bespoke differentiation. The vendor base concentrates around three European suppliers controlling aluminum composite body production for configurations exceeding twelve meters. Two strategic archetypes dominate: vertically integrated chassis-body builders capturing premium positioning through manufacturing control, and atelier-style specialists commanding margin through bespoke interior craftsmanship. Competitive moves center on direct-to-fleet contracting absorption of aftermarket obligations and modular platform development spanning battery-electric and hydrogen fuel cell architectures.
Within the integrated manufacturing tier, Prevost anchors North American charter segment positioning through captive chassis production. Marathon Coach and Newell Coach exemplify the atelier archetype, with the former representing bespoke interior specialization for ultra-high-net-worth purchasers and the latter occupying a position tied to in-house battery thermal management development. These three entities collectively illustrate the market's bifurcation between scale-driven manufacturing efficiency and craftsmanship-based premium differentiation.
| Leading Market Players |
|---|
| American Coach |
| Renegade RV |
| Prevost |
| Winnebago Industries |
| Newmar |
| Newell Coach |
| Marathon Coach |
| Thor Motor Coach |
| Entegra Coach |
| Others |
Cost & Logistics Intelligence
European integrated chassis-body manufacturers in Germany and the Czech Republic anchor aluminum composite supply for twelve-meter-plus configurations, concentrating margin capture downstream with sovereign wealth-backed hospitality buyers in Saudi Arabia and the UAE who bypass dealer networks entirely.
Pricing Analysis
Configured-to-order premiums for bespoke interior specifications command spreads exceeding standard fleet pricing by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels segments buyers by customization depth and after-sales service bundling. Price differentiation hinges on certification grade for Euro VI Stage V compliance and volume scale in direct manufacturer contracts. Pricing pressure stems from chassis supply bottlenecks as integrated European suppliers constrain fulfillment timelines for large-volume Middle Eastern orders. Corporate shuttle operators exhibit highest price sensitivity, while sovereign wealth-backed hospitality groups absorb premiums for accelerated delivery.
Supply Chain Analysis
Export-control regimes on carbon-fiber-reinforced composite technologies limit adhesive-bonding equipment flows to non-European manufacturing sites. Supply concentrates in Germany, the Czech Republic, and Switzerland for integrated chassis-body production. Raw material dependencies span aluminum sheet from Norwegian smelters, carbon fiber from Japanese and German suppliers, and lithium-ion cells from South Korean producers. Single-source vulnerability concentrates in bonded panel repair certification, where specialized technician training outpaces vocational program output. Distribution runs through direct-to-fleet contracting for large-volume buyers, displacing traditional dealer networks in Middle Eastern procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from rail and air mobility alternatives as infrastructure improves and emissions pricing shifts modal economics. The core threat is compressed-route electrification and urban zero-emission mandates eroding the coach's cost advantage on intercity corridors.
For Market Incumbents: Build captive chassis-body integration moats through backward integration into aluminum composite manufacturing. Absorb aftermarket service obligations under direct contracting arrangements to lock in sovereign wealth-backed hospitality accounts. Defend against hydrogen fuel cell entrants by accelerating battery thermal management specialization for range consistency across Alpine and desert temperature extremes.
For New Entrants and Emerging Players: Establish a beachhead in mini-coach electric configurations for European urban zero-emission zones where charging infrastructure investment lags fleet mandates. Target Swiss and Austrian mountain corridor operators with carbon-fiber-reinforced adhesive-bonded body alternatives to incumbent riveted aluminum platforms. Lead with depot-based fast-charging infrastructure partnerships as the go-to-market wedge.
For Investors and Strategic Acquirers: Capital is best deployed toward atelier-style configurators with bespoke interior craftsmanship capabilities and established sovereign wealth relationships. Long-term viability rests on manufacturers who control both platform flexibility for dual powertrain architectures and direct-to-fleet contracting scale. Watch hydrogen refueling network buildout pace across Alpine corridors as the inflection signal for fuel cell platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Fleet Contracting | Bypasses dealer margin extraction and compresses delivery windows for Saudi giga-project timelines. |
| Modular Powertrain Platform | Shares chassis architectures between battery-electric and hydrogen fuel cell to hedge infrastructure uncertainty. |
| Composite Body Repair Certification | Addresses technician training gaps in Germany and Czech Republic that constrain service network expansion. |
| Battery Thermal Management Investment | Differentiates range consistency for fleet operators across Alpine winter and Middle Eastern summer extremes. |
| Autonomous Highway Pilot Integration | Enables Level 3+ liability frameworks under EU AI Act for reduced driver fatigue on overnight touring routes. |
Research Approach
A spread of perspectives from fleet procurement directors at sovereign wealth hospitality groups, integrated chassis-body manufacturing engineers, bonded panel repair technicians, and European regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from Euro VI Stage V certification databases, KBA type-approval records, Saudi SFDA transport specifications, and UAE MOHAP fleet registration data. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Demand-supply balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product configuration, powertrain architecture, application type, and end-user procurement authority. CAGRs derived from replacement cycle analysis for Euro VI mandates and sovereign wealth capital deployment schedules. Industry-specific inputs incorporated hydrogen refueling station deployment trajectories and bonded composite technician training program graduation rates.
Sensitivities concentrate around hydrogen infrastructure buildout pace and California Advanced Clean Trucks compliance timelines. Forecasts reflect assumptions on regulatory enforcement intensity and sovereign wealth project completion schedules. Material shifts in EU Green Deal funding allocation or Saudi giga-project scope revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Hydrogen Buses Market
Buses
Bus Chassis Market
Buses
Intercity Bus Travel Market
Buses
Intelligent Bus Shelter Market
Buses
Buses & Coaches Market
Buses
Electric Intercity Bus Market
Buses
Africa Electric Bus Market
Buses
Bus Bellows Market
Buses
Canada School Bus Market
Buses
School Bus Market
Buses
Airport Bus Market
Buses
United States Electric Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Europe Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Seat Market