
 Canada School Bus Market | 2026-2036
Canada School Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Canada School Bus Market Outlook
The buyer base for Canadian school bus procurement is broadening beyond traditional public school districts to encompass charter operators and third-party transport services. Blue Bird Corporation leverages its established dealer network to sustain dominance in conventional diesel segments across prairie provinces. Lion Electric Co anchors the electric subsegment with in-house battery manufacturing and Quebec-based assembly capacity.
A school bus is a purpose-built motor vehicle designed to transport students, typically featuring reinforced side-impact protection, flashing signal lamps, and stop-sign arms integrated into a body-on-frame or integrated chassis architecture. Canadian specifications require compliance with CMVSS 220 rollover structural integrity standards and CMVSS 221 school bus body joint strength criteria, ensuring occupant protection during daily routes. Electric bus type is capturing the fastest expansion as provincial fleets pursue decarbonization targets, while diesel fuel type retains the largest installed base despite regulatory pressure. Standard size configurations concentrate procurement volume, though mini buses serve growing demand from rural districts with lower ridership density.
Health Canada and Transport Canada jointly shape vehicle safety mandates through the Canada Motor Vehicle Safety Standards, while provincial ministries of education control fleet replacement budgets and contracting rules. The federal Zero Emission Transit Fund directly influences procurement timing by offsetting capital costs for electric school bus acquisitions. Stakeholders must track how provincial ZEV mandates and utility rate structures interact to determine total cost of ownership parity across fuel technologies.
Market Dynamics
Zero-emission mandates from Transport Canada and provincial education ministries are compressing diesel replacement cycles while expanding the addressable market for electric powertrains across Ontario, Quebec, and British Columbia.
Growth Catalysts
- CMVSS 220 rollover standards:Federal structural integrity requirements drive fleet-wide replacement of pre-2007 vehicles, accelerating procurement volume across all fuel types.
- Zero Emission Transit Fund:Federal capital cost offsets reduce electric bus acquisition premiums, pulling forward adoption timelines for cash-constrained school districts.
- Quebec battery manufacturing:Domestic cell production capacity shortens lead times and insulates buyers from USD-denominated import volatility.
Market Restraints
- Charging infrastructure capex:Rural districts in Saskatchewan and Manitoba face six-figure depot electrical upgrades without utility co-investment programs.
- Lithium carbonate price volatility:Battery pack input cost swings compress OEM margins and complicate multi-year fleet pricing contracts.
- CMVSS 221 joint strength testing:Prototype validation timelines for novel composite body materials extend type-approval cycles by 8-14 months.
Strategic Opportunities
- Northern Ontario rural routes:Mini-bus configurations with 200km winter-range capability remain underpenetrated relative to urban standard-size saturation.
- Vehicle-to-grid integration:Bidirectional charging contracts with provincial utilities create new revenue streams offsetting idle-asset depreciation.
- Third-party transport operators:Charter and special-needs service providers currently source from fragmented used-bus markets, presenting greenfield fleet sales potential.
Industry Challenges
- HV technician certification:High-voltage maintenance training lags electric fleet deployment, forcing reliance on OEM service networks with 72-hour response windows.
- Depot electrical permitting:Municipal approval timelines for 480V three-phase infrastructure vary 4-11 months across Ontario municipalities, stalling commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada School Bus Market |
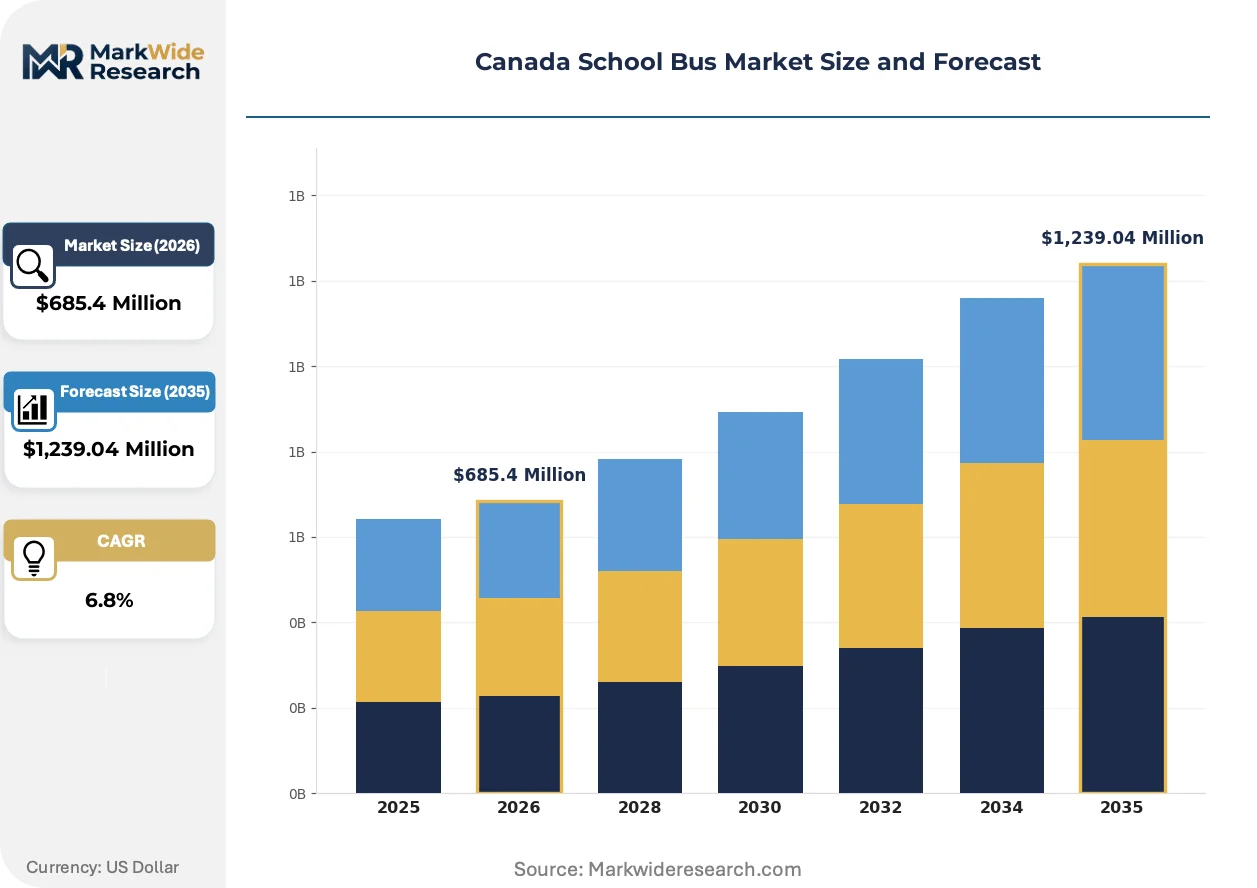
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Conventional, Transit, Special Needs, Electric Fuel Type: Diesel, CNG, Propane, Hybrid Size: Standard, Mini, Large, Over-sized End User: Public Schools, Private Schools, Charter Schools, Transport Services |
| Companies Covered | Blue Bird Corporation, Lion Electric Co, Thomas Built Buses Inc., Navistar International, REV Group, Von-Con Inc., Girardin Blue Bird, Student Transportation of America, Groupe-Gaudreault Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada School Bus Market Strategic Shifts
Battery-electric powertrains are compressing total cost of ownership calculations while reshaping buyer-supplier relationships around energy management rather than vehicle hardware alone.
Silicon carbide inverters are electrifying motor control efficiency in sub-150kWh battery packs. Prairie school districts with 80-120km daily routes are adopting these configurations to eliminate midday charging infrastructure. The technology is electrifying procurement criteria, displacing range anxiety as the primary evaluation metric in favor of energy consumption per kilometer.
Transport Canada's proposed amendments to CMVSS 108 lighting standards will mandate sequential LED activation patterns for stop-sign arms and crossing gates. The regulation compresses redesign cycles for body manufacturers while elevating electronics supplier influence in platform architecture. Ontario and British Columbia districts are accelerating pre-compliance orders to avoid 2027-2028 production bottlenecks.
Consolidated fleet management contracts are replacing discrete vehicle purchases. Third-party operators in Alberta now procure transportation-as-a-service bundles spanning vehicles, drivers, routing software, and energy costs. This restructuring concentrates buyer power with four provincial procurement consortiums, marginalizing small independent dealers in secondary markets.
Canada School Bus Market Segmentation
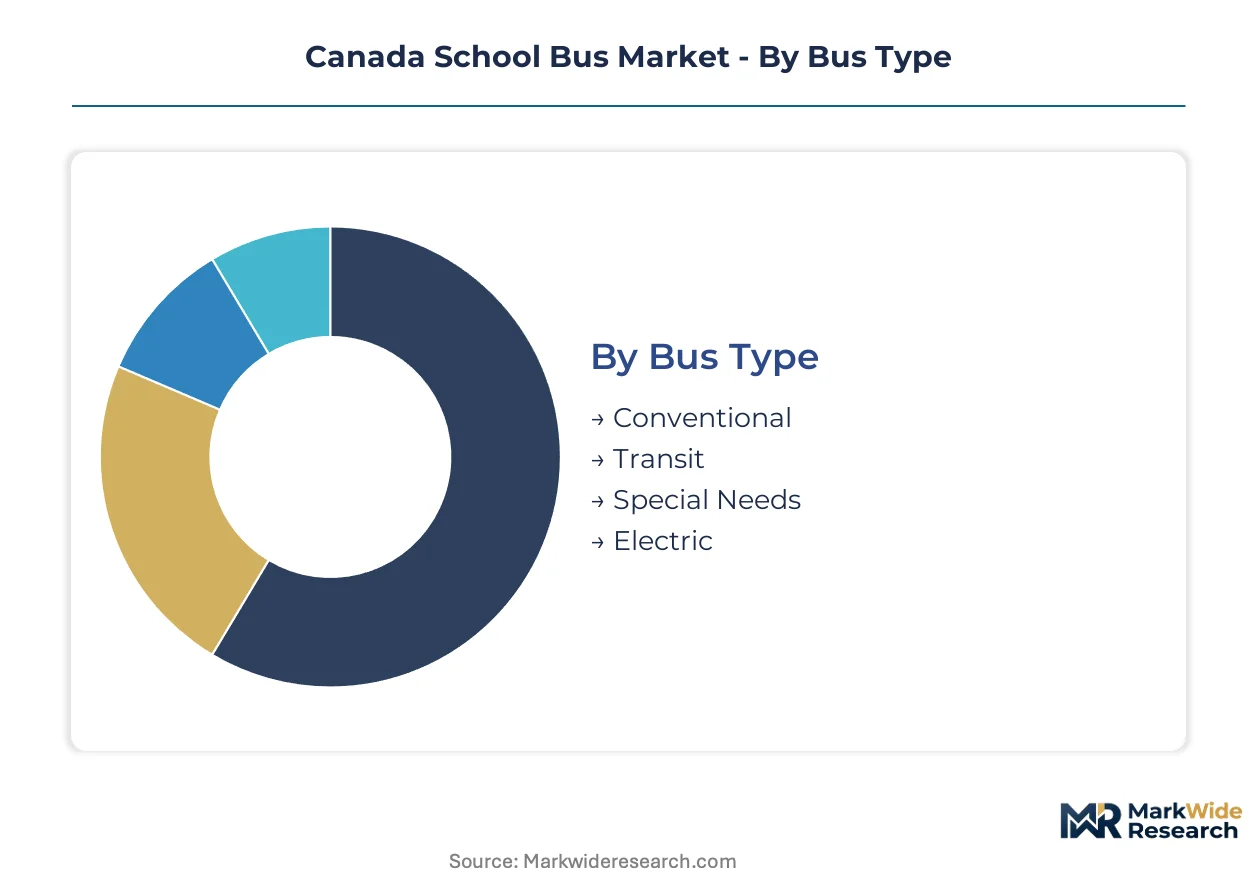
Segmentation in the Canadian school bus market reflects divergent procurement logics across fuel technologies, vehicle specifications, and contracting structures. Understanding these divisions clarifies how Transport Canada regulations and provincial education budgets allocate demand across distinct buyer categories.
Bus Type:
Bus type segmentation centers on chassis architecture and passenger accessibility design, determining which vehicles qualify for specific route classifications under CMVSS standards.
- Conventional:Body-on-frame construction with front-engine layout dominates prairie provinces where cold-weather reliability and established service networks outweigh efficiency considerations. Alberta and Saskatchewan districts favor this architecture for rural routes exceeding 100km daily.
- Electric:Integrated battery-electric platforms with regenerative braking systems anchor zero-emission procurement in Ontario and British Columbia. Transport Canada's Zero Emission Transit Fund eligibility criteria specifically reference this bus type, accelerating replacement timelines in Vancouver and Toronto metropolitan areas.
- Transit:Low-floor configurations with wheelchair ramps serve urban consolidated routes where accessibility mandates intersect with high-frequency scheduling demands.
- Special Needs:Lift-equipped variants with reinforced restraint anchoring systems address student transport requiring medical equipment accommodation or behavioral support protocols.
Mature deployment sits with Conventional configurations. Newer deployment is concentrated in Electric platforms.
Fuel Type:
Fuel segmentation tracks total cost of ownership calculations against infrastructure availability, with provincial utility rate structures heavily influencing adoption economics.
- Diesel:Compression-ignition engines with particulate filter aftertreatment retain the largest installed base despite federal decarbonization pressure. Remote districts in Manitoba and northern Ontario continue procurement where electric charging infrastructure remains economically unviable.
- CNG:Compressed natural gas systems with on-vehicle cylinder storage find limited application in Quebec where provincial gas utility incentives offset conversion costs for high-mileage urban fleets.
- Propane:LPG conversions with liquid fuel injection offer intermediate emissions reduction for districts lacking electrical infrastructure capacity but facing municipal clean air mandates.
- Hybrid:Diesel-electric parallel systems with stop-start functionality serve stop-and-go urban routes in Montreal where regenerative braking yields measurable fuel economy gains.
Propane and CNG adoption clusters in provinces with indigenous fuel production. Hybrid configurations are expanding most quickly in dense urban catchments.
Size:
Size classification determines route economics through passenger density matching, with CMVSS 220 rollover standards applying differential structural requirements across weight classes.
- Standard:72-84 passenger capacity with single rear axle serves the majority of Ontario and Quebec urban and suburban routes where ridership density justifies full-size procurement.
- Mini:16-30 passenger configurations with cutaway van chassis dominate rural British Columbia and Atlantic Canada districts where sparse population distribution and narrow road geometry constrain vehicle selection.
- Large:90+ passenger tandem axle designs address consolidated regional routes in Alberta where school consolidation policies extend transport distances.
- Over-sized:Articulated or extended-length variants remain rare, deployed exclusively for major event transport and temporary route surges.
Standard size captures procurement volume concentration. Mini configurations are gaining share fastest in declining-enrollment rural jurisdictions.
End User:
End user segmentation reveals shifting contracting authority from traditional district ownership toward diversified service delivery models.
- Public Schools:Provincial ministry-funded districts in Ontario and British Columbia control the majority of fleet replacement budgets, with procurement centralized through four major purchasing consortiums.
- Transport Services:Third-party operators providing contracted student transport represent the fastest-expanding buyer category, particularly in Alberta where transportation-as-a-service bundles now encompass vehicles, drivers, and routing software.
- Private Schools:Independent institutions with self-directed procurement typically source from dealer inventory rather than participating in consortium bidding cycles.
- Charter Schools:Alternative education providers with autonomous governance structures often lease vehicles or acquire used fleet assets, creating aftermarket demand distinct from new vehicle procurement patterns.
Public Schools retain procurement volume leadership. Transport Services represent the steepest expansion trajectory as provincial outsourcing policies accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial procurement budgets concentrate demand in Ontario and Quebec, where urban transit authorities and school districts drive fleet replacement cycles. Federal zero-emission incentives and Transport Canada safety mandates reshape investment patterns across sub-regional markets.
Ontario
Toronto and Ottawa metropolitan districts dominate electric bus procurement through consolidated purchasing consortiums. Transport Canada's Zero Emission Transit Fund eligibility criteria accelerate replacement timelines for diesel fleets exceeding fifteen years of service. The Greater Toronto Area anchors manufacturing partnerships between domestic assemblers and battery suppliers.
Quebec
Montreal's transit authorities prioritize integrated battery-electric platforms with regenerative braking for stop-and-go urban routes. The province's indigenous battery cell production capacity insulates procurement from currency volatility and shortens delivery lead times. Saint-Jérôme hosts Lion Electric Co's assembly operations serving Atlantic Canada and Ontario markets.
British Columbia
Vancouver school districts concentrate demand for mid-size electric models compliant with provincial zero-emission vehicle mandates. Health Canada and Transport Canada joint safety protocols govern fleet specifications for special-needs transport services. The Lower Mainland region experiences fastest adoption of vehicle-to-grid integration contracts with BC Hydro.
Alberta
Calgary and Edmonton charter operators expand transportation-as-a-service bundles encompassing vehicles, drivers, and energy management. Rural districts favor conventional body-on-frame configurations for routes exceeding 100km daily where charging infrastructure remains economically unviable. The province's procurement centralization marginalizes small independent dealers in secondary markets.
Atlantic Canada
Mini-bus configurations with cutaway van chassis dominate Nova Scotia and New Brunswick rural districts facing declining enrollment and narrow road geometry. Provincial education ministries control fragmented fleet replacement budgets without federal transit fund eligibility. Halifax anchors limited electric pilot programs constrained by depot electrical upgrade costs.
Canada School Bus Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrification specialization and service-based contracting models. The vendor base concentrates around three strategic archetypes: legacy chassis manufacturers with dealer network density, integrated electric platform specialists with captive battery supply, and third-party fleet operators consolidating transportation-as-a-service contracts. Competitive positioning hardens through provincial procurement consortiums and federal incentive eligibility criteria. Dominant moves include backward integration into battery cell production and geographic expansion through dealer acquisition in prairie provinces.
Within the integrated electric platform tier, Lion Electric Co exemplifies domestic manufacturing anchorage with Quebec-based assembly capacity. Blue Bird Corporation occupies a position representing legacy dealer network strength across conventional diesel segments. Thomas Built Buses Inc. and Navistar International sit within the established chassis manufacturer archetype serving rural route requirements. These entities collectively represent the competitive spectrum from electrification-first specialists to incumbent volume producers managing technology transition timelines.
| Leading Market Players |
|---|
| Blue Bird Corporation |
| Lion Electric Co |
| Thomas Built Buses Inc. |
| Navistar International |
| REV Group |
| Von-Con Inc. |
| Girardin Blue Bird |
| Student Transportation of America |
| Groupe-Gaudreault Inc. |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate volatility cascades through battery pack costs into tiered procurement contracts, compressing OEM margins while Transport Canada's Zero Emission Transit Fund offsets create price anchoring for electric bus buyers in Ontario and British Columbia.
Pricing Analysis
Volume procurement through provincial consortiums commands standard-tier pricing, while individual district purchases face premium markups reflecting dealer network fragmentation. Price differentiation hinges on CMVSS 220 certification tier and after-sales service bundling. Pricing pressure stems from Quebec-based battery cell production scaling, which undercuts import-dependent competitors. Rural districts in Saskatchewan and Manitoba exhibit highest price sensitivity due to depot infrastructure co-investment requirements.
Supply Chain Analysis
CMVSS 221 joint strength qualification gates entry for composite body materials, extending type-approval cycles and concentrating certified supplier relationships. Battery cell supply draws from South Korea, China, and domestic Quebec production facilities. Steel chassis components and silicon carbide inverters rest on Asian manufacturing concentration. Single-source vulnerability sits with lithium carbonate processing. Distribution runs through four provincial procurement consortiums marginalizing independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive battery manufacturing and in-house high-voltage service capacity determine margin capture across the electrification transition.
For Market Incumbents: Acquire high-voltage technician training infrastructure to reduce 72-hour OEM service dependency that erodes fleet uptime guarantees. Consolidate dealer networks in Alberta and Saskatchewan before transportation-as-a-service bundles eliminate independent channel margins. Battery cell backward integration represents the critical defensive lever against Quebec-based competitors. For New Entrants and Emerging Players: Capture Northern Ontario rural route contracts for mini-bus configurations with 200km winter-range capability, a segment where urban electric saturation has not penetrated. Target third-party charter operators currently sourcing from fragmented used-bus markets. Position through vehicle-to-grid integration partnerships with provincial utilities as the differentiated procurement criterion. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated electric platform specialists with captive battery supply in Quebec and established CMVSS certification pathways. Long-term viability centers on OEMs controlling upstream cell production and downstream service networks. Monitor provincial ZEV mandate acceleration and utility rate structure reforms as inflection signals for total cost of ownership parity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Quebec cell production capacity insulates OEMs from USD-denominated import volatility and shortens delivery lead times. |
| Backward Integration | In-house lithium carbonate processing secures margin control against commodity price swings compressing pack economics. |
| Charging Infrastructure Partnership | BC Hydro vehicle-to-grid contracts create revenue streams offsetting idle-asset depreciation for fleet operators. |
| Geographic Manufacturing Footprint | Saint-Jérôme assembly anchors Lion Electric Co's service response advantage across Ontario and Atlantic Canada. |
| Platform Standardization | Silicon carbide inverter adoption across sub-150kWh packs eliminates midday charging infrastructure for prairie districts. |
Study Parameters
Independent corroboration across fleet procurement directors, high-voltage maintenance technicians, and provincial ministry transportation officers underwrites the qualitative findings. Primary fieldwork encompassed school district operations managers, third-party charter service executives, and OEM platform engineering leads. Secondary validation drew from Transport Canada CMVSS amendment dockets, provincial education ministry budget disclosures, and utility rate filing documents. Bottom-up fleet replacement schedules triangulate against top-down federal incentive allocation models.
Comparable-period anchoring referenced historical diesel replacement cycles against electric adoption acceleration patterns across the projection horizon. Segmentation modeling spanned fuel technology, chassis architecture, size classification, and end-user contracting structure. CAGRs derived from unit volume trajectories weighted by provincial procurement consortium concentration. Forecast inputs incorporated battery pack cost curves and CMVSS regulatory compliance timelines.
The model holds under stable federal zero-emission incentive continuity and provincial education budget allocation; deviation in lithium carbonate price volatility or utility co-investment program suspension would shift replacement timeline assumptions. Forecasts reflect documented assumptions around infrastructure buildout rates and technician certification scaling. A model refresh is warranted upon material change in Transport Canada Motor Vehicle Safety Standards amendment schedules or provincial ZEV mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Bus Rental Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
School Bus Market
Buses
Europe Bus Market
Buses
Bus Charter Services Market
Buses
Airport Bus Market
Buses
Buses & Coaches Market
Buses
Canada Transit Buses Market
Buses
Luxury Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Seat Market
Buses
Africa Electric Bus Market
Buses
Europe Trolley Bus Market
Buses
Intelligent Bus Shelter Market
Buses
Trolley Bus Market
Buses
Hydrogen Buses Market