
 Bus Flooring Market | 2026-2036
Bus Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Flooring Market Outlook
The EU Green Deal's embodied carbon requirements for public procurement is broadening material specification scope across European transit authorities. Forbo Flooring Systems leverages integrated manufacturing to control substrate-to-surface supply chains. Gerflor anchors its position through specialized resilient flooring R&D for rolling stock and bus applications. Nora Systems differentiates via advanced rubber compound formulations that meet stringent fire-smoke-toxicity standards.
Bus flooring encompasses surface systems engineered for passenger vehicles, typically constructed from homogeneous or heterogeneous vinyl, vulcanized rubber, or fiber-reinforced composites with wear layers ranging from 0.3mm to 2.0mm, designed to withstand rolling loads, chemical exposure, and high-frequency foot traffic while maintaining slip resistance and acoustic dampening. Rubber formulations dominate structural demand in high-traffic urban transit where durability thresholds exceed fifteen years, while vinyl segments capture retrofit volume through lighter weight and faster installation cycles. Composite materials represent the fastest-growing structural category as electric bus platforms prioritize mass reduction to extend battery range.
EMA's MDR framework and ECHA REACH restrictions on SVHC substances directly constrain formulation chemistry and supplier qualification timelines for European bus flooring contracts. China's GB standards on interior material fire performance and volatile organic compound emissions create parallel compliance gateways for manufacturers serving state-owned transit operators. India's BIS certification mandates for automotive interior materials add another layer of market access conditioning. Stakeholders must monitor regulatory divergence between fire-safety-centric European frameworks and emissions-focused Asian standards when allocating product development resources.
Market Dynamics
Electric bus platform proliferation is compressing specification cycles as mass reduction targets force material substitution away from traditional rubber toward fiber-reinforced composites and engineered thermoplastics.
Growth Catalysts
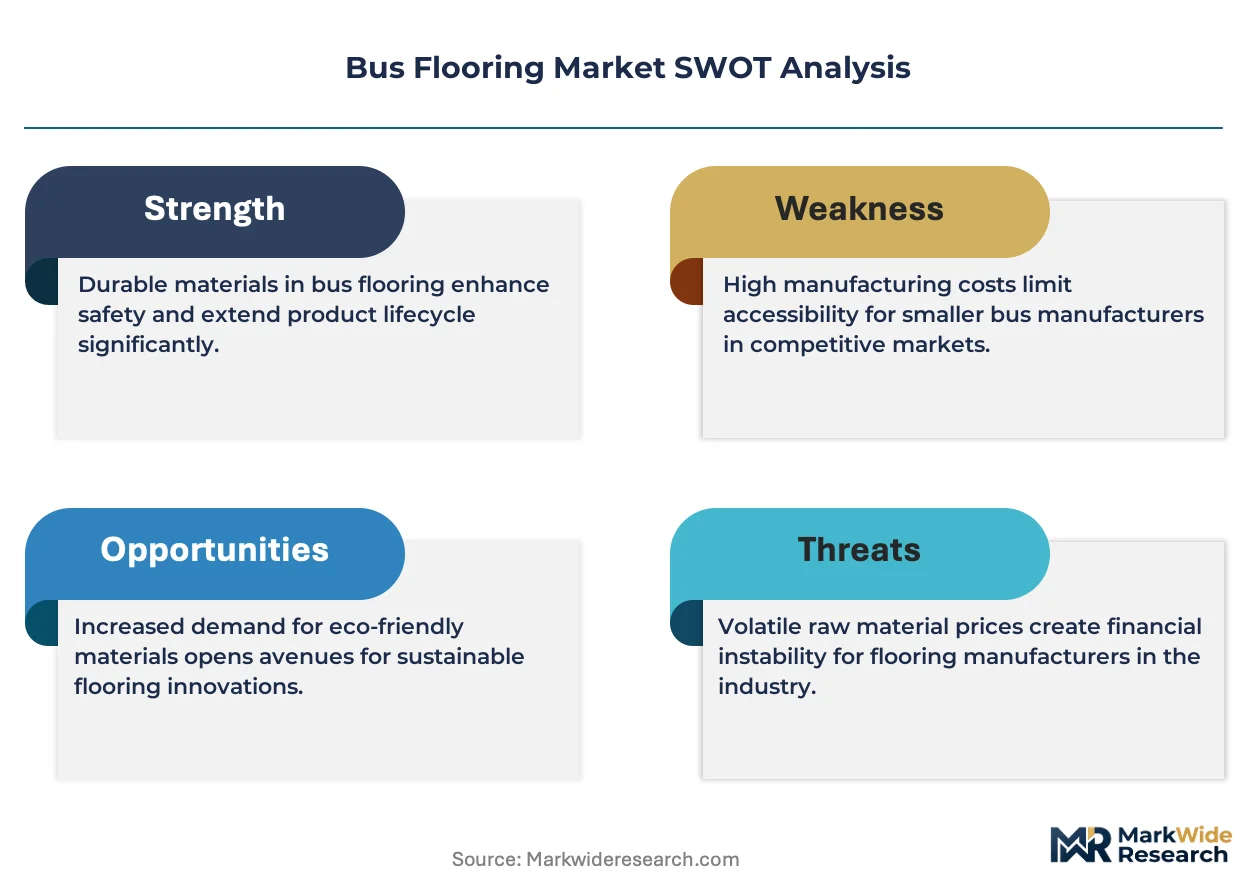
- EU Green Deal embodied carbon mandates:Public procurement across German, French, and Dutch transit authorities now requires lifecycle carbon disclosure, redirecting specifications toward low-emission substrate systems.
- China's provincial electric fleet conversions:State-owned operators in Guangdong, Jiangsu, and Shandong are retrofitting diesel fleets with battery-electric platforms that demand lighter flooring assemblies.
- ECHA REACH SVHC restrictions:Phthalate-free formulation requirements are disqualifying legacy suppliers and opening contract opportunities for compliant compound developers.
Market Restraints
- Petrochemical feedstock volatility:PVC and rubber compound costs fluctuate with crude oil derivatives, squeezing margin stability for formulation-dependent manufacturers.
- Supply concentration in East Asian substrate production:Glass fiber and specialty resin supply chains cluster around Chinese and South Korean chemical complexes, creating single-source vulnerability.
- Fire-smoke-toxicity certification bottlenecks:EN 45545-2 testing protocols for rail and bus applications extend qualification timelines by 8-14 months for new material entrants.
Strategic Opportunities
- Brazil municipal fleet renewal:São Paulo and Rio de Janeiro transit agencies are expanding tender volumes for urban bus refurbishment with modernized interior systems.
- Recyclable thermoplastic composite convergence:Polypropylene-based flooring with integrated wear layers enables closed-loop material recovery aligned with circular procurement criteria.
- India BIS certification pathway:Automotive interior material standards are tightening, creating first-mover advantage for suppliers achieving early compliance certification.
Industry Challenges
- Formulation chemist scarcity:Expertise in halogen-free flame retardant compounding is concentrated among a narrow cohort of European and Japanese specialists, constraining R&D bandwidth.
- Legacy fleet retrofit integration:Adhesive bonding systems for new lightweight materials often prove incompatible with existing bus floor substrates, requiring costly surface preparation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Flooring Market |
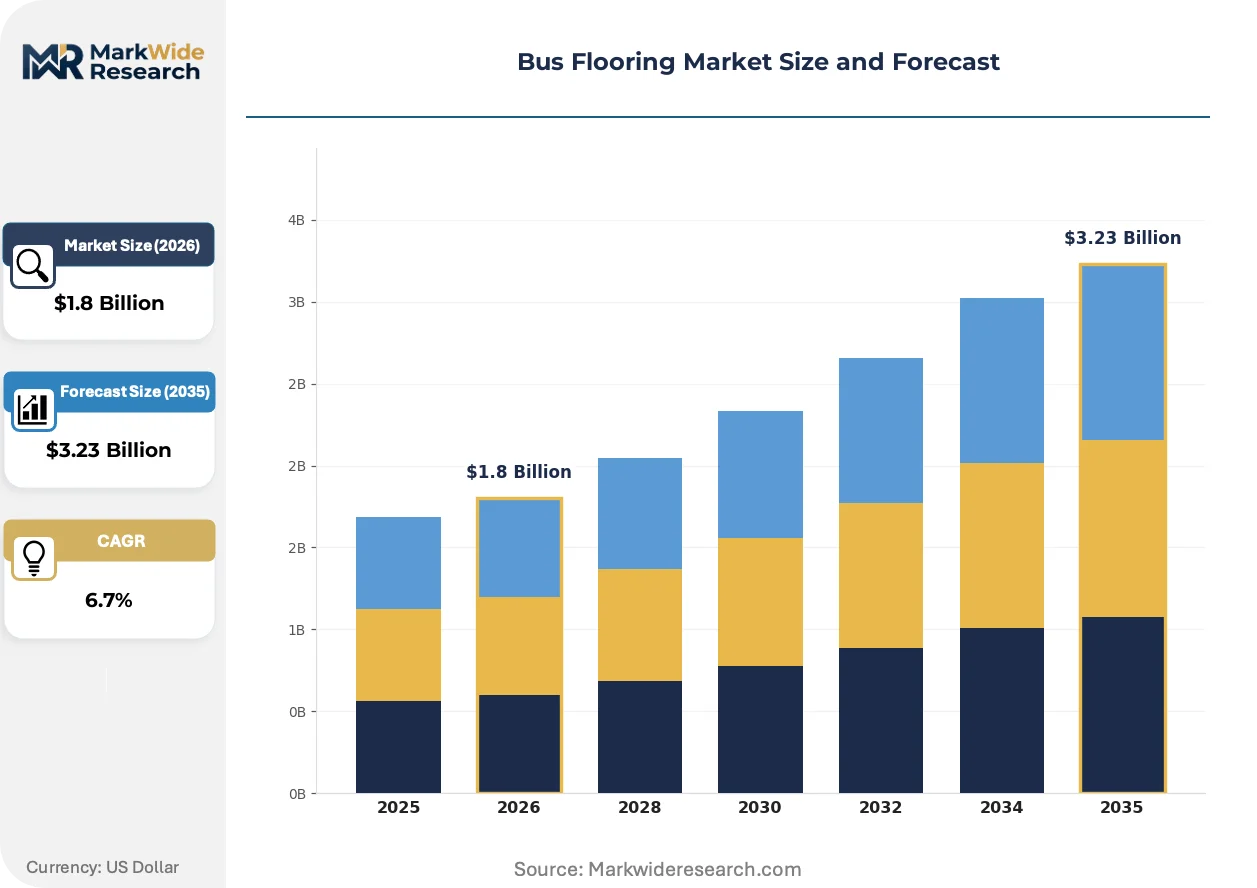
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, Vinyl, Carpet, Composite Application: Public Transit, Shuttle Services, School Buses, Tour Buses Installation Method: Glue Down, Loose Lay, Interlocking, Snap-in Thickness: 2mm, 4mm, 6mm, 8mm |
| Companies Covered | Forbo Flooring Systems, Gerflor, Wonderfloor, Ergis, Nora Systems, TKflor, Magnus Plywood, Wellknown Business Ventures, MarvelVinyls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Flooring Market Strategic Shifts
Material science advancement is compressing the performance gap between durability and weight, while regulatory chemistry constraints are forcing formulation reinvention across European and Asian supply bases.
Continuous fiber-reinforced thermoplastic (CFRTP) flooring systems are electrifying bus platform design by enabling 40-60% mass reduction versus vulcanized rubber alternatives. Chinese electric bus manufacturers BYD and Yutong have adopted these composites for battery range extension. CFRTP is electrifying supplier competition as traditional rubber compounders lose platform specification control to polymer composite specialists.
ECHA REACH Annex XIV authorization requirements for phthalate plasticizers are forcing PVC flooring reformulation across European transit supply chains. Manufacturers serving German KBA-registered bus builders must submit SVHC substitution plans by specified deadlines. Vinyl flooring segments are responding with bio-based plasticizer migration, though performance validation cycles lag regulatory compliance timelines.
Direct manufacturer-to-transit authority contracting is displacing traditional distributor networks for large fleet renewal programs. Municipal procurement departments in São Paulo and Mexico City now require technical specification workshops with flooring producers prior to tender submission. This pattern is most visible in Latin American markets where distributor technical capabilities failed to meet electric fleet modernization requirements.
Bus Flooring Market Segmentation
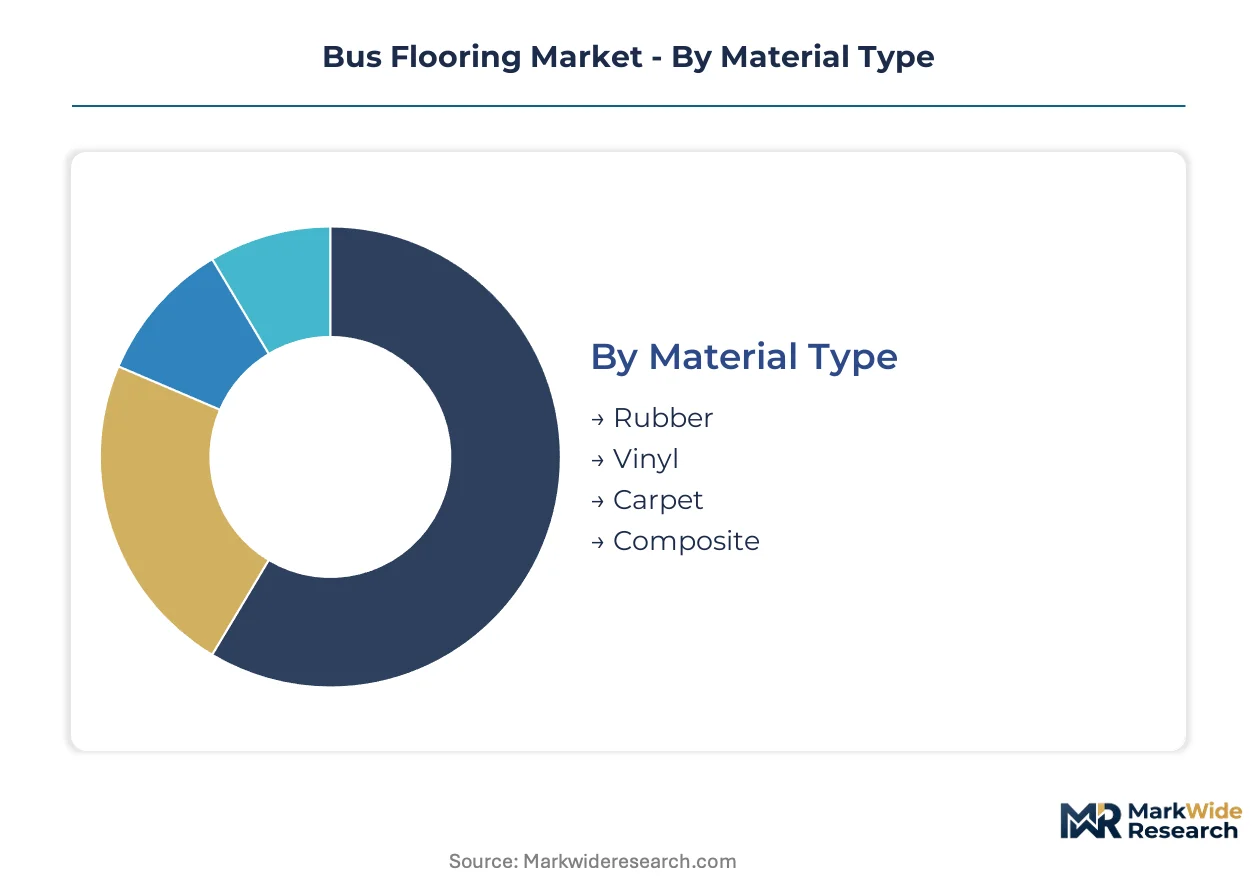
Bus flooring specifications diverge sharply across duty cycles, regulatory environments, and platform architectures. Material selection directly constrains vehicle weight, fire certification pathways, and lifecycle maintenance costs for fleet operators.
Material Type:
Cost tier separates specification behavior, with premium transit authorities funding durability investments while retrofit operators prioritize acquisition economics.
- Rubber:Vulcanized rubber compounds with dense wear layers deliver fifteen-plus year service life in high-traffic urban corridors. Demand concentrates in German and Brazilian municipal fleets where KBA and ANVISA fire-smoke-toxicity standards mandate proven formulations.
- Vinyl:Homogeneous and heterogeneous PVC constructions offer lighter weight and faster installation cycles for fleet refurbishment programs. China's provincial electric bus conversions favor vinyl for mass reduction targets, though ECHA REACH phthalate restrictions are forcing formulation reinvention across European supply chains.
- Carpet:Tufted or needle-punched textile surfaces dominate tour bus and premium intercity segments where acoustic comfort outweighs durability requirements.
- Composite:Fiber-reinforced thermoplastic systems enable 40-60% mass reduction versus rubber alternatives, climbing fastest as BYD and Yutong prioritize battery range extension.
Volume sits with rubber; growth tilts toward composite.
Application:
Volume scale distinguishes procurement patterns, with thousand-unit fleet operators commanding custom specifications versus fragmented small-fleet purchasing.
- Public Transit:Urban bus networks in São Paulo, Rio de Janeiro, and Guangdong specify heavy-duty rubber or composite systems for 300,000-plus annual passenger cycles. ECHA REACH compliance and EU Green Deal embodied carbon mandates are redirecting European transit authority specifications toward low-emission substrates.
- School Buses:North American yellow bus fleets prioritize slip resistance and chemical spill containment over extended wear life, with state-level procurement consortiums driving specification consolidation.
- Shuttle Services:Airport and corporate campus operators favor rapid-install vinyl or loose-lay systems for minimal vehicle downtime.
- Tour Buses:Long-distance coach operators in India and Mexico specify carpet or premium vinyl for passenger comfort differentiation on extended routes.
Public transit commands volume share; electric fleet conversions are expanding fastest.
Installation Method:
Customer technical capability determines method selection, with in-house maintenance teams favoring modular systems versus outsourced installation for permanent bonding.
- Glue Down:Permanent adhesive bonding delivers maximum durability and acoustic dampening for rubber and vinyl sheet goods in heavy-duty transit applications.
- Loose Lay:Friction-fit installation enables rapid replacement cycles for shuttle and tour operators prioritizing vehicle uptime.
- Interlocking:Mechanical connection systems allow segmented repair without full floor replacement, gaining traction in school bus refurbishment.
- Snap-in:Rigid panel systems designed for composite flooring integrate with electric bus platform substructures for precision fit and mass reduction.
Retrofit volume flows through glue down; new electric platform builds favor snap-in integration.
Thickness:
Maturity stage separates specification logic, with established markets standardizing on proven dimensions versus emerging markets experimenting with thinner profiles.
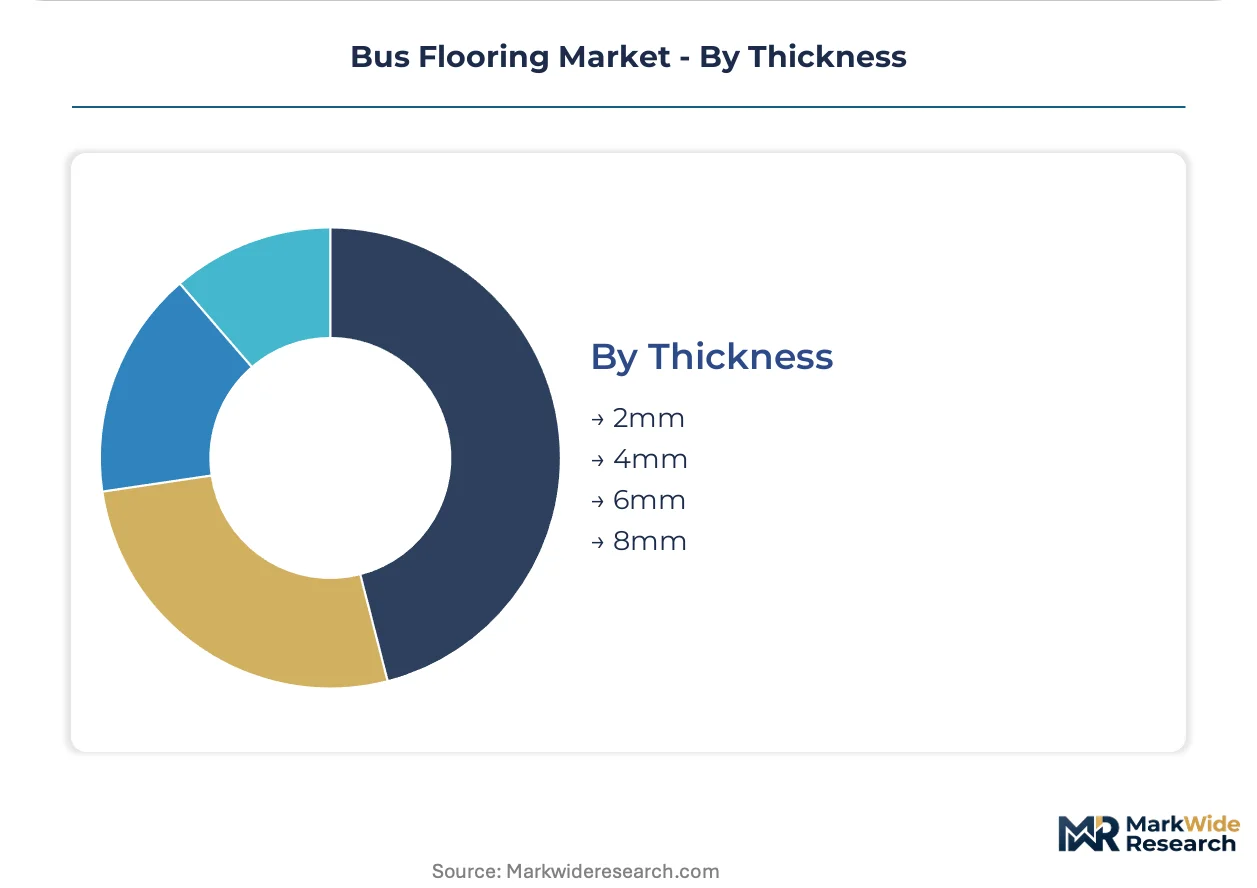
- 2mm:Ultra-thin vinyl and composite systems minimize weight and material cost for electric range optimization in Chinese battery-electric platforms.
- 4mm:Standard-duty vinyl and rubber constructions balance durability and weight for general transit and shuttle applications.
- 6mm:Heavy-duty rubber formulations with reinforced wear layers serve high-traffic urban corridors in Germany and Brazil.
- 8mm:Maximum-thickness rubber systems deliver extended lifecycle for rail-interoperable bus rapid transit corridors with rolling load requirements.
4mm and 6mm specifications anchor current procurement; 2mm composites are gaining share fastest in electric conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production capacity for composite substrates and vinyl compounds, while consumption spreads across municipal transit authorities in Germany, Brazil, and India's state-owned operators. This geographic split creates supply chain exposure for European and Latin American fleet operators dependent on East Asian material inputs.
Germany
KBA fire-smoke-toxicity standards and EU Green Deal embodied carbon mandates are redirecting procurement toward low-emission rubber and composite systems. ECHA REACH Annex XIV phthalate restrictions disqualify legacy PVC formulations from federal transit tenders. Munich and Berlin transit authorities now require lifecycle carbon disclosure for flooring contracts exceeding €500,000.
China
Provincial electric fleet conversions in Guangdong, Jiangsu, and Shandong drive demand for 2mm composite flooring to extend battery range. GB standards on interior material fire performance and VOC emissions gate market access for state-owned operators. BYD and Yutong manufacturing clusters in Shenzhen and Zhengzhou specify fiber-reinforced thermoplastic systems for new platform builds.
Brazil
São Paulo and Rio de Janeiro municipal agencies are expanding tender volumes for urban bus refurbishment with modernized interior systems. ANVISA fire-smoke-toxicity regulations align with European EN 45545-2 protocols, opening procurement to compliant international suppliers. Local assembly plants in São Paulo state integrate flooring systems during vehicle retrofit cycles.
India
State transport undertakings in Maharashtra, Karnataka, and Tamil Nadu are retrofitting diesel fleets with compressed natural gas and electric platforms. BIS certification mandates for automotive interior materials create compliance gateways for flooring suppliers. Delhi-NCR and Bengaluru municipal corporations prioritize rapid-install vinyl systems to minimize vehicle downtime during refurbishment.
United States
School bus fleet operators across Texas, California, and Florida prioritize slip resistance and chemical containment in state-level procurement consortiums. EPA and NHTSA safety standards influence material specification for yellow bus applications. Midwest manufacturing clusters supply interlocking and loose-lay systems to regional refurbishment contractors.
Bus Flooring Market Competitive Environment
The competitive structure tilts toward integrated compounders with captive substrate production and specialized resilient flooring developers with rail-certified product lineages. Tier-one positions cluster among European and Chinese manufacturers with vertical control over polymer compounding and wear-layer formulation. Three archetypes dominate: integrated chemical-to-surface manufacturers, specialized rolling-stock flooring developers, and regional retrofit distributors with installation service bundling. Capacity expansion and ECHA REACH-compliant formulation reinvention represent the dominant competitive moves across European supply bases.
Among integrated flooring specialists, Forbo Flooring Systems, Gerflor, and Nora Systems exemplify distinct strategic positions within the supplier hierarchy. Forbo represents the archetype of manufacturing integration spanning substrate-to-surface supply chain control. Gerflor occupies a position as a specialized resilient flooring developer with dedicated R&D bandwidth for rolling stock and bus applications. Nora Systems anchors the advanced rubber compound formulation segment, with fire-smoke-toxicity certification credentials that gate European transit authority procurement. These three entities collectively illustrate how regulatory chemistry constraints and electric platform mass reduction targets are reshaping competitive differentiation across the supplier landscape.
| Leading Market Players |
|---|
| Forbo Flooring Systems |
| Gerflor |
| Wonderfloor |
| Ergis |
| Nora Systems |
| TKflor |
| Magnus Plywood |
| Wellknown Business Ventures |
| MarvelVinyls |
| Others |
Value Chain & Pricing Dynamics
Crude oil derivative indices for PVC resin and synthetic rubber feedstocks cascade through three pricing tiers in bus flooring, compressing margins for compounders without captive polymer production while rewarding integrated manufacturers with cost pass-through stability. Procurement officers at German transit authorities and Chinese electric bus OEMs now index contract renewals to quarterly petrochemical benchmarks, forcing formulation-dependent suppliers into defensive hedging positions.
Pricing Analysis
Service-life guarantees anchor value-based pricing, with fifteen-year durability commitments commanding substantial premiums over standard five-year performance assurances in municipal transit tenders. Certification grade—specifically EN 45545-2 HL3 fire-smoke-toxicity ratings—separates premium rubber formulations from economy vinyl alternatives, while volume scale discounts consolidate around thousand-unit fleet operators. Cost compression in mid-tier vinyl segments intensifies as ECHA REACH phthalate restrictions force reformulation investments, with retrofit operators exhibiting highest price sensitivity versus electric platform OEMs prioritizing mass reduction over acquisition cost.
Supply Chain Analysis
Specialized polymer compounding expertise concentrates in Germany, China, and South Korea, constraining formulation flexibility for manufacturers without regional technical partnerships. Glass fiber substrate and specialty thermoplastic resin inputs draw from Chinese chemical complexes around Shanghai and South Korean producers near Busan, creating single-source vulnerability for European and Latin American flooring assemblers. Tariff exposure on East Asian composite substrates threatens margin stability for Brazilian and Indian retrofit specialists. Distribution runs through direct manufacturer-to-transit authority contracting for large fleet programs, displacing traditional distributor networks in São Paulo and Mexico City procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH SVHC restrictions and EU Green Deal embodied carbon mandates erect formidable compliance barriers, entrenching first-mover advantages for compounders with certified low-emission formulations and disqualifying price-focused entrants lacking technical qualification bandwidth.
For Market Incumbents: Anchor platform specification control through backward integration into thermoplastic composite substrate production, securing supply certainty for BYD and Yutong electric bus programs. Deepen captive compounding capabilities in halogen-free flame retardant chemistry to defend against Japanese polymer specialists entering European transit tenders. Prioritize certification maintenance investments as EN 45545-2 testing protocol extensions threaten qualification timelines for legacy product lines. For New Entrants and Emerging Players: E-commerce-enabled technical specification platforms offer low-friction entry into fragmented Latin American retrofit markets where distributor technical capabilities lag electric fleet modernization requirements. Target São Paulo municipal refurbishment tenders with rapid-install loose-lay systems that minimize vehicle downtime during fleet conversion cycles. Pursue white-label partnerships with established composite substrate suppliers to bypass capital-intensive polymer compounding infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European rubber compounders with dormant EN 45545-2 certifications and underutilized calendaring capacity in Germany and France. Long-term viability hinges on electric bus platform penetration sustaining composite flooring demand growth through the next decade. Monitor phthalate-free plasticizer validation cycles as inflection indicator—suppliers achieving performance parity with bio-based alternatives before regulatory deadlines will capture specification lock-in across EU transit authorities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Substrate Production | Captive supply of fiber-reinforced thermoplastics secures margin control for BYD and Yutong platform specifications. |
| Halogen-Free Flame Retardant R&D Investment | Formulation chemistry leadership gates European transit authority procurement under ECHA REACH Annex XIV timelines. |
| Direct-to-Transit-Authority Technical Sales | Bypassing distributor networks captures São Paulo and Mexico City fleet renewal programs requiring specification workshops. |
| Recyclable Thermoplastic Composite Development | Closed-loop material recovery aligns with EU Green Deal circular procurement criteria for German municipal tenders. |
| BIS Certification Pre-Qualification | Early compliance with Indian automotive interior standards creates first-mover positioning in Maharashtra and Karnataka retrofit cycles. |
Study Parameters
Multi-period observation of electric bus platform deployment rates, municipal fleet renewal tender volumes, and polymer feedstock price movements anchored the trend analysis, supplemented by interviews with transit authority procurement directors, bus OEM platform engineers, flooring manufacturer R&D heads, and chemical compounder technical directors. Secondary validation drew from ECHA SVHC candidate list updates, EU Green Deal procurement guidance documents, Chinese GB standard revision notices, and customs trade data on vinyl and rubber compound flows. Bottom-up segment sizing triangulated against top-down fleet replacement forecasts across the analysis window.
Segment-weighting approaches modeled material type, application duty cycle, installation method, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from platform penetration curves for battery-electric buses, retrofit cycle frequencies, and formulation substitution rates under REACH restrictions. Industry-specific inputs included EN 45545-2 certification pipeline data, BIS approval timelines for Indian market entry, and provincial electric fleet conversion targets in Guangdong and Jiangsu.
The model holds under steady regulatory enforcement intensity and petrochemical feedstock accessibility; deviation in REACH authorization timelines or composite substrate trade restrictions would shift volume trajectories materially. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intercity Bus Travel Market
Buses
School Bus Market
Buses
Canada Transit Buses Market
Buses
Europe Bus Market
Buses
Luxury Coaches Market
Buses
Bus Transmission System Market
Buses
Buses & Coaches Market
Buses
Bus Seat Market
Buses
Canada School Bus Market
Buses
United States Electric Bus Market
Buses
Bus Rental Market
Buses
North America Bus Market
Buses
Hydrogen Buses Market
Buses
Africa Electric Bus Market
Buses
Solar Bus Market
Buses
Bus Chassis Market