
 Global Circulating Tumor Cells Market | 2026-2036
Global Circulating Tumor Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Circulating Tumor Cells Market Foresight
Oncology clinics is consolidating as the fastest-expanding end user channel for circulating tumor cell isolation systems. Thermo Fisher Scientific leverages its clinical diagnostics footprint to anchor instrument placement in hospital networks across North America and Europe. QIAGEN sustains competitive intensity through specialized sample preparation chemistries that integrate with third-party detection platforms.
Circulating tumor cells are rare malignant cells shed from primary or metastatic tumors into peripheral blood, typically isolated through immunomagnetic separation or microfluidic devices that exploit differential size, density, or dielectric properties. These cells enable non-invasive longitudinal monitoring of cancer progression and therapeutic response. Microfluidic devices command premium positioning due to higher capture efficiency and gentler cell handling, while immunomagnetic separation dominates installed base volume because of protocol familiarity and lower capital barriers. Size-based isolation is gaining traction in research settings where label-free recovery preserves downstream molecular integrity.
The FDA regulates circulating tumor cell assays as in vitro diagnostics under premarket notification or approval pathways, while the EMA's In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence standards for CE-marked products in Europe. China's NMPA has accelerated review timelines for innovative tumor profiling technologies under its priority review channels. Stakeholders must monitor how divergent validation requirements across FDA, EMA, and NMPA jurisdictions reshape go-to-market sequencing and portfolio prioritization.
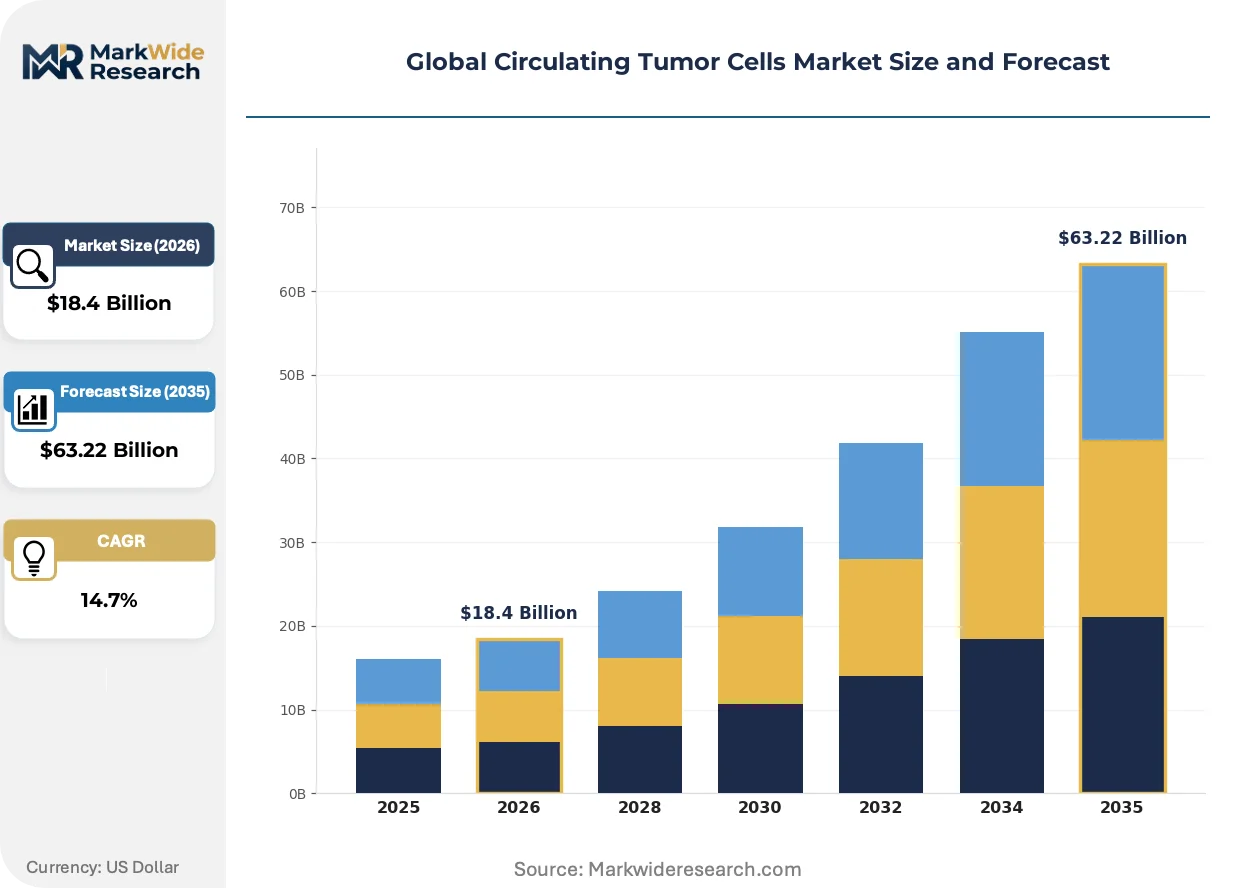
Market Dynamics
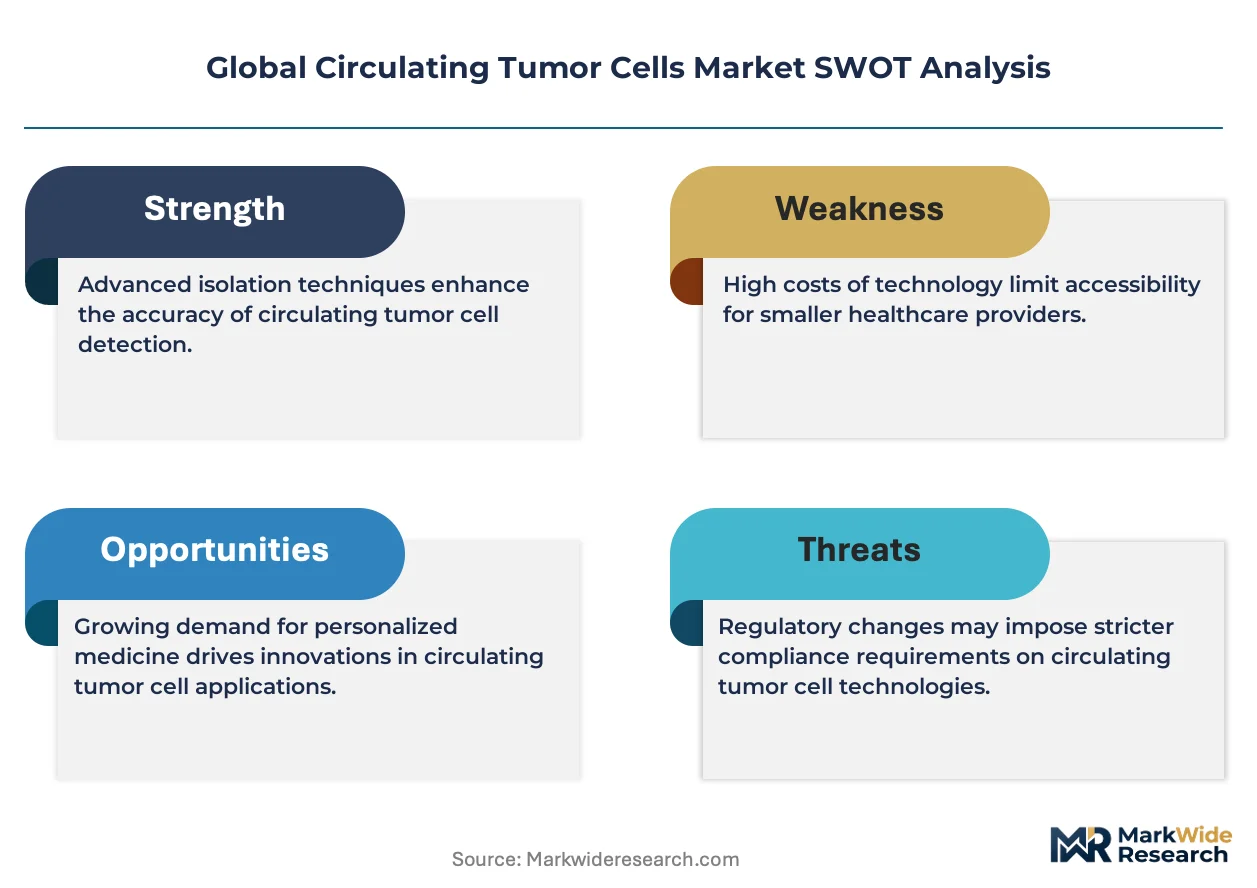
The FDA's companion diagnostics guidance and EMA's In Vitro Diagnostic Medical Devices Regulation are forcing parallel validation tracks that reshape product development timelines and geographic rollout sequencing for circulating tumor cell assay manufacturers.
Growth Catalysts
- Liquid biopsy protocol expansion:Oncology clinics in the United States, Germany, and China are embedding CTC isolation into standard treatment monitoring workflows, creating installed base pull-through for detection platforms.
- NMPA priority review channels:China's accelerated timelines for innovative tumor profiling technologies compress market entry delays for novel microfluidic capture devices.
- Precision medicine infrastructure scaling:Hospital networks are consolidating molecular diagnostics capabilities, concentrating procurement authority for high-throughput CTC enumeration systems.
Market Restraints
- Antibody reagent cost volatility:EpCAM and cytokeratin capture reagents face supply concentration among specialized biologics suppliers, squeezing gross margins on immunomagnetic separation consumables.
- EMA clinical evidence thresholds:The MDR's expanded performance study requirements extend CE-marking timelines and inflate regulatory affairs spending for European market entry.
- Digital PCR substitution threat:Cell-free DNA analysis platforms are capturing share in treatment monitoring applications where mutational burden suffices, limiting CTC addressable market expansion.
Strategic Opportunities
- Label-free isolation in research:Size-based microfluidic devices are penetrating academic and contract research settings where downstream single-cell sequencing demands intact RNA integrity.
- Brazil's diagnostic infrastructure buildout:ANVISA's streamlined registration pathways for oncology IVDs create first-mover positioning for platforms with existing FDA or CE marks.
- AI-assisted enumeration convergence:Machine learning image classification is integrating with fluorescence microscopy workflows to automate CTC scoring and reduce pathologist labor burden.
Industry Challenges
- Rare cell handling expertise scarcity:Clinical laboratories lack standardized training protocols for low-abundance sample processing, generating reproducibility failures that trigger assay rejection.
- Multi-jurisdiction validation synchronization:Divergent FDA, EMA, and NMPA evidentiary requirements force redundant clinical studies that strain development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Circulating Tumor Cells Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $63.22 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunomagnetic Separation, Microfluidic Devices, Size-based Isolation, Dielectrophoresis, Density Gradient Centrifugation Application: Early Cancer Detection, Treatment Monitoring, Prognosis, Drug Development, Personalized Medicine End User: Diagnostic Laboratories, Oncology Clinics, Research Institutes, Pharmaceutical Companies Technology: Fluorescence In Situ Hybridization, RT-PCR, Immunocytochemistry, Nucleic Acid Sequencing, Microfluidics |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Bio-Techne Corporation, Menarini Silicon Biosystems, Miltenyi Biotec, Greiner Bio-One International GmbH, Illumina, Inc., Precision Medicine Group, LLC, Ikonisys Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Circulating Tumor Cells Market Shifts & Advancements
Microfluidic engineering and computational pathology are converging to automate circulating tumor cell workflows that previously demanded specialized operator skill, compressing turnaround times and expanding test menu feasibility.
Microfluidic devices exploiting inertial focusing and deterministic lateral displacement are integrating gentle cell handling with high capture efficiency. Academic medical centers in the United States and Switzerland are adopting these platforms for longitudinal patient monitoring studies. The technology is integrating downstream single-cell omics capabilities that immunomagnetic methods compromise through harsh elution conditions.
The EMA's In Vitro Diagnostic Medical Devices Regulation is tightening clinical performance standards for CE-marked CTC enumeration kits. Manufacturers must now submit prospective studies demonstrating analytical validity across multiple cancer indications. European reference laboratories are responding by consolidating validation partnerships with platform developers to share evidence generation costs.
Hospital procurement committees are unbundling instrument placement from reagent supply contracts that previously locked laboratories into single-vendor ecosystems. Third-party assay developers in Germany and Japan are capitalizing on this flexibility to place compatible chemistries on installed microfluidic hardware. This shift is most visible in university hospital networks where pathology departments retain independent sourcing authority.
Global Circulating Tumor Cells Market Segmentation
CTC market segmentation reveals how isolation technologies, clinical applications, and end-user workflows fragment procurement patterns. Supply concentration in antibody reagents and microfluidic engineering creates divergent margin structures across product categories.
Product Type:
Supply concentration in EpCAM antibody production and microfluidic chip manufacturing shapes competitive positioning across isolation modalities.
- Immunomagnetic Separation:Antibody-coated magnetic beads capture EpCAM-expressing cells through external magnetic fields. Oncology clinics in the United States deploy these systems for routine enumeration where protocol familiarity outweighs capture efficiency limitations. Reagent cost volatility from concentrated biologics suppliers squeezes gross margins.
- Microfluidic Devices:Precision-engineered channels exploit inertial focusing and deterministic lateral displacement for label-free cell handling. Academic medical centers in Switzerland and the United States adopt these platforms for longitudinal studies requiring intact RNA integrity. Higher capital barriers limit penetration in cost-sensitive settings.
- Size-based Isolation:Membrane filtration and spiral microfluidics separate cells by physical dimensions without antibody dependency.
- Dielectrophoresis:Electric field gradients manipulate cells based on dielectric property differentials.
- Density Gradient Centrifugation:Centrifugal force stratifies blood components by buoyant density for crude enrichment.
Today's leader: Immunomagnetic Separation. Tomorrow's challenger: Microfluidic Devices.
Application:
Clinical utility varies by cancer stage and therapeutic decision point, concentrating revenue in monitoring workflows over screening.
- Early Cancer Detection:Screening asymptomatic populations for occult malignancy through blood-based sampling. Research institutes in Germany pilot these applications where sensitivity thresholds remain unresolved. Regulatory validation requirements for screening indications exceed therapeutic monitoring standards.
- Treatment Monitoring:Longitudinal enumeration tracks therapeutic response and residual disease during chemotherapy or immunotherapy. Oncology clinics embed these workflows into standard care protocols, creating recurring revenue streams. Serial sampling feasibility drives preference over tissue biopsy repetition.
- Prognosis:Baseline CTC counts correlate with progression-free survival across multiple solid tumor types.
- Drug Development:Pharmaceutical companies employ CTC enumeration as pharmacodynamic biomarkers in early-phase trials.
- Personalized Medicine:Single-cell molecular profiling guides targeted therapy selection based on emergent resistance mutations.
Treatment Monitoring commands current revenue concentration. Early Cancer Detection holds the steepest expansion trajectory pending sensitivity breakthroughs.
End User:
Procurement authority consolidation in hospital networks restructures vendor relationships across laboratory types.
- Diagnostic Laboratories:High-throughput reference labs process CTC enumeration as send-out or in-house developed tests. Centralized equipment placement serves multiple oncology practices. Volume economics favor immunomagnetic platforms with lower per-test consumable costs.
- Oncology Clinics:Point-of-care isolation integrates with same-day treatment decisions. Point-of-need microfluidic devices reduce sample transport degradation risks. Workflow integration demands drive preference for automated enumeration systems.
- Research Institutes:Academic laboratories prioritize label-free methods preserving downstream omics capabilities.
- Pharmaceutical Companies:Drug developers deploy CTC platforms across clinical trial sites for companion diagnostic validation.
Diagnostic Laboratories anchor installed base volume. Oncology Clinics are gaining share fastest through workflow integration mandates.
Technology:
Detection modality selection depends on analyte type—protein expression versus nucleic acid—required for clinical decision support.
- Fluorescence In Situ Hybridization:Chromogenic probes visualize genomic aberrations in isolated CTCs. Cytogenetic laboratories in China deploy FISH for HER2 amplification assessment guiding trastuzumab eligibility. Probe manufacturing concentration limits assay menu expansion speed.
- RT-PCR:Reverse transcription polymerase chain reaction quantifies expression of epithelial markers and tissue-specific transcripts. Reference laboratories favor this approach for standardized enumeration across multiple cancer types. RNA degradation sensitivity requires rapid sample processing post-isolation.
- Immunocytochemistry:Antibody-based staining confirms epithelial origin and excludes leukocyte contamination.
- Nucleic Acid Sequencing:Next-generation platforms enable mutational profiling of CTC-derived DNA for resistance monitoring.
- Microfluidics:Integrated lab-on-chip devices combine isolation with downstream molecular analysis in sealed cartridges.
RT-PCR dominates current test volume. Nucleic Acid Sequencing represents the fastest-climbing modality as targeted therapy portfolios expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision medicine infrastructure in the United States, Germany, and China anchors circulating tumor cell platform deployment. Oncology clinics in these markets embed liquid biopsy workflows into standard treatment monitoring. Regulatory pathways at the FDA, EMA, and NMPA reshape geographic rollout sequencing for assay manufacturers.
United States
Oncology clinics in the United States deploy immunomagnetic separation systems for routine CTC enumeration where protocol familiarity drives procurement decisions. The FDA's companion diagnostics guidance forces parallel validation tracks that extend product development timelines. Academic medical centers in Boston and Houston adopt microfluidic platforms for longitudinal patient monitoring studies requiring intact RNA integrity.
Germany
Hospital networks in Germany consolidate molecular diagnostics capabilities, concentrating procurement authority for high-throughput CTC enumeration systems. The EMA's In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence standards for CE-marked products, inflating regulatory affairs spending. Reference laboratories in Heidelberg and Munich partner with platform developers to share evidence generation costs for MDR compliance.
China
Oncology departments in China scale precision medicine infrastructure, creating installed base pull-through for detection platforms. The NMPA's priority review channels accelerate timelines for innovative tumor profiling technologies, compressing market entry delays. Research institutes in Shanghai and Beijing pilot early cancer detection applications where sensitivity thresholds remain under active investigation.
Switzerland
Academic medical centers in Switzerland prioritize label-free microfluidic methods preserving downstream single-cell sequencing capabilities. Swissmedic maintains alignment with EMA regulatory standards while offering streamlined pathways for breakthrough diagnostic technologies. The Basel and Zurich clusters concentrate contract research operations serving pharmaceutical developers deploying CTC enumeration as pharmacodynamic biomarkers.
Japan
Diagnostic laboratories in Japan favor RT-PCR approaches for standardized enumeration across multiple cancer types. The PMDA reviews circulating tumor cell assays under in vitro diagnostic pathways with emphasis on analytical validity demonstrations. Tokyo and Osaka hospital networks integrate automated enumeration systems to reduce pathologist labor burden in fluorescence microscopy workflows.
Global Circulating Tumor Cells Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to unbundle instrument placement from reagent supply contracts. The vendor base concentrates around diversified life sciences conglomerates and specialized sample preparation chemists. Three archetypes define competitive positioning: platform developers integrating microfluidic engineering, reagent specialists supplying capture antibodies and detection chemistries, and sequencing technology providers enabling downstream molecular profiling. Technology licensing and geographic expansion represent the dominant competitive moves as firms navigate divergent FDA, EMA, and NMPA validation requirements.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages its clinical diagnostics footprint to anchor instrument placement in hospital networks, while QIAGEN sustains competitive intensity through specialized sample preparation chemistries. Menarini Silicon Biosystems occupies a position exemplifying the microfluidic platform specialist archetype. These three entities represent distinct strategic postures: one emphasizing installed base scale, another prioritizing reagent compatibility across third-party hardware, and the third concentrating on premium capture efficiency for research-intensive settings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Bio-Techne Corporation |
| Menarini Silicon Biosystems |
| Miltenyi Biotec |
| Greiner Bio-One International GmbH |
| Illumina, Inc. |
| Precision Medicine Group, LLC |
| Ikonisys Inc. |
| Others |
Supply & Pricing Matrix
Capture efficiency divergence between microfluidic precision platforms and immunomagnetic commodity systems manifests in divergent margin structures and supply chain configurations across the circulating tumor cell market. Premium positioning rests on proprietary chip engineering and antibody reagent quality grades, while cost-sensitive oncology clinics in the United States and China drive volume through standardized consumables.
Pricing Analysis
Antibody reagent cost pass-through from concentrated EpCAM and cytokeratin suppliers squeezes gross margins on immunomagnetic separation consumables. Three-tier pricing structure across premium microfluidic systems, standard immunomagnetic platforms, and economy-size filtration devices reflects certification grade and downstream omics compatibility. Pricing pressure stems from digital PCR substitution in treatment monitoring applications where mutational burden suffices. Hospital networks exhibit lowest price sensitivity for integrated workflow systems; independent diagnostic laboratories face tightest budget constraints.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States maintain hub-and-spoke patterns for temperature-sensitive antibody reagents and precision-engineered microfluidic chips. Manufacturing concentrates in Germany for immunomagnetic bead production and Switzerland for microfluidic device fabrication, with China scaling domestic chip foundry capacity. Single-source vulnerability pervades specialized biologics suppliers for capture antibodies. Distribution runs through hospital procurement committees consolidating molecular diagnostics authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The circulating tumor cell market compounds regulatory complexity as the FDA's companion diagnostics guidance and EMA's MDR reshape validation requirements, creating sustained demand for compliant platform developers.
For Market Incumbents: Extend platform compatibility through third-party assay integration as hospital procurement committees unbundle instrument placement from reagent contracts. Deepen backward integration into antibody reagent production to defend margins against biologics supplier concentration. Prioritize NMPA priority review channel qualification to capture China's accelerated market entry timelines. For New Entrants and Emerging Players: Enter via Brazil's ANVISA streamlined registration pathways for oncology IVDs, leveraging existing FDA or CE marks for first-mover positioning. Target academic medical centers in Switzerland and the United States where label-free microfluidic methods command premium adoption. Pursue AI-assisted enumeration partnerships to automate CTC scoring and reduce pathologist labor burden. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction validation capabilities separate viable platform developers from stranded reagent specialists. Five-to-ten-year viability favors microfluidic platform specialists with intact downstream omics integration and established European MDR compliance partnerships. Watch NMPA approval velocity for innovative tumor profiling technologies as inflection indicator for geographic demand shift.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Partnership | European reference laboratories share evidence generation costs with platform developers for CE marking. |
| AI-Assisted Enumeration Integration | Machine learning image classification automates CTC scoring in fluorescence microscopy workflows. |
| NMPA Priority Review Qualification | Accelerated timelines compress market entry delays for novel microfluidic capture devices in China. |
| Third-Party Assay Compatibility | Unbundled procurement enables independent chemistry placement on installed microfluidic hardware. |
| Label-Free Method Development | Size-based isolation preserves RNA integrity for downstream single-cell sequencing applications. |
Research Methodology
Bottom-up oncology clinic modeling reconciled against top-down instrument placement tracking forms the analytical core of this study. Primary interviews with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers were combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Cross-referencing bottom-up enumeration demand with top-down platform shipment data ensures triangulation integrity.
Historical trendline analysis across installed base expansion and reagent consumption patterns informed the projection framework. Segmentation dimensions modeled include isolation technology type, clinical application, end-user laboratory category, and detection modality across the projection horizon. CAGRs were derived from regression analysis of technology adoption curves and regulatory approval velocity. Forecast inputs incorporate NMPA review timeline compression and EMA MDR evidence threshold inflation.
Inputs from clinical laboratory directors and regulatory affairs specialists were available through the study window; gaps in real-time hospital procurement contract terms introduce uncertainty bands around instrument placement forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market