
 Wi-Fi Adapter Card Market | 2026-2036
Wi-Fi Adapter Card Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Adapter Card Market Analysis
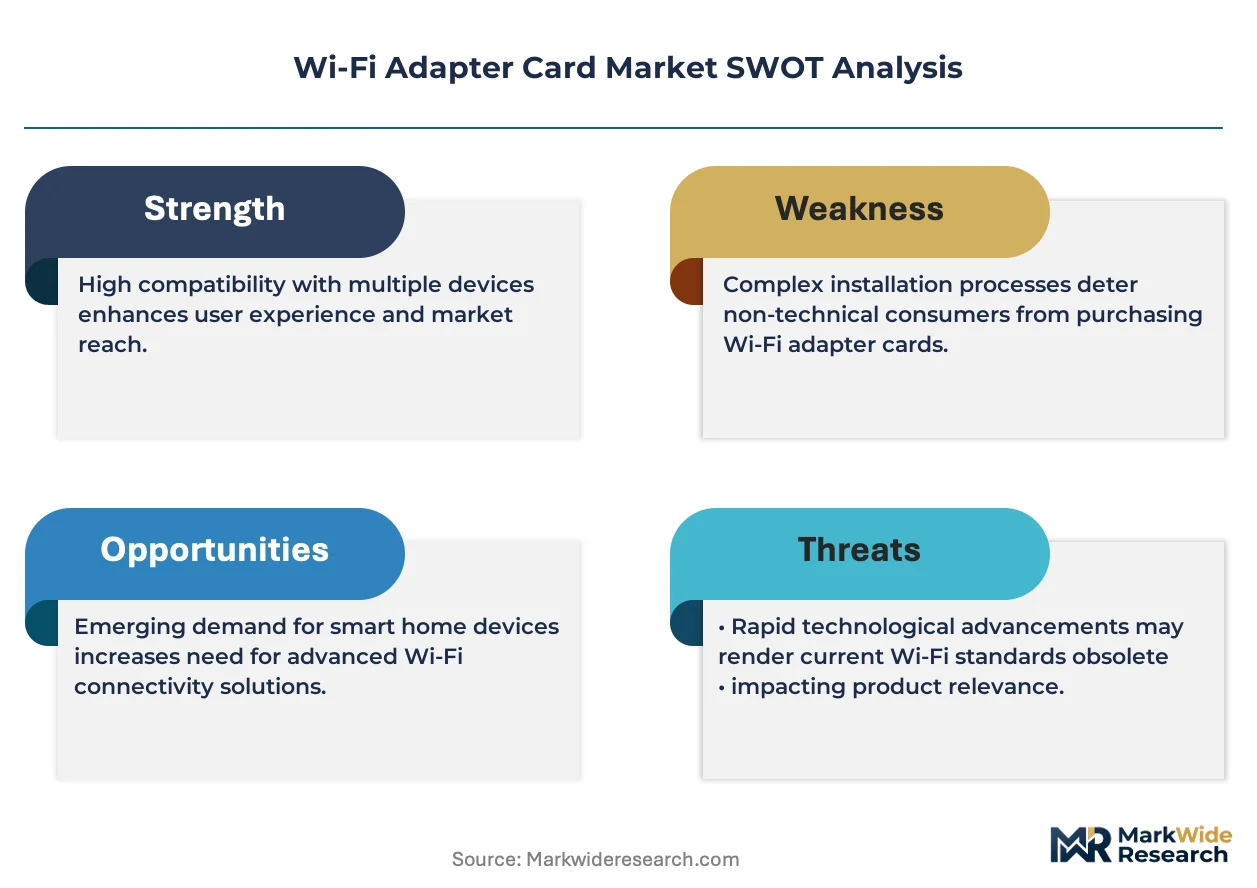
Enterprise networking buyers is unwinding the consumer-heavy demand mix that dominated prior Wi-Fi adapter cycles. TP-Link Technologies Co., Ltd. leverages its channel depth across Asian distribution networks to capture volume in small and medium business segments. Intel Corporation anchors the premium tier through integrated M.2 module designs that ship with enterprise motherboard bundles. Qualcomm Technologies, Inc differentiates via tri-band radio architectures that target high-density wireless environments.
A Wi-Fi adapter card is a network interface expansion device that installs into PCIe slots, M.2 connectors, or USB ports to add wireless connectivity to computing systems, typically supporting 2.4 GHz and 5 GHz bands with throughput rates from 300 Mbps to over 9.6 Gbps under Wi-Fi 6E standards. These cards serve industrial and commercial purposes by enabling desktop workstations, servers, and embedded systems to access wireless LANs without native onboard radios. M.2 modules now lead product type shipments due to space constraints in compact enterprise desktops and edge servers. Wi-Fi 6 technology segments show the fastest upgrade momentum as organizations retire 802.11ac infrastructure. Gaming systems applications command elevated average prices through dual-band and tri-band configurations with external antenna arrays.
The FCC in the United States governs unlicensed spectrum access including 6 GHz band certification for Wi-Fi 6E devices, while ETSI in Europe enforces harmonized radio equipment directives that shape product compliance timelines. China's MIIT manages type approval for wireless LAN equipment, creating distinct certification pathways that manufacturers must navigate for market entry. Stakeholders must monitor spectrum reallocation proceedings across these three jurisdictions to anticipate hardware refresh cycles and inventory positioning.
Market Dynamics
Enterprise procurement teams now dominate Wi-Fi adapter demand as consumer desktop replacement cycles extend beyond five years, while FCC 6 GHz spectrum allocation forces infrastructure refresh timelines across North American data centers.
Growth Catalysts
- Wi-Fi 6E Spectrum Allocation:FCC rulings in the United States and ANFR decisions in France unlock 6 GHz band access, compelling hardware replacement in high-density wireless environments.
- Data Center Buildouts:Hyperscale facility construction in Germany and China absorbs premium PCIe modules for server connectivity.
- Gaming PC Assembly Clusters:Concentrated manufacturing zones in Shenzhen and Taipei drive elevated shipments of tri-band configurations with external antenna arrays.
Market Restraints
- Semiconductor Supply Concentration:Foundry capacity constraints in Taiwan limit radio frequency component availability for M.2 module production.
- Radio Certification Fragmentation:Divergent type approval pathways between China's MIIT and European ETSI directives extend product launch timelines by quarters.
- Integrated Alternative Threat:Motherboard vendors embed Wi-Fi directly into enterprise platform chipsets, compressing discrete adapter attach rates.
Strategic Opportunities
- Industrial IoT Penetration:Factory automation deployments in Japan and South Korea create demand for ruggedized PCIe adapters in harsh environments.
- Open RAN Convergence:Disaggregation of radio access networks enables adapter card suppliers to supply white-box baseband processing units.
- India PLI Incentive:Production-linked incentive schemes for electronics manufacturing attract module assembly investments serving domestic enterprise demand.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave antenna design expertise concentrates among a narrow pool of specialists in San Diego and Helsinki.
- Legacy Infrastructure Integration:Enterprise IT teams struggle to bridge 802.11ac endpoints with Wi-Fi 6E access points without full forklift upgrades.
- Interoperability Certification Backlogs:Wi-Fi Alliance testing queue delays compress seasonal product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Adapter Card Market |
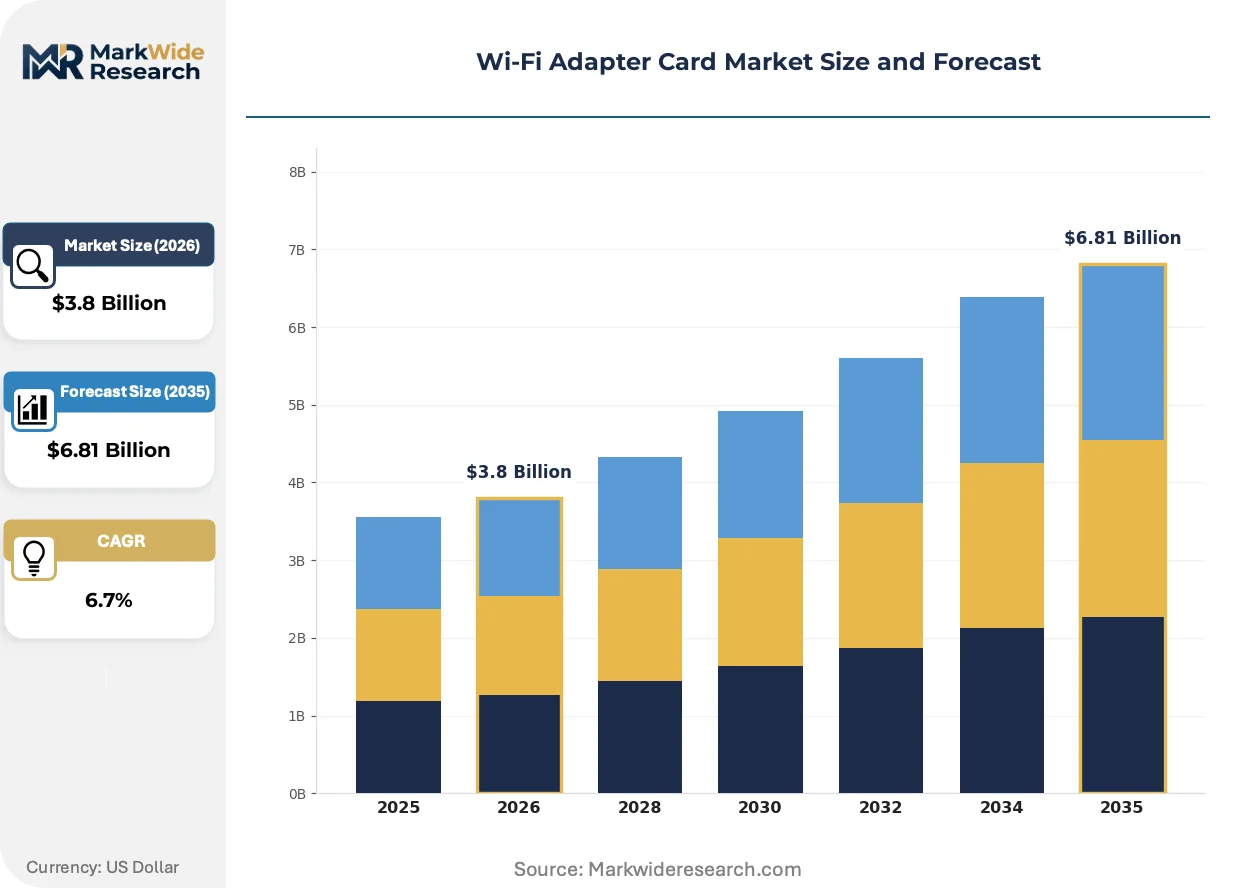
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCIe Card, USB Adapter, Mini PCIe, M.2 Module, ExpressCard Technology: Wi-Fi 6, Wi-Fi 5, Bluetooth Integration, Dual-Band, Tri-Band Application: Personal Computing, Enterprise Networking, Gaming Systems, IoT Devices, Smart Home End User: Consumers, Small & Medium Businesses, Data Centers, Managed Service Providers |
| Companies Covered | ASUSTek Computer Inc., Broadcom Inc., Intel Corporation, Belkin International Inc., Qualcomm Technologies, Inc, TP-Link Technologies Co., Ltd., D-Link Corporation, Realtek Semiconductor Corp., Netgear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Adapter Card Market Emerging Trajectories
Radio architecture modularization is fragmenting traditional supply chains, as specialized fabless designers separate from integrated platform vendors. This decomposition is reshaping how enterprise buyers evaluate total cost of ownership.
Tri-band radio chipsets is decomposing the legacy dual-band standard by adding 6 GHz capability alongside 2.4 GHz and 5 GHz operation. Enterprise networking teams in the United States adopt these modules aggressively for high-density conference and co-working spaces. The technology is decomposing incumbent supplier relationships as buyers source radio silicon independently from platform integrators.
ETSI harmonized radio equipment directives in Europe now mandate specific power spectral density limits for 6 GHz operation that diverge from FCC frameworks. Equipment vendors maintain separate firmware branches for European and North American shipments. German industrial automation buyers face delayed certification timelines as notified bodies adapt testing protocols.
Enterprise sourcing teams now negotiate direct volume agreements with adapter module suppliers rather than accepting bundled motherboard configurations. System integrators in China and Taiwan lose margin capture as buyers disintermediate traditional distribution. This pattern concentrates in United States federal and healthcare IT procurement, where security certification requirements favor discrete component traceability.
Wi-Fi Adapter Card Market Segmentation
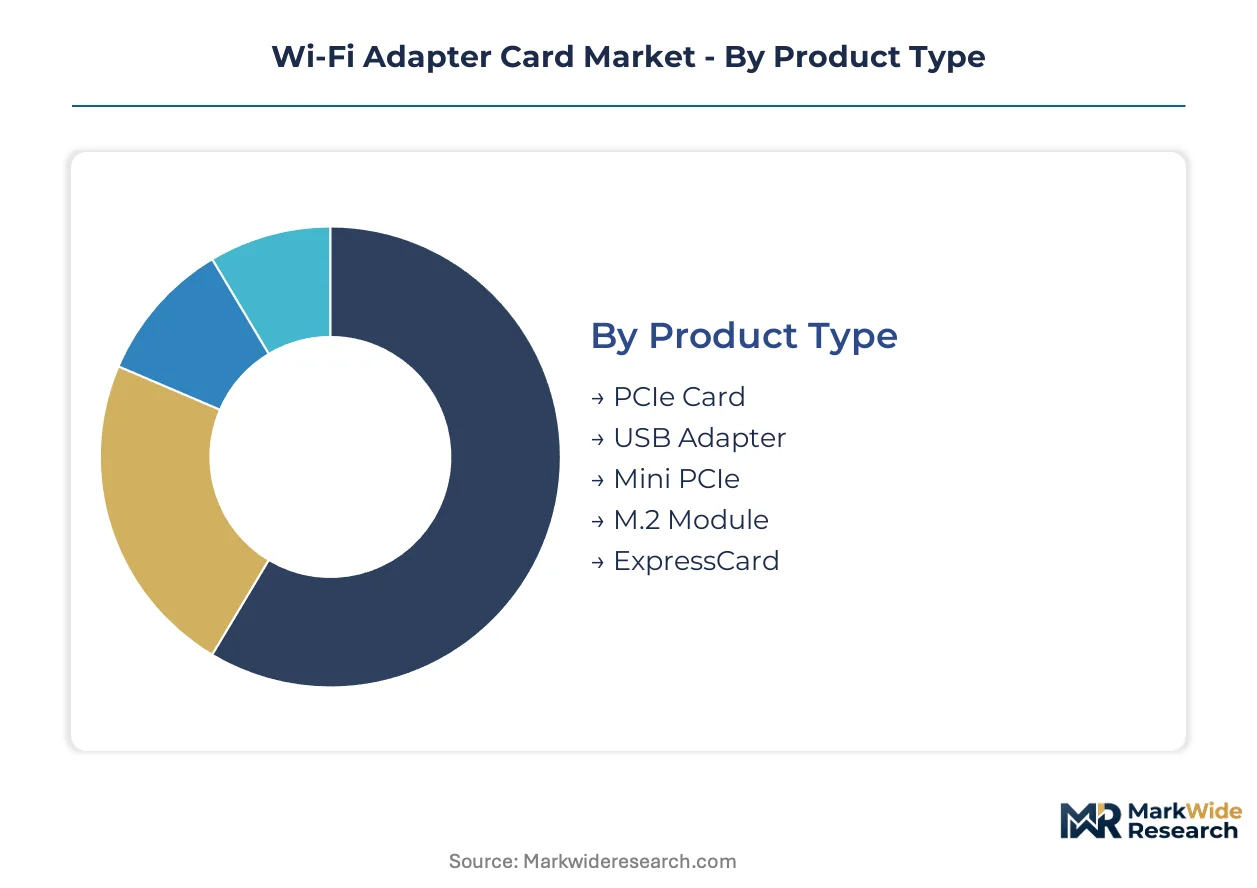
Wi-Fi adapter card procurement channels diverge sharply by segment, with enterprise networking teams sourcing M.2 modules direct from manufacturers while gaming and consumer segments flow through distributor networks. Understanding these channel dynamics helps suppliers calibrate pricing power and inventory positioning across each category.
Product Type:
Channel mix varies dramatically by form factor, with enterprise direct procurement favoring internal modules and retail channels dominating external adapters.
- M.2 Module:Compact form factor integrating directly onto motherboards via PCIe/NVMe lanes, supporting Wi-Fi 6E tri-band configurations. Data center buildouts in Germany and China absorb premium units for server connectivity, constrained by Taiwan foundry capacity for RF components.
- PCIe Card:Full-height expansion cards occupying desktop PCIe slots with external antenna connectivity. Gaming PC assembly clusters in Shenzhen and Taipei drive elevated shipments of dual-band and tri-band configurations with detachable antenna arrays.
- USB Adapter:Plug-and-play external connectivity for legacy systems and temporary deployments.
- Mini PCIe:Legacy form factor for embedded systems and industrial computing with limited new design wins.
- ExpressCard:Obsolete laptop expansion standard with residual replacement demand only.
M.2 modules dominate installed base in enterprise refresh cycles. PCIe cards are where expansion concentrates in gaming and workstation segments.
Technology:
Cost tier stratification separates premium 6 GHz capable silicon from legacy 2.4/5 GHz solutions, with pricing spreads exceeding 3x at the component level.
- Wi-Fi 6:OFDMA and MU-MIMO architecture delivering 9.6 Gbps theoretical throughput with improved spectral efficiency. Enterprise networking teams in the United States adopt aggressively for high-density conference spaces, driven by FCC 6 GHz spectrum allocation timelines.
- Tri-Band:Simultaneous 2.4 GHz, 5 GHz, and 6 GHz operation for uncongested backhaul and client access. High-density wireless environments in France and the United States command premium positioning as ANFR and FCC rulings unlock 6 GHz access.
- Wi-Fi 5:802.11ac wave 2 standard with 3.5 Gbps maximum throughput, now concentrated in budget consumer tiers.
- Bluetooth Integration:Combo modules reducing antenna count and BOM cost for mobile and IoT endpoints.
- Dual-Band:Legacy 2.4/5 GHz configuration facing displacement by tri-band in premium tiers.
Wi-Fi 5 dominates installed base in consumer desktop refresh cycles. Wi-Fi 6 is where expansion concentrates across enterprise infrastructure replacement schedules.
Application:
Volume concentration aligns with customer procurement scale, from individual consumer purchases to thousand-unit enterprise tenders.
- Enterprise Networking:Bulk procurement of M.2 and PCIe modules for desktop workstation fleets and edge server deployments. United States federal and healthcare IT procurement favors discrete component traceability for security certification compliance.
- Gaming Systems:Performance-oriented configurations with external antenna arrays and heatsink-equipped modules. Manufacturing concentration in Shenzhen and Taipei drives regional sourcing patterns for tri-band silicon.
- Personal Computing:Consumer desktop and laptop aftermarket replacement demand with extended refresh cycles beyond five years.
- IoT Devices:Embedded wireless connectivity for industrial sensors and automation controllers.
- Smart Home:Gateway and hub connectivity with cost-optimized single-band and dual-band configurations.
Personal computing dominates installed base in consumer channels. Enterprise networking is where expansion concentrates as infrastructure refresh accelerates.
End User:
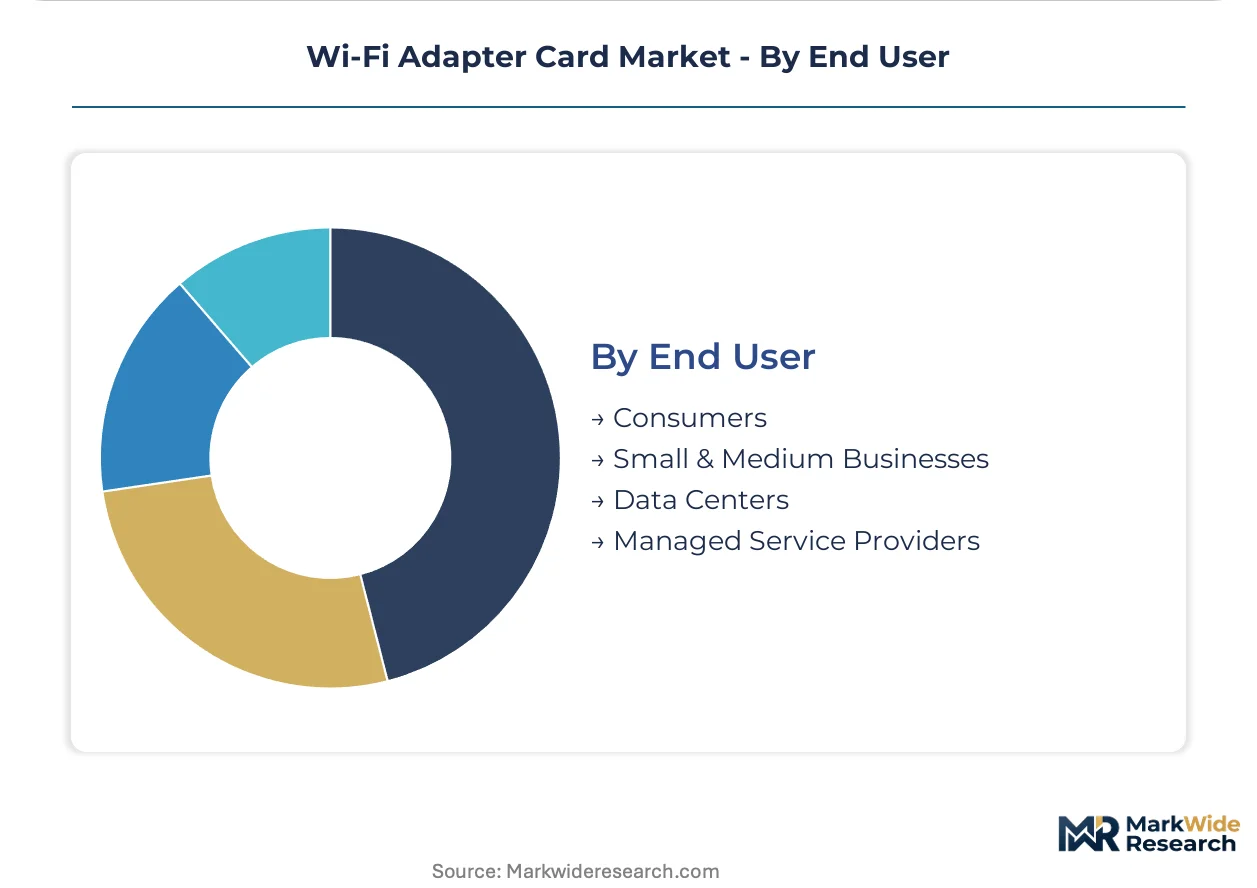
Margin structure varies by customer scale, with data centers commanding volume discounts and managed service providers seeking flexible procurement terms.
- Data Centers:Hyperscale facility operators sourcing premium PCIe modules for server connectivity and out-of-band management. Buildouts in Germany and China absorb high-reliability units with extended temperature specifications.
- Small & Medium Businesses:Volume procurement through Asian distribution networks, with TP-Link Technologies Co., Ltd. capturing share via channel depth.
- Consumers:Individual purchasers with replacement-driven demand and price sensitivity.
- Managed Service Providers:Flexible procurement for client infrastructure with standardization requirements across heterogeneous environments.
Consumers dominate installed base in historical demand mix. Data centers are where expansion concentrates in premium module absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains its position through hyperscale data center interconnects in Northern Virginia and Dallas-Fort Worth, while China's Yangtze River Delta manufacturing belt underwrites component supply security for the sector.
United States
FCC 6 GHz spectrum allocation drives enterprise infrastructure refresh across federal IT and healthcare procurement channels. The agency's equipment authorization database shapes product launch sequencing for M.2 module vendors. Northern Virginia's data center corridor absorbs premium PCIe adapters for server out-of-band management at scale.
China
MIIT type approval requirements create distinct certification pathways that manufacturers must navigate for domestic market entry. The regulator's wireless LAN equipment standards mandate specific testing protocols that extend product timelines. Shenzhen and Taipei's gaming PC assembly clusters drive elevated shipments of tri-band configurations with external antenna arrays.
Germany
Hyperscale facility construction across Frankfurt and Munich absorbs premium PCIe modules for server connectivity and industrial automation. ETSI harmonized radio equipment directives enforce power spectral density limits for 6 GHz operation that diverge from FCC frameworks. Baden-Württemberg's automotive electronics suppliers integrate ruggedized adapters into factory automation deployments.
France
ANFR decisions unlock 6 GHz band access for high-density wireless environments in Paris and Lyon commercial districts. The regulator's spectrum allocation timeline compels hardware replacement schedules that lag FCC rulings by quarters. Île-de-France's co-working space operators adopt tri-band modules aggressively for uncongested client access.
Japan
METI industrial policy supports factory automation deployments that create demand for ruggedized PCIe adapters in harsh manufacturing environments. The ministry's IoT penetration targets channel procurement toward embedded wireless connectivity for sensors and controllers. Kyushu's semiconductor packaging facilities source high-reliability units with extended temperature specifications.
Wi-Fi Adapter Card Market Vendor Landscape
Listed leaders compete with private specialists across radio architecture design and channel reach dimensions. The vendor base organizes into three tiers: integrated platform vendors with captive silicon supply, fabless module specialists sourcing radio components independently, and distribution-heavy volume players capturing small and medium business segments. Two competitive moves dominate: direct enterprise procurement agreements that disintermediate system integrators, and tri-band portfolio diversification that captures 6 GHz upgrade cycles.
Within the integrated platform tier, Intel Corporation and Qualcomm Technologies, Inc occupy positions that exemplify divergent strategic approaches to enterprise motherboard bundling and high-density wireless environments. TP-Link Technologies Co., Ltd. represents the distribution-anchored volume archetype across Asian small and medium business channels. ASUSTek Computer Inc. and D-Link Corporation sit within the specialist tier that balances gaming segment premium positioning with industrial IoT ruggedization requirements.
| Leading Market Players |
|---|
| ASUSTek Computer Inc. |
| Broadcom Inc. |
| Intel Corporation |
| Belkin International Inc. |
| Qualcomm Technologies, Inc |
| TP-Link Technologies Co., Ltd. |
| D-Link Corporation |
| Realtek Semiconductor Corp. |
| Netgear Inc. |
| Others |
Supply Flow & Price Mechanics
FCC equipment authorization timelines gate both supplier qualification and price differentiation simultaneously, as vendors must maintain separate firmware branches for North American and European shipments while enterprise buyers negotiate direct volume agreements that bypass traditional distribution markups.
Pricing Analysis
Volume-discount tiering separates data center procurement from small and medium business channels, with hyperscale operators extracting 40-60% unit cost reductions at thousand-module scale while Asian distributors capture margin on sub-hundred-unit transactions. Price differentiation rests on certification grade and after-sales service bundling, with Wi-Fi Alliance interoperability testing and FCC ID compliance commanding 15-25% premiums over uncertified alternatives. Cost compression in the consumer tier intensifies because motherboard vendors embed Wi-Fi directly into platform chipsets, eroding discrete adapter attach rates. Gaming system integrators show least price sensitivity, prioritizing tri-band performance and external antenna configurability over per-unit economics.
Supply Chain Analysis
Inventory lead times for M.2 RF components stretched to 26-32 weeks during foundry capacity constraints, forcing enterprise buyers to place binding forecasts six months ahead of deployment. Manufacturing concentrates in Taiwan, China, and Vietnam, with radio frequency silicon fabrication anchored in Hsinchu and module assembly distributed across Shenzhen and Dongguan. Component sourcing draws from GaAs power amplifiers, substrate-based antenna substrates, and high-frequency laminates. Single-source vulnerability concentrates in Taiwan foundry capacity for 6 GHz-capable radio dies. Distribution runs through Asian electronics distributors for volume segments and direct manufacturer agreements for enterprise and data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wi-Fi 6E spectrum allocation functions as a high-growth disruption, compelling infrastructure replacement across enterprise wireless environments as FCC and ANFR rulings unlock 6 GHz band access and force hardware refresh timelines.
For Market Incumbents: Secure captive foundry allocation for 6 GHz radio silicon through multi-year supply agreements, insulating against Taiwan capacity constraints that constrain M.2 module availability. Deepen backward integration into RF front-end components to defend margin position against fabless module specialists sourcing radio architecture independently. Prioritize Wi-Fi Alliance certification pipeline investment to compress interoperability testing queues that currently delay seasonal product launches. For New Entrants and Emerging Players: Anchor in India's production-linked incentive schemes for electronics manufacturing, leveraging domestic module assembly investments to serve enterprise demand with cost-optimized configurations. Target industrial IoT penetration in Japan and South Korea, where factory automation deployments create demand for ruggedized PCIe adapters in harsh environments that incumbent gaming-focused suppliers underserve. Pursue Open RAN convergence opportunities by supplying white-box baseband processing units to disaggregated radio access networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless module specialists holding Wi-Fi 6E certification portfolios and Asian distribution relationships. Long-term viability centers on 5-10 year spectrum utilization windows as 6 GHz infrastructure replacement cycles mature and Wi-Fi 7 standards emerge. Monitor FCC equipment authorization database velocity as the inflection indicator, with quarterly approval spikes signaling vendor product pipeline health and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Tri-Band Portfolio Diversification | Captures 6 GHz upgrade cycles in United States and French high-density wireless environments. |
| Direct Enterprise Procurement Agreements | Disintermediates Taiwanese system integrators in federal and healthcare IT channels. |
| Foundry Capacity Reservation | Secures Taiwan radio frequency component allocation against semiconductor supply concentration risks. |
| Open RAN Baseband Supply | Enables adapter card suppliers to penetrate disaggregated radio access network infrastructure. |
| India PLI Manufacturing Investment | Attracts module assembly capacity serving domestic enterprise demand with tariff-advantaged positioning. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with enterprise networking procurement managers, data center infrastructure engineers, gaming PC system integrators, RF component sourcing specialists, and Wi-Fi Alliance certification directors. Secondary validation drew from FCC equipment authorization databases, ETSI harmonized radio equipment directive filings, MIIT type approval records, SEC 10-K disclosures from listed semiconductor vendors, and hyperscaler capex deployment trackers. Bottom-up module shipment estimates triangulated against top-down enterprise IT spending surveys across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including form factor category, Wi-Fi standard generation, end-use application, and regional regulatory cluster. CAGRs were derived from curve-fitting historical replacement cycles against spectrum allocation timelines and infrastructure refresh patterns. Industry-specific forecast inputs incorporated data center buildout pipelines in Germany and China, gaming PC assembly cluster output indices from Shenzhen and Taipei, and enterprise desktop fleet depreciation schedules.
Material uncertainties — foundry capacity constraints, divergent certification timelines between China's MIIT and European ETSI frameworks, and motherboard Wi-Fi integration rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding spectrum allocation proceeding on announced timelines and enterprise refresh cycles maintaining historical patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market