
 Connector for PV System Market | 2026-2036
Connector for PV System Market Size, Share, and Industry Trends Forecast 2026-2036
Connector for PV System Market Insights
Utility-scale EPC contractors are bifurcating procurement patterns away from residential installers as gigawatt-scale solar farms demand higher-amperage connector assemblies. Stäubli Electrical Connectors leverages its Swiss manufacturing heritage to dominate premium MC4-compatible product lines for European utility projects. TE Connectivity anchors North American supply through extensive distributor networks serving commercial installation contractors. Amphenol Corporation specializes in ruggedized connector systems engineered for desert and coastal utility-scale environments.
A connector for PV system is an electromechanical coupling device, typically rated between 30 A and 150 A, designed to join photovoltaic module strings to inverters or combiner boxes while maintaining IP67 or IP68 ingress protection against moisture and dust infiltration. MC4 connectors occupy the largest product category due to their de facto standardization across module manufacturers, while plug-in connectors represent the fastest-growing segment as installers seek tool-free field assembly to reduce labor hours. Crimping technology leads manufacturing methods for permanent installations, though injection molding is displacing older assembly techniques for high-volume connector housing production.
IEC 62852 governs European connector safety requirements, while UL 6703 shapes North American product certification and market access protocols. China's GB/T standards, administered by SAMR, mandate domestic testing for connectors deployed in state-backed solar farms. Stakeholders must monitor evolving fire safety codes and copper-aluminum transition specifications as module wattages climb and string currents rise beyond legacy connector ratings.
Market Dynamics
Module power ratings climbing past 600 W are forcing connector architectures to handle 20 A to 30 A per string, compressing legacy 15 A designs and accelerating procurement of high-current assemblies across utility-scale EPCs.
Growth Catalysts
- Utility-Scale Deployment Surge:Gigawatt-scale solar farms in the US, India, and Saudi Arabia are standardizing 1500 V DC architectures that require upgraded connector voltage ratings and higher amperage capacity.
- IEC 62852 Certification Harmonization:European safety standardization is reducing technical barriers for connector manufacturers seeking cross-border market access within EU member states.
- Aluminum Conductor Adoption:Module manufacturers are shifting from copper to aluminum cabling, creating demand for copper-aluminum transition connectors engineered for galvanic corrosion resistance.
Market Restraints
- Copper Price Volatility:Terminal and contact material costs fluctuate with London Metal Exchange pricing, compressing margin stability for connector assemblers dependent on spot-market metal sourcing.
- Chinese Manufacturing Concentration:Over 70% of global connector housing production clusters in Zhejiang and Jiangsu provinces, creating single-source vulnerability for international procurement managers.
- Legacy System Interoperability:Field-installed MC4-compatible connectors from 2015-2019 vintages lack current-carrying capacity for modern high-wattage modules, forcing costly string rewiring rather than simple plug upgrades.
Strategic Opportunities
- Floating PV Expansion:Reservoir and coastal solar installations in Vietnam, South Korea, and the Netherlands require IP68-rated submersible connectors with marine-grade sealing technologies.
- Agrivoltaic Integration:Dual-use solar-plus-agriculture projects in France and Japan are specifying quick-disconnect connectors enabling seasonal module repositioning without specialized tooling.
- US IRA Domestic Content Credits:The Inflation Reduction Act's manufacturing tax incentives are attracting connector assembly investment to Ohio, Texas, and Arizona to qualify for project-level adders.
Industry Challenges
- Field Installation Skill Gaps:Improper crimping torque and sealing gland assembly by non-certified contractors causes 12% of warranty claims across utility-scale fleets, per NREL field assessments.
- Multi-Certification Timeline Compression:Simultaneous UL 6703, IEC 62852, and TÜV testing for global product launches extends engineering validation cycles by 8 to 14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connector for PV System Market |
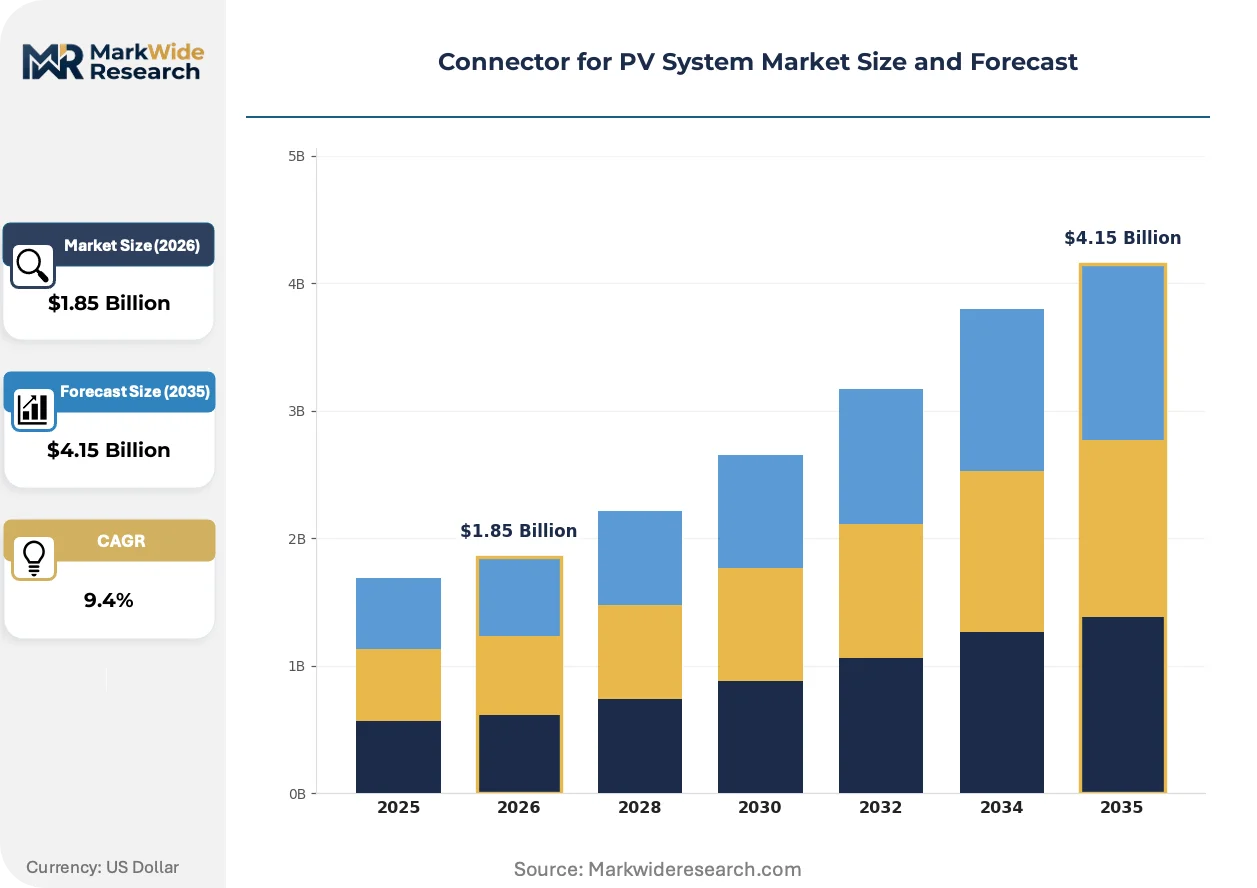
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MC4 Connectors, PV Junction Boxes, Terminal Blocks, Plug-in Connectors Technology: Crimping, Soldering, Injection Molding, Heat Shrink End User: Solar Panel Manufacturers, Installers, EPC Contractors, Utility Companies Application: Residential Systems, Commercial Installations, Utility-scale Projects, Off-grid Solutions |
| Companies Covered | Stäubli Electrical Connectors, TE Connectivity, Amphenol Corporation, Phoenix Contact, Handa Power, Targray, QC Solar, J.A.E. Electronics, GEYA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connector for PV System Market Trends and Innovations
Connector architectures are bifurcating between premium sealed assemblies for utility-scale durability and tool-free plug designs that reduce labor hours in distributed commercial installations. Three forces are compressing legacy product categories.
Push-in spring-contact termination is displacing traditional screw-clamp and crimp-based field assembly across commercial rooftop segments. Installers in Germany and Australia are adopting these connectors to cut string wiring time by 40% per megawatt. The technology is displacing manual torque-tool dependency, reducing contractor training costs and warranty exposure from improper field crimps.
REACH substance restrictions on cadmium plating and certain flame retardants are forcing housing material reformulation across European supply chains. Connector manufacturers are engineering glass-filled polyamide alternatives that maintain UL 94 V-0 ratings without restricted additives. German TÜV and DEKRA testing labs are reporting 60% volume increases in material re-certification submissions for PV connector portfolios.
Aggregator-led procurement consortia are consolidating purchasing power among mid-scale commercial installers in California, Texas, and Florida. These buying groups bypass traditional electrical distributor markups by contracting directly with Asian connector OEMs for container-quantity orders. The channel shift is most visible in the 50 kW to 500 kW commercial segment, where price transparency from direct sourcing is compressing regional distributor margins by 15 to 22 percentage points.
Connector for PV System Market Segmentation
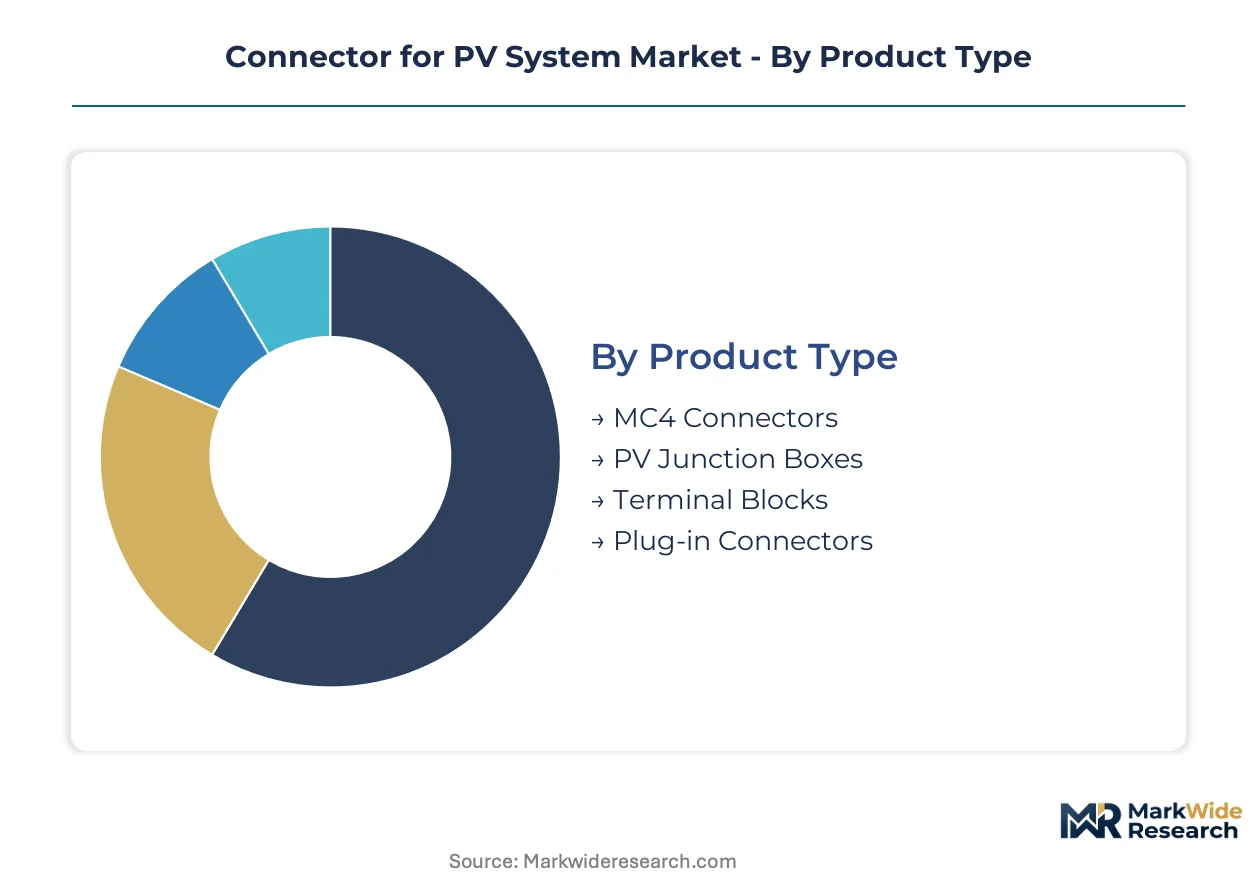
Connector procurement patterns diverge sharply across product architectures and installation scales. Each segment carries distinct margin profiles, certification burdens, and supply chain dependencies that shape vendor positioning.
Product Type:
Premium margin pools concentrate in sealed, high-amperage assemblies for utility-scale durability, while commoditized plug formats compete on labor-cost reduction.
- MC4 Connectors:These multi-contact 4mm diameter connectors dominate module-to-module string wiring with IP67 sealing and 30A to 150A current ratings. Demand concentrates among Chinese solar panel manufacturers supplying gigawatt-scale utility projects in Saudi Arabia and India, driven by IEC 62852 certification harmonization reducing cross-border technical barriers.
- Plug-in Connectors:Tool-free field assembly designs cut installation labor by 40% per megawatt. Installers in Germany and Australia are standardizing these for commercial rooftop deployments where contractor skill gaps and warranty exposure from improper crimps create procurement preference for spring-contact termination.
- PV Junction Boxes:Integrated diode and bypass assemblies manufactured through automated soldering lines.
- Terminal Blocks:Screw-clamp and push-in variants for inverter and combiner box terminations.
The dominant share belongs to MC4 Connectors, while Plug-in Connectors is closing the gap fastest.
Technology:
Manufacturing method selection tracks volume scale and permanence requirements, with automated processes capturing utility-scale contracts.
- Injection Molding:Glass-filled polyamide housing production at 70% concentration in Zhejiang and Jiangsu provinces enables cost structures that undercut European competitors. Chinese OEMs serving aggregator procurement consortia in California and Texas rely on this method for container-quantity orders bypassing traditional distributor markups.
- Crimping:Permanent compression termination remains mandatory for utility-scale installations where field rework costs exceed material savings. NREL field assessments link 12% of warranty claims to improper crimping torque by non-certified contractors, reinforcing demand for factory-controlled crimp quality.
- Soldering:Diode integration within junction boxes using automated wave soldering systems.
- Heat Shrink:Sealing technology for submersible IP68-rated connectors in floating PV reservoirs.
Injection Molding commands the largest volume share, though Crimping retains pricing power in premium utility segments.
End User:
Procurement authority sits with entities controlling installation scale and warranty liability exposure.
- EPC Contractors:Gigawatt-scale project developers in the US and India standardize 1500V DC architectures requiring upgraded connector voltage ratings. These firms bifurcate procurement away from residential installers, consolidating purchasing power through direct Asian OEM contracts.
- Solar Panel Manufacturers:Module OEMs in China specify connector compatibility during production, locking in MC4 formats across 600W+ high-wattage platforms.
- Installers:Distributed commercial contractors in Florida and Texas adopting push-in spring-contact designs to reduce training costs.
- Utility Companies:Grid operators in Saudi Arabia and Vietnam specifying IP68 submersible connectors for floating and coastal installations.
EPC Contractors hold the dominant procurement position, while Utility Companies are expanding specifications fastest for specialized environments.
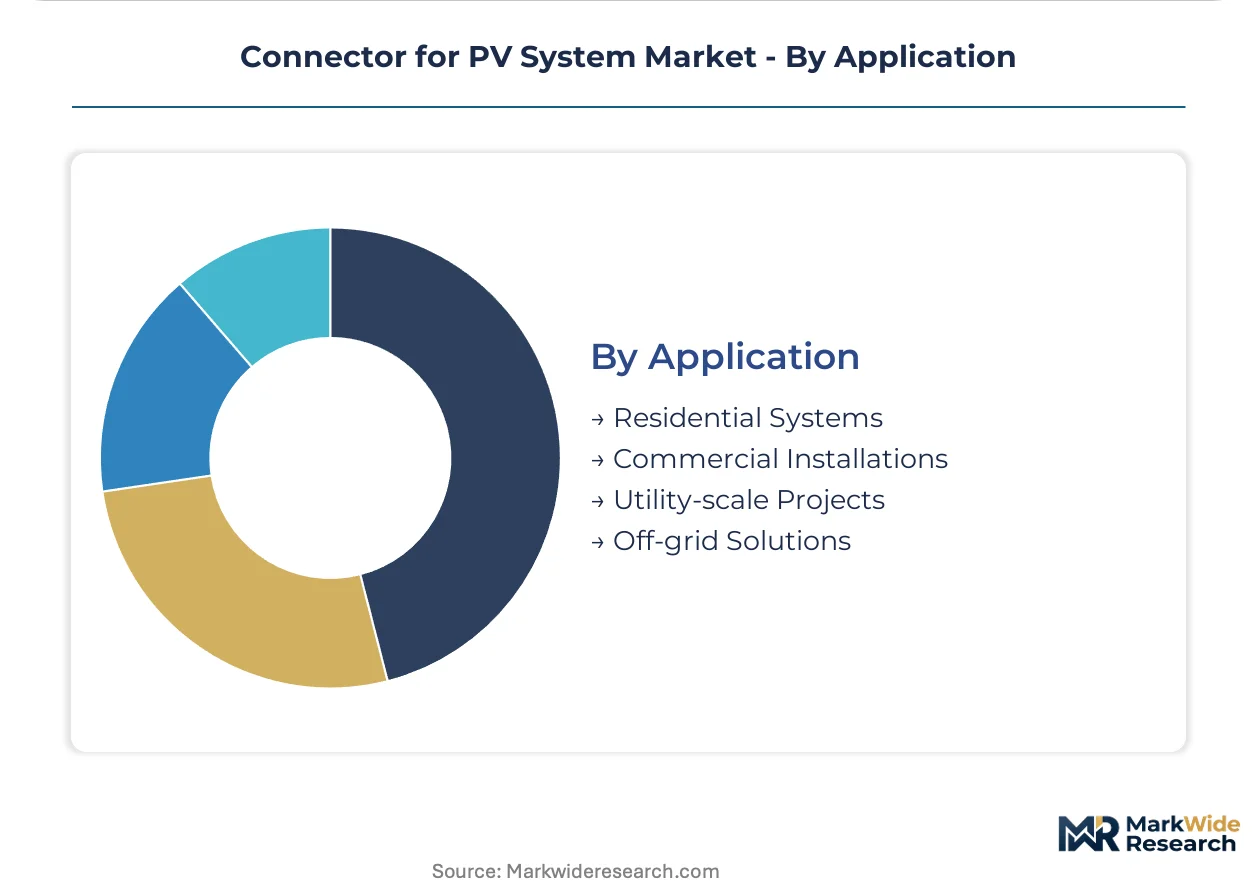
Application:
Voltage and current requirements scale non-linearly with installation size, compressing legacy product categories.
- Utility-scale Projects:1500V DC systems handling 20A to 30A per string force connector architectures beyond legacy 15A ratings. Projects in India and Saudi Arabia demand copper-aluminum transition connectors engineered for galvanic corrosion resistance as module manufacturers shift conductor materials.
- Commercial Installations:50kW to 500kW rooftops in California and Texas drive aggregator-led procurement consortia. Price transparency from direct Asian sourcing compresses regional distributor margins by 15 to 22 percentage points in this segment.
- Residential Systems:Smaller-format installations where MC4 compatibility remains standard.
- Off-grid Solutions:Remote and rural deployments requiring ruggedized environmental sealing.
Utility-scale Projects absorb the largest connector volumes, while Commercial Installations show the steepest channel disruption from direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPC contractors in utility-scale solar drive connector procurement concentration across four demand centers, with certification requirements and manufacturing scale determining regional supplier access.
China
Domestic solar manufacturing scale in Zhejiang and Jiangsu provinces generates the world's highest connector volume consumption. SAMR-administered GB/T standards mandate domestic testing for state-backed solar farms, creating a protected procurement channel for local housing producers. Ningbo and Suzhou industrial clusters supply injection-molded connector assemblies to gigawatt-scale projects across Saudi Arabia and India through direct OEM contracts.
United States
Utility-scale deployment in Texas, California, and Arizona drives 1500V DC architecture standardization requiring upgraded connector voltage ratings. The Inflation Reduction Act's domestic content manufacturing tax incentives attract connector assembly investment to Ohio and Texas facilities seeking project-level credit adders. EPC contractors in the Southwest consolidate purchasing power through direct Asian OEM contracts bypassing traditional electrical distributor networks.
Germany
Commercial rooftop installers adopt push-in spring-contact termination designs to reduce string wiring time and contractor training costs. REACH substance restrictions on cadmium plating and flame retardants force housing material reformulation across European supply chains. TÜV and DEKRA testing labs in Munich and Stuttgart report surging material re-certification submissions for PV connector portfolios.
India
Gigawatt-scale solar farms in Rajasthan and Gujarat standardize high-amperage connector assemblies as module power ratings climb past 600W. CEA technical standards govern grid-interconnection safety requirements for utility-scale installations. Domestic EPC contractors face copper-aluminum transition engineering challenges as module manufacturers shift conductor materials to reduce raw material costs.
Saudi Arabia
Vision 2030 renewable energy targets drive floating and coastal solar installations requiring IP68-rated submersible connectors with marine-grade sealing. SFDA and national standards bodies coordinate with IEC frameworks for product safety certification. NEOM and Eastern Province development zones specify ruggedized connector systems engineered for desert environmental extremes.
Connector for PV System Market Competitive Landscape
Player mix skews toward diversified electrical component conglomerates with captive solar verticals, intermixed with specialized connector engineering houses. Tier-one suppliers leverage multi-certification portfolios spanning UL 6703, IEC 62852, and TÜV standards to capture utility-scale EPC contracts. Two strategic archetypes dominate: Swiss and German precision manufacturers serving European premium segments, and Chinese scale producers capturing volume through direct procurement consortia. Competitive moves concentrate on backward integration into contact material sourcing and geographic capacity expansion to qualify for US IRA domestic content credits.
Within the precision-engineering tier, Stäubli Electrical Connectors and Phoenix Contact exemplify European heritage manufacturers leveraging certification depth for utility project access. TE Connectivity anchors North American supply chain positioning through extensive distributor network relationships. Among Asian volume producers, Handa Power and QC Solar occupy positions serving aggregator-led procurement consortia in California and Texas commercial segments.
| Leading Market Players |
|---|
| Stäubli Electrical Connectors |
| TE Connectivity |
| Amphenol Corporation |
| Phoenix Contact |
| Handa Power |
| Targray |
| QC Solar |
| J.A.E. Electronics |
| GEYA |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with London Metal Exchange copper indexation lock in terminal material costs for utility-scale EPCs while exposing connector assemblers to margin compression when spot prices spike above contracted baselines. These structures tie procurement managers in Texas and Arizona to quarterly price adjustments that cascade through distributor markups and direct OEM container orders alike.
Pricing Analysis
Cost-plus contracts indexed to LME copper pricing dominate procurement between Chinese housing manufacturers and international EPC contractors. Price differentiation hinges on IEC 62852 certification grade and volume scale, with certified premium assemblies commanding substantial premiums over uncertified commodity connectors. Pricing pressure stems from aggregator-led procurement consortia in California and Texas bypassing traditional distributor channels, forcing 15 to 22 percentage point margin compression on regional electrical distributors. Commercial installers in the 50 kW to 500 kW segment exhibit highest price sensitivity, while utility-scale developers in Saudi Arabia and India prioritize durability and certification depth over unit cost.
Supply Chain Analysis
China and Vietnam anchor global connector housing production, with Zhejiang and Jiangsu provinces supplying 70% of injection-molded glass-filled polyamide assemblies. Raw material dependencies rest on copper rod from Chilean smelters, polyamide resin from BASF and DuPont regional facilities, and marine-grade sealing compounds from Japanese specialty chemical producers. Single-source vulnerability concentrates in Zhejiang industrial clusters, where COVID-era lockdowns demonstrated procurement disruption risk for international EPCs. Distribution runs through three channels: direct OEM contracts for gigawatt-scale projects, electrical distributor networks serving commercial installers, and aggregator consortia consolidating mid-scale commercial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connector market is entering cyclical recovery as photovoltaic deployment accelerates through utility-scale project backlogs accumulated during 2022-2024 interest rate peaks. Module power ratings climbing past 600 W force replacement demand for legacy 15 A connector architectures, creating upgrade cycles across installed bases.
For Market Incumbents:Fortify certification portfolios by accelerating simultaneous UL 6703, IEC 62852, and TÜV testing to compress 8 to 14 month validation cycles threatening product launch timelines. Backward integration into copper-aluminum contact material sourcing hedges London Metal Exchange volatility while qualifying for US IRA domestic content manufacturing tax incentives in Ohio and Texas facilities.
For New Entrants and Emerging Players:Differentiate on IP68 submersible connector engineering for floating PV reservoirs in Vietnam, South Korea, and the Netherlands, where marine-grade sealing technologies face supply scarcity. Target agrivoltaic integration projects in France and Japan specifying quick-disconnect formats for seasonal module repositioning, leveraging tool-free spring-contact termination to reduce contractor training barriers.
For Investors and Strategic Acquirers:Specialist connector engineering houses with captive TÜV and DEKRA certification relationships represent priority acquisition archetypes as REACH material reformulation mandates drive 60% volume increases in re-certification submissions. Long-term viability hinges on qualification for US IRA project-level adders and 1500V DC architecture compatibility. The signal to watch is CEA technical standard revisions in India mandating copper-aluminum transition specifications, which would accelerate consolidation among contact material specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Portfolio Expansion | Simultaneous UL 6703, IEC 62852, and TÜV testing compresses 8 to 14 month validation cycles for utility EPC access. |
| Domestic Content Manufacturing Investment | Ohio and Texas assembly facilities qualify connector producers for US IRA project-level tax credit adders. |
| Copper-Aluminum Contact Material Integration | In-house production of galvanic corrosion-resistant terminals hedges LME price volatility and module manufacturer conductor shifts. |
| Floating PV Submersible Connector Development | IP68-rated marine-grade sealing captures reservoir and coastal solar specifications in Vietnam and the Netherlands. |
| Aggregator Consortium Direct Contracting | Bypassing electrical distributor networks captures 50 kW to 500 kW commercial segment price transparency advantages. |
Research Methodology
Cross-validation between primary interviews with utility-scale EPC procurement directors, commercial installer contractors, and connector manufacturer product managers anchors the qualitative findings. Secondary validation draws from IEC 62852 certification databases, UL 6703 product listings, NREL field assessment reports, and SAMR GB/T standard filings. Bottom-up connector shipment data from Zhejiang and Jiangsu production clusters triangulates against top-down photovoltaic deployment projections from national renewable energy agencies.
Sensitivity analysis around copper price volatility, certification timeline compression, and module power rating adoption curves stress-tests base case assumptions across the projection horizon. The analytical framework models segmentation across product architecture, manufacturing technology, end-user procurement authority, and application voltage tier. CAGRs derive from installation volume forecasts weighted by connector content per megawatt and technology transition curves for 1500V DC architectures.
Material uncertainties — copper price spikes exceeding contracted indexation bands, REACH substance restriction expansions, and CEA technical standard revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification harmonization progress and IRA domestic content rule finalization. Recalibration cycles align with material shifts in module power ratings, floating PV deployment trajectories, and national renewable energy auction schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector Kits Market
Connectors
Connector Adapter Kits Market
Connectors
Relay Sockets Market
Connectors
Middle East Connector Market
Connectors
Circular Waterproof Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
India Connector Market
Connectors
Terminal Pins Market
Connectors
Magnetic Connector Market
Connectors
China Connector Market
Connectors
Underwater Connectors Market
Connectors
Press Fit Connector Market
Connectors
Canada Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Line Clamp Market
Connectors
Telecom Mounting Hardware Market