
 Multi-Layer Ceramic Capacitor (MLCC) Market | 2026-2036
Multi-Layer Ceramic Capacitor (MLCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Layer Ceramic Capacitor (MLCC) Market Foresight
Authorized distributor networks for passive components is fragmenting as original equipment manufacturers pursue direct procurement contracts with Asian foundries. Murata Manufacturing Co., Ltd. dominates high-frequency dielectric formulations for 5G base stations. Samsung Electro-Mechanics leverages captive semiconductor packaging lines to secure automotive qualification pipelines. Yageo Corporation anchors mid-tier consumer electronics supply through bulk volume agreements with contract manufacturers.
A multi-layer ceramic capacitor consists of alternating layers of ceramic dielectric and metal electrode materials, typically barium titanate-based compositions with nickel or palladium electrodes, sintered into monolithic blocks to achieve capacitance densities exceeding hundreds of microfarads per cubic centimeter. These components filter noise, stabilize voltage rails, and couple alternating current signals across consumer electronics, automotive control modules, and telecommunications infrastructure. X7R dielectric formulations occupy the largest share of industrial and automotive designs due to stable capacitance across temperature extremes. C0G variants command premium positioning in precision instrumentation and medical devices where near-zero capacitance drift is mandatory. Automotive end-user demand is outpacing consumer electronics as electric drivetrains multiply MLCC counts per vehicle.
Japan's Ministry of Economy, Trade and Industry (METI) classifies high-capacitance MLCCs as critical goods under supply chain resilience frameworks, prompting domestic subsidy programs for capacity expansion. China's Ministry of Industry and Information Technology (MIIT) enforces GB standards for ceramic dielectric performance in telecommunications equipment, creating compliance barriers for non-certified imports. The European Chemicals Agency (ECHA) evaluates nickel electrode powders under REACH authorization procedures, elevating material traceability costs for suppliers serving EU automotive customers. Stakeholders must monitor regulatory divergence between Asian production standards and European environmental compliance to avoid supply disqualification.
Market Dynamics
Automotive electrification is compressing design cycles for high-reliability dielectric components as electric drivetrains multiply MLCC counts per vehicle. Supply concentration in East Asian refining operations creates vulnerability amplification for Western automotive qualification pipelines.
Growth Catalysts
- Automotive Voltage Stabilization:Electric drivetrains require 10-15x more MLCCs per vehicle than internal combustion platforms, pulling high-capacitance formulations into power inverter modules.
- REACH Material Traceability:European environmental compliance mandates are forcing electrode powder purification upgrades that lock in qualified supplier relationships.
- 5G Infrastructure Deployment:Base station densification drives demand for ultra-low-loss dielectric formulations capable of millimeter-wave frequency operation.
Market Restraints
- Barium Titanate Supply Concentration:Over 70% of high-purity feedstock refining occurs in Chinese state-controlled enterprises, creating single-source vulnerability for global formulators.
- Palladium Electrode Cost Volatility:Precious metal price swings in PGM markets compress margin predictability for high-reliability automotive grades.
- Layer Thickness Physical Limits:Dielectric thinning below 0.3 microns introduces breakdown risk that constrains capacitance density scaling in standard manufacturing flows.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme subsidies for semiconductor packaging are attracting MLCC module assembly investments outside traditional East Asian hubs.
- Medical Implant Miniaturization:C0G precision formulations are penetrating active implantable device markets previously served by tantalum capacitors.
- Direct OEM-Foundry Contracting:Automotive tier-1 suppliers are bypassing authorized distributors to secure dedicated capacity allocations from Japanese and Korean manufacturers.
Industry Challenges
- Automotive AEC-Q200 Certification Timelines:18-24 month qualification cycles for new dielectric formulations lag behind electric vehicle platform refresh rates.
- Thin-Film Deposition Talent Scarcity:Process engineering expertise for sub-micron layer control concentrates in aging workforces at legacy Japanese facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Layer Ceramic Capacitor (MLCC) Market |
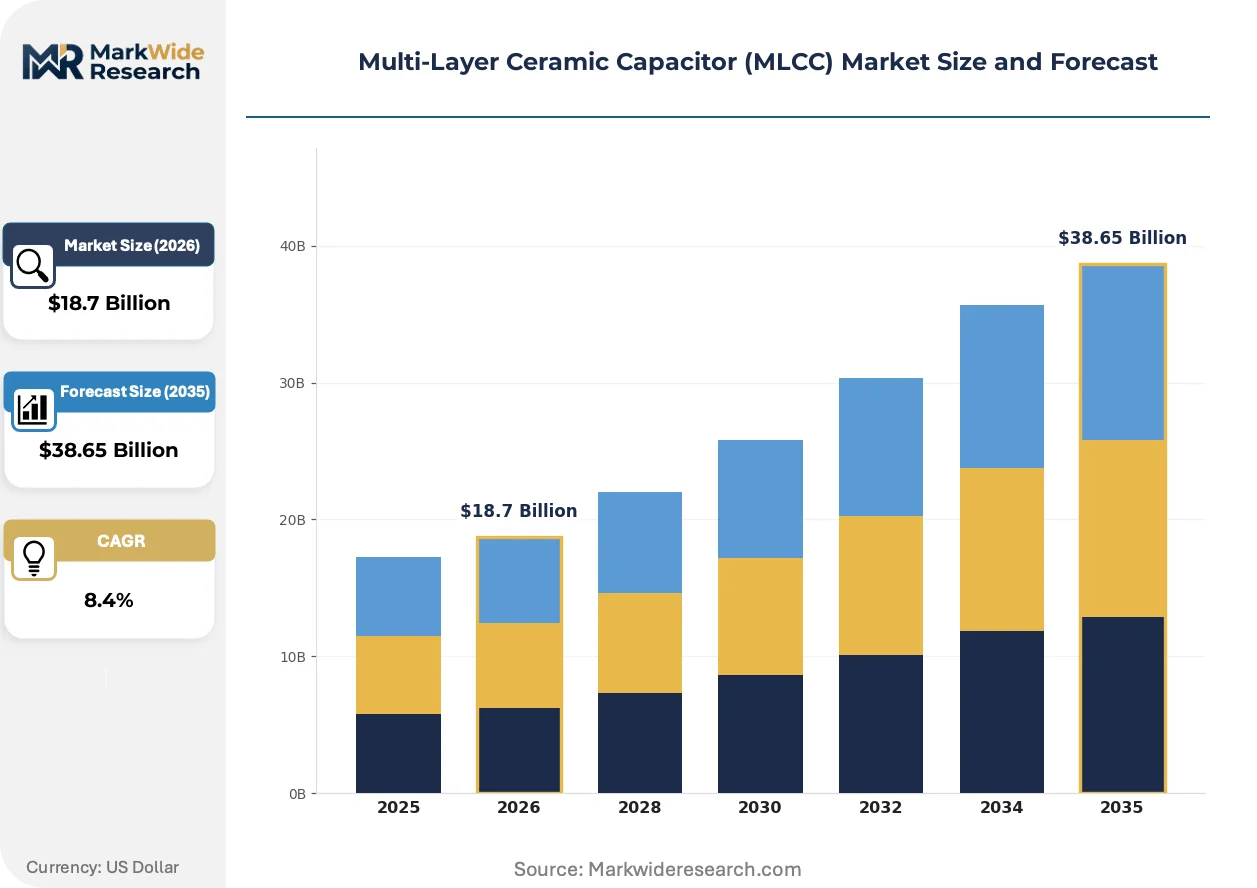
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X7R, X5R, C0G, Y5V End User: Consumer Electronics, Automotive, Industrial, Telecommunications Capacitance Value: 100nF, 1μF, 10μF, 100μF Application: Power Supply, Filtering, Coupling, Bypass |
| Companies Covered | Taiyo Yuden Co., Ltd., Kyocera AVX Components Corporation, Murata Manufacturing Co., Ltd., Vishay Intertechnology Inc., KEMET Corporation, Samsung Electro-Mechanics, Yageo Corporation, Nippon Chemi-Con Corporation, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Layer Ceramic Capacitor (MLCC) Market Shifts & Advancements
Dielectric formulation chemistry and electrode metallurgy are undergoing simultaneous transformation as thermal and electrical performance requirements diverge across end-use verticals. Manufacturing process innovation is compressing traditional yield-loss mechanisms.
Nickel electrode technology is collapsing palladium dependency in automotive-grade MLCCs through advanced reduction-atmosphere sintering protocols. Tier-1 electric vehicle manufacturers are qualifying nickel-base formulations for 150°C continuous operation. This electrode substitution is collapsing precious metal cost exposure while maintaining equivalent reliability metrics in powertrain inverters.
Japan's METI supply chain resilience framework is channeling subsidy capital into domestic high-capacitance MLCC capacity expansion. Domestic manufacturers are accelerating vertical integration into barium titanate precursor synthesis. Korean competitors are responding with parallel government-backed capacity programs under industrial technology protection statutes.
Automotive procurement teams are consolidating supplier panels from 12-15 qualified vendors to 3-4 strategic partners with captive semiconductor packaging capabilities. Direct material flow agreements are displacing traditional distributor-managed inventory programs. German automotive OEMs are pioneering this consolidation, locking in five-year capacity reservations with Japanese foundries.
Multi-Layer Ceramic Capacitor (MLCC) Market Segmentation
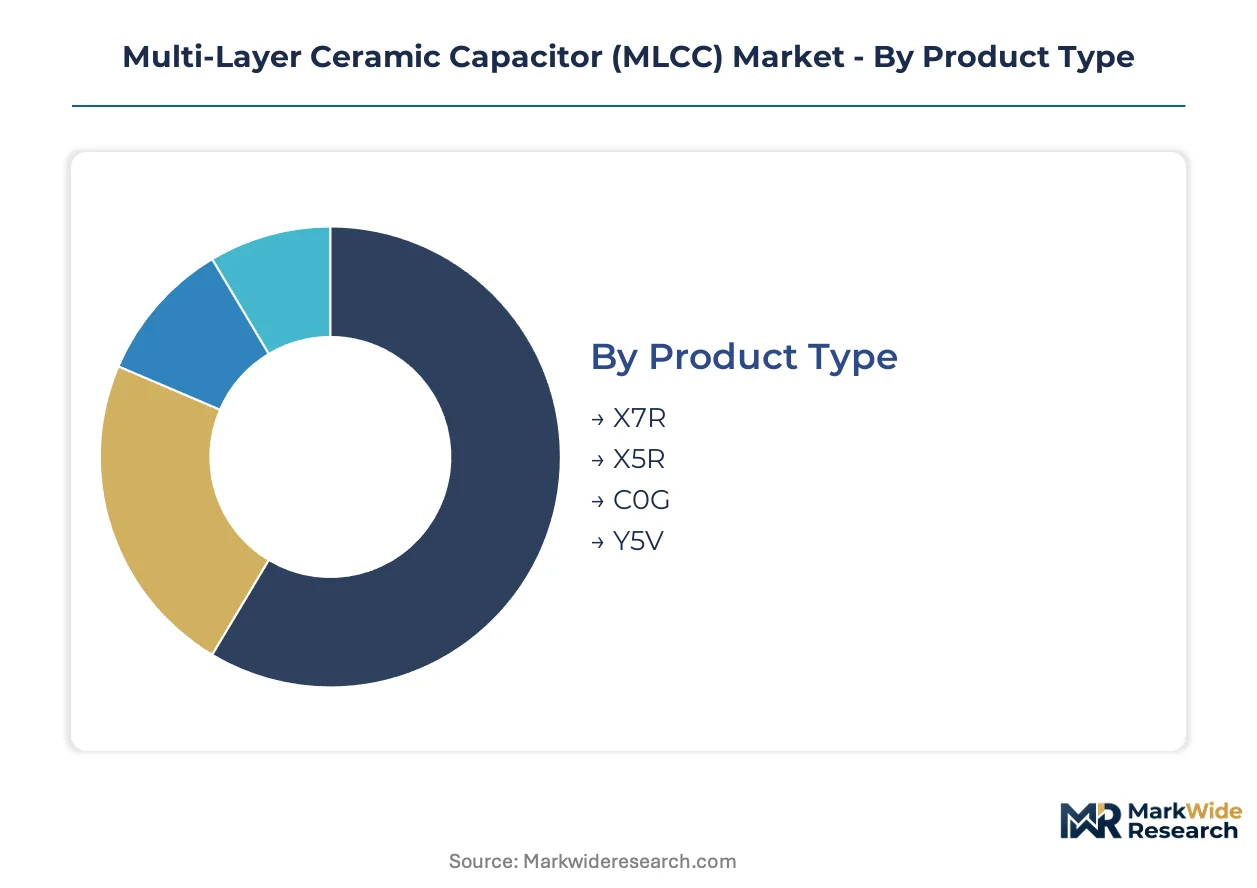
MLCC procurement decisions pivot on dielectric stability, voltage rating, and thermal tolerance. Each segmentation dimension reveals distinct margin structures and qualification barriers that separate commodity volume from premium positioning.
Product Type:
Mature formulations dominate industrial procurement while emerging dielectrics capture automotive electrification demand.
- X7R:Temperature-stable dielectric maintains capacitance across -55°C to 125°C ranges. Automotive control modules and industrial motor drives in Germany and Japan specify X7R for thermal cycling endurance. This formulation anchors the largest procurement volumes across qualified supplier panels.
- C0G:Near-zero capacitance drift across temperature extremes suits precision instrumentation. Medical device manufacturers in Switzerland and aerospace contractors in the US specify C0G for signal integrity where drift tolerance measures parts-per-million. Premium pricing reflects sintering complexity and palladium electrode requirements.
- X5R:Cost-optimized dielectric for consumer electronics operating within narrower thermal windows. Chinese smartphone assemblers specify X5R for non-critical decoupling applications.
- Y5V:High-capacitance density formulation with steep temperature coefficients. Budget-tier power supplies in Southeast Asian manufacturing clusters accept Y5V where cost dominates over stability specifications.
X7R handles the majority of throughput; C0G is climbing the fastest on share as medical and aerospace procurement tightens drift specifications.
End User:
Customer-type concentration is shifting from dispersed consumer electronics toward consolidated automotive procurement with multi-year capacity reservations.
- Automotive:Electric drivetrains require 10-15x MLCC multiplication per vehicle versus combustion platforms. German and Korean OEMs now execute direct foundry contracts bypassing distributor networks. AEC-Q200 qualification timelines create 18-24 month supplier lock-in effects.
- Telecommunications:5G base station densification demands ultra-low-loss dielectrics for millimeter-wave frequencies. Japanese and US infrastructure deployments specify high-Q formulations for signal path integrity.
- Consumer Electronics:Smartphone and laptop manufacturers in China and Vietnam drive high-volume, thin-layer demand. This segment faces margin compression as procurement consolidates toward top-three contract manufacturers.
- Industrial:Factory automation and power conversion equipment specify mid-tier dielectrics for reliability-cost balance. European machinery builders favor X7R for extended temperature operation in motor control modules.
Automotive commands the steepest expansion trajectory; consumer electronics remains the volume anchor despite share erosion.
Capacitance Value:
Dielectric thinning economics favor specific capacitance nodes where layer count and breakdown voltage optimize manufacturing yield.
- 1μF:Workhorse capacitance for decoupling applications across consumer and automotive boards. This value node captures the highest unit volumes in standard 0402 and 0603 case sizes.
- 100μF:Bulk capacitance for power entry modules and inverter DC-link filtering. Korean and Japanese foundries compete on layer-stacking precision for automotive-grade 100μF qualification.
- 100nF:High-frequency bypass standard for digital logic power rails. Chinese EMS providers consume 100nF in highest unit volumes for motherboard assembly.
- 10μF:Mid-range capacitance for voltage regulator modules and intermediate filtering stages. Industrial power supply designers specify 10μF for hold-up time requirements.
1μF represents the throughput workhorse; 100μF is expanding most quickly on electrification-driven demand.
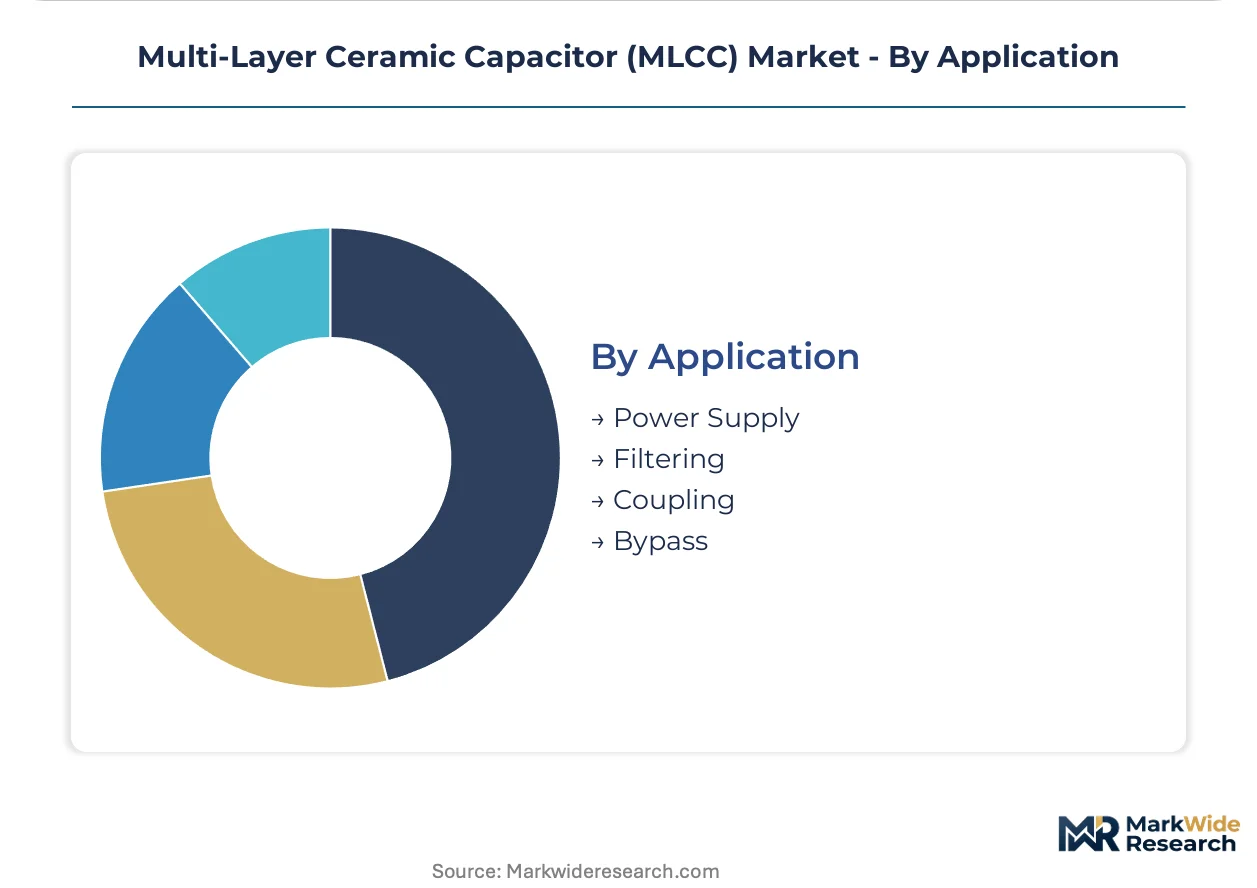
Application:
Functional use case determines dielectric grade, voltage rating, and reliability screening intensity.
- Power Supply:Input filtering and output stabilization demand high-ripple-current endurance. Automotive onboard chargers specify X7R and X5R grades for 150°C continuous operation.
- Filtering:Noise suppression across frequency bands requires impedance matching precision. 5G infrastructure deployments in Japan and the US specify C0G for base station RF paths.
- Coupling:AC signal transfer with DC isolation uses capacitance stability over bias voltage. Medical imaging equipment manufacturers specify C0G for analog front-end coupling.
- Bypass:High-frequency decoupling for digital ICs prioritizes low equivalent series resistance. Smartphone SoC packages drive 100nF and 1μF bypass demand in highest unit volumes.
Bypass applications handle the majority of unit throughput; power supply filtering is gaining share fastest on electrification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI classifies high-capacitance MLCCs as critical goods under supply chain resilience frameworks, prompting domestic subsidy programs for capacity expansion. China's MIIT enforces GB standards for ceramic dielectric performance in telecommunications equipment, creating compliance barriers for non-certified imports. The European Chemicals Agency evaluates nickel electrode powders under REACH authorization procedures, elevating material traceability costs for suppliers serving EU automotive customers.
China
Electric vehicle production in Shenzhen and Shanghai is pulling high-capacitance formulations into power inverter modules at unprecedented scale. MIIT enforces GB standards for ceramic dielectric performance in telecommunications equipment, creating compliance barriers for non-certified imports. State-controlled enterprises in Jiangsu province concentrate over 70% of high-purity barium titanate feedstock refining for global formulators.
Japan
5G base station densification drives demand for ultra-low-loss dielectric formulations capable of millimeter-wave frequency operation in Tokyo and Osaka metro areas. METI classifies high-capacitance MLCCs as critical goods under supply chain resilience frameworks, prompting domestic subsidy programs for capacity expansion. Murata Manufacturing anchors high-frequency dielectric formulation leadership from Kyoto prefecture facilities.
Germany
Automotive electrification is compressing design cycles for high-reliability dielectric components as electric drivetrains multiply MLCC counts per vehicle. The European Chemicals Agency evaluates nickel electrode powders under REACH authorization procedures, elevating material traceability costs for suppliers serving Stuttgart and Munich automotive clusters. German OEMs pioneer supplier panel consolidation, locking in five-year capacity reservations with Japanese foundries.
South Korea
Captive semiconductor packaging capabilities secure automotive qualification pipelines for Seoul and Suwon-based manufacturers. Korean competitors respond to Japanese subsidy programs with parallel government-backed capacity initiatives under industrial technology protection statutes. Samsung Electro-Mechanics leverages integrated packaging lines to anchor mid-tier consumer electronics supply through bulk volume agreements.
United States
5G infrastructure deployments in Dallas and Phoenix specify high-Q formulations for signal path integrity at millimeter-wave frequencies. FCC equipment authorization procedures create certification timelines that lag behind Asian qualification cycles. Aerospace contractors in Southern California specify C0G precision formulations for satellite systems where near-zero capacitance drift is mandatory.
Multi-Layer Ceramic Capacitor (MLCC) Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by dielectric formulation capability and captive integration depth. Japanese and Korean manufacturers anchor premium positioning through metallurgical expertise in sub-micron layer deposition. Western distributors face margin compression as automotive OEMs pursue direct procurement contracts with Asian foundries. Dominant competitive moves include backward integration into barium titanate precursor synthesis and multi-year capacity reservation agreements with tier-1 electric vehicle manufacturers.
Among Japanese fabricators, Murata Manufacturing Co., Ltd. and Taiyo Yuden Co., Ltd. exemplify the premium-tier archetype built on high-frequency dielectric leadership. Samsung Electro-Mechanics represents the integrated Korean model combining captive semiconductor packaging with automotive qualification pipelines. Yageo Corporation anchors mid-tier positioning through bulk volume agreements with contract manufacturers across consumer electronics supply chains.
| Leading Market Players |
|---|
| Taiyo Yuden Co., Ltd. |
| Kyocera AVX Components Corporation |
| Murata Manufacturing Co., Ltd. |
| Vishay Intertechnology Inc. |
| KEMET Corporation |
| Samsung Electro-Mechanics |
| Yageo Corporation |
| Nippon Chemi-Con Corporation |
| TDK Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese high-frequency dielectric facilities is tightening supplier pricing power while accelerating direct contracting between automotive OEMs and foundries. This utilization dynamic compresses margin buffers for distributors caught between volume commitments and spot-market volatility.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-specification, and consumer-economy levels dominates procurement negotiations. Price differentiation rests on AEC-Q200 certification status and palladium versus nickel electrode metallurgy. Cost compression in consumer-tier X5R formulations is intensifying because Chinese EMS providers consolidate purchase volumes with top-three contract manufacturers. Automotive procurement teams exhibit lowest price sensitivity due to 18-24 month qualification lock-in effects.
Supply Chain Analysis
Export-control restrictions on sub-micron deposition equipment limit technology transfer to emerging fabrication facilities. Geographic supply concentration centers on Japan, South Korea, and China for both dielectric formulation and electrode metallurgy. Raw material dependencies include high-purity barium titanate from Jiangsu province, nickel electrode powders subject to REACH traceability, and palladium feedstock from PGM markets. Single-source vulnerability in Chinese state-controlled barium titanate refining amplifies disruption risk. Distribution runs through authorized distributor networks that automotive OEMs increasingly bypass for direct foundry agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film deposition expertise concentrates in aging Japanese engineering workforces, creating a capability gap that constrains capacity expansion timelines and inflates specialist compensation.
For Market Incumbents: Pre-empt nickel electrode qualification pipelines by locking five-year capacity reservations with German and Korean automotive OEMs before rival foundries complete AEC-Q200 certification cycles. Accelerate backward integration into barium titanate precursor synthesis to reduce dependency on Chinese state-controlled feedstock suppliers.
For New Entrants and Emerging Players: India's electronics manufacturing clusters under PLI scheme subsidies offer underpenetrated assembly capacity outside traditional East Asian hubs. Target medical implant miniaturization segments where C0G precision formulations displace tantalum capacitors with less entrenched incumbent relationships. Pursue joint qualification programs with Swiss and US aerospace contractors seeking secondary-source diversification.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-grade MLCC sub-segments as layer-stacking precision requirements multiply equipment costs. Long-term viability favors foundries with captive semiconductor packaging integration and demonstrated AEC-Q200 qualification track records. Monitor METI subsidy disbursement velocity as an inflection indicator for Japanese capacity expansion momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barium Titanate Synthesis | Reduces single-source exposure to Chinese state-controlled feedstock refiners. |
| Multi-Year Capacity Reservation Agreements | Locks automotive OEM procurement before rival foundries complete qualification cycles. |
| Nickel Electrode Qualification for 150°C Operation | Collapses palladium cost exposure while meeting Tier-1 EV inverter reliability metrics. |
| Direct OEM-Foundry Contracting Bypass | Displaces distributor margin layers and secures dedicated allocation visibility. |
| Medical Implant C0G Certification Pipeline | Penetrates precision instrumentation markets with premium drift-tolerance specifications. |
Research Methodology
A standing panel of MLCC procurement directors at Tier-1 automotive suppliers, dielectric formulation chemists at Japanese foundries, and semiconductor packaging engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT GB standards filings, METI supply chain resilience framework documents, ECHA REACH authorization procedures, and customs trade data for barium titanate precursor flows. Bottom-up demand modeling across electric vehicle platform MLCC counts triangulated against top-down capacity announcements from Murata, Samsung Electro-Mechanics, and Taiyo Yuden.
Scenario-bracketing framed low-case assumptions around palladium price volatility and high-case assumptions around accelerated automotive electrification penetration. The analytical framework segmented volume and value outputs across dielectric formulation, end-user vertical, capacitance value node, and regional production hub throughout the forecast period. CAGRs derived from layer-thinning yield curves and automotive content-per-vehicle trajectories calibrated against foundry capacity utilization surveys.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed capacitor manufacturers would shift outcomes beyond modeled ranges. Material shifts in REACH authorization timelines for nickel electrode powders or METI subsidy disbursement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
North America MLCC Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Display Port Adapters Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Breadboards Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Audio CODEC Market
Electronic Components
Passive Attenuator Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Electromechanical Timers Market