
 Middle East and Africa Surgical Equipment Market | 2026-2036
Middle East and Africa Surgical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Surgical Equipment Market Analytics
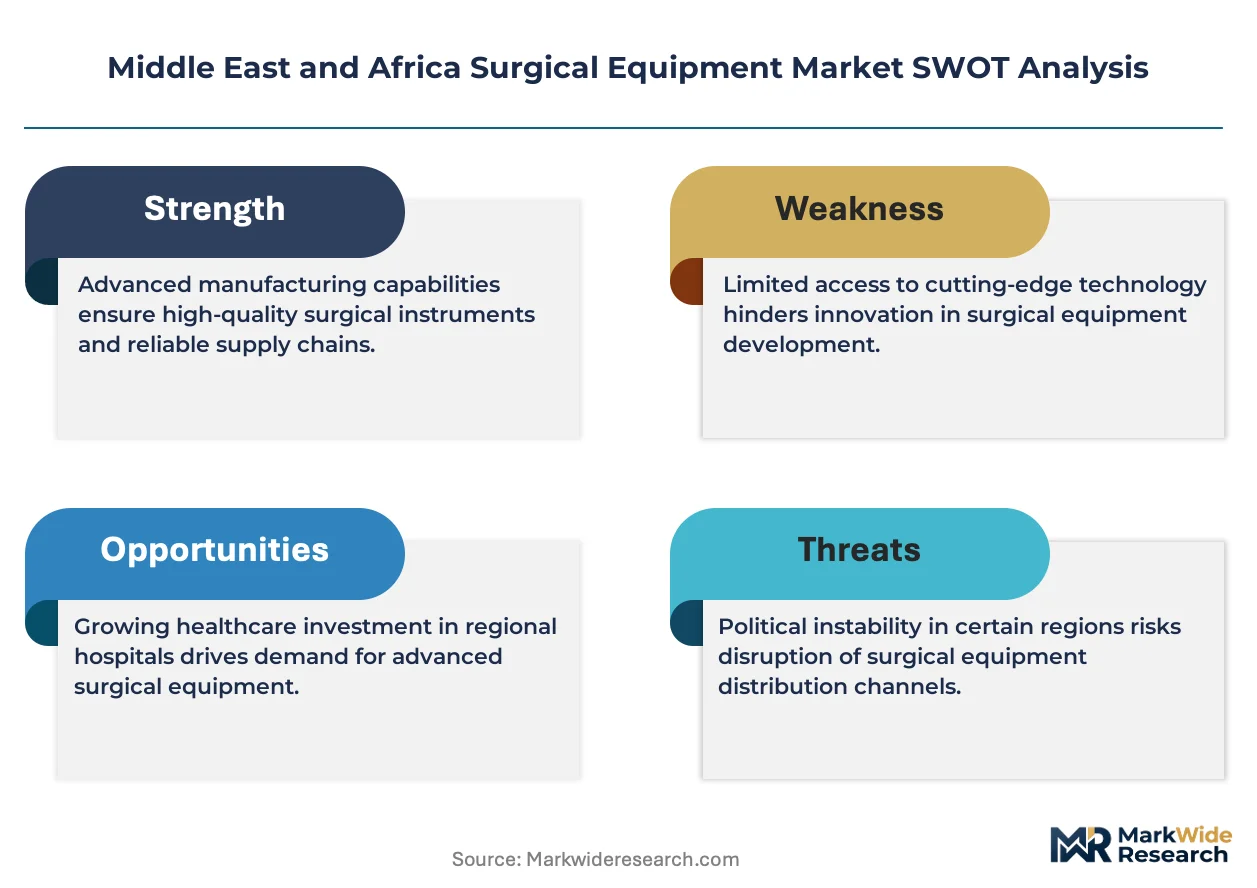
Private hospital chains are redrawing procurement priorities across the Middle East and Africa surgical equipment landscape. Medtronic PLC leverages its electrosurgical portfolio to anchor high-volume contracts in Saudi Arabia and the UAE. Johnson & Johnson sustains suture and mesh dominance through direct distribution to government hospital networks. Stryker Corp competes on robotic surgery integration, positioning its Mako platform for orthopedic centers in South Africa and Egypt.
Middle East and Africa surgical equipment encompasses precision-engineered instruments, powered devices, and consumables designed for sterile operative environments, typically manufactured from medical-grade stainless steel, titanium, or polymer composites to withstand autoclave cycles and biocompatibility testing. Electrosurgical devices command premium pricing due to generator complexity and disposable electrode attachment requirements, while sutures represent the highest-volume recurring revenue stream with thinner margins. Robotic surgery technology absorbs disproportionate capital allocation despite limited installed bases, whereas conventional surgery instruments still occupy the majority of procedure volumes across undercapitalized facilities in sub-Saharan Africa.
Saudi Arabia's SFDA, South Africa's national health product regulator, and the UAE's Ministry of Health and Prevention collectively enforce device registration, sterilization standards, and import licensing that filter non-compliant suppliers from tender processes. SFDA's alignment with FDA predicate device pathways accelerates approval timelines for US-origin manufacturers while creating documentation barriers for smaller Asian exporters. Stakeholders must monitor how Egypt's emerging medical device regulatory framework and Nigeria's drug and food regulatory agency evolve their technical requirements, as these jurisdictions represent the next frontier for formalized surgical equipment distribution beyond the Gulf and South African core markets.
Market Dynamics
SFDA sterilization validation protocols are compressing import timelines for surgical equipment suppliers while Gulf hospital infrastructure spending accelerates demand for integrated operating room systems.
Growth Catalysts
- SFDA Predicate Alignment:Saudi Arabia's adoption of FDA-equivalent device pathways accelerates registration for sterilized instrument sets. Foreign manufacturers bypass redundant clinical trials.
- Minimally Invasive Surgery:South African ambulatory centers expand laparoscopic tool procurement. Procedure volumes in cataract and arthroscopy drive disposable instrument consumption.
- GCC Infrastructure Spending:Hospital construction across the UAE, Qatar, and Kuwait concentrates demand for electrosurgical generators and powered orthopedic tools.
Market Restraints
- Medical-Grade Steel Volatility:Nickel and chromium price swings squeeze margin on reusable forceps and retractors. Turkish and Indian steel suppliers dominate raw material sourcing.
- Single-Source Generator Dependency:Electrosurgical device manufacturers rely on concentrated German and Japanese radiofrequency component suppliers. Disruption propagates through Gulf procurement pipelines.
- Autoclave Compatibility Limits:Polymer-composite instruments face thermal degradation thresholds below 134°C steam cycles. Material science constraints restrict design flexibility.
Strategic Opportunities
- Egypt Regulatory Formalization:Cairo's emerging medical device framework creates first-mover advantage for compliant suppliers. Tender processes shift from informal to structured procurement.
- Robotic-Assisted Surgery Convergence:Integration of haptic feedback with existing laparoscopic towers enables partial automation. Egyptian and South African orthopedic centers pilot hybrid platforms.
- Direct Hospital Contracting:Bypassing layered distributors, manufacturers secure multi-year service agreements with Saudi and UAE private chains. Spare parts and training bundles lock in recurring revenue.
Industry Challenges
- Sterile Processing Technician Shortage:Gulf hospitals lack certified staff for complex endoscope reprocessing. Training lag extends equipment downtime.
- SFDA Documentation Burden:Biocompatibility testing protocols for polymer coatings extend submission timelines. Smaller Asian exporters abandon Saudi tenders.
- Legacy Inventory Integration:New powered surgical tools interface poorly with 1990s-era sterilization tracking systems. Hospital IT departments delay upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Surgical Equipment Market |
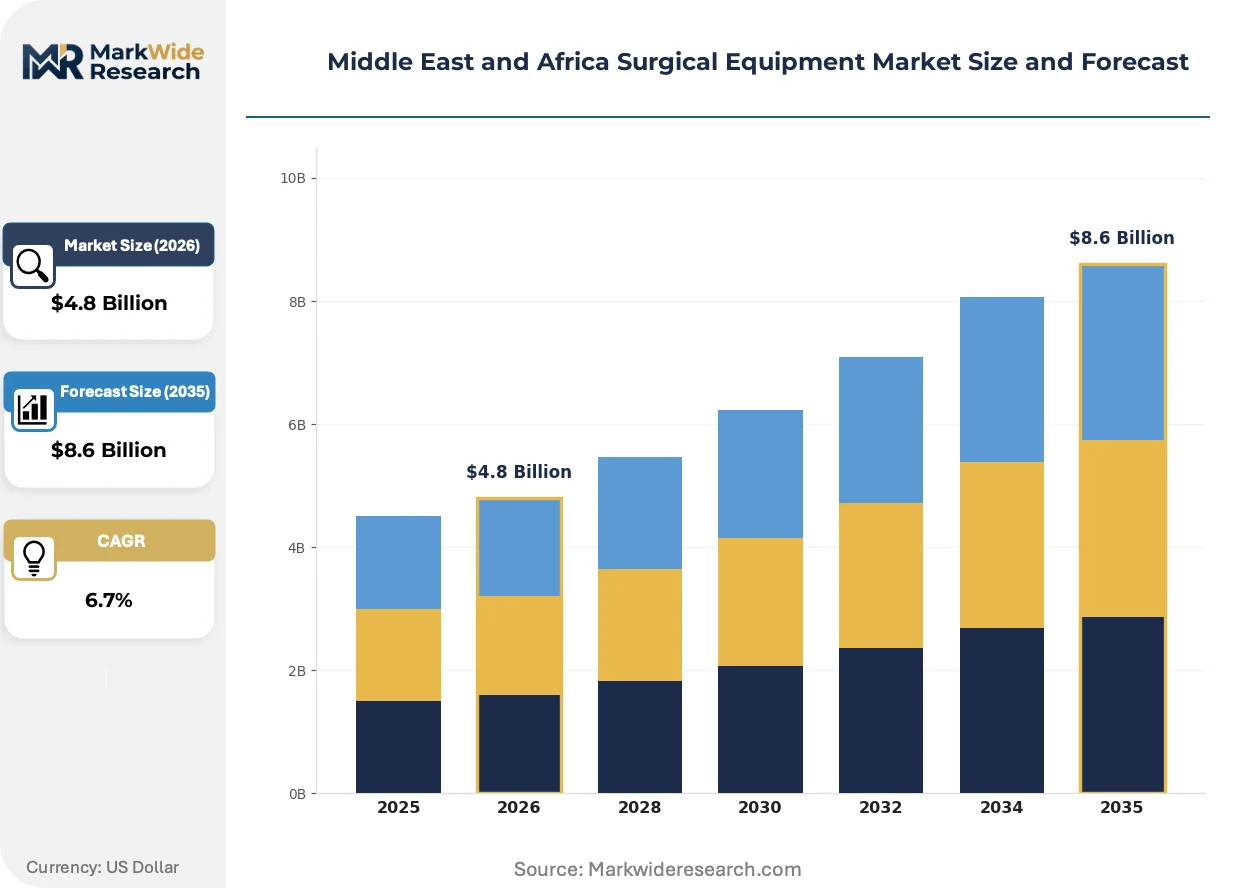
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Electrosurgical Devices, Sutures, Surgical Drapes End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Surgical Facilities Application: Orthopedic Surgery, Cardiovascular Surgery, Neurological Surgery, Cosmetic Surgery Technology: Robotic Surgery, Minimally Invasive Surgery, Conventional Surgery, Imaging Systems |
| Companies Covered | Medtronic PLC, Johnson & Johnson, Stryker Corp, B. Braun SE, Smith & Nephew PLC, Zimmer Biomet Holdings Inc, BD, GE HealthCare, Koninklijke Philips N.V., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Surgical Equipment Market Evolving Landscape
Disposable instrument miniaturization intersects with tightened sterilization standards across Middle East and Africa surgical workflows. Three developments are compressing equipment specifications and procurement patterns.
Single-use laparoscopic graspers and scissors are miniaturizing from 5mm to 3mm shaft diameters. Egyptian and Saudi bariatric centers adopt these profiles for reduced port trauma. The shift is compressing demand for reusable titanium instrument sets in high-volume facilities.
SFDA's 2024 sterilization validation circular mandates ethylene oxide residue testing for all imported polymer instruments. Manufacturers reconfigure packaging and aeration protocols. Saudi distributors absorb compliance costs or exit the market.
Ambulatory surgical centers in Johannesburg and Cape Town unbundle service contracts from capital equipment purchases. Buyers procure maintenance and training separately through third-party clinical engineering firms. The model spreads to Nigerian private hospital groups seeking cost transparency.
Middle East and Africa Surgical Equipment Market Segmentation
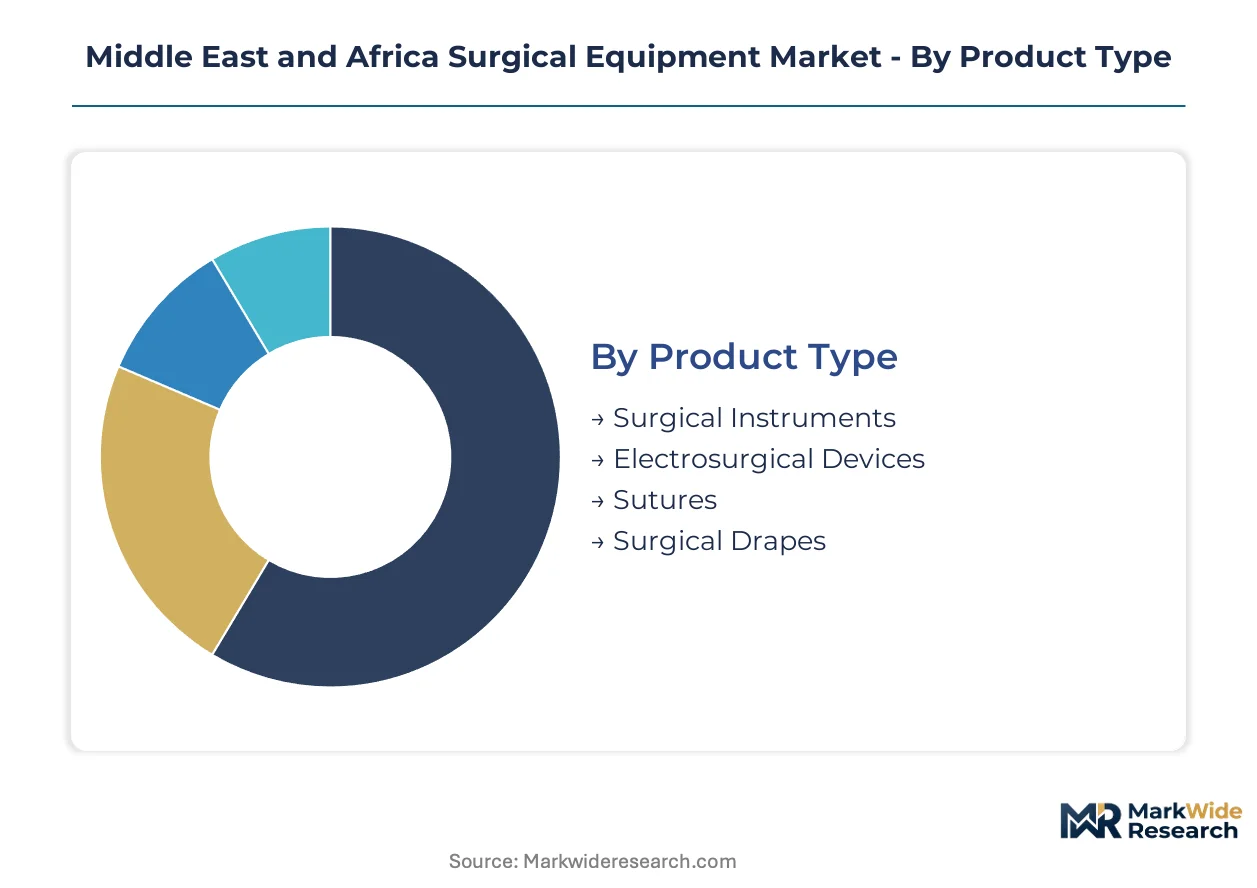
Surgical equipment procurement patterns across the Middle East and Africa diverge sharply between high-volume Gulf hospital networks and undercapitalized sub-Saharan facilities. Segmentation reveals where capital constraints, regulatory alignment, and procedure specialization reshape supplier priorities.
Product Type:
Electrosurgical devices face the most acute substitution pressure from disposable alternatives as SFDA sterilization protocols tighten validation costs for reusable systems.
- Surgical Instruments:Reusable forceps, retractors, and clamps manufactured from medical-grade stainless steel or titanium dominate procedure volumes across Egyptian and Nigerian public hospitals. Autoclave compatibility requirements and nickel price volatility squeeze margins on these metal instrument sets.
- Electrosurgical Devices:Radiofrequency generators with disposable electrode attachments command premium pricing in Saudi and UAE private chains. German and Japanese component concentration creates supply vulnerability, while SFDA predicate alignment accelerates registration for US-origin systems.
- Sutures:Absorbable and non-absorbable wound closure products generate the highest recurring revenue stream with thinner margins, serving cataract and arthroscopy volumes in South African ambulatory centers.
- Surgical Drapes:Single-use sterile barriers see expanding adoption in GCC facilities seeking to bypass reprocessing compliance burdens.
Surgical instruments retain volume leadership; electrosurgical devices hold the steepest expansion curve.
End User:
Procurement authority concentrates differently across customer types, with private hospital chains consolidating vendor relationships while government networks fragment purchasing.
- Hospitals:Saudi and UAE private chains negotiate multi-year service agreements bundling capital equipment, spare parts, and clinical training. Government hospital networks in Egypt and South Africa maintain fragmented tender processes with shorter contract horizons.
- Ambulatory Surgical Centers:Johannesburg and Cape Town facilities unbundle service contracts from equipment purchases, procuring maintenance through third-party clinical engineering firms. Laparoscopic tool procurement accelerates for cataract and arthroscopy procedures.
- Clinics:Smaller facilities in sub-Saharan Africa rely on conventional surgery instruments due to capital constraints and limited sterile processing infrastructure.
- Specialty Surgical Facilities:Orthopedic and bariatric centers in Cairo and Riyadh pilot hybrid robotic-laparoscopic platforms, absorbing disproportionate technology investment.
Hospitals dominate absolute spending; ambulatory surgical centers are climbing the fastest.
Application:
Procedure reimbursement rates and infrastructure requirements create divergent equipment specifications across surgical specialties.
- Orthopedic Surgery:Powered orthopedic tools and robotic platforms concentrate demand in South African and Egyptian centers. Mako-style systems compete for placement in high-volume joint replacement facilities.
- Cardiovascular Surgery:Precision electrosurgical generators and sternal closure systems serve the limited but high-value procedure base in Gulf tertiary hospitals.
- Neurological Surgery:Specialized micro-instruments and navigation systems face constrained demand due to surgeon training gaps and capital intensity across the region.
- Cosmetic Surgery:Liposuction cannulas and facial rejuvenation tools find growing private demand in UAE and Lebanese aesthetic clinics, though regulatory oversight varies.
Orthopedic surgery anchors capital equipment deployment; cosmetic surgery gains share fastest.
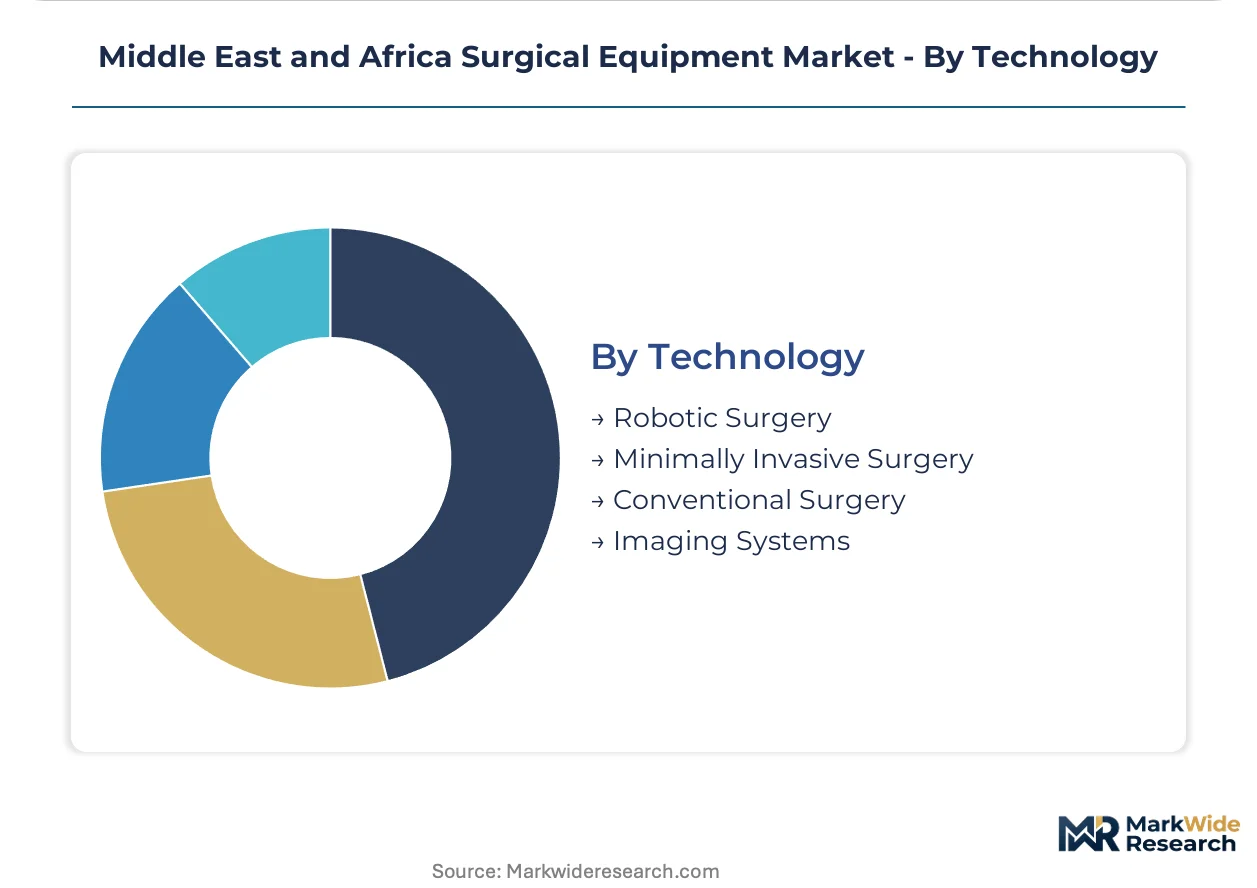
Technology:
Capital allocation skews toward integrated systems despite limited installed bases, while conventional methods persist in volume terms.
- Robotic Surgery:Haptic-feedback platforms absorb disproportionate infrastructure spending in Saudi and South African orthopedic centers. Limited surgeon training programs and maintenance networks constrain rollout beyond flagship facilities.
- Minimally Invasive Surgery:Laparoscopic towers and 3mm disposable graspers displace reusable titanium sets in Egyptian bariatric and Saudi general surgery workflows. Ethylene oxide residue testing mandates reshape packaging requirements.
- Conventional Surgery:Basic instrument sets still occupy the majority of procedure volumes across undercapitalized sub-Saharan facilities, particularly in Nigerian and Kenyan public hospitals.
- Imaging Systems:C-arm and endoscopic visualization towers integrate with laparoscopic stacks in GCC hospital construction projects, though legacy IT infrastructure delays full deployment.
Conventional surgery retains procedure volume leadership; minimally invasive surgery commands the steepest technology investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway connects Saudi Arabia and Bahrain, channeling surgical equipment flows through Gulf port infrastructure that underwrites the region's distribution dominance.
Saudi Arabia
Government hospital networks in Riyadh and Jeddah consolidate procurement for electrosurgical generators and robotic platforms. SFDA predicate alignment with FDA pathways accelerates device registration timelines for sterilized instrument sets. The King Faisal Specialist Hospital anchors high-volume orthopedic surgery demand in the capital corridor.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi's Cleveland Clinic Abu Dhabi drive demand for integrated operating room systems and minimally invasive toolsets. MOHAP enforces import licensing and sterilization validation that filters non-compliant suppliers from tender processes. Private hospital chains in Dubai negotiate multi-year service agreements bundling capital equipment with clinical training.
South Africa
Ambulatory surgical centers in Johannesburg and Cape Town expand laparoscopic procurement for cataract and arthroscopy procedures. The national health product regulator maintains fragmented tender processes with shorter contract horizons than Gulf counterparts. The Western Cape medical device cluster concentrates sterile processing infrastructure for reusable titanium instrument sets.
Egypt
Cairo's emerging medical device regulatory framework creates first-mover advantage for compliant suppliers as tender processes shift from informal to structured procurement. Bariatric centers in the capital pilot hybrid robotic-laparoscopic platforms. The Nile Delta corridor concentrates government hospital demand for conventional surgery instruments amid capital constraints.
Qatar
Hamad Medical Corporation drives procurement for powered orthopedic tools and electrosurgical systems in Doha's flagship facilities. Hospital infrastructure spending accelerates demand for single-use sterile barriers that bypass reprocessing compliance burdens. The Education City medical cluster anchors specialized surgical training programs that shape equipment specifications.
Middle East and Africa Surgical Equipment Market Competitive Landscape
Concentration sits with diversified multinationals that leverage electrosurgical portfolios and robotic platforms to anchor high-volume contracts. The vendor base spans three tiers: integrated conglomerates with full surgical portfolios, mid-scale specialists in sutures and wound closure, and regional distributors serving undercapitalized sub-Saharan facilities. Strategic moves center on direct hospital contracting that bypasses layered distribution, plus service bundling that locks in spare parts and training revenue.
Among US-based diversified medical technology conglomerates, Medtronic PLC, Johnson & Johnson, and Stryker Corp exemplify the integrated tier that dominates premium procurement channels. These entities represent archetypes of portfolio breadth, with Medtronic anchoring electrosurgical positioning, Johnson & Johnson exemplifying suture and consumables dominance, and Stryker occupying the robotic surgery integration vector. Their collective presence shapes tender specifications across Saudi and UAE private chains where multi-year agreements consolidate vendor relationships.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson |
| Stryker Corp |
| B. Braun SE |
| Smith & Nephew PLC |
| Zimmer Biomet Holdings Inc |
| BD |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese radiofrequency component plants sets price floors for electrosurgical generators across Gulf procurement pipelines, compressing margin for distributors serving Saudi and UAE hospital networks while elevating entry barriers for smaller Asian exporters facing SFDA documentation burdens.
Pricing Analysis
Volume-discount tiering structures separate premium electrosurgical systems bundled with multi-year service agreements from standard instrument sets and economy-grade reusable forceps. Price differentiation rests on SFDA predicate alignment certification and after-sales training inclusion, with Gulf private chains absorbing premium positioning while Egyptian and Nigerian public hospitals gravitate toward unbundled procurement. Cost compression in the reusable metal instrument tier is intensifying because nickel price volatility squeezes Turkish and Indian steel sourcing. Government hospital networks exhibit highest price sensitivity; integrated private chains prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes extend inbound logistics timelines for polymer-composite instruments requiring ethylene oxide residue validation. Geographic supply concentration centers on Germany and Japan for radiofrequency generator components, India and Turkey for medical-grade steel feedstock, and China for disposable laparoscopic tool molding. Raw material dependencies encompass nickel-chromium alloys, medical-grade titanium, and sterilization-grade polymer resins. Single-source vulnerability in German radiofrequency component supply propagates disruption risk through Gulf procurement pipelines. Distribution runs through layered distributor networks in sub-Saharan Africa and direct hospital contracting channels in Saudi Arabia and the UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA predicate alignment with FDA pathways constitutes a regulatory inflection compressing approval timelines and redrawing competitive access across Middle East and Africa surgical equipment procurement.
For Market Incumbents: Shield market position by deepening backward integration into radiofrequency component supply and securing captive sterilization validation capacity in Riyadh and Dubai. SFDA documentation burdens threaten smaller Asian competitors; incumbents should accelerate biocompatibility testing investment to widen compliance gaps. For New Entrants and Emerging Players: Anchor in Egypt's emerging regulatory formalization window before tender processes rigidify around incumbent certification profiles. Cairo's bariatric centers and Nile Delta government hospitals represent the most penetrable white-space; pursue direct contracting models unbundling service from capital equipment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consumables specialists with suture and disposable instrument portfolios serving South African ambulatory surgical centers. Long-term viability favors acquisition targets with established SFDA registration and spare parts logistics networks; monitor Egypt's regulatory framework maturation as inflection signal for market structure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Predicate Alignment Investment | Accelerates device registration timelines for sterilized instrument sets entering Saudi hospital networks. |
| Direct Hospital Contracting Expansion | Bypasses layered distributors to capture multi-year service agreements with UAE private chains. |
| Backward Integration into RF Components | Reduces single-source dependency on German and Japanese radiofrequency generator suppliers. |
| Egypt Regulatory First-Mover Positioning | Establishes compliant supplier status before Cairo's tender processes formalize around incumbent profiles. |
| Ambulatory Center Service Unbundling | Aligns with Johannesburg and Cape Town procurement models separating maintenance from capital purchases. |
Research Methodology
Cross-validation between hospital procurement databases and GPO contract filings anchors the qualitative findings across the Middle East and Africa surgical equipment landscape. Primary interviews with biomedical engineers, hospital purchasing committees, sterile processing technicians, and GPO contracts managers combined with secondary validation from SFDA device registration records, MOHAP import licensing data, and hospital construction pipeline disclosures. Bottom-up procedure volume estimates and top-down infrastructure spending analysis triangulate market sizing.
Sensitivity analysis across the projection horizon tests forecast robustness against nickel price volatility scenarios and SFDA regulatory timeline variations. Segmentation dimensions modeled encompass product type, end-user category, application specialty, and technology tier alongside regional regulatory cluster alignment. CAGRs derive from procedure volume trajectories, equipment replacement cycles, and infrastructure spending commitments. Industry-specific inputs include laparoscopic adoption rates in South African ambulatory centers and robotic surgery training program expansion in Saudi orthopedic facilities.
Decision-makers should treat outputs as directional under base assumptions of sustained Gulf hospital infrastructure spending and gradual Egyptian regulatory formalization; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Global Concussion Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Posture Correction Market