
 Antitussive Drugs Market | 2026-2036
Antitussive Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antitussive Drugs Market Outlook
Subscription-based patient monitoring tied to chronic cough management is hardening as a recurring revenue layer for pharmaceutical portfolios. Pfizer Inc. leverages its hospital formulary relationships to sustain preferential positioning for institutional antitussive procurement. GlaxoSmithKline plc anchors consumer-facing cough-cold portfolios through retail pharmacy channel dominance. Johnson & Johnson competes across both clinical and over-the-counter segments with differentiated formulation strengths.
Antitussive drugs function as centrally or peripherally acting agents that suppress the cough reflex through opioid receptor agonism, local anesthetic effects on pulmonary stretch receptors, or modulation of medullary cough centers, with specifications including precise dosing thresholds to avoid respiratory depression. The primary commercial purpose spans acute symptom relief in upper respiratory infections, chronic obstructive pulmonary disease exacerbations, and post-surgical recovery protocols. Dextromethorphan formulations capture expanding share in liquid and syrup delivery modes due to favorable safety profiles relative to codeine. Oral administration remains the mature volume base, while inhalation delivery represents the fastest-growing structural segment for targeted bronchial action. Retail pharmacies concentrate margin pools through private-label antitussive lines and pharmacist-directed substitution protocols.
The FDA's Controlled Substances Act scheduling and the EMA's pharmacovigilance frameworks constrain codeine-containing product distribution while accelerating demand for non-narcotic alternatives such as benzonatate and dextromethorphan. WHO essential medicines criteria and national formularies further stratify market access based on abuse-liability assessments and pediatric safety data. Stakeholders must monitor regulatory reclassification proceedings and real-world evidence requirements that will determine which formulations retain formulary placement versus forced reformulation toward non-scheduled actives.
Market Dynamics
The FDA's Controlled Substances Act scheduling of codeine is forcing manufacturers toward non-narcotic actives, restructuring formulation pipelines and procurement patterns across hospital and retail channels.
Growth Catalysts
- Post-operative protocols:Surgical recovery units in the United States sustain rising dextromethorphan procurement for cough suppression following anesthesia withdrawal.
- EMA pharmacovigilance frameworks:European safety monitoring accelerates demand for benzonatate as prescribers abandon opioid-linked alternatives.
- Liquid delivery innovation:Pediatric formulation specialists capture volume through palatable syrup vehicles that improve compliance in acute respiratory infections.
Market Restraints
- API supply concentration:Dextromethorphan bulk manufacturing clusters in Chinese chemical parks, exposing formulators to shipping disruptions and tariff volatility.
- Respiratory depression thresholds:Narrow therapeutic windows for centrally acting agents constrain dosing flexibility and limit combination product development.
- Generic substitution protocols:Retail pharmacy chains enforce automatic substitution of branded antitussives, compressing originator margins.
Strategic Opportunities
- Inhalation delivery expansion:Metered-dose devices targeting bronchial receptors offer faster onset than oral routes for acute exacerbation management.
- Chronic cough monitoring services:Subscription-based patient tracking creates recurring revenue streams tied to persistent respiratory conditions.
- India's domestic manufacturing:PLI scheme incentives for active pharmaceutical ingredients attract backward integration investments from multinational formulators.
Industry Challenges
- Abuse-deterrent formulation expertise:Shortage of pharmaceutical chemists skilled in tamper-resistant polymer matrix design delays product launches.
- Pediatric trial recruitment:Ethical constraints and parental consent complexity extend development timelines for age-appropriate dosing studies.
- Legacy system integration:Hospital pharmacy inventory management platforms require costly upgrades to track serialized controlled substance alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antitussive Drugs Market |
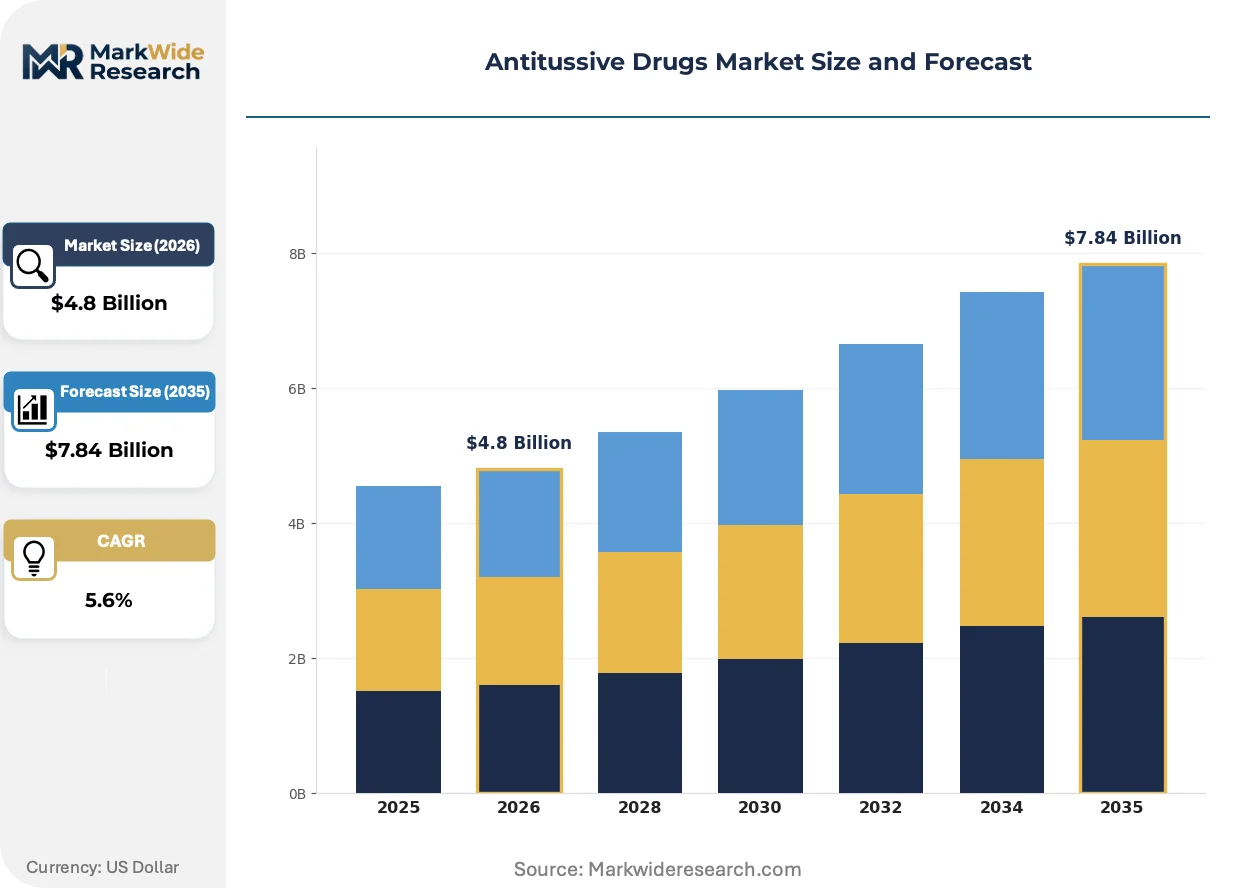
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Codeine, Dextromethorphan, Benzonatate, Phenylephrine Delivery Mode: Oral, Injectable, Inhalation, Topical End User: Hospitals, Clinics, Home Care, Retail Pharmacies Formulation: Liquid, Tablet, Capsule, Syrup |
| Companies Covered | F. Hoffmann-La Roche Ltd., Pfizer Inc., GlaxoSmithKline plc, Sanofi, Teva Pharmaceutical Industries Ltd., Novartis AG, Johnson & Johnson, Reckitt Benckiser, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antitussive Drugs Market Strategic Shifts
Formulation science and delivery mechanism innovation are compressing development cycles while regulatory pressure on opioid actives accelerates investment in peripherally acting alternatives.
Controlled-release polymer matrices are automating the once-manual process of dose-titration for chronic cough patients. Hospital formularies in Germany and Japan are adopting these platforms to reduce nursing administration burden. The technology is automating adherence monitoring through embedded sensors that transmit consumption data to prescribing physicians.
REACH substance restrictions on certain excipients are compelling European manufacturers to reformulate liquid antitussives with plant-derived alternatives. The regulation is accelerating R&D spending on natural polymer stabilizers that meet biodegradability criteria. Pediatric syrup producers face the steepest compliance costs, with several German facilities retrofitting production lines to eliminate restricted surfactants.
Pharmacist-directed therapeutic substitution is displacing physician-prescribed brand loyalty in United States retail channels. Chain pharmacy protocols now auto-substitute dextromethorphan for codeine unless explicit carve-outs appear on electronic prescriptions. This behavioral shift concentrates margin capture with private-label house brands, particularly visible in CVS and Walgreens formulary positioning.
Antitussive Drugs Market Segmentation
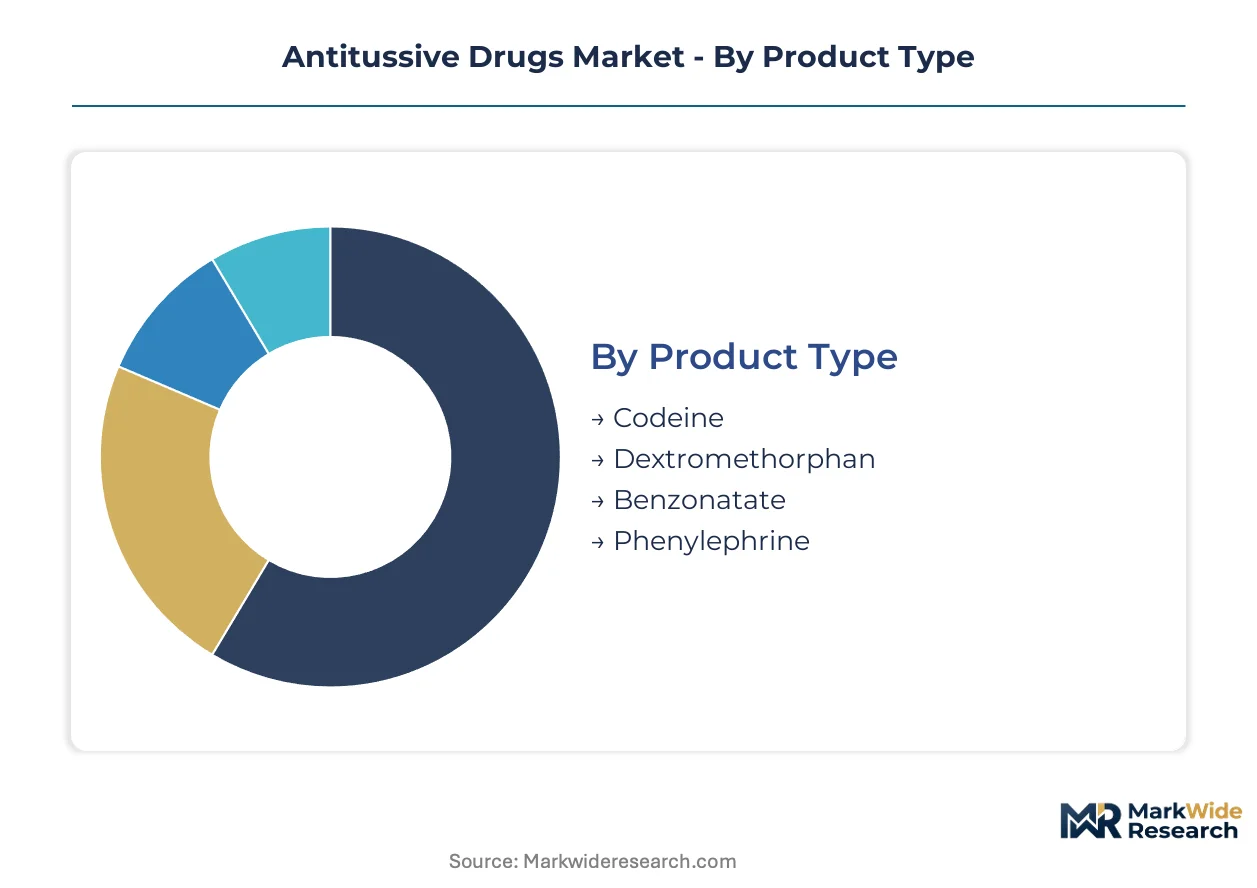
Antitussive market stratification reveals how formulation choices and procurement channels determine revenue capture. Each segmentation axis exposes distinct margin structures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Replacement cycles for opioid-based therapies accelerate as scheduling constraints force formulary revisions toward safer actives.
- Codeine:Centrally acting opioid agonist with established efficacy in suppressing medullary cough centers. Hospital formularies in the United States restrict procurement to controlled-substance protocols, driving volume erosion toward non-narcotic substitutes.
- Dextromethorphan:Non-opioid NMDA receptor antagonist delivering comparable cough suppression without respiratory depression risk. Retail pharmacy chains favor this active for automatic substitution programs, concentrating volume in private-label house brands.
- Benzonatate:Peripherally acting anesthetic agent numbing pulmonary stretch receptors. EMA pharmacovigilance frameworks accelerate prescriber migration from opioid alternatives.
- Phenylephrine:Decongestant adjunct in combination antitussive formulations. FDA efficacy scrutiny limits standalone positioning.
Dextromethorphan sits at the top of the volume ranking, with benzonatate climbing the fastest.
Delivery Mode:
Cost tier differentiation separates acute intervention formats from maintenance therapy vehicles.
- Oral:Mature administration route dominating outpatient prescriptions. Tablet and liquid formats sustain manufacturing scale advantages.
- Injectable:Hospital-exclusive delivery for post-operative patients unable to tolerate oral intake. Surgical recovery units in Germany and Japan drive institutional procurement.
- Inhalation:Metered-dose devices targeting bronchial receptors with rapid onset kinetics. Device development costs limit competitor entry.
- Topical:Transdermal patches and chest rubs capturing pediatric and geriatric compliance segments. Formulation stability challenges constrain geographic expansion.
Oral administration commands the largest installed base, though inhalation delivery gains share fastest among acute exacerbation protocols.
End User:
Customer type segmentation maps directly to reimbursement mechanics and procurement authority concentration.
- Hospitals:Institutional formularies governed by pharmacy and therapeutics committees. Dextromethorphan procurement rises for post-anesthesia cough management.
- Clinics:Outpatient settings with prescriber discretion over branded versus generic selection. Physician preference samples influence initial therapy choice.
- Home Care:Long-term respiratory patients requiring chronic cough suppression. Subscription monitoring services create recurring revenue attachment.
- Retail Pharmacies:CVS and Walgreens auto-substitution protocols displace physician brand loyalty. Private-label margins concentrate with chain house brands.
Retail pharmacies generate the highest transaction frequency, while hospitals anchor the steepest per-unit value capture.
Formulation:
Supply concentration in liquid manufacturing clusters exposes formulators to excipient regulation and shipping disruption risks.
- Liquid:Pediatric-focused vehicles with palatability engineering for compliance improvement. REACH substance restrictions force European producers toward plant-derived stabilizers.
- Tablet:Solid-dose formats enabling precise unit-dose packaging and extended-release matrix design. Controlled-release polymer technology reduces nursing administration burden.
- Capsule:Gelatin and vegetarian shell alternatives for adult outpatient markets. Bioavailability consistency separates originator from generic positioning.
- Syrup:Viscous formulations with flavor masking for acute respiratory infection episodes. German facilities retrofit production lines to eliminate restricted surfactants.
Tablets lead manufacturing throughput, with liquid formulations expanding fastest in pediatric and geriatric compliance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital formularies adopt controlled-release antitussive platforms faster than Japan's surgical recovery units, yet both markets face converging pressures from opioid scheduling restrictions and pediatric formulation compliance costs.
United States
Seasonal respiratory illness patterns drive consistent dextromethorphan consumption through CVS and Walgreens auto-substitution protocols. The FDA's Controlled Substances Act scheduling constrains codeine distribution while accelerating prescriber migration toward non-narcotic alternatives. Philadelphia and New Jersey pharmaceutical corridors concentrate formulation R&D investments in abuse-deterrent polymer matrices.
Germany
Hospital pharmacy and therapeutics committees prioritize controlled-release antitussive platforms to reduce nursing administration burden in post-operative units. REACH substance restrictions force retrofitting of liquid formulation production lines to eliminate restricted surfactants. Bavarian chemical parks host specialized excipient manufacturers developing plant-derived stabilizers for pediatric syrups.
Japan
Surgical recovery units in Tokyo and Osaka metropolitan areas sustain institutional procurement of metered-dose inhalation devices for acute cough suppression. METI guidelines on pharmaceutical manufacturing quality influence regional adoption of embedded sensor technologies for adherence monitoring. Nagoya-area device specialists collaborate with formulators on bronchial-targeted delivery systems.
India
Domestic API manufacturing expansion under the PLI scheme attracts backward integration investments from multinational formulators seeking dextromethorphan supply chain resilience. CDSCO pediatric safety data requirements extend development timelines for age-appropriate dosing studies. Hyderabad and Ahmedabad clusters concentrate bulk active production for export to European and North American markets.
China
Dextromethorphan bulk manufacturing concentration in Yangtze River Delta chemical parks exposes formulators to shipping disruptions and tariff volatility. NMPA pharmacovigilance frameworks align with international standards for respiratory depression risk assessment. Shanghai-based contract manufacturers upgrade facilities to meet serialization requirements for controlled substance alternatives.
Antitussive Drugs Market Competitive Environment
Top-tier vendors anchor hospital formulary relationships and retail pharmacy channel dominance, while mid-tier specialists compete on pediatric formulation expertise and regional manufacturing proximity. The vendor base stratifies across three archetypes: diversified pharmaceutical conglomerates with cough-cold portfolio breadth, API-integrated formulators controlling active supply, and device-specialized delivery innovators. M&A activity concentrates on pediatric formulation capabilities and inhalation delivery platforms. Geographic expansion into India's PLI-incentivized manufacturing zones represents a secondary competitive vector.
Within the diversified pharmaceutical tier, Pfizer Inc., GlaxoSmithKline plc, and Johnson & Johnson occupy positions reflecting distinct channel strategies. Pfizer exemplifies institutional formulary anchoring through hospital pharmacy relationships. GlaxoSmithKline represents consumer-facing portfolio dominance via retail pharmacy channel control. Johnson & Johnson sits within a hybrid positioning spanning clinical and over-the-counter segments with differentiated formulation strengths. These three entities collectively illustrate how scale-driven players balance regulatory compliance investments across multiple jurisdiction frameworks.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Johnson & Johnson |
| Reckitt Benckiser |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical chemists skilled in tamper-resistant polymer matrix design cluster in Philadelphia and New Jersey corridors, where labor-cost differentials between specialized formulation scientists and standard manufacturing technicians widen pricing-tier spreads across abuse-deterrent and conventional antitussive products.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for dextromethorphan bulk actives. Three-tier pricing structure across premium, standard, and economy levels separates originator brands with embedded sensor adherence monitoring from private-label house brands and unbranded generics. Price differentiation hinges on FDA scheduling status and formulation complexity. Pricing pressure stems from retail pharmacy auto-substitution protocols that compress originator margins. Hospital procurement committees demonstrate lowest price sensitivity due to formulary anchoring, while retail chain buyers enforce aggressive cost compression.
Supply Chain Analysis
Workforce availability for specialized excipient manufacturing concentrates in Bavarian chemical parks and Yangtze River Delta hubs. Dextromethorphan bulk production draws from China and India, while plant-derived stabilizer R&D rests on German facilities. API supply is anchored in Hyderabad and Ahmedabad clusters for export markets. Single-source vulnerability in Chinese chemical parks exposes formulators to shipping disruptions and tariff volatility. Distribution runs through hospital pharmacy and therapeutics committees for institutional procurement, with retail pharmacy chains capturing margin pools through private-label substitution protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in antitussive formulations depends on cost-down drivers in Indian API manufacturing and premium-tier shifts toward controlled-release polymer platforms with embedded adherence monitoring.
For Market Incumbents: Deepen hospital formulary relationships through controlled-release platform adoption that reduces nursing administration burden. Anchor procurement contracts with surgical recovery units in Germany and Japan to defend against generic substitution threats. Invest in backward integration into Indian API supply under PLI incentives to secure cost-competitive dextromethorphan sourcing. For New Entrants and Emerging Players: The price-point gap between premium sensor-enabled formulations and economy-tier syrups creates entry space for mid-market device-formulator partnerships. Target inhalation delivery platforms for acute exacerbation protocols where device development costs limit incumbent expansion. Pursue white-label manufacturing arrangements with CVS and Walgreens private-label programs as the fastest penetration vector. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with cough-cold portfolio breadth are the most active acquirer in this space, seeking pediatric formulation capabilities and inhalation delivery platforms. Long-term viability centers on regulatory resilience across multiple jurisdiction frameworks rather than single-market dominance. Monitor FDA scheduling reclassification proceedings as the critical inflection signal for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | PLI scheme incentives in India secure dextromethorphan supply chain resilience against Chinese concentration risk. |
| Controlled-Release Platform Development | Polymer matrix automation reduces nursing burden in German hospital formularies and commands premium positioning. |
| Pediatric Formulation Specialization | Palatable syrup vehicles with plant-derived stabilizers capture compliance-critical segments under REACH restrictions. |
| Inhalation Delivery Partnership | Metered-dose device collaborations with Nagoya-area specialists target acute bronchial receptor action. |
| Subscription Monitoring Service Launch | Recurring revenue attachment to chronic cough patients creates pharmaceutical portfolio annuity streams. |
Study Parameters
Bottom-up hospital and retail pharmacy modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and pharmacy chain category buyers combine with secondary validation from FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov records, and national formulary placement data. Triangulation between prescriber behavior patterns and manufacturer shipment records ensures demand-side and supply-side estimates converge.
Input-output matrices connect dextromethorphan bulk production volumes to finished formulation throughput across oral, inhalation, and injectable delivery modes. Segmentation dimensions span product type, delivery mode, end user, and formulation format, with regional regulatory cluster overlays capturing FDA, EMA, and NMPA framework divergences. CAGRs derive from patient population epidemiology, seasonal respiratory illness patterns, and post-operative protocol adoption curves across surgical recovery units.
Caveats apply where FDA scheduling reclassification, EMA pharmacovigilance framework expansion, or Chinese chemical park disruption could materially shift the outlook. Forecasts reflect assumptions around prescriber migration velocity from opioid to non-narcotic actives and pediatric trial recruitment timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Apixaban Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Injectable Drugs Market
Pharmacology
Semaglutide API Market
Pharmacology
Olanzapine API Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Aspirin API Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Cough Remedies Market