
 Chromium Trioxide Market | 2026-2036
Chromium Trioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Trioxide Market Analysis
Premium electrochemical grade chromium trioxide is decoupling from commodity industrial grade supply chains on purity thresholds and lot-traceability requirements. Lanxess AG leverages its integrated chromite-to-derivative platform to sustain European supply security for aerospace-qualified material. Vishnu Chemicals anchors South Asian demand through captive chromite processing and regional distribution density.
Chromium trioxide is a dark red crystalline solid with the chemical formula CrO₃, produced primarily through the sodium dichromate-sulfuric acid reaction; it serves as the principal industrial source of hexavalent chromium for surface treatment and chemical synthesis. Industrial grade material dominates volume throughput for wood preservation and bulk pigment production, while electrochemical grade commands concentrated margin pools from semiconductor and precision aerospace applications. Metal finishing absorbs the largest application share, though electroplating for electronics substrates represents the fastest-expanding demand node as miniaturization tightens coating uniformity specifications.
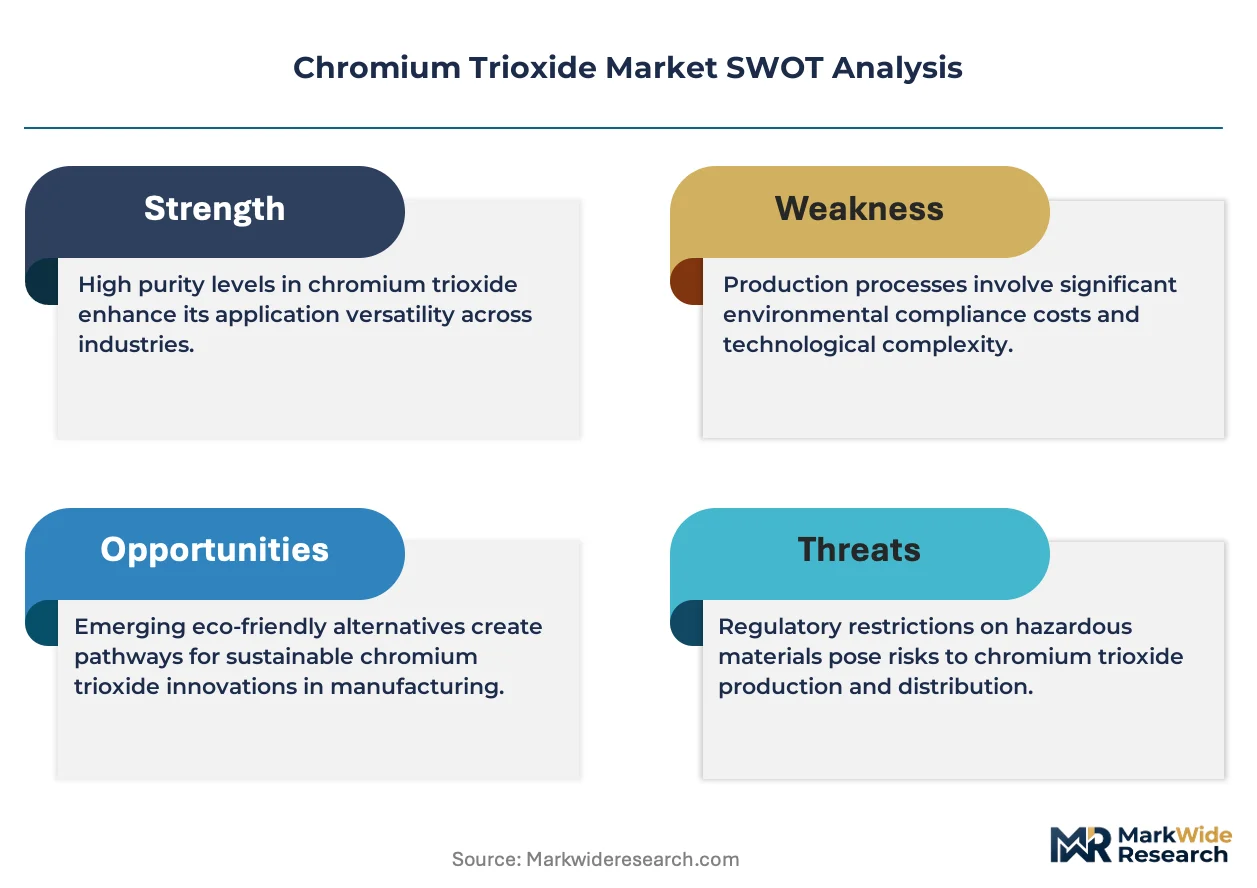
REACH restrictions on carcinogenic substance authorization and OSHA hexavalent chromium permissible exposure limits constrain product formulation and workplace handling protocols across manufacturing economies. China's GB standards and SAMR chemical registration requirements shape import access and domestic production compliance for foreign suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with market entry sequencing.
Market Dynamics
REACH authorization pressures and OSHA exposure limits are forcing chromium trioxide users into closed-loop application systems, while aerospace demand for electrochemical-grade material tightens supply availability for commodity applications.
Growth Catalysts
- Electronics miniaturization:Semiconductor substrate plating specifications now require sub-micron coating uniformity that only electrochemical-grade chromium trioxide delivers.
- REACH authorization renewal:European aerospace manufacturers secured continued hexavalent chromium use for corrosion-critical airframe components through 2027.
- China's electroplating base:Domestic chemical producers in Shandong and Jiangsu provinces expanded captive chromite processing to serve regional automotive and hardware plating demand.
Market Restraints
- Chromite ore concentration:South African and Kazakh mining operations control over 70% of global chromite supply, creating geopolitical exposure for derivative producers.
- Trivalent chromium substitution:Decorative plating applications in consumer goods manufacturing increasingly migrate to chromium(III) sulfate formulations.
- OSHA PEL compliance costs:US metal finishing shops face capital outlays for exhaust ventilation and personal protective equipment monitoring systems.
Strategic Opportunities
- Closed-loop plating systems:German and French equipment manufacturers now bundle chromium trioxide recovery units with new installation contracts.
- India's PLI scheme:Electronics manufacturing incentives in Gujarat and Tamil Nadu are attracting electroplating capacity that requires high-purity hexavalent chromium feedstock.
- Precision aerospace coatings:Thermal barrier coating applications for next-generation turbine blades represent an emerging demand node beyond traditional plating.
Industry Challenges
- Electrochemical-grade certification timelines:Lot-traceability documentation and third-party purity verification add 12-18 months to supplier qualification cycles.
- Waste treatment capex:Chromium(VI) reduction and sludge handling infrastructure requires substantial upfront investment for plating shops facing regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Trioxide Market |
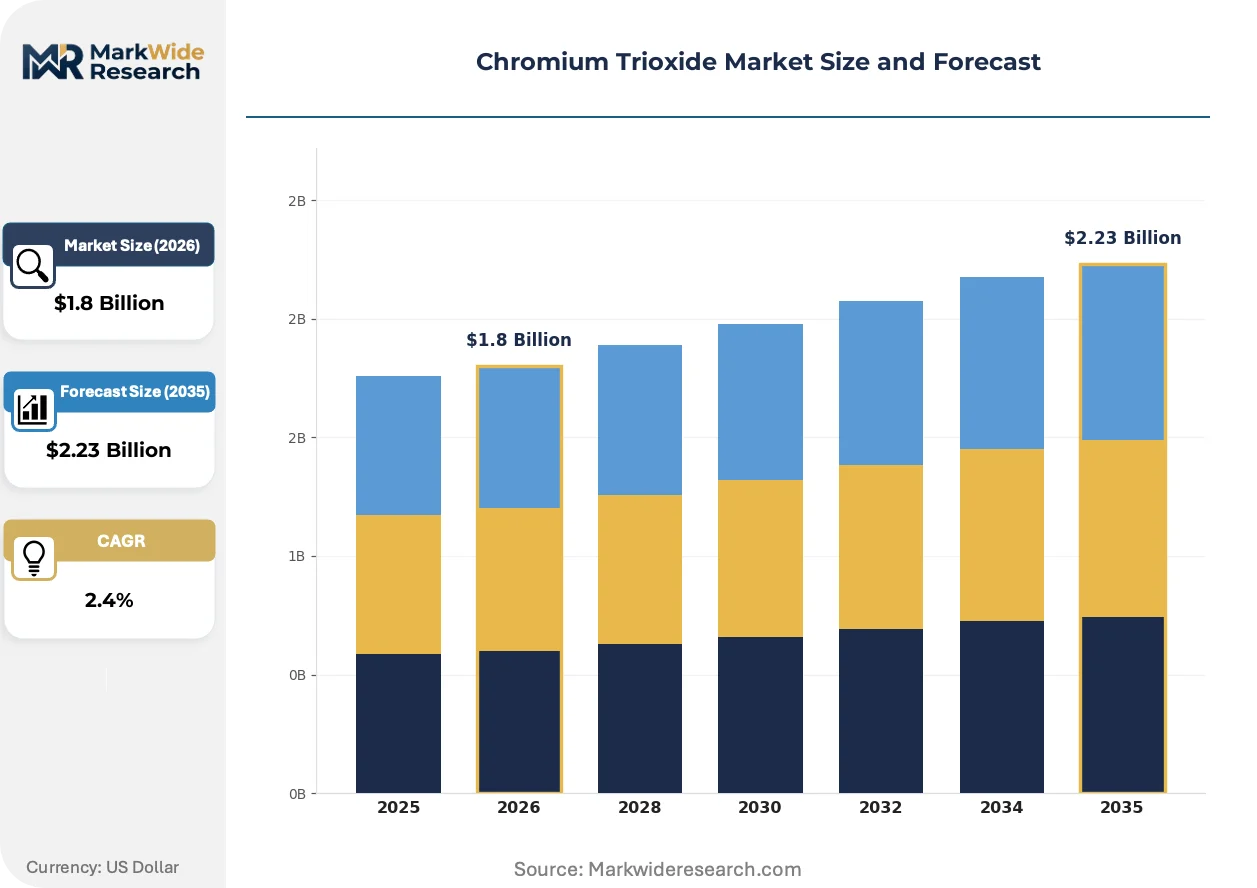
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Anhydrous Grade, Electrochemical Grade Application: Metal Finishing, Wood Preservation, Pigment Production, Electroplating End User: Aerospace, Automotive, Electronics, Manufacturing Packaging Type: Drum, Bag, Bottle, Bulk |
| Companies Covered | Hubei Zhenhua Chemical, Soda Sanayii A.S., Lanxess AG, Oxkem Ltd, Chongqing Minfeng Chemical, Nippon Chemical Industrial Co., Sichuan Yinhe Chemical, Elementis PLC, Vishnu Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Trioxide Market Emerging Trajectories
Application technology and regulatory compliance systems are converging to reshape how hexavalent chromium reaches end-use manufacturing, with purity segmentation and closed-loop handling emerging as decisive competitive differentiators.
Membrane-cell chromium trioxide production is consolidating electrochemical-grade supply chains around continuous-flow reactor designs that eliminate batch-to-batch variation. Aerospace-qualified suppliers in Germany and the United States are adopting these systems to meet lot-traceability mandates from Boeing and Airbus. The technology is consolidating premium-grade production into facilities capable of ISO 17025-certified analytical laboratories.
REACH sunset date extensions for chromium trioxide authorization are forcing European manufacturers into downstream-user consortiums that pool toxicology data and exposure scenario documentation. ECHA review timelines now stretch 24-36 months for new use category approvals. Metal finishing operations in Italy and Poland are responding by consolidating into larger entities with dedicated regulatory affairs capabilities.
Long-term supply agreements are displacing spot-market purchasing for electrochemical-grade material as semiconductor and aerospace buyers seek allocation security. Japanese and South Korean electronics substrate manufacturers now contract directly with chromite-to-derivative integrated producers rather than distributors. This pattern is most visible in Taiwan's printed circuit board cluster, where three-year offtake contracts have become standard procurement practice.
Chromium Trioxide Market Segmentation
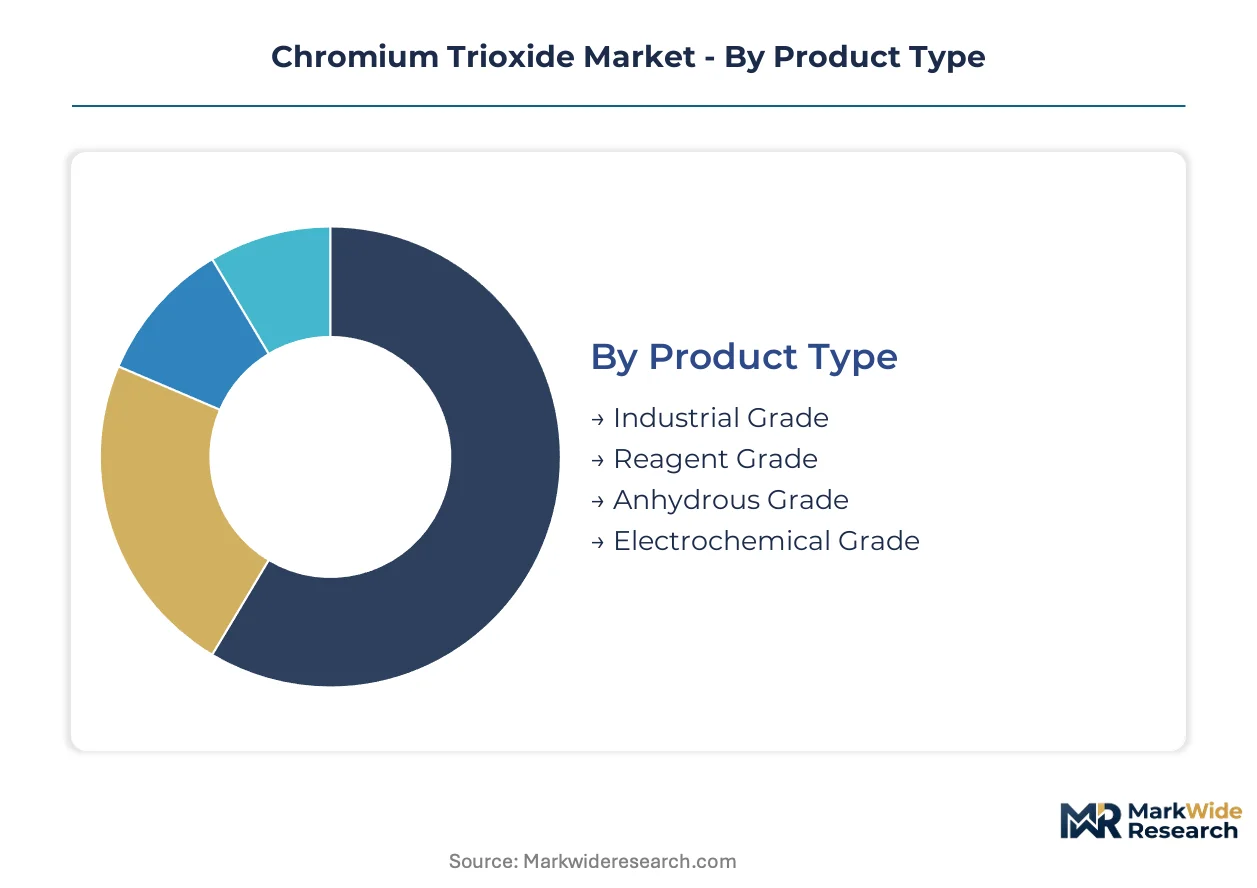
Purity thresholds and lot-traceability requirements are fragmenting chromium trioxide supply chains into parallel commodity and premium ecosystems. Aerospace-qualified material now commands distinct procurement protocols from bulk industrial grades, reshaping how producers allocate capacity and how buyers structure supplier relationships.
Product Type:
Volume throughput concentrates in commodity grades serving wood preservation and bulk pigment markets, while margin pools accrue to electrochemical material for semiconductor and aerospace applications.
- Electrochemical Grade:Membrane-cell continuous-flow reactor designs deliver sub-batch variation essential for semiconductor substrate plating specifications. Taiwan's printed circuit board cluster and South Korean electronics substrate manufacturers now contract directly with chromite-to-derivative integrated producers for three-year offtake agreements, bypassing distributor channels entirely.
- Industrial Grade:Sodium dichromate-sulfuric acid reaction output dominates tonnage for wood preservation and bulk chromium pigment production. REACH authorization pressures and OSHA exposure limits are forcing users into closed-loop application systems, constraining spot-market availability as larger plating operations consolidate purchasing.
- Reagent Grade:Laboratory and analytical chemistry applications in pharmaceutical and environmental testing laboratories require documented purity certificates.
- Anhydrous Grade:Specialized chemical synthesis feedstock for chromium-based catalyst production in polymer manufacturing.
Today's leader: Industrial Grade. Tomorrow's challenger: Electrochemical Grade.
Application:
Metal finishing absorbs the largest share of hexavalent chromium consumption, though electronics miniaturization is redirecting capacity toward coating uniformity specifications that only premium grades satisfy.
- Metal Finishing:Corrosion-resistant coatings for aerospace airframe components and automotive hardware constitute the foundational demand base. Boeing and Airbus lot-traceability mandates have consolidated aerospace-qualified supply around ISO 17025-certified analytical laboratories in Germany and the United States.
- Electroplating:Sub-micron coating uniformity requirements for semiconductor substrates represent the steepest expansion trajectory as miniaturization tightens specifications. China's electroplating base in Shandong and Jiangsu provinces expanded captive chromite processing to serve regional automotive and hardware plating demand.
- Wood Preservation:Chromated copper arsenate alternatives and pressure-treatment applications for utility poles and marine pilings.
- Pigment Production:Chromium oxide green and lead chromate pigment intermediates for coatings and plastics coloration.
Metal finishing commands current volume. Electroplating for electronics substrates is climbing the fastest.
End User:
Aerospace procurement patterns are decoupling from automotive and general manufacturing through dedicated qualification timelines and long-term supply security requirements.
- Aerospace:Corrosion-critical airframe components and thermal barrier coatings for next-generation turbine blades require 12-18 month supplier qualification cycles for lot-traceability documentation. European manufacturers secured REACH authorization renewal for hexavalent chromium use through 2027.
- Electronics:Semiconductor and printed circuit board substrate plating specifications now require direct contracting with chromite-to-derivative integrated producers rather than distributor relationships.
- Automotive:Decorative and functional plating for exterior trim, engine components, and hardware fasteners faces trivalent chromium substitution pressure in consumer-visible applications.
- Manufacturing:General industrial plating, tool hardening, and surface treatment operations across machinery and equipment production.
Aerospace sets the premium standard. Electronics is gaining share fastest.
Packaging Type:
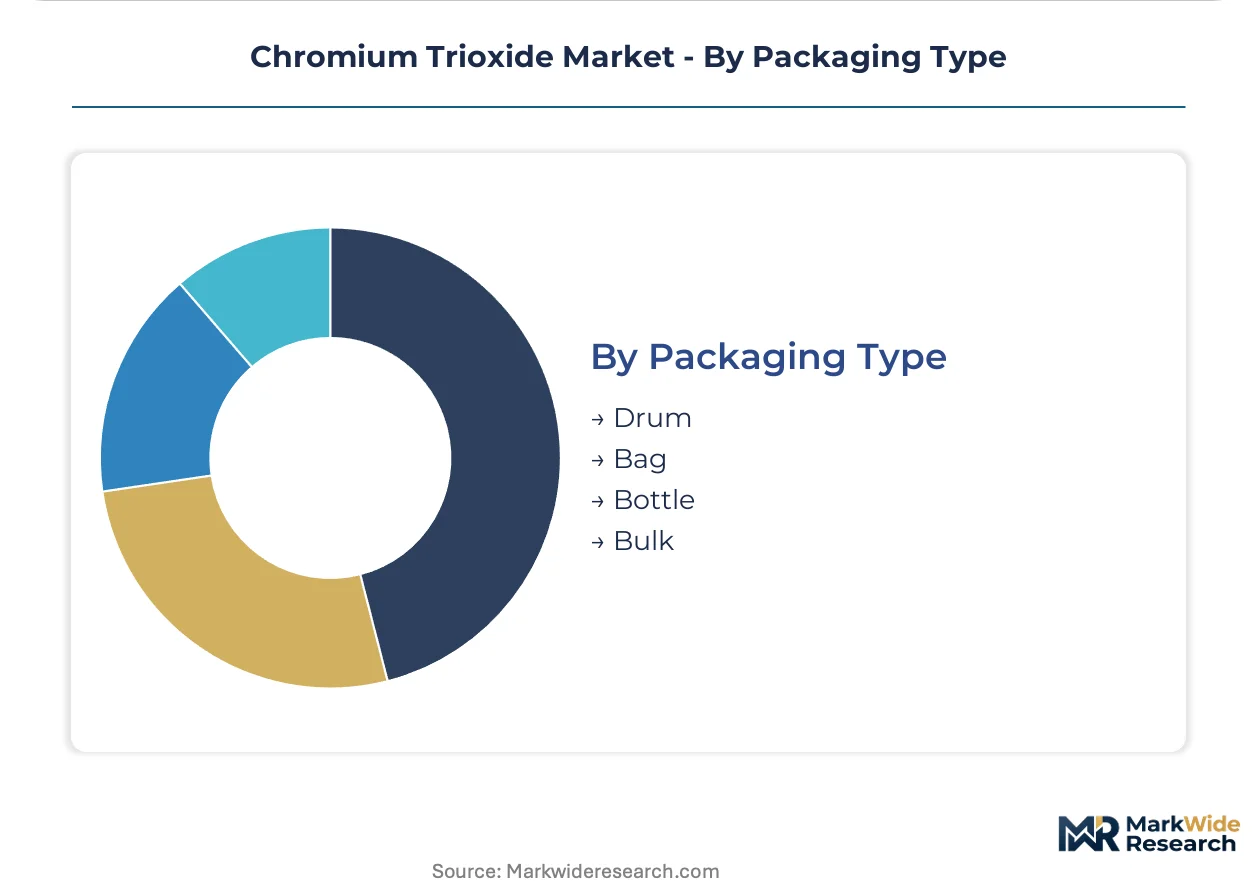
Regulatory compliance costs and handling protocol stringency are segmenting packaging selection by end-user scale and exposure control requirements.
- Drum:Standard 200-250 kg steel drums dominate mid-volume electroplating and metal finishing operations requiring controlled dispensing.
- Bulk:Tanker and hopper deliveries serve large integrated chemical producers and continuous-flow plating systems with recovery unit integration.
- Bag:Multi-layer laminated bags for moisture-sensitive anhydrous grade material in specialized chemical synthesis.
- Bottle:Laboratory-scale reagent grade packaging for analytical and research applications.
Drum packaging leads current logistics. Bulk delivery is expanding most quickly as closed-loop systems consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electroplating technicians and chemical process engineers concentrate in industrial clusters where aerospace and electronics manufacturing intersect, anchoring regional demand patterns for high-purity hexavalent chromium feedstock.
United States
Aerospace airframe production in Washington and South Carolina sustains electrochemical-grade consumption for corrosion-resistant coatings. OSHA hexavalent chromium permissible exposure limits drive capital investment in exhaust ventilation systems across metal finishing shops. The printed circuit board cluster in California's Silicon Valley contracts directly with chromite-to-derivative integrated producers for three-year supply security.
Germany
REACH authorization renewal through 2027 secures continued hexavalent chromium use for Boeing and Airbus supply chains. ECHA review timelines stretching 24-36 months force downstream-user consortiums to pool toxicology data. The industrial corridor between Cologne and Leverkusen hosts membrane-cell continuous-flow reactor facilities serving semiconductor substrate manufacturers.
China
Domestic chemical producers in Shandong and Jiangsu provinces expanded captive chromite processing to serve automotive and hardware plating demand. SAMR chemical registration requirements and GB standards shape import access for foreign suppliers. The Yangtze River Delta electroplating base concentrates regional consumption for electronics and automotive components.
India
Electronics manufacturing incentives under the PLI scheme in Gujarat and Tamil Nadu attract electroplating capacity requiring high-purity hexavalent chromium feedstock. BIS certification mandates govern industrial chemical import quality. Vishnu Chemicals anchors South Asian demand through captive chromite processing and regional distribution density from its Andhra Pradesh operations.
Japan
Semiconductor substrate manufacturers in Kyushu and the Kanto region contract directly with integrated chromite-to-derivative producers rather than distributors. METI industrial chemical handling guidelines shape workplace exposure protocols. The Osaka-Tokyo electronics corridor represents concentrated demand for sub-micron coating uniformity specifications.
Chromium Trioxide Market Vendor Landscape
Top-tier vendors anchor electrochemical-grade supply chains with ISO 17025-certified analytical laboratories, while commodity-grade producers compete on chromite ore access and regional distribution density. The vendor base stratifies across three archetypes: integrated chromite-to-derivative platforms, regional electroplating chemical specialists, and captive aerospace-qualified suppliers. Competitive moves center on backward integration into chromite mining concessions and technology licensing for membrane-cell continuous-flow reactor designs.
Among integrated chromite-to-derivative platforms, Lanxess AG exemplifies the European aerospace-qualified supplier archetype with its Leverkusen-based operations. Vishnu Chemicals occupies a position within the South Asian regional specialist tier, anchoring demand through captive processing capabilities. Hubei Zhenhua Chemical and Sichuan Yinhe Chemical represent the Chinese domestic producer archetype, serving Shandong and Jiangsu province electroplating clusters with expanded captive chromite processing capacity.
| Leading Market Players |
|---|
| Hubei Zhenhua Chemical |
| Soda Sanayii A.S. |
| Lanxess AG |
| Oxkem Ltd |
| Chongqing Minfeng Chemical |
| Nippon Chemical Industrial Co. |
| Sichuan Yinhe Chemical |
| Elementis PLC |
| Vishnu Chemicals |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements from semiconductor substrate manufacturers are displacing spot-market purchasing and forcing electrochemical-grade producers into dedicated allocation contracts that compress pricing flexibility for commodity-grade buyers.
Pricing Analysis
Bundled closed-loop plating systems with integrated chromium trioxide recovery units command premium positioning against unbundled chemical-only supply. Three-tier pricing structure across electrochemical, industrial, and reagent grades reflects lot-traceability certification and ISO 17025 laboratory access. Cost compression in industrial-grade spot markets is intensifying because REACH-authorized users consolidate purchasing into larger downstream consortiums. Electronics substrate manufacturers show least price sensitivity due to coating uniformity specifications, while decorative plating shops face acute margin pressure from trivalent chromium substitution.
Supply Chain Analysis
Lot-traceability documentation and third-party purity verification add 12-18 months to supplier qualification cycles, gating electrochemical-grade supply chains around ISO 17025-certified analytical laboratories. Chromite ore draws from South African and Kazakh mining operations, with derivative production concentrating in Germany, China, and the United States. Sodium dichromate and sulfuric acid feedstock costs hinge on energy-intensive processing economics. Single-source vulnerability runs through South African chromite concentration exceeding 70% of global supply. Distribution feeds from chromite-to-derivative integrated producers directly to semiconductor and aerospace buyers, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronics miniaturization and aerospace corrosion protection requirements position chromium trioxide as a stable compounder anchored by specification-tight demand that resists substitution.
For Market Incumbents: To counter trivalent chromium substitution in decorative plating, deepen captive chromite processing capacity in South Asia and secure ECHA authorization renewal documentation for downstream-user consortiums. Backward integration into membrane-cell continuous-flow reactor technology protects electrochemical-grade margin pools from batch-variation competitors. For New Entrants and Emerging Players: Begin with India's PLI scheme electronics manufacturing incentives in Gujarat and Tamil Nadu, where electroplating capacity expansion outruns qualified hexavalent chromium supply. Target thermal barrier coating applications for next-generation turbine blades as the most penetrable aerospace segment outside established airframe plating relationships. Pursue direct contracting with semiconductor substrate manufacturers seeking supply security beyond distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with chromite-to-derivative integrated platforms possessing ISO 17025-certified analytical laboratories and existing aerospace qualification timelines. Five-to-ten year viability rests on regulatory authorization continuity rather than technology displacement risk. Watch for ECHA review timeline acceleration or South African mining concession instability as inflection indicators requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Mining | South African and Kazakh concession access insulates derivative producers from supply disruption and price volatility. |
| Membrane-Cell Continuous-Flow Reactor Deployment | German and U.S. aerospace-qualified facilities adopt continuous-flow designs to eliminate batch-to-batch purity variation. |
| Long-term Supply Agreement Structuring | Taiwan's printed circuit board cluster now contracts directly with integrated producers for three-year offtake security. |
| Closed-Loop Plating System Bundling | French and German equipment manufacturers bundle recovery units with new installation contracts to meet OSHA exposure limits. |
| Downstream-User Consortium Formation | Italian and Polish metal finishing operations consolidate to pool REACH toxicology data and ECHA exposure documentation. |
Methodological Framework
Bottom-up electroplating and metal finishing demand modeling reconciled against top-down chromite ore supply tracking forms the analytical core of this study. Primary interviews with plant managers at plating operations, procurement leads at semiconductor substrate manufacturers, distribution channel partners in specialty chemicals, and technical R&D directors at aerospace-qualified suppliers combined with secondary validation from customs trade data, ECHA authorization registries, SEC 10-K filings from listed chemical producers, and REACH downstream-user consortium disclosures. Triangulation between bottom-up end-use consumption estimates and top-down production capacity assessments ensures cross-verified output integrity.
Input-output matrices map chromite ore extraction through sodium dichromate intermediate production to derivative chromium trioxide output across the modeling period. Segmentation dimensions include grade tier (electrochemical, industrial, reagent, anhydrous), end-use industry (aerospace, electronics, automotive, manufacturing), packaging format (drum, bulk, bag, bottle), and regional production hub. CAGRs derive from regression analysis against historical consumption patterns and projected specification-tight demand expansion. Forecast inputs incorporate REACH authorization renewal timelines, OSHA permissible exposure limit compliance cost trajectories, and semiconductor miniaturization-driven coating uniformity requirements.
Caveats apply where ECHA review timeline acceleration, South African mining concession instability, or trivalent chromium substitution breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory authorization continuity and chromite ore supply concentration. A model refresh is warranted upon material change in REACH sunset date extensions or aerospace procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Desalination Chemicals Market
Chemicals
Power Plant Chemicals Market
Chemicals
South Korea Methanol Market
Chemicals
Oxybenzone Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Europe Methanol Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Antiozonant Market
Chemicals
Potassium Fluoride Market
Chemicals
Iscotrizinol Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Germany Methanol Market