
 Oxybenzone Market | 2026-2036
Oxybenzone Market Size, Share, and Industry Trends Forecast 2026-2036
Oxybenzone Market Analytics
Specialty dermatology clinics is collapsing as the dominant buyer archetype in oxybenzone procurement, displacing mass-market retailers who once controlled bulk orders. BASF SE leverages its integrated aromatics chain to sustain cost advantages in benzophenone-3 synthesis. Evonik Industries AG anchors European supply through its specialty chemicals network. Hangzhou Sunny Chemical dominates Asian merchant sales with concentrated production in Zhejiang province.
Oxybenzone, chemically benzophenone-3, functions as an organic UV-B filter absorbing radiation in the 280-320 nm wavelength range through a conjugated carbonyl structure that undergoes reversible photoisomerization. Manufacturers incorporate this compound at concentrations up to six percent in sunscreen formulations to prevent photodegradation of co-formulants while maintaining broad-spectrum protection. Personal care applications lead volume consumption due to entrenched sunscreen demand, though pharmaceutical-grade specifications command premium pricing through tighter purity thresholds. Emulsion formulations occupy the largest share of oxybenzone consumption as consumers prefer spreadable textures over gel or spray alternatives.
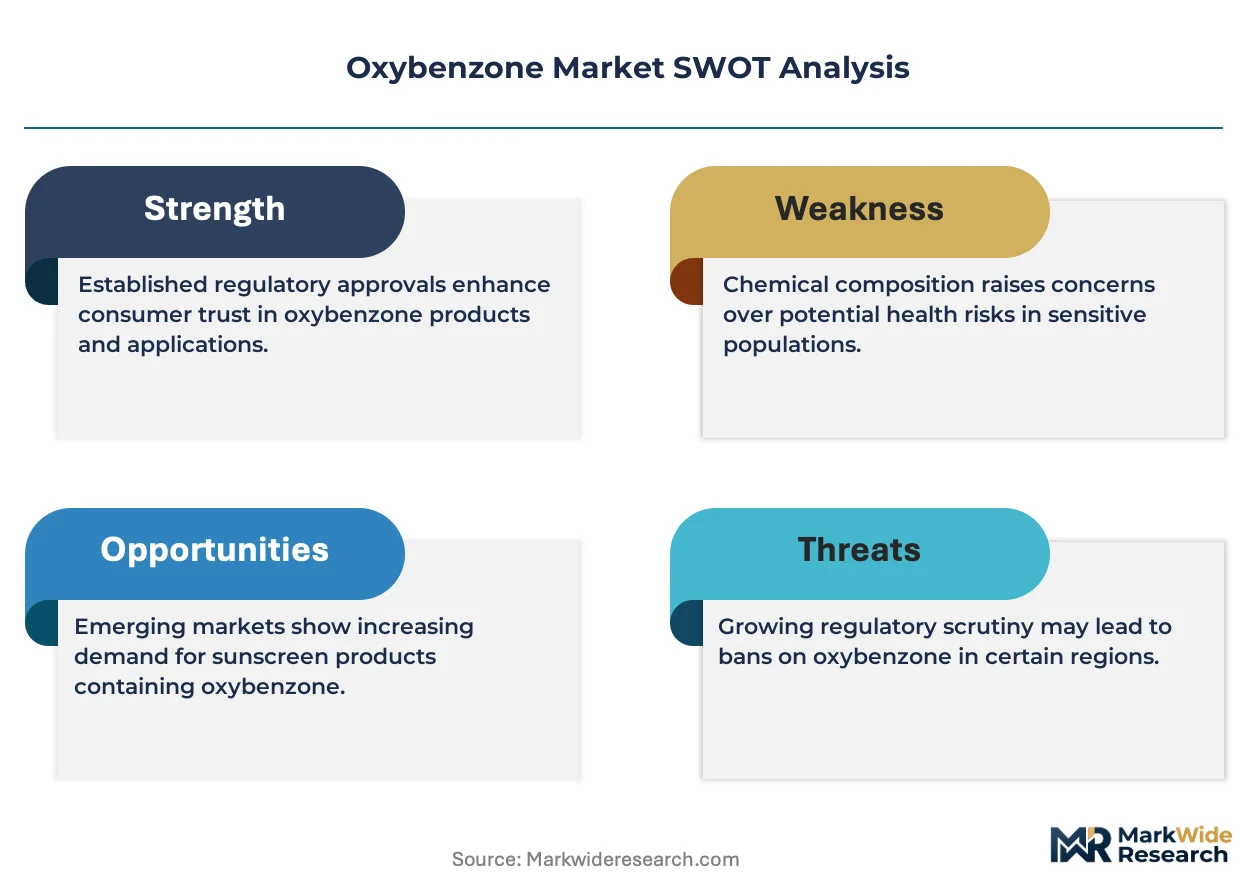
The US FDA regulates oxybenzone as an over-the-counter drug ingredient under the Sunscreen Monograph, while Hawaii and Key West enforce bans on reef-toxic formulations that exclude this chemical entirely. The EU's REACH framework classifies benzophenone-3 as a suspected endocrine disruptor, compelling substitution investments across cosmetic supply chains. India's CDSCO and BIS jointly oversee import quality standards for UV filters used in domestic personal care manufacturing. Stakeholders must monitor regulatory divergence between jurisdictions that permit oxybenzone and those accelerating phase-out timelines.
Market Dynamics
Specialty dermatology clinics are collapsing the traditional mass-retail procurement model for oxybenzone, while REACH-driven reformulation costs compound across European supply chains and India's personal care manufacturing belt concentrates volume demand around Mumbai and Ahmedabad.
Growth Catalysts
- Personal care manufacturing expansion:India's CDSCO and BIS joint oversight streamlines import quality standards for UV filters, accelerating domestic sunscreen production capacity around Gujarat and Maharashtra.
- REACH substitution mandates:The EU's endocrine disruptor classification forces cosmetic supply chains to invest in alternative formulation R&D, sustaining demand for compliant benzophenone-3 grades during transition periods.
- Emulsion formulation preference:Consumer texture preferences for spreadable sunscreens lock in oxybenzone incorporation at concentrations up to six percent, stabilizing volume offtake from personal care compounders.
Market Restraints
- Input cost volatility in aromatics feedstocks:Benzene and acetone price swings transmit directly into benzophenone-3 synthesis economics, compressing margin predictability for non-integrated producers.
- Regulatory friction from reef-toxicity bans:Hawaii and Key West prohibition regimes exclude oxybenzone entirely from coastal sunscreen sales, fragmenting addressable market geography.
- Substitution threat from mineral UV filters:Zinc oxide and titanium dioxide formulations capture reef-conscious consumer segments without endocrine disruptor liability.
Strategic Opportunities
- Pharmaceutical-grade specification premium:Tighter purity thresholds for dermatological applications command pricing differentiation above personal care commodity grades.
- Channel innovation through direct clinic supply:Specialty dermatology procurement bypasses traditional distributor markups, enabling margin capture through captive pharmacy networks.
- Regulatory tailwind in India's PLI scheme:Production-linked incentives for active pharmaceutical ingredients and specialty chemicals subsidize domestic benzophenone-3 capacity expansion.
Industry Challenges
- Reformulation capex intensity:REACH-compliant substitution investments require dedicated pilot-scale equipment and toxicology testing budgets that strain mid-tier compounders.
- Certification timeline compression:CDSCO import quality standard updates demand accelerated dossier preparation, delaying market entry for new supply sources.
- Photoisomerization stability engineering:Reversible UV-B absorption chemistry requires sophisticated formulation expertise to prevent photodegradation in finished sunscreen products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxybenzone Market |
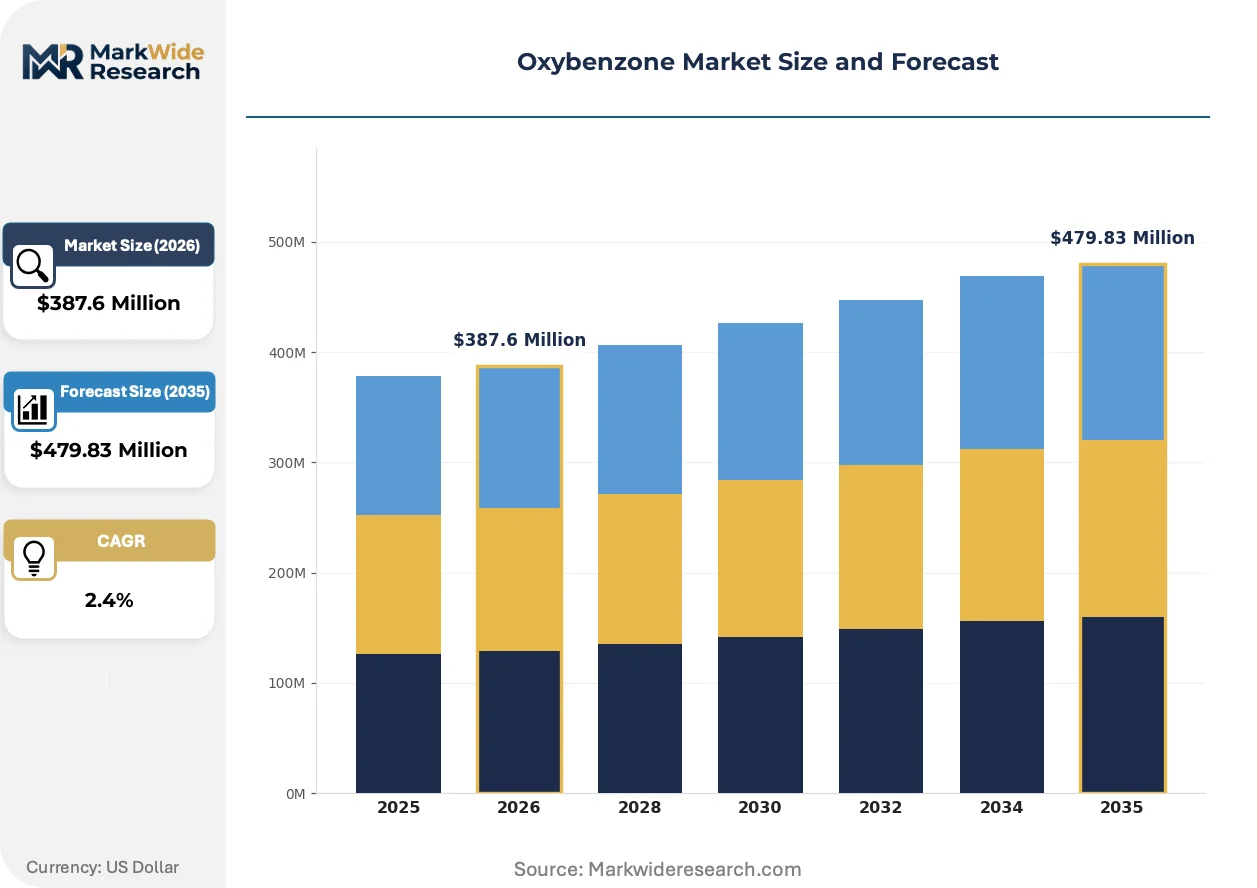
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $479.83 Million |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreens, Cosmetics, Lotions, Creams End User: Consumers, Dermatologists, Retailers, Manufacturers Application: Personal Care, Pharmaceuticals, Nutraceuticals, Household Products Formulation Type: Emulsions, Gels, Sprays, Powders |
| Companies Covered | BASF SE, Merck KGaA, Evonik Industries AG, Solvay S.A., 3V Sigma, SI Group, Clariant AG, Everlight Chemical Industrial Corp., Hangzhou Sunny Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxybenzone Market Evolving Landscape
Reversible photoisomerization chemistry is reshaping competitive positioning as manufacturers engineer stability into benzophenone-3 formulations, while regulatory divergence between jurisdictions accelerates formulation portfolio diversification strategies.
Encapsulation technology is displacing conventional bulk oxybenzone incorporation in premium sunscreen lines. Microsphere and lipid-shell delivery systems isolate the UV-B filter from direct skin contact, addressing endocrine disruptor concerns without abandoning proven photoprotection performance. Specialty dermatology clinics in Germany and France are adopting these formats fastest, compressing demand for unencapsulated commodity grades.
REACH's suspected endocrine disruptor classification for benzophenone-3 is forcing cosmetic supply chains into parallel formulation tracks. European manufacturers must maintain oxybenzone-free portfolios for domestic compliance while preserving traditional formulations for export markets without equivalent restrictions. Personal care exporters in India face the steepest compliance burden, as their Mumbai and Ahmedabad production hubs serve both regulatory regimes simultaneously.
Direct procurement from compounders is replacing traditional distributor intermediation in clinic-channel supply. Specialty dermatology networks now source benzophenone-3 through qualified API suppliers rather than personal care chemical distributors, unbundling technical service from logistics. This pattern concentrates most visibly in Germany's clinic-owned pharmacy chains and India's corporate hospital dermatology departments.
Oxybenzone Market Segmentation
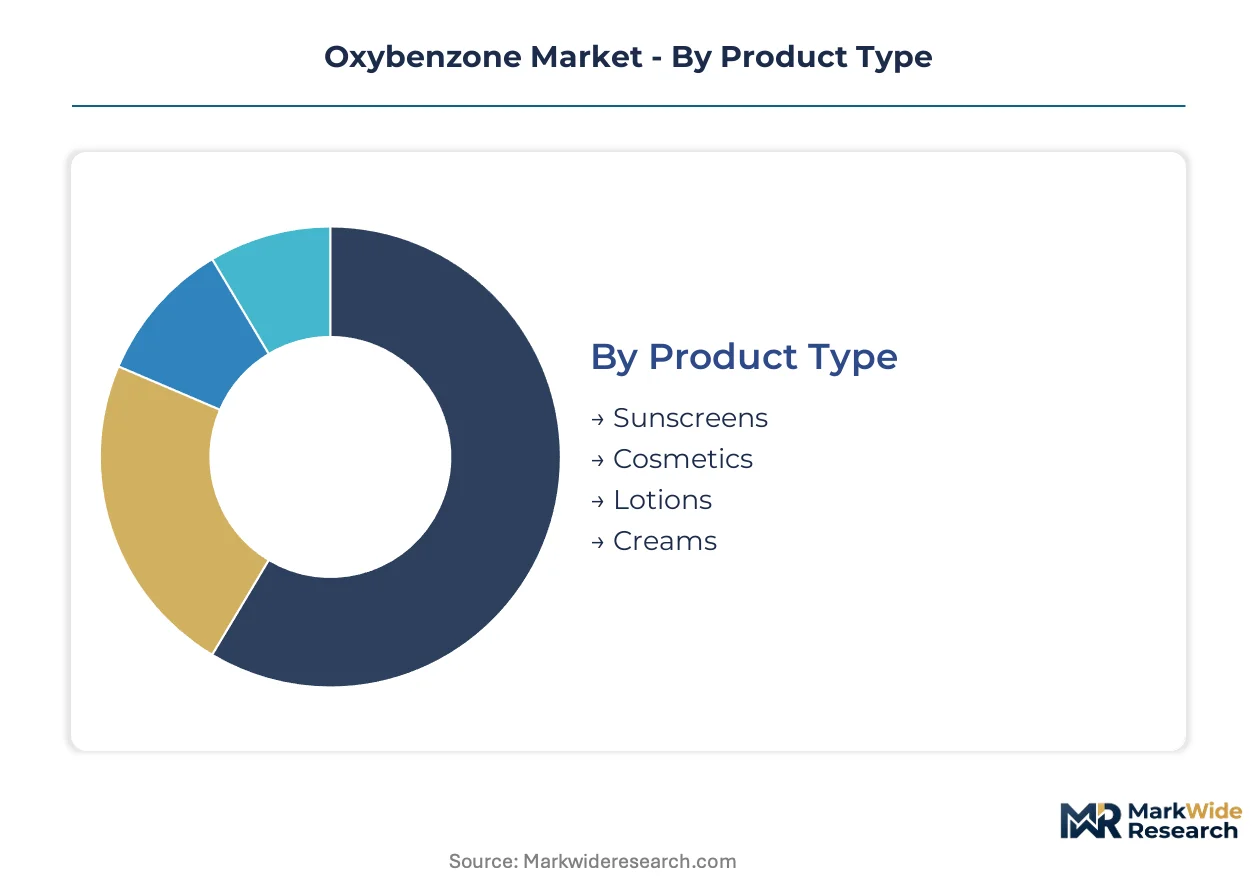
Oxybenzone demand fragments across formulation chemistry, professional versus consumer channels, and regulatory compliance tiers. Substitution pressures from mineral UV filters and REACH-driven reformulation create divergent growth trajectories within each slice.
Product Type:
Substitution threat from zinc oxide and titanium dioxide formulations concentrates most intensely in reef-conscious coastal markets, forcing product-level strategic pivots.
- Sunscreens:Formulations incorporate benzophenone-3 at concentrations up to six percent through conjugated carbonyl structures that absorb UV-B radiation in the 280-320 nm range. Demand concentrates in India's Mumbai-Ahmedabad manufacturing belt where CDSCO oversight streamlines domestic production capacity. REACH's endocrine disruptor classification in Europe forces parallel formulation tracks for export compliance.
- Cosmetics:Color cosmetic applications leverage oxybenzone for photostabilization of dye compounds and fragrance components. Specialty dermatology clinics in Germany and France are adopting encapsulated formats fastest, compressing demand for unencapsulated commodity grades in premium lines.
- Lotions:Spreadable textures dominate consumer preference over alternatives, locking in emulsion-compatible oxybenzone incorporation.
- Creams:Thicker formulations serve pharmaceutical-grade specifications with tighter purity thresholds commanding premium pricing differentiation.
Sunscreens retain volume leadership; Cosmetics holds the steepest expansion curve.
End User:
Procurement authority is shifting from mass-market intermediaries toward qualified compounders with direct clinic relationships, reshaping margin capture across the value chain.
- Consumers:Individual purchasers drive volume through retail channel selection, with texture preferences for spreadable emulsions stabilizing oxybenzone offtake.
- Dermatologists:Specialty clinic networks now source benzophenone-3 through API suppliers rather than personal care distributors, bypassing traditional markups. Germany's clinic-owned pharmacy chains and India's corporate hospital dermatology departments concentrate this pattern most visibly.
- Retailers:Mass-market intermediaries face collapsing procurement control as direct compounder relationships displace bulk order aggregation.
- Manufacturers:Personal care compounders in Gujarat and Maharashtra integrate backward into benzophenone-3 synthesis under India's PLI scheme subsidies for specialty chemicals.
Manufacturers retain volume leadership; Dermatologists hold the steepest expansion curve.
Application:
Regulatory divergence between jurisdictions permitting oxybenzone and those accelerating phase-out timelines forces application-level portfolio diversification strategies.
- Personal Care:Entrenched sunscreen demand leads volume consumption, though emulsion formulation preferences lock in specific incorporation chemistries. India's CDSCO and BIS joint oversight streamlines import quality standards for UV filters used in domestic production.
- Pharmaceuticals:Dermatological applications command premium pricing through tighter purity thresholds, with specialty clinics driving faster volume uptake than mass retail channels.
- Nutraceuticals:Limited penetration due to oral toxicity concerns restricts oxybenzone incorporation to topical delivery formats.
- Household Products:Functional UV protection for packaging and surface applications represents niche demand outside cosmetic supply chains.
Personal Care retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
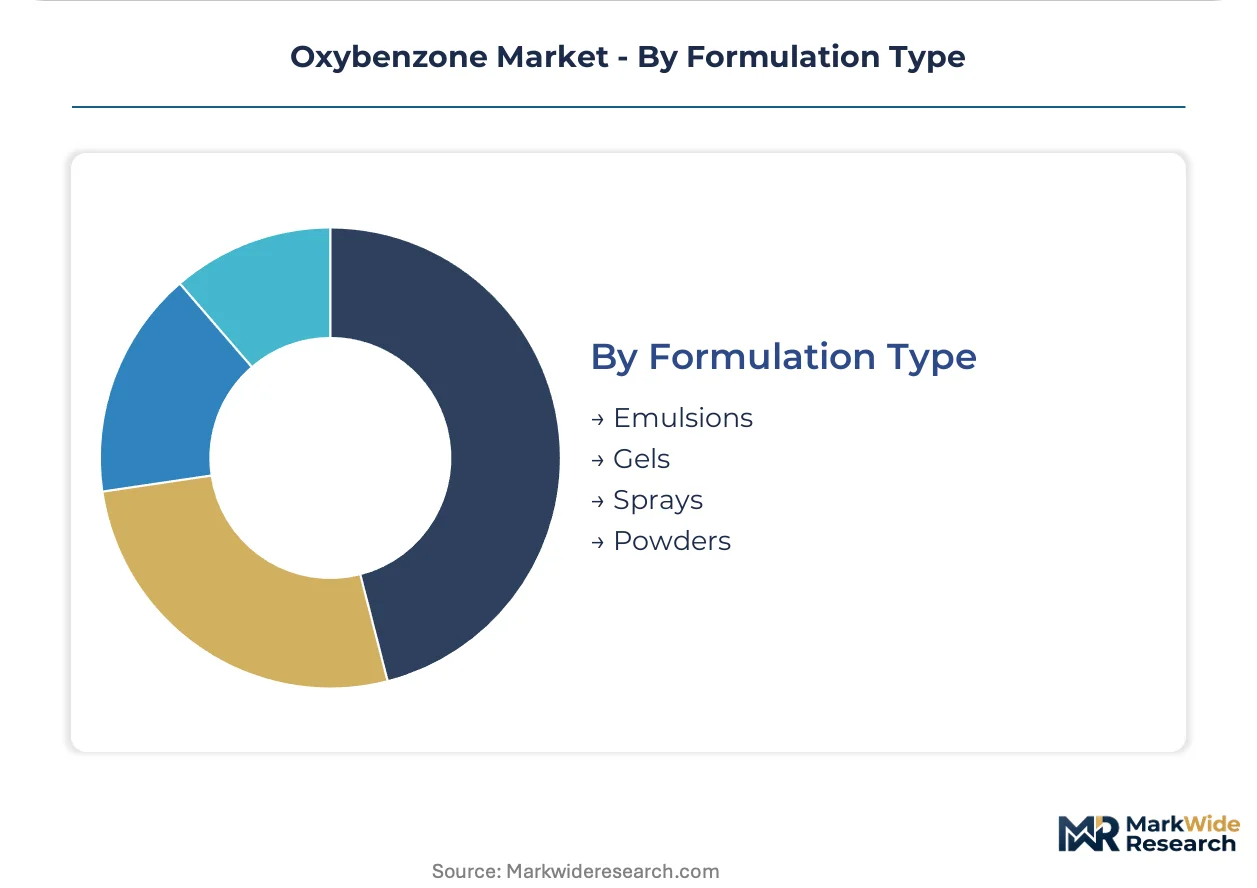
Formulation Type:
Consumer texture preferences and photostability engineering requirements concentrate demand toward spreadable, reversible photoisomerization-compatible delivery systems.
- Emulsions:Spreadable textures occupy the largest share of oxybenzone consumption as consumers prefer them over gel or spray alternatives. Microsphere and lipid-shell encapsulation systems isolate the UV-B filter from direct skin contact in premium European lines.
- Gels:Clear formulations serve specific cosmetic aesthetics, though photoisomerization stability engineering demands sophisticated formulation expertise to prevent photodegradation.
- Sprays:Aerosol and pump formats face reef-toxicity ban exclusions in Hawaii and Key West, fragmenting addressable market geography for this delivery mode.
- Powders:Dry formulations serve mineral-composite hybrid applications with limited pure oxybenzone incorporation.
Emulsions retain volume leadership; Gels holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated aromatics producers cluster in Germany and the United States, while formulation demand concentrates in India's western manufacturing belt and coastal Chinese provinces serving export markets.
United States
Dermatology clinic networks in Florida and California drive specialty-grade procurement despite Hawaii's reef-toxicity ban excluding oxybenzone from coastal sunscreen sales. FDA Sunscreen Monograph oversight maintains OTC drug classification for benzophenone-3, preserving formulation pathways for inland markets. Houston and New Jersey host benzophenone derivative production serving North American personal care compounders.
Germany
REACH's suspected endocrine disruptor classification forces cosmetic supply chains into parallel formulation tracks for domestic compliance versus export markets. ECHA regulatory pressure sustains demand for compliant benzophenone-3 grades during transition periods. BASF SE's integrated Ludwigshafen complex anchors European benzophenone-3 synthesis capacity.
India
CDSCO and BIS joint oversight streamlines import quality standards for UV filters, accelerating domestic sunscreen production capacity around Gujarat and Maharashtra. PLI scheme subsidies for specialty chemicals support backward integration into benzophenone-3 synthesis. Mumbai and Ahmedabad concentrate personal care manufacturing demand for emulsion-compatible grades.
China
Zhejiang province hosts concentrated benzophenone-3 merchant production serving Asian formulation houses. Hangzhou Sunny Chemical anchors regional supply through specialty chemicals distribution networks. Export-oriented personal care manufacturers in Jiangsu and Guangdong provinces maintain dual-formulation portfolios for regulated versus unregulated destination markets.
France
ANSM oversight of cosmetic ingredients reinforces ECHA-driven substitution investments across domestic supply chains. Specialty dermatology clinics in Paris and Lyon adopt encapsulated oxybenzone formats fastest, compressing demand for unencapsulated commodity grades. Rhône-Alpes region hosts pharmaceutical-grade specification production for dermatological applications.
Oxybenzone Market Competitive Landscape
Concentration sits with integrated chemical conglomerates possessing captive aromatics feedstock positions. The vendor base stratifies across three tiers: multinational diversified chemicals groups with backward integration into benzene derivatives, regional specialty chemical distributors serving formulation houses, and merchant producers concentrated in Asian manufacturing zones. Strategic moves center on REACH-compliant grade development and direct clinic-channel supply relationships bypassing traditional distributor markups.
Among European-based integrated producers, BASF SE, Evonik Industries AG, and Merck KGaA exemplify the diversified chemicals archetype with positions spanning pharmaceutical-grade and personal care commodity specifications. Hangzhou Sunny Chemical occupies a merchant-producer position within Asian supply networks. These entities represent contrasting strategic postures: captive feedstock integration versus geographic proximity to formulation demand clusters.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Evonik Industries AG |
| Solvay S.A. |
| 3V Sigma |
| SI Group |
| Clariant AG |
| Everlight Chemical Industrial Corp. |
| Hangzhou Sunny Chemical |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles in benzophenone-3 merchant markets signal supply-chain rigidity that amplifies pricing power for integrated aromatics producers while compressing margin buffers for non-captive compounders serving REACH-compliant European demand.
Pricing Analysis
REACH's suspected endocrine disruptor classification dictates the pricing tier structure across European supply chains, separating pharmaceutical-grade specifications with tighter purity thresholds from personal care commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in standard grades is intensifying because aromatics feedstock volatility transmits directly into benzophenone-3 synthesis economics. Personal care compounders in India exhibit highest price sensitivity due to thin formulation margins, while specialty dermatology clinics demonstrate lowest sensitivity through direct API supplier relationships.
Supply Chain Analysis
Inventory concentration in Ludwigshafen, Houston, and Zhejiang province anchors global benzophenone-3 availability, with sixty-day cycles reflecting just-in-time coordination between aromatics crackers and downstream UV filter synthesis. The supply chain draws from benzene, acetone, and phenol feedstocks whose price swings transmit directly into manufacturing economics. Single-source vulnerability concentrates around BASF SE's integrated Ludwigshafen complex, which anchors European capacity. Distribution runs through qualified API suppliers serving direct clinic procurement networks, bypassing traditional personal care chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oxybenzone incumbents face a substitution defense against mineral UV filters capturing reef-conscious coastal markets, requiring portfolio diversification to preserve volume positions amid regulatory divergence.
For Market Incumbents: Compound defensive positions through backward integration into aromatics feedstocks and captive supply of REACH-compliant benzophenone-3 grades during European transition periods. Anchor capacity expansion in India's PLI-subsidized Gujarat corridor to serve Mumbai-Ahmedabad formulation demand. Mineral UV filter substitution in Hawaii and Key West demands parallel oxybenzone-free portfolio maintenance for export market preservation. For New Entrants and Emerging Players: Direct clinic supply relationships represent the most penetrable service-layer gap where integrated incumbents under-serve specialty dermatology networks with technical formulation support. Target India's corporate hospital dermatology departments with encapsulated benzophenone-3 formats addressing endocrine disruptor concerns. Pursue qualified API supplier certification as the primary go-to-market angle, bypassing saturated personal care distributor channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core UV filter assets amid REACH-driven portfolio rebalancing. Long-term viability hinges on regulatory divergence persistence between jurisdictions permitting oxybenzone and those accelerating phase-out timelines. Watch ECHA regulatory updates as the primary inflection indicator for European demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatics Feedstocks | BASF SE's Ludwigshafen complex demonstrates margin capture through captive benzene supply. |
| Encapsulation Technology Development | Microsphere delivery systems isolate UV-B filters from skin contact, addressing ECHA concerns. |
| Direct Clinic Channel Establishment | Germany's clinic-owned pharmacy chains bypass distributor markups through API supplier relationships. |
| PLI-Subsidized Capacity Expansion | India's production-linked incentives support domestic benzophenone-3 synthesis in Gujarat. |
| Dual-Formulation Portfolio Maintenance | Parallel oxybenzone and oxybenzone-free tracks serve REACH-compliant and unregulated export markets. |
Research Methodology
The analysis maps benzophenone-3 synthesis grades, formulation applications, and regulatory compliance tiers, each validated through procurement managers at personal care compounders, technical directors at specialty chemical distributors, regulatory affairs leads navigating REACH and FDA frameworks, and dermatology clinic pharmacy buyers. Primary interviews combined with secondary validation from ECHA substance dossiers, FDA Sunscreen Monograph updates, CDSCO import quality standards, and customs trade data for UV filter shipments. Bottom-up volume modeling triangulated against top-down aromatics demand estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled grade tier, end-use industry, formulation type, and regional regulatory cluster segmentation dimensions. CAGRs were derived from historical trajectory analysis and forward-looking substitution elasticity assumptions. Forecast inputs incorporated REACH implementation timelines, PLI scheme subsidy disbursement patterns, and clinic channel procurement shift velocities.
Forecasts assume regulatory continuity in EU REACH, US FDA Sunscreen Monograph, and India CDSCO-BIS frameworks; material policy shifts would require re-modeling. Substitution acceleration in reef-toxicity jurisdictions and feedstock price volatility represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Japan Methanol Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Isoamyl Acetate Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Aluminum Chemicals Market
Chemicals
Calcium Carbide Market
Chemicals
Thioacetic Acid Market
Chemicals
Detergent Alcohols Market
Chemicals
Amyl Nitrite Market
Chemicals
Ferric Fluoride Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Tanning Agents Market
Chemicals
Phenothiazine Market