
 Germany Methanol Market | 2026-2036
Germany Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Methanol Market Insights
CE marking under the EU F-Gas Regulation is unwinding competitive access for methanol suppliers serving German heating and cooling applications. BASF SE anchors its position through captive steam reforming capacity at Ludwigshafen. Thyssenkrupp AG specializes in gasification technology licensing for industrial methanol production. Helm AG controls distribution logistics across Northwest European port networks.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily via catalytic steam reforming of natural gas or coal gasification, serving as a fundamental chemical building block and emerging energy carrier. The chemical industry end-user segment dominates current offtake, absorbing methanol for formaldehyde and acetic acid synthesis. Fuel cell applications represent the fastest-expanding demand pool, driven by maritime and stationary power trials. Gas phase product types occupy the mature volume position, while aqueous solutions command premium positioning in specialty solvent markets.
KBA vehicle type-approval requirements and EU Green Deal carbon-border adjustments are tightening specifications for methanol used in German transport fuels. The Federal Network Agency's renewable gas grid codes are creating new offtake pathways for green methanol producers. Stakeholders must track how the EU AI Act and automated process controls reshape plant certification timelines for new production assets.
Market Dynamics
The automotive sector's pivot toward hydrogen fuel cell architectures is fundamentally restructuring methanol demand patterns across Germany's chemical corridor. Federal Network Agency reforms to renewable gas grid codes are simultaneously opening new offtake channels for green methanol producers while compressing margins for conventional gray methanol suppliers.
Growth Catalysts
- EU Green Deal carbon-border adjustments:German industrial buyers face mounting pressure to decarbonize feedstock portfolios, redirecting procurement toward low-carbon methanol variants for formaldehyde and acetic acid synthesis.
- Rhine-Ruhr chemical corridor infrastructure:Dense clustering of steam reforming capacity, pipeline networks, and port access creates unmatched supply density for methanol distribution across Northwest Europe.
- Fuel cell maritime trials:German shipyards and engine manufacturers are validating methanol-to-hydrogen reforming systems for commercial vessel propulsion, opening a new demand vertical.
Market Restraints
- Natural gas price volatility:Steam reforming economics remain tethered to TTF hub pricing, exposing Ludwigshafen and Leuna production complexes to input cost swings that compress operating margins.
- CE marking under EU F-Gas Regulation:Methanol suppliers serving German heating and cooling applications face unwinding competitive access as fluorinated gas phase-out timelines accelerate.
- Green methanol production cost premiums:Electrolysis-based e-methanol from renewable hydrogen carries structural cost disadvantages against fossil-derived alternatives, limiting near-term scale.
Strategic Opportunities
- Federal Network Agency renewable gas grid codes:New injection standards for synthetic gases create certified offtake pathways for green methanol producers seeking pipeline access.
- Maritime fuel blending:German port authorities in Hamburg and Bremen are positioning methanol bunkering infrastructure to serve IMO 2025-compliant vessel fuel specifications.
- Power-to-X convergence:Integration of electrolyzer capacity with existing chemical plant infrastructure enables methanol producers to capture carbon dioxide streams for circular carbon utilization.
Industry Challenges
- KBA type-approval timelines:Vehicle certification requirements for methanol fuel systems impose extended validation cycles that delay commercial deployment in automotive applications.
- EU AI Act plant certification:Automated process control systems in new production assets face evolving compliance timelines that extend project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Methanol Market |
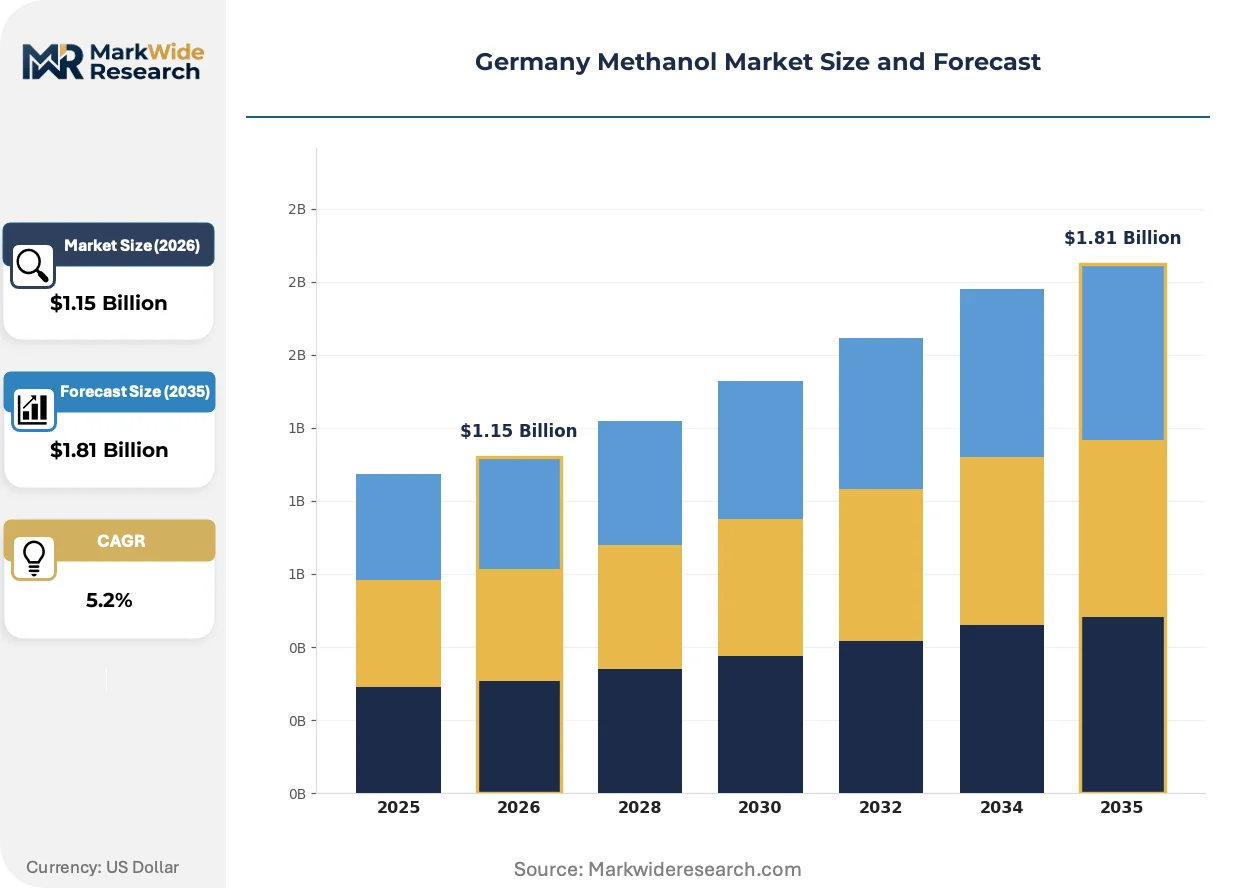
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $1.81 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fuel Cell, Solvent, Formaldehyde, Acetic Acid Product Type: Gas Phase, Liquid Phase, Aqueous Solutions, Anhydrous Methanol End User: Chemical Industry, Automotive Sector, Energy Sector, Construction Sector Technology: Steam Reforming, Gasification, Catalytic Conversion, Direct Synthesis |
| Companies Covered | BASF SE, Helm AG, Thyssenkrupp AG, Mider-Helm Methanol, Shell, DEA Oil, Topsoe A/S, Södra Skogsägarna, Eni S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Methanol Market Trends and Innovations
Electrolysis-based methanol synthesis is actively disrupting conventional production economics across German chemical sites. Three convergent forces are compressing technology adoption cycles and reshaping competitive positioning.
Power-to-methanol technology is supplanting steam reforming as the preferred pathway for new capacity additions. Chemical producers in the Rhine-Ruhr corridor are piloting 10-50 MW electrolyzer integrations to produce e-methanol from captured industrial carbon dioxide. This shift is enabling producers to secure long-term offtake contracts with automotive OEMs seeking Scope 3 emissions reductions.
REACH authorization requirements for formaldehyde precursors are tightening purity specifications for methanol feedstocks. German chemical manufacturers must now certify sub-ppm contaminant levels that exceed legacy technical standards. The acetic acid synthesis segment is responding by demanding certificate-of-analysis documentation for every bulk delivery.
Long-term contracting is displacing spot market procurement among German industrial buyers. Formaldehyde producers in North Rhine-Westphalia are locking in three to five year supply agreements to hedge against carbon-border adjustment volatility. This behavioral shift is most visible among midsized chemical processors lacking captive reforming capacity.
Germany Methanol Market Segmentation
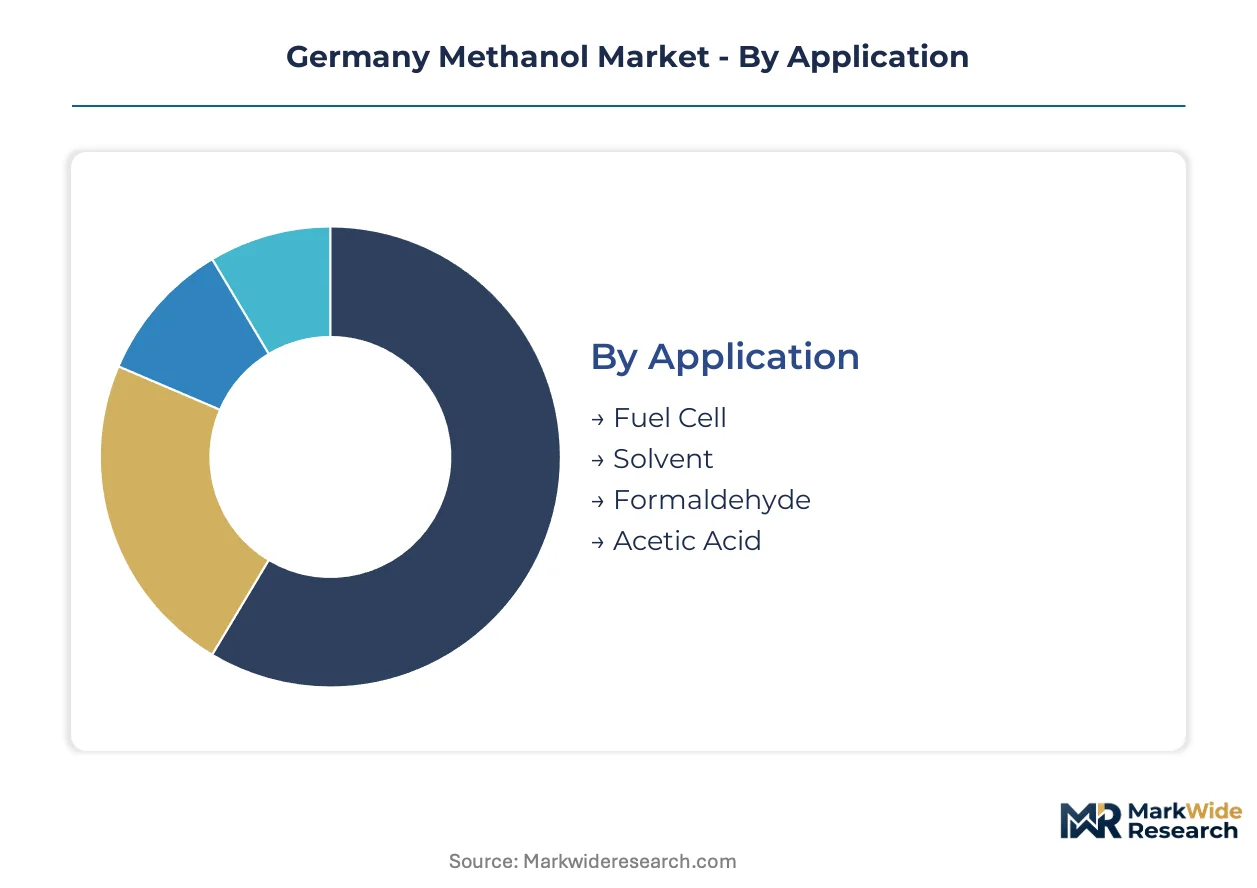
Methanol demand across Germany fragments sharply across production technologies and end-use specifications. Each segment carries distinct regulatory exposure and margin profiles that reshape procurement strategies for Rhine-Ruhr chemical processors.
Application:
Fuel cell trials concentrate in Hamburg and Bremen port zones, while formaldehyde synthesis dominates inland offtake across North Rhine-Westphalia.
- Fuel Cell:Methanol-to-hydrogen reforming systems for maritime propulsion and stationary power units. German shipyards in Hamburg are validating commercial vessel architectures under KBA type-approval frameworks, with demand climbing fastest for IMO-compliant bunkering specifications.
- Formaldehyde:Primary feedstock for urea-formaldehyde resins and engineered wood panels. Chemical processors in the Rhine-Ruhr corridor absorb bulk volumes for construction adhesive applications, though REACH authorization requirements are tightening purity thresholds.
- Acetic Acid:Catalytic carbonylation of methanol yields acetic acid for vinyl acetate monomer and PTA production. BASF SE's Ludwigshafen complex anchors domestic demand.
- Solvent:Industrial degreasing and paint formulation applications. Aqueous methanol blends serve specialty coating manufacturers in Bavaria.
Formaldehyde holds the largest share; momentum sits with fuel cell applications.
Product Type:
Cost tiers separate commodity-grade gas phase methanol from premium-priced aqueous and anhydrous variants serving precision synthesis.
- Gas Phase:Standard industrial grade delivered via pipeline and bulk tanker. Dense clustering of steam reforming capacity in Ludwigshafen and Leuna creates supply concentration for Northwest European distribution.
- Anhydrous Methanol:Water content below 0.1% for moisture-sensitive chemical reactions. Pharmaceutical and electronics-grade specifications command substantial premia over technical grades.
- Aqueous Solutions:Pre-blended water-methanol mixtures for solvent and antifreeze applications. Specialty chemical distributors in Frankfurt-Rhine-Main control formulation logistics.
- Liquid Phase:Pressurized storage and transport variant for maritime bunkering infrastructure. Hamburg port authorities are certifying dedicated methanol storage terminals.
Gas phase dominates volume; anhydrous methanol captures the steepest margin expansion.
End User:
Chemical industry procurement patterns diverge from automotive sector trials in validation timelines and contract structures.
- Chemical Industry:Formaldehyde and acetic acid synthesis absorb the bulk of German methanol offtake. Long-term contracting is displacing spot procurement among midsized processors lacking captive reforming capacity.
- Automotive Sector:Fuel cell system developers and engine manufacturers. Extended KBA certification cycles delay commercial deployment despite pilot program acceleration.
- Energy Sector:Power-to-X project developers integrating electrolyzer capacity with methanol synthesis. Federal Network Agency renewable gas grid codes are opening certified injection pathways.
- Construction Sector:Formaldehyde-based adhesive and insulation material producers. Demand tracks residential construction permitting in southern German states.
Chemical industry holds the largest share; energy sector applications are expanding most quickly.
Technology:
Production maturity separates established steam reforming from emerging electrolysis-based pathways with divergent carbon intensity profiles.
- Steam Reforming:Catalytic conversion of natural gas over nickel-based catalysts. BASF SE's Ludwigshafen complex and Leuna refineries anchor German capacity, though TTF price volatility compresses operating margins.
- Gasification:Coal or biomass feedstock conversion via partial oxidation. Thyssenkrupp AG licenses industrial gasification technology for refinery-integrated methanol units.
- Catalytic Conversion:Heterogeneous catalyst systems for selective methanol synthesis from syngas. Process licensors optimize copper-zinc-alumina formulations for yield efficiency.
- Direct Synthesis:Electrochemical reduction of carbon dioxide with renewable hydrogen. Pilot installations in the Rhine-Ruhr corridor are capturing industrial CO₂ streams for circular carbon utilization.
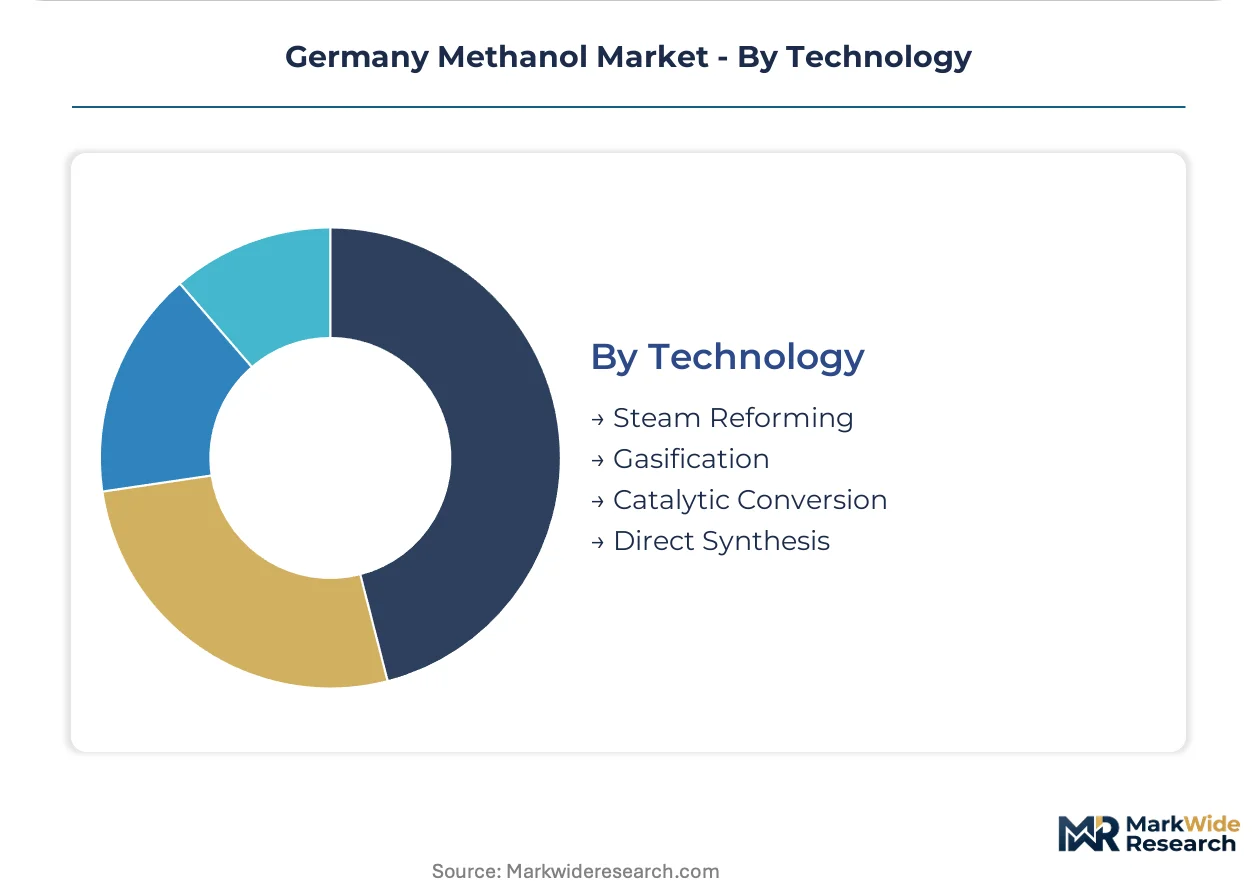
Steam reforming holds the largest share; direct synthesis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr pipeline network and Rotterdam-Antwerp-Ghent port corridor underwrite Germany's methanol distribution dominance across Northwest Europe. Dense chemical infrastructure clustering creates unmatched supply density for industrial offtake.
North Rhine-Westphalia
Fuel cell maritime trials and formaldehyde synthesis anchor demand across the Ruhr industrial belt. KBA type-approval frameworks for methanol-to-hydrogen systems are compressing commercial deployment timelines. Ludwigshafen's steam reforming complexes and Duisburg port terminals concentrate production and import capacity.
Bavaria
Specialty solvent applications for electronics and pharmaceutical manufacturing drive premium methanol consumption. REACH authorization requirements for sub-ppm purity specifications are tightening procurement standards. Munich-Freising chemical processors are locking in long-term supply agreements to hedge carbon-border adjustment exposure.
Lower Saxony
Power-to-X project developers are integrating electrolyzer capacity with methanol synthesis for renewable gas grid injection. Federal Network Agency renewable gas grid codes are opening certified offtake pathways for green methanol producers. Wilhelmshaven port authorities are certifying dedicated methanol bunkering terminals for IMO-compliant vessel fueling.
Hamburg
Maritime fuel blending and shipyard validation of methanol propulsion systems are accelerating demand. EU Green Deal carbon-border adjustments are redirecting procurement toward low-carbon methanol variants for vessel operators. Port infrastructure investments are positioning Hamburg as a Northwest European methanol bunkering hub.
Baden-Württemberg
Automotive fuel cell system developers and precision chemical manufacturers absorb high-purity methanol volumes. EU AI Act compliance timelines for automated process controls are extending plant certification schedules for new production assets. Stuttgart's industrial corridor hosts concentrated demand from midsized chemical processors lacking captive reforming capacity.
Germany Methanol Market Competitive Landscape
Listed leaders compete with private specialists across production technology and distribution logistics. The market structure concentrates around integrated chemical conglomerates with captive reforming capacity and independent traders controlling port-based distribution networks. Three archetypes dominate: captive producers with backward-integrated natural gas supply, technology licensors monetizing gasification patents, and logistics specialists arbitraging Northwest European port differentials. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among Germany-based integrated producers, BASF SE and Thyssenkrupp AG occupy positions representing the captive producer and technology licensor archetypes respectively. Helm AG exemplifies the logistics specialist model, controlling distribution networks across Northwest European port systems. These three entities anchor competitive dynamics through their respective control over production infrastructure, process technology licensing, and physical supply chain coordination.
| Leading Market Players |
|---|
| BASF SE |
| Helm AG |
| Thyssenkrupp AG |
| Mider-Helm Methanol |
| Shell |
| DEA Oil |
| Topsoe A/S |
| Södra Skogsägarna |
| Eni S.p.A |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with take-or-pay provisions lock in supply access for formaldehyde producers across North Rhine-Westphalia while anchoring price visibility against TTF hub volatility. These structures compress spot market liquidity and concentrate bargaining power with integrated producers possessing captive steam reforming capacity at Ludwigshafen and Leuna.
Pricing Analysis
Volume-discount tiering structures separate contract volumes above ten thousand metric tons annually from smaller spot purchases, with formaldehyde synthesis commanding the steepest discounts due to offtake predictability. Price differentiation rests on carbon intensity certification under EU Green Deal frameworks and REACH purity grades, with green methanol variants capturing substantial premia over gray methanol. Cost compression in standard-grade gas phase supply is intensifying because TTF-linked input costs expose merchant producers to margin erosion. Midsized chemical processors lacking captive reforming capacity exhibit the highest price sensitivity, while automotive fuel cell developers prioritize certification grade over unit cost.
Supply Chain Analysis
Strategic stockpiling preferences dominate among formaldehyde producers hedging against Rhine-Ruhr pipeline maintenance windows, while just-in-time delivery governs specialty solvent applications in Bavaria. Geographic supply concentration centers on Germany, the Netherlands, and Belgium, with Rotterdam-Antwerp-Ghent port infrastructure feeding Northwest European distribution. Raw material dependencies draw from natural gas feedstock, nickel-based reforming catalysts, and electrolyzer stacks for green methanol pathways. Single-source vulnerability runs through TTF-indexed natural gas contracts exposing reforming economics to commodity price swings. Distribution runs through pipeline networks for bulk chemical offtake and dedicated tanker fleets for maritime bunkering terminals at Hamburg and Wilhelmshaven.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Methanol Market represents a high-growth disruption as electrolysis-based e-methanol production crosses cost-parity thresholds against steam reforming, accelerated by Federal Network Agency renewable gas grid code reforms opening certified injection pathways.
For Market Incumbents: Consolidate backward integration into electrolyzer capacity and carbon capture infrastructure to defend margin position against merchant gray methanol suppliers facing TTF price volatility. Lock in five-year offtake agreements with automotive OEMs seeking Scope 3 emissions reductions before green methanol production scales. Prioritize certification investment for sub-ppm purity grades exceeding REACH authorization thresholds to maintain formaldehyde synthesis market share. For New Entrants and Emerging Players: Anchor in maritime fuel blending infrastructure at Hamburg and Bremen ports, where IMO 2025-compliant bunkering specifications outpace supply availability. Target power-to-X project development in Lower Saxony, where Federal Network Agency grid codes create first-mover advantages for synthetic gas injection. Pursue tolling arrangements with existing chemical plant operators rather than greenfield capacity builds to compress commissioning timelines. For Investors and Strategic Acquirers: Capital is best deployed toward logistics specialists controlling Northwest European port networks and storage terminals, positioned to arbitrage regional price differentials as green methanol trade flows mature. Long-term viability favors assets with dual-product flexibility across gray and green methanol production pathways. Watch KBA type-approval acceleration for methanol-to-hydrogen fuel cell systems as the inflection signal for automotive demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Capacity | Captures renewable hydrogen supply for e-methanol production at Rhine-Ruhr chemical sites. |
| Long-term Supply Agreement with Automotive OEMs | Secures offtake visibility for green methanol volumes under Scope 3 emissions reduction commitments. |
| Maritime Bunkering Infrastructure Certification | Positions Hamburg port terminals for IMO 2025-compliant methanol fuel blending operations. |
| Carbon Capture Integration with Steam Reforming | Enables circular carbon utilization from Ludwigshafen complex emissions for power-to-methanol synthesis. |
| REACH Purity Grade Certification Investment | Locks in formaldehyde synthesis market share as authorization requirements tighten contaminant thresholds. |
Research Methodology
Cross-validation between plant manager interviews at Ludwigshafen and Leuna production complexes and secondary validation through customs trade data, Cefic industry reports, and SEC 10-K filings anchors the qualitative findings. Primary fieldwork engaged procurement leads at downstream formaldehyde and acetic acid processors, distribution channel partners across Northwest European port networks, and technical R&D directors evaluating electrolysis-based synthesis pathways. Bottom-up capacity assessments triangulate against top-down demand modeling across chemical industry, automotive sector, and energy sector end-use segments.
Sensitivity analysis frameworks test forecast robustness across natural gas price scenarios, carbon-border adjustment stringency levels, and renewable hydrogen cost curves throughout the projection horizon. Segmentation dimensions modeled include production technology tier, carbon intensity certification grade, end-use application, and regional production hub clustering. CAGRs derive from compound growth trajectory fitting against historical production volume trends and announced capacity expansion timelines. Industry-specific forecast inputs incorporate TTF hub price volatility bands and Federal Network Agency grid code implementation schedules.
Underlying assumptions cover sustained EU Green Deal carbon-border adjustment enforcement, stable Rhine-Ruhr pipeline network availability, and electrolyzer cost decline curves, with deviation risk concentrated in natural gas supply disruptions and KBA type-approval timeline extensions. Forecasts reflect these documented assumptions with explicit scenario boundaries. Revision becomes warranted when renewable hydrogen production costs cross below fifty euros per megawatt-hour thresholds or when IMO marine fuel specifications accelerate beyond current bunkering infrastructure readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Paint Remover Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Flooring Chemicals Market
Chemicals
Isopropanolamine Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Acetophenone Market
Chemicals
Potassium Fluoride Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Tin Chemicals Market
Chemicals
Cummene Derivatives Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
5 Dinitroaniline Market
Chemicals
Asia-Pacific Methyl Acrylate Market