
 Lanthanum Nitrate Market | 2026-2036
Lanthanum Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Lanthanum Nitrate Market Outlook
Rare earth processing chemists is bifurcating the competitive landscape between integrated miners and specialty refiners. China Minmetals Corporation leverages captive ore access to sustain cost advantages across upstream operations. American Elements differentiates through domestic U.S. refining capabilities that shorten lead times for pharmaceutical-grade orders. Lynas Corporation anchors its position with Australian mining assets and Malaysian separation facilities.
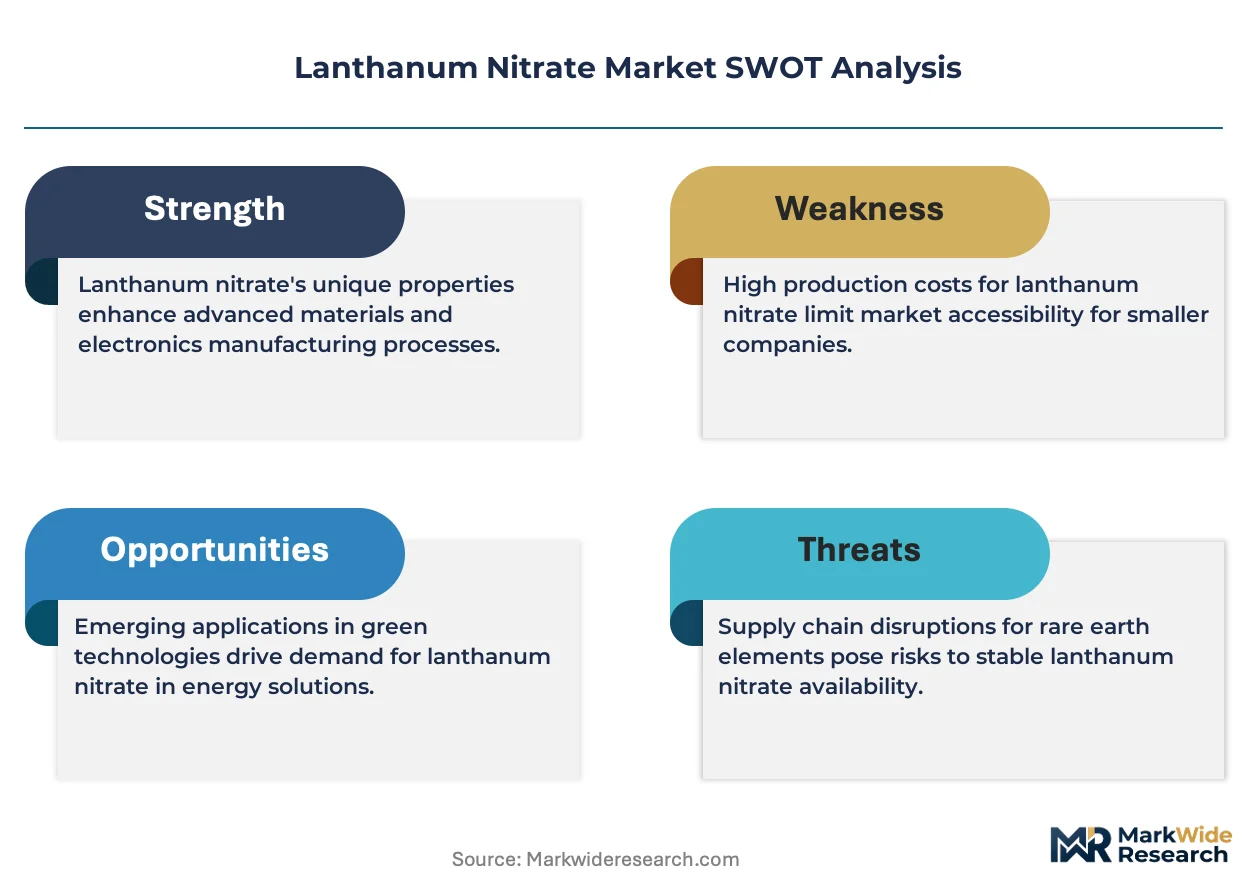
Lanthanum nitrate is a water-soluble rare earth salt typically supplied as a hexahydrate crystal with purity grades ranging from 99.9% to 99.999%, produced through nitric acid dissolution of lanthanum oxide or carbonate precursors. The compound serves primarily as a precursor in catalyst formulations, optical glass manufacturing, and pharmaceutical active ingredient synthesis. High Purity material commands the strongest margin pool due to stringent trace-metal specifications in electronics and drug applications. Catalyst end users represent the fastest-growing demand segment as automotive emission standards tighten across multiple jurisdictions. Technical Grade supply dominates volume throughput, though pricing pressure from industrial-grade alternatives limits expansion in commodity applications.
EPA emission standards and REACH registration requirements in Europe are elevating analytical documentation burdens for importers, favoring suppliers with established certification protocols. China's MIIT rare earth production quotas and export license system directly constrain raw material availability for non-integrated processors. ISO 9001 and IATF 16949 certifications have become baseline requirements for catalyst supply chain qualification. Stakeholders must weigh backward integration into rare earth oxide refining against long-term offtake partnerships with state-backed Chinese producers.
Market Dynamics
China's MIIT rare earth production quotas and export license system are tightening raw material availability for non-integrated processors, forcing Western catalyst manufacturers to rebuild supply chains around certified high-purity suppliers with established REACH documentation protocols.
Growth Catalysts
- EPA Tier 3 emission standards:Automotive catalyst loadings are rising across North American passenger vehicle platforms, expanding lanthanum nitrate consumption in zeolite washcoat formulations.
- Jiangsu province specialty chemical clusters:Concentrated refining infrastructure near Shanghai port facilities shortens logistics lead times for pharmaceutical-grade orders bound for European formulation houses.
- Optical glass manufacturing:High-index lens production for augmented reality headsets is absorbing technical-grade material previously directed to commodity catalyst applications.
Market Restraints
- Nitric acid feedstock volatility:Fertilizer sector demand spikes and energy cost fluctuations transmit directly to lanthanum nitrate production economics, compressing margin stability for toll refiners.
- Single-source oxide dependency:Non-integrated processors in Malaysia and Estonia remain captive to Chinese state-backed producers for lanthanum oxide precursors, exposing offtake agreements to quota-driven allocation cuts.
- Cerium-zirconium solid solution substitutes:Advanced three-way catalyst formulations are displacing pure lanthanum loadings in certain stoichiometric engine applications, ceding volume share in mid-tier automotive programs.
Strategic Opportunities
- Brazilian rare earth development:Serra Verde's ionic clay deposits and emerging separation infrastructure offer non-Chinese oxide sourcing for processors seeking supply chain diversification.
- Solid oxide fuel cell electrolytes:Lanthanum-doped ceria compositions for distributed power generation represent a nascent demand vertical with multi-year qualification timelines but premium pricing potential.
- EU Critical Raw Materials Act:Strategic stockpiling mandates and domestic processing incentives are redirecting procurement budgets toward European-based refiners with established ECHA registration dossiers.
Industry Challenges
- Rare earth separation chemist scarcity:Specialized expertise in solvent extraction cascade optimization is concentrating at state-owned Chinese producers, constraining capacity expansion at Western greenfield projects.
- IATF 16949 certification timelines:Automotive supply chain qualification protocols demand 18-24 month validation cycles for new lanthanum nitrate sources, freezing out speculative entrants during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lanthanum Nitrate Market |
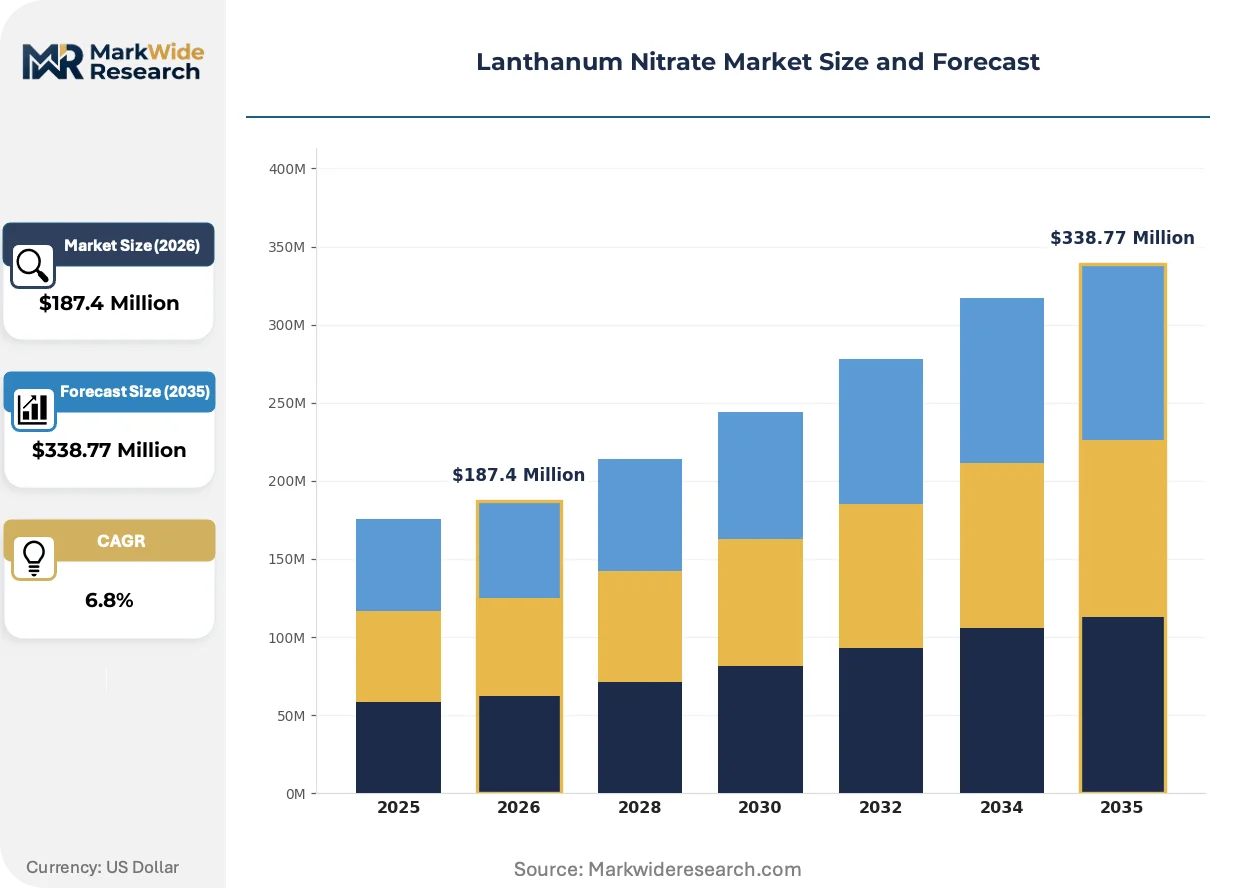
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Analytical Grade, Industrial Grade End User: Ceramics, Electronics, Pharmaceuticals, Catalysts Application: Optical Materials, Magnetic Materials, Catalytic Converters, Emission Control Packaging Type: Bags, Drums, Bottles, Cylinders |
| Companies Covered | China Minmetals Corporation, Sigma Aldrich, American Elements, Metall Rare Earth, Alfa Aesar, ALB Materials, Lynas Corporation, China Northern Rare Earth Group High Tech Co, Stanford Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lanthanum Nitrate Market Strategic Shifts
Process intensification and regulatory documentation automation are reshaping competitive advantage in lanthanum nitrate supply. Refiners are embedding analytical traceability directly into production workflows rather than treating certification as a post-manufacture overlay.
Continuous flow nitric acid dissolution is decomposing traditional batch reactor economics in lanthanum nitrate production. German specialty chemical houses are piloting microreactor arrays that cut residence times from hours to minutes. This technology is decomposing the scale advantages historically held by large-volume Chinese producers, enabling viable smaller-batch output for pharmaceutical-grade specifications.
REACH registration dossier automation is compressing compliance timelines for European catalyst customers. Automated substance identity profiling and hazard classification algorithms are reducing manual analytical documentation burdens. Specialty refiners in Estonia and Malaysia are deploying these tools to accelerate qualification with German automotive Tier 1 suppliers facing CSRD supply chain disclosure mandates.
Direct refiner-to-formulator relationships are displacing trader-mediated procurement in high-purity segments. Pharmaceutical active ingredient manufacturers are bypassing distributors to secure lot-specific trace-metal documentation. This pattern is most pronounced in Swiss and Danish formulation houses where FDA and EMA dual-filing requirements demand granular batch records unavailable through commodity channels.
Lanthanum Nitrate Market Segmentation
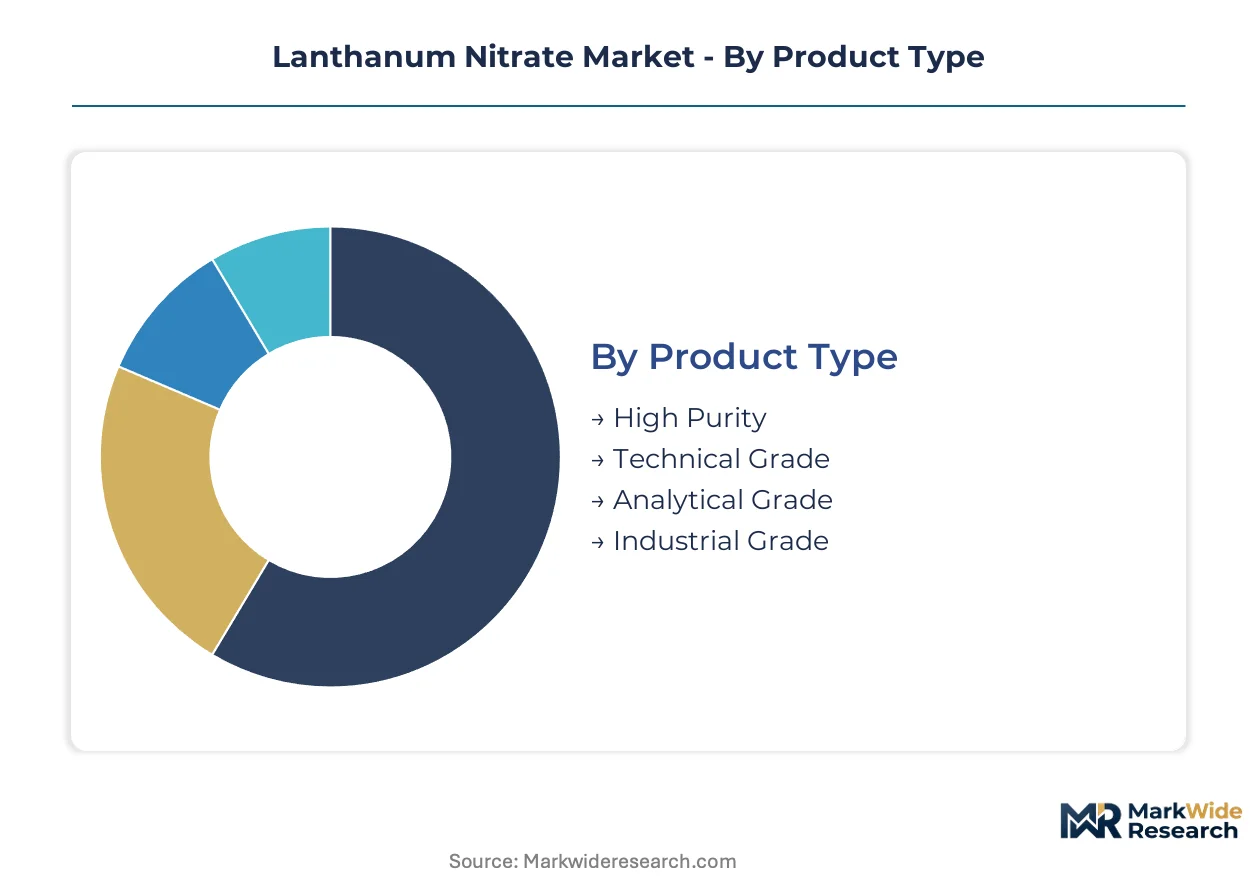
Lanthanum nitrate pricing stratifies sharply across purity tiers, with pharmaceutical and electronics specifications commanding multiples over industrial grades. Catalyst manufacturers and optical glass producers drive divergent procurement patterns, splitting the market between long-term offtake contracts and spot-volume flexibility.
Product Type:
Margin pools concentrate at the extreme purity end, where trace-metal certification requirements create defensible pricing power against commodity alternatives.
- High Purity:Material meeting 99.99% to 99.999% specifications carries stringent limits on iron, calcium, and heavy metal contaminants. Swiss and Danish pharmaceutical formulation houses absorb the majority of output, driven by FDA and EMA dual-filing requirements for active ingredient precursors.
- Technical Grade:The 99.9% purity tier serves optical glass manufacturers producing high-index lenses for augmented reality headsets. Jiangsu province specialty chemical clusters channel this material toward emission control catalyst producers seeking cost-optimized zeolite washcoat formulations.
- Analytical Grade:Laboratory reagent specifications with batch-level certificates of analysis support research institutions and quality control laboratories validating rare earth separation processes.
- Industrial Grade:Lower-purity material with relaxed trace-element tolerances feeds ceramic pigment production and fertilizer additive applications where functional performance tolerates broader compositional variance.
The dominant share belongs to Technical Grade, while High Purity is closing the gap fastest.
End User:
Volume throughput clusters where automotive emission regulations are tightening most aggressively, redirecting refinery capacity toward catalyst precursors.
- Catalysts:Automotive three-way catalyst manufacturers in Germany and the United States drive the steepest demand expansion, as EPA Tier 3 and EU Euro 7 standards force higher lanthanum loadings in zeolite washcoats. IATF 16949 certification requirements lock qualified suppliers into 18-24 month validation cycles.
- Electronics:Solid oxide fuel cell developers and phosphor manufacturers consume high-purity material for electrolyte doping and LED phosphor activation, with qualification timelines stretching across multi-year development programs.
- Pharmaceuticals:Active ingredient synthesis for contrast agents and therapeutic compounds demands lot-specific trace-metal documentation unavailable through commodity distribution channels.
- Ceramics:Traditional refractory and structural ceramic applications absorb technical-grade material previously directed to commodity catalyst programs, though cerium-zirconium substitutes are displacing pure lanthanum in certain stoichiometric formulations.
Catalysts command the largest volume position, with Electronics expanding most quickly on fuel cell electrolyte development timelines.
Application:
Supply chain configuration separates qualified automotive suppliers from generalist refiners unable to sustain documentation burdens for Tier 1 qualification.
- Catalytic Converters:Zeolite washcoat formulations for gasoline and diesel aftertreatment systems represent the highest-volume consumption channel, with EPA and EU emission standards directly translating to lanthanum nitrate offtake commitments.
- Optical Materials:High-index lens production for augmented reality hardware is absorbing technical-grade capacity previously available to commodity catalyst applications, tightening supply for mid-tier automotive programs.
- Emission Control:Stationary source catalysts for power generation and industrial boilers operate on less stringent purity requirements, though REACH registration dossiers still favor established European refiners.
- Magnetic Materials:Bonded magnet precursor applications consume lower-purity grades with tolerance for rare earth co-precipitation, limiting pricing power for non-specialized producers.
Catalytic Converters anchor volume throughput, while Optical Materials is climbing the fastest on consumer electronics demand.
Packaging Type:
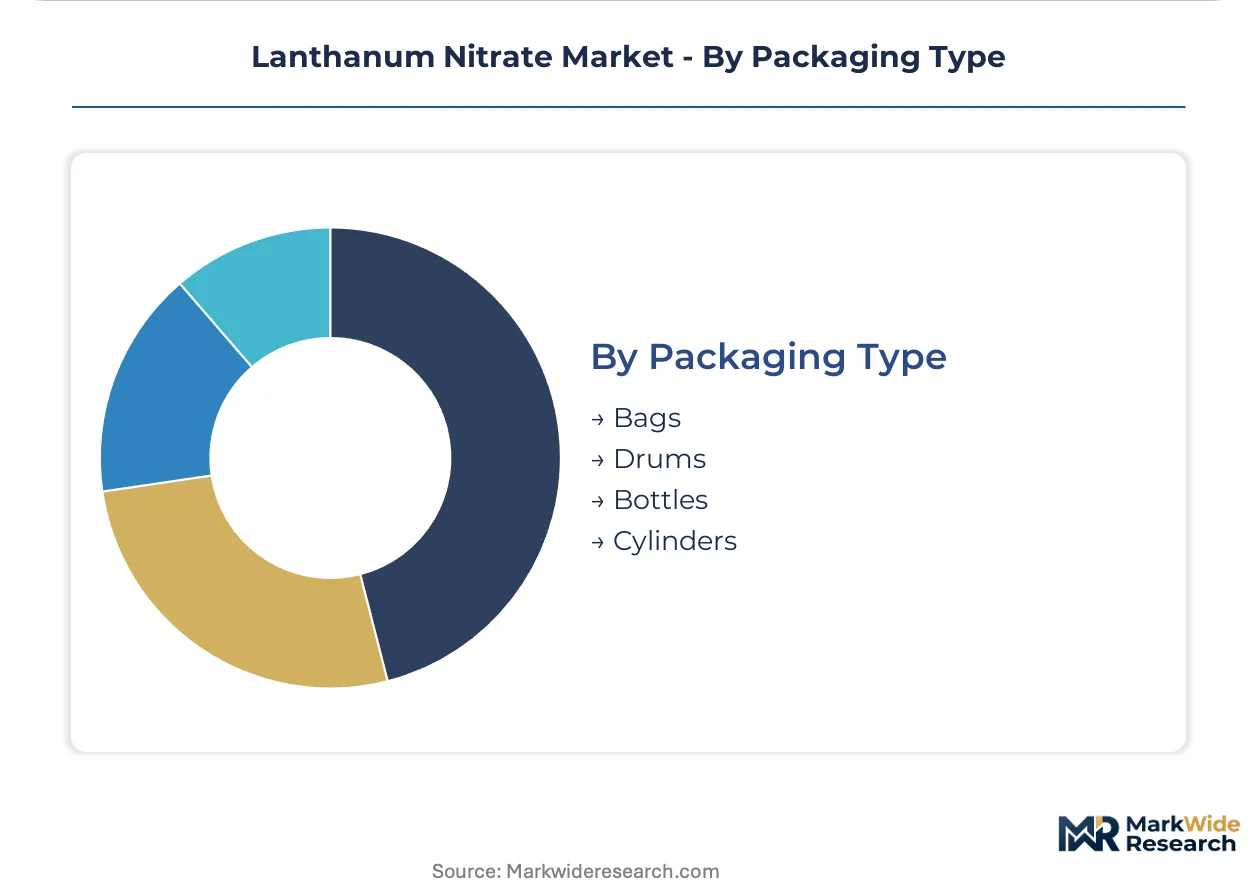
Logistics economics favor bulk formats for integrated catalyst manufacturers, while pharmaceutical procurement insists on contamination-controlled smaller units.
- Drums:Standard 200-liter steel and fiber drums dominate technical-grade shipments to catalyst formulators, with UN-certified designs required for nitric acid derivative transport regulations.
- Bottles:Amber glass and fluoropolymer bottles protect high-purity material from moisture and light degradation during pharmaceutical and electronics industry distribution.
- Bags:Multi-layer laminated bags with nitrogen flushing serve ceramic pigment and fertilizer additive producers prioritizing cost minimization over atmospheric protection.
- Cylinders:Specialized gas cylinder formats support research-scale and ultra-high-purity applications requiring inert atmosphere preservation through point-of-use delivery.
Drums hold the dominant procurement share, with Bottles gaining ground fastest on pharmaceutical direct-sourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes lanthanum nitrate predominantly for automotive catalyst precursors, while Switzerland and Denmark absorb high-purity grades for pharmaceutical synthesis, creating divergent procurement patterns across major demand centers.
China
Jiangsu province specialty chemical clusters and automotive emission control manufacturers drive concentrated consumption. MIIT rare earth production quotas and export license systems constrain raw material flows to non-integrated processors. Shanghai port facilities anchor pharmaceutical-grade distribution networks serving European formulation houses.
Germany
Automotive three-way catalyst manufacturers and zeolite washcoat formulators absorb technical-grade volumes. REACH registration requirements and ECHA documentation protocols favor established suppliers with automated compliance systems. Rhineland chemical clusters host qualification programs for IATF 16949-certified supply chains.
United States
EPA Tier 3 emission standards elevate lanthanum loadings in passenger vehicle catalyst platforms. Domestic refining capabilities shorten lead times for pharmaceutical-grade orders. Southeast chemical processing corridors concentrate toll refining capacity for catalyst precursor production.
Malaysia
Separation facilities process Australian-mined rare earth oxides into nitrate precursors. Non-integrated processors remain exposed to Chinese state-backed quota allocations for oxide feedstock. Port Klang logistics hubs facilitate REACH-registered shipments to European automotive Tier 1 suppliers.
Switzerland
Pharmaceutical active ingredient manufacturers demand lot-specific trace-metal documentation for FDA and EMA dual-filing requirements. Direct refiner-to-formulator relationships displace trader-mediated procurement. Basel formulation clusters absorb the majority of high-purity imports for contrast agent synthesis.
Lanthanum Nitrate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive ore access separating cost-advantaged upstream operators from toll refiners dependent on spot oxide markets. State-backed Chinese producers and Australian-Malaysian integrated miners occupy the upper tier, while American and European specialty refiners compete on certification velocity and pharmaceutical-grade documentation. Strategic moves concentrate on backward integration into oxide refining and long-term offtake partnerships with quota-controlled Chinese suppliers.
Among integrated mining and refining operators, China Minmetals Corporation and Lynas Corporation exemplify divergent geographic anchoring strategies. China Minmetals Corporation represents state-backed vertical control from ore through nitrate production. Lynas Corporation occupies a position bridging Australian mining assets with Malaysian separation infrastructure. American Elements sits within the domestic U.S. refining archetype, shortening lead times for North American pharmaceutical and electronics customers.
| Leading Market Players |
|---|
| China Minmetals Corporation |
| Sigma Aldrich |
| American Elements |
| Metall Rare Earth |
| Alfa Aesar |
| ALB Materials |
| Lynas Corporation |
| China Northern Rare Earth Group High Tech Co |
| Stanford Advanced Materials |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Jiangsu province specialty chemical clusters shapes both supply concentration and price floors for lanthanum nitrate. MIIT rare earth production quotas constrain oxide feedstock availability, elevating cost floors for non-integrated toll refiners while state-backed Chinese producers leverage captive ore access to sustain margin advantages.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive catalyst manufacturers and established refiners, insulating qualified suppliers from nitric acid feedstock volatility while spot-volume flexibility serves ceramic pigment and fertilizer additive buyers. Price differentiation rests on REACH registration status and IATF 16949 certification tier, with pharmaceutical-grade material commanding substantial premiums over technical-grade alternatives. Cost compression in industrial-grade tiers is intensifying because cerium-zirconium solid solution substitutes displace pure lanthanum loadings in mid-tier automotive programs. Ceramic pigment producers exhibit the highest price sensitivity, while Swiss and Danish pharmaceutical formulation houses prioritize lot-specific trace-metal documentation over unit economics.
Supply Chain Analysis
Shanghai port transit underwrites pharmaceutical-grade distribution networks serving European formulation houses, creating a logistics chokepoint that elevates lead time risk for just-in-time catalyst manufacturers. Supply concentrates in China, Malaysia, and Germany, with non-integrated processors in Malaysia and Estonia drawing from Chinese state-backed oxide producers. Raw material dependencies span lanthanum oxide precursors, nitric acid feedstock, and specialized solvent extraction reagents. Single-source oxide vulnerability exposes Western toll refiners to quota-driven allocation cuts from MIIT-licensed Chinese producers. Distribution runs through direct refiner-to-formulator relationships in high-purity segments, displacing trader-mediated channels previously dominant in commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive emission standard tightening across EPA Tier 3 and EU Euro 7 jurisdictions positions lanthanum nitrate as an early-cycle expansion story, with zeolite washcoat formulation demand accelerating ahead of solid oxide fuel cell electrolyte qualification timelines.
For Market Incumbents: Consolidate supply chain position through backward integration into rare earth oxide refining or long-term offtake partnerships with quota-controlled Chinese producers. Threat from cerium-zirconium substitute technologies in stoichiometric engine applications demands defensive capacity allocation toward high-purity pharmaceutical and electronics specifications. Certification investment in automated REACH dossier generation preserves qualification velocity against emerging Estonian and Malaysian competitors. For New Entrants and Emerging Players: Differentiate on domestic U.S. or European refining capabilities that shorten lead times for pharmaceutical-grade orders bound for FDA and EMA dual-filing requirements. The most penetrable white space sits in solid oxide fuel cell electrolyte precursors, where multi-year qualification timelines have delayed incumbent capacity commitment. Target Brazilian rare earth development corridors as oxide sourcing alternatives to Chinese state-controlled supply, leveraging Serra Verde ionic clay deposits for supply chain narrative differentiation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IATF 16949-certified catalyst suppliers locked into 18-24 month automotive qualification cycles. Long-term viability across the analysis window favors integrated miners with Australian or Brazilian ore assets and Malaysian or Estonian separation infrastructure. Acquisition target archetype: specialty refiners with established ECHA registration dossiers and automated compliance systems. The signal to watch is EPA emission standard advancement timelines, which directly translate to lanthanum loading specifications in North American passenger vehicle platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxide Refining | Captive ore access from Australian mining assets insulates margin stability against MIIT quota volatility. |
| Automated REACH Dossier Generation | Estonian and Malaysian refiners compress compliance timelines for German automotive Tier 1 suppliers facing CSRD mandates. |
| Long-term Supply Agreement | Direct refiner-to-formulator relationships secure lot-specific documentation for Swiss pharmaceutical active ingredient synthesis. |
| Capacity Expansion in Jiangsu Province | Shanghai port proximity shortens logistics lead times for pharmaceutical-grade orders bound for European formulation houses. |
| Green Manufacturing Transition | Continuous flow microreactor arrays decompose scale advantages of large-volume Chinese batch reactor producers. |
Study Parameters
A spread of perspectives from rare earth separation chemists, automotive catalyst procurement leads, pharmaceutical formulation directors, and specialty chemical distribution channel partners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with plant managers at Jiangsu province refining clusters and procurement officers at German zeolite washcoat formulators. Secondary validation drew from MIIT rare earth production quota disclosures, ECHA REACH registration databases, EPA emission standard filings, and customs trade data documenting nitric acid derivative flows. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from automotive production and pharmaceutical active ingredient synthesis forecasts.
Segmentation dimensions modeled include purity grade tier, end-use industry vertical, packaging format, and regional production hub concentration. Value outputs across the analysis window reflect price stratification between pharmaceutical, electronics, catalyst, and ceramic application specifications. CAGRs were derived from demand elasticity modeling against EPA and EU emission standard implementation timelines, with fuel cell electrolyte development programs and optical glass manufacturing for augmented reality hardware as industry-specific volume drivers.
The analysis sits within stated boundaries; outcomes outside sustained automotive emission standard tightening or unimpaired Chinese rare earth quota administration would require recalibration. Forecasts reflect assumptions regarding solvent extraction cascade optimization capacity expansion and nitric acid feedstock cost stability. Practitioners should keep alternative scenarios live as Brazilian rare earth project development timelines and solid oxide fuel cell commercialization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Whitening Ingredients Market
Chemicals
Global Methylene Chloride Market
Chemicals
Chromium Trioxide Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Europe Biguanide Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Mercuric Chloride Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Sodium Hydride Market
Chemicals
Zinc Chemicals Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Chloroplatinic Acid Market
Chemicals
Benzoyl Alcohol Market