
 Flame Retardants Chemicals Market | 2026-2036
Flame Retardants Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Retardants Chemicals Market Analysis
Modular additive packages is restructuring buyer procurement in flame retardants chemicals, shifting purchasing from single-chemical orders to bundled systems that combine synergists, stabilizers, and processing aids. Albemarle Corporation leverages its bromine supply chain to dominate integrated halogenated bundles. ICL Group anchors its position through phosphorus-based portfolio breadth across electronics and construction applications. LANXESS competes on reactive flame retardant technology for engineering polymers.
Flame retardants chemicals encompass halogenated, phosphorus-based, nitrogen-based, inorganic, and intumescent compounds formulated to inhibit, suppress, or delay combustion in polymeric materials, typically requiring loading levels of 10-30% by weight to achieve UL-94 V-0 ratings in thermoplastics. These additives function through endothermic decomposition, char formation, or radical quenching mechanisms to protect electrical equipment, building materials, transportation components, textiles, and adhesives across manufacturing sectors. Phosphorus-based formulations represent the fastest-expanding chemistry class as halogenated options face substitution pressure under REACH restrictions and state-level prohibitions in the United States. Inorganic segments, particularly aluminum hydroxide and magnesium hydroxide, occupy mature volume positions in wire and cable applications where cost sensitivity outweighs performance premiums. Intumescent systems command concentrated margin pools in aerospace tier-1 supplier contracts where FAA certification requirements create qualification barriers.
EPA regulations under the Toxic Substances Control Act restrict certain polybrominated diphenyl ethers, while REACH and RoHS in Europe drive reformulation toward phosphorus and nitrogen chemistries. China's GB standards and MEE enforcement tighten fire safety mandates for building materials and electrical equipment, redirecting domestic production toward compliant additive systems. India's BIS certification requirements for construction products create parallel compliance pathways that favor pre-tested formulation bundles. Stakeholders must monitor evolving substance restrictions across these jurisdictions while building qualification databases that accelerate customer approval cycles.
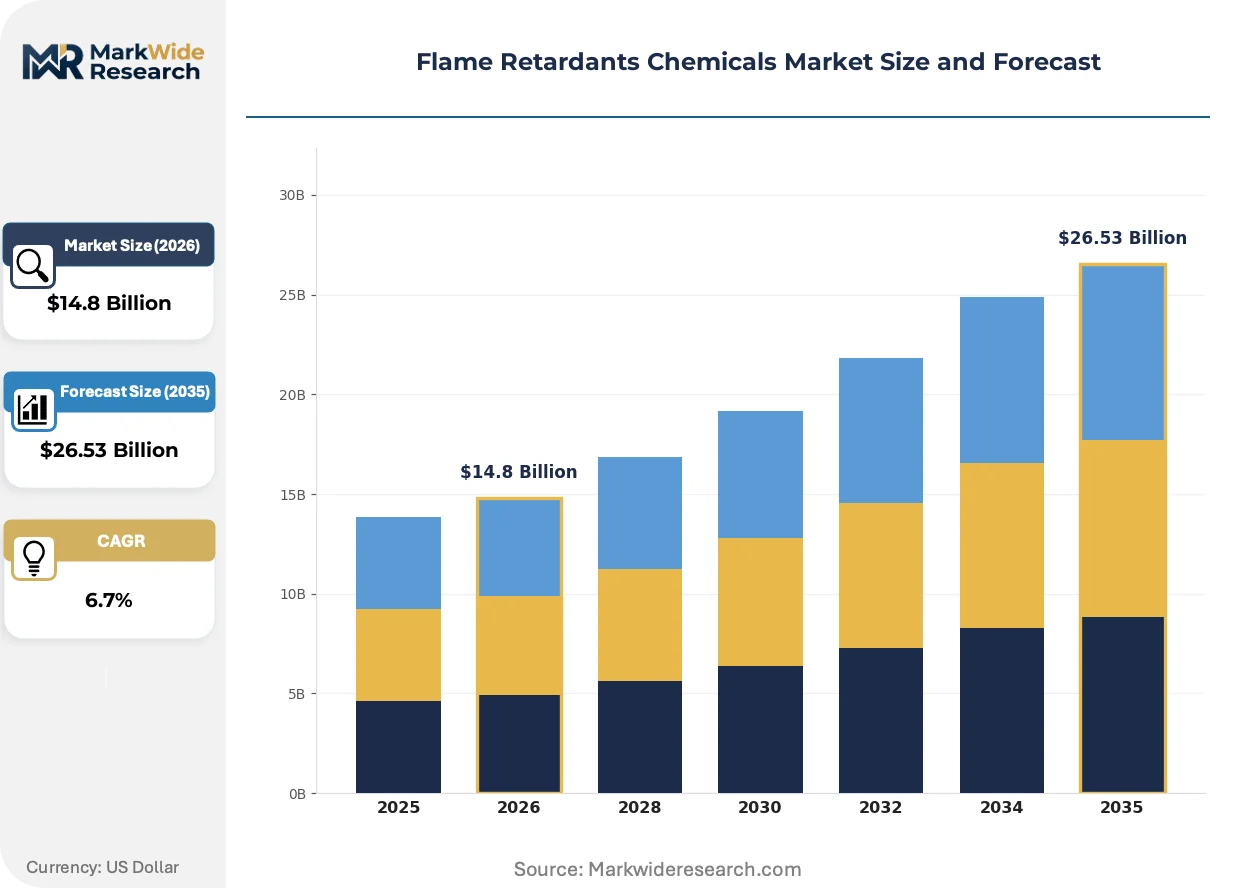
Market Dynamics
Modular additive packages are restructuring procurement patterns across the flame retardants chemicals market, compressing supplier bases as buyers abandon single-chemical spot purchasing in favor of pre-formulated bundles that integrate synergists, stabilizers, and processing aids.
Growth Catalysts
- GB Standard Enforcement:China's Ministry of Ecology and Environment tightens fire safety mandates for building materials and electrical equipment, redirecting domestic production toward compliant phosphorus-based additive systems.
- Wire and Cable Expansion:India's transmission infrastructure buildout drives volume demand for aluminum hydroxide and magnesium hydroxide formulations in low-voltage insulation applications.
- Phosphorus Chemistry Migration:REACH restrictions and state-level prohibitions in the United States accelerate substitution away from polybrominated diphenyl ethers toward reactive phosphorus technologies.
Market Restraints
- Bromine Supply Concentration:Dead Sea brine operations and Arkansas chemical facilities concentrate upstream halogen feedstock control among integrated producers, exposing non-integrated formulators to input volatility.
- Aluminum Hydroxide Cost Sensitivity:Mature inorganic segments face margin compression as wire and cable buyers prioritize price over performance in commodity insulation grades.
- FAA Certification Barriers:Intumescent system qualification timelines for aerospace tier-1 contracts lock out new entrants despite concentrated margin pools in cabin interior applications.
Strategic Opportunities
- India BIS Certification Pathways:Pre-tested formulation bundles that satisfy Bureau of Indian Standards requirements for construction products accelerate customer approval cycles in the subcontinent's fragmented building materials sector.
- Engineering Polymer Reactive Integration:Covalent bonding of phosphorus moieties into polymer backchains enables permanent flame resistance without additive migration in high-temperature automotive underhood applications.
- Electronics Miniaturization:Thin-wall device housings for 5G infrastructure and consumer electronics create specification pull for low-loading phosphorus-nitrogen synergists that preserve mechanical properties.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in polymer-flame retardant compatibility and processing stability remains concentrated among legacy additive houses, constraining new product development velocity at mid-scale compounders.
- Multi-Jurisdictional Registration Burden:Parallel substance notification requirements under EPA TSCA, REACH, and China's MEE chemical inventory create compliance cost stacking for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Retardants Chemicals Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogenated, Phosphorus-Based, Nitrogen-Based, Inorganic, Intumescent Application: Electrical Equipment, Building Materials, Transportation Components, Textiles, Adhesives & Sealants End User Industry: Electronics Manufacturing, Construction Firms, Aerospace Tier-1 Suppliers, Apparel Production, Chemical Processing Plants Form: Powder, Liquid, Granule, Resin, Dispersion |
| Companies Covered | Albemarle Corporation, ICL Group, LANXESS, BASF SE, Clariant, J.M. Huber Corporation, Dow, Italmatch Chemicals, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Retardants Chemicals Market Emerging Trajectories
Reactive flame retardant technologies and digital qualification platforms are compressing traditional development cycles while regulatory fragmentation forces parallel formulation tracks for regional compliance.
Phosphorus-nitrogen intumescent coatings are rewriting performance benchmarks in thin-wall polymer applications. Electronics manufacturers in South Korea and Taiwan adopt these systems for 5G base station housings and server chassis where legacy loadings would compromise dimensional stability. The technology is rewriting supplier-customer relationships by embedding formulation houses deeper into OEM design cycles rather than commodity spot sales.
REACH authorization procedures and RoHS substance restrictions in Europe drive systematic reformulation across electrical equipment supply chains. Manufacturers face substance sunset deadlines that force dual-track development—maintaining legacy halogenated production for non-EU markets while scaling phosphorus alternatives for European customers. Wire and cable producers in Germany and Italy absorb the steepest compliance costs as they serve both regulatory environments from shared production assets.
Specification-driven procurement now dominates aerospace and automotive tier-1 purchasing, with buyers demanding bundled additive packages that include processing guidance and failure analysis support. Electronics contract manufacturers in Vietnam and Mexico increasingly source pre-qualified formulation systems from distributors rather than direct chemical procurement. This behavioral shift concentrates volume with integrated suppliers capable of delivering technical service alongside material supply.
Flame Retardants Chemicals Market Segmentation
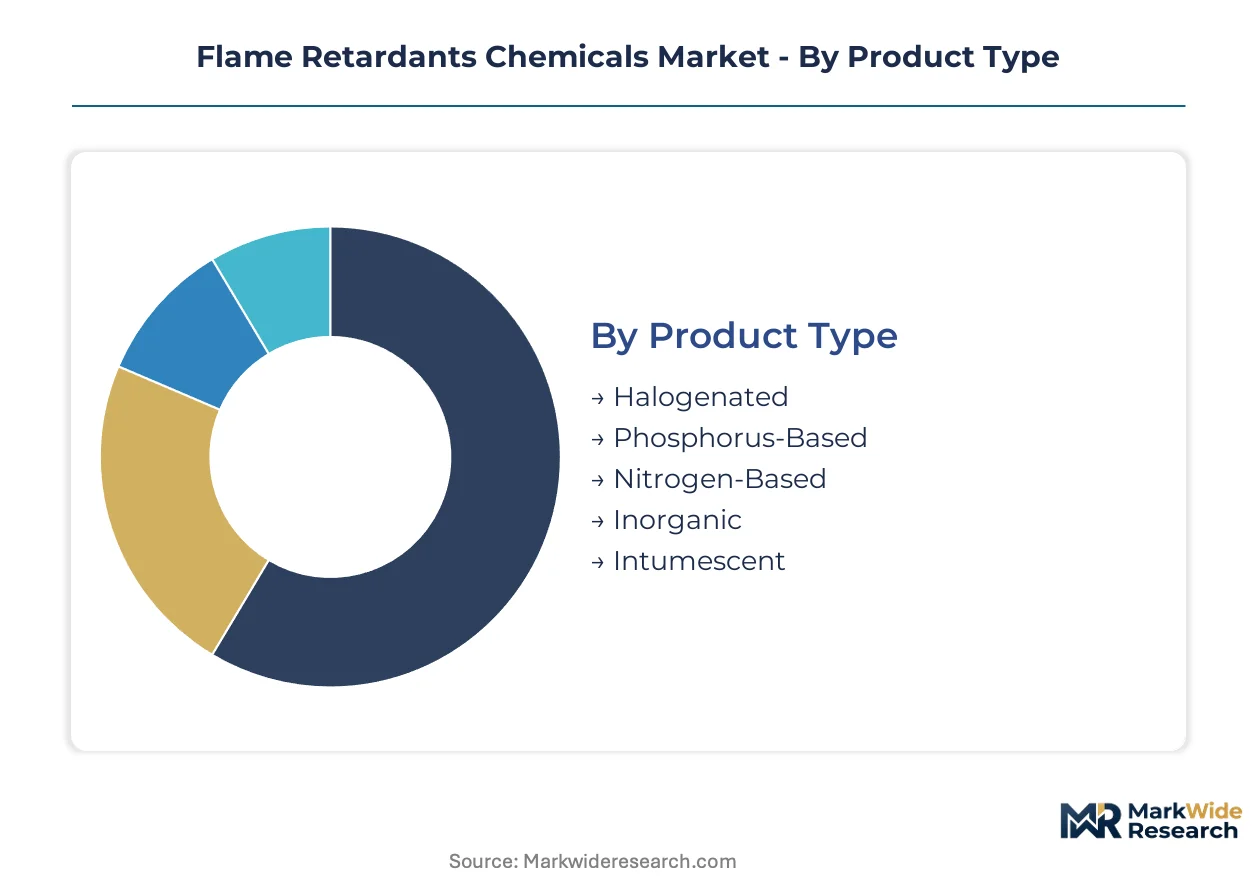
Flame retardants chemicals segment along four critical dimensions that determine formulation complexity, regulatory burden, and customer qualification requirements. Product chemistry dictates raw material sourcing strategies. Application specifications drive loading levels and synergist selection. End-user industry determines certification pathways and technical service intensity.
Product Type:
Capital intensity varies sharply across chemistries, with phosphorus-based and intumescent systems requiring specialized synthesis equipment and purification infrastructure that halogenated producers already amortize through bromine integration.
- Halogenated:Brominated and chlorinated compounds deliver high efficiency at low loadings in thermoplastics. Demand concentrates in electrical equipment exports from China to markets without REACH-equivalent restrictions, though EPA TSCA limitations on polybrominated diphenyl ethers compress domestic volumes.
- Phosphorus-Based:Organophosphates and phosphonates function through char formation and radical quenching in engineering polymers. Electronics manufacturers in South Korea and Taiwan specify these for 5G infrastructure housings where RoHS compliance is mandatory and halogen-free branding commands premium positioning.
- Nitrogen-Based:Melamine derivatives and guanidine compounds serve as gas-phase flame suppressants in polyolefin applications.
- Inorganic:Aluminum hydroxide and magnesium hydroxide dominate wire and cable insulation where cost sensitivity outweighs performance premiums in commodity grades.
- Intumescent:Expandable graphite and ammonium polyphosphate systems form protective char layers in thin-wall aerospace and construction applications.
Most installed capacity flows through halogenated segments. Expansion is steepest in phosphorus-based formulations.
Application:
Application selection determines formulation bundle complexity, with electrical equipment and aerospace demanding integrated additive packages while building materials tolerate single-chemical procurement.
- Electrical Equipment:Connectors, housings, and printed circuit boards require UL-94 V-0 ratings at minimal loadings to preserve dimensional tolerances. Wire and cable producers in Germany and Italy absorb dual-track compliance costs as they serve both REACH-regulated European customers and legacy halogen-tolerant export markets from shared production assets.
- Building Materials:Insulation foams, structural panels, and roofing membranes face GB standard enforcement in China and BIS certification requirements in India. Construction firms in Asia-Pacific drive specification pull for pre-tested formulation bundles that accelerate project approval timelines.
- Transportation Components:Automotive underhood parts and interior trim demand thermal stability alongside flame resistance.
- Textiles:Upholstery, protective clothing, and drapery applications require durable finishes that survive laundering cycles.
- Adhesives & Sealants:Construction and electronics bonding applications need compatibility with cure chemistry and substrate adhesion.
Electrical equipment commands the highest formulation service intensity. Building materials deliver the steepest volume expansion trajectory.
End User Industry:
Customer type dictates sales channel structure, with aerospace tier-1 suppliers and electronics contract manufacturers demanding embedded technical support that commodity chemical distributors cannot provide.
- Electronics Manufacturing:OEMs and contract manufacturers in Vietnam and Mexico increasingly source pre-qualified formulation systems rather than direct chemical procurement. Thin-wall device housings for consumer electronics and 5G infrastructure create specification pull for low-loading phosphorus-nitrogen synergists.
- Construction Firms:Fragmented building materials sectors in India and Southeast Asia favor bundled additive packages with processing guidance and failure analysis support.
- Aerospace Tier-1 Suppliers:FAA certification requirements for cabin interior applications create qualification barriers that lock out new entrants despite concentrated margin pools.
- Apparel Production:Technical textiles and protective clothing manufacturers specify durable flame-resistant finishes.
- Chemical Processing Plants:Industrial equipment and containment systems require corrosion-resistant flame-retardant coatings.
Electronics manufacturing concentrates the most integrated supplier relationships. Construction firms represent the most fragmented procurement landscape.
Form:
Physical form selection determines handling equipment, dust exposure controls, and dispersion uniformity in compounding operations.
- Powder:Dry blends dominate high-volume thermoplastic compounding where dust collection systems are already installed.
- Liquid:Pumpable dispersions enable precise metering in reactive extrusion and coating applications.
- Granule:Dust-free handling improves workplace safety in manual weighing operations.
- Resin:Masterbatch concentrates simplify downstream processing for compounders without formulation expertise.
- Dispersion:Aqueous or solvent-based suspensions serve textile finishing and coating applications.
Powder forms account for the majority of commodity volume. Liquid and dispersion forms are expanding most quickly in specialized coating and electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flame retardants chemicals industry traces its modern scaling to post-war German chemical engineering and subsequent US petrochemical expansion, with contemporary production gravity shifting toward Asia-Pacific manufacturing clusters.
United States
Electrical equipment manufacturers and aerospace tier-1 suppliers drive specification demand for low-loading phosphorus formulations. EPA regulations under the Toxic Substances Control Act restrict polybrominated diphenyl ethers, redirecting procurement toward reactive phosphorus technologies. Arkansas chemical facilities and Gulf Coast petrochemical corridors concentrate upstream bromine and phosphorus derivative production.
Germany
Wire and cable producers absorb dual-track compliance costs serving both REACH-regulated European customers and legacy halogen-tolerant export markets. ECHA authorization procedures and RoHS substance restrictions force systematic reformulation across electrical equipment supply chains. Industrial clusters in North Rhine-Westphalia and Bavaria host compounded material operations with integrated technical service capabilities.
China
Construction firms and electronics exporters generate volume demand for GB-compliant additive systems. The Ministry of Ecology and Environment tightens fire safety mandates for building materials and electrical equipment under GB standards enforcement. Yangtze River Delta manufacturing corridors concentrate domestic phosphorus-based formulation capacity serving domestic and Southeast Asian markets.
India
Transmission infrastructure buildout and fragmented building materials sectors favor bundled additive packages with processing guidance. Bureau of Indian Standards certification requirements for construction products create parallel compliance pathways that accelerate customer approval cycles. Gujarat and Maharashtra industrial zones concentrate wire and cable compounding operations for domestic and Middle Eastern export markets.
South Korea
Electronics manufacturers specify phosphorus-based formulations for 5G infrastructure housings and server chassis where RoHS compliance is mandatory. MFDS chemical inventory requirements and consumer safety regulations align with EU substance restrictions. Seoul Capital Area and Busan-Ulsan corridors concentrate thin-wall device housing production with embedded flame retardant specification authority.
Flame Retardants Chemicals Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive feedstock positions. Supplier bases compress as buyers abandon single-chemical spot purchasing in favor of pre-formulated bundles. Three archetypes dominate: bromine-integrated halogenated producers, phosphorus portfolio specialists, and reactive technology developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure qualification databases across multiple jurisdictions.
Within the integrated chemical tier, Albemarle Corporation anchors halogenated bundle supply through upstream bromine positions. ICL Group and LANXESS occupy the phosphorus-reactive technology vector, with the former representing portfolio breadth across electronics and construction applications and the latter exemplifying engineering polymer specialization. These three firms exemplify how feedstock integration and formulation expertise concentrate procurement relationships.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL Group |
| LANXESS |
| BASF SE |
| Clariant |
| J.M. Huber Corporation |
| Dow |
| Italmatch Chemicals |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Phosphorus-based formulation migration simultaneously compresses production economics and concentrates supply control among integrated chemical conglomerates with captive feedstock positions. Buyers absorbing REACH compliance costs and GB standard mandates face asymmetric pricing power as non-integrated formulators confront input volatility from concentrated bromine and phosphorus derivative sources.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified intumescent bundles from commodity wire and cable grades. Price differentiation hinges on UL-94 certification tier and volume scale, with electronics manufacturers least sensitive due to RoHS-mandated specification premiums. Cost compression in inorganic aluminum hydroxide segments is intensifying because wire and cable buyers prioritize price over performance in low-voltage insulation. Construction firms in India and Southeast Asia represent the most price-sensitive segment, favoring pre-tested formulation bundles that reduce per-project procurement complexity.
Supply Chain Analysis
Bromine supply rests on Dead Sea brine operations in Israel and Jordan alongside Arkansas chemical facilities in the United States. Phosphorus derivative production draws from phosphate rock deposits in Morocco, China, and the United States, with downstream formulation concentrated in Germany, China, and the Yangtze River Delta. Single-source vulnerability in specialty phosphorus intermediate supply creates qualification timeline risk for new product development. Distribution runs through integrated chemical distributors and direct technical service channels to electronics contract manufacturers and aerospace tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flame retardants chemicals constitute a late-cycle quality story as specification-driven procurement shifts volume toward bundled additive packages with embedded technical support. Electronics miniaturization and thin-wall polymer applications pull demand toward premium phosphorus-nitrogen synergists with qualification-backed pricing power.
For Market Incumbents: Anchor defensive positioning through backward integration into phosphorus intermediate supply and accelerated BIS certification database expansion in India. Reactive flame retardant technology for engineering polymers represents the critical R&D lever against emerging phosphorus-specialist compounders. Capacity addition in Gujarat and Maharashtra industrial zones secures wire and cable volume against regional formulators. For New Entrants and Emerging Players: Phosphorus-nitrogen intumescent coatings for 5G infrastructure housings offer the most penetrable white-space target given South Korean and Taiwanese electronics manufacturer specification windows. India's fragmented building materials sector presents parallel entry opportunity through pre-tested bundle partnerships with construction distributors. Go-to-market execution should emphasize embedded formulation support rather than commodity chemical spot sales. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale phosphorus compounders lacking captive feedstock but holding BIS and GB qualification databases. Long-term viability over the analysis window favors targets with reactive technology portfolios and aerospace tier-1 supplier relationships. Watch FAA certification timeline acceleration as inflection signal for intumescent system margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Intermediates | Captive supply of organophosphate precursors insulates margin from Moroccan phosphate rock price volatility. |
| BIS Certification Database Expansion | Pre-tested formulation bundles accelerate customer approval cycles in India's fragmented construction sector. |
| Reactive Technology R&D Investment | Covalent phosphorus-polymer bonding enables permanent flame resistance for automotive underhood specifications. |
| Long-term Supply Agreement with Electronics OEMs | Embedded technical service contracts lock in volume for 5G infrastructure and thin-wall device housing applications. |
| Joint Venture with Regional Distributor | Local formulation expertise in Vietnam and Mexico captures electronics contract manufacturer procurement shifts. |
Methodological Framework
Direct dialogue with plant managers at phosphorus formulation facilities, procurement leads at wire and cable OEMs, distribution channel partners in India and Southeast Asia, and technical R&D directors at integrated chemical conglomerates grounded qualitative assessment. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and GB standard enforcement documentation. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates across the analysis window.
Segment-level projections incorporate chemistry type, application specification, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs derive from elasticity modeling against construction spending, electronics production indices, and regulatory enforcement timelines. Key inputs include phosphorus derivative capacity utilization rates, BIS certification pipeline velocity, and aerospace tier-1 supplier qualification backlogs.
The model holds under steady regulatory enforcement trajectories and stable phosphate rock supply conditions; deviation in GB standard acceleration, REACH substance sunset timing, or Moroccan export policy would shift volume and value estimates. Forecasts reflect documented assumptions regarding substitution elasticity between halogenated and phosphorus-based chemistries. A small set of named triggers—FAA certification reform, MEE enforcement intensity, and Indian transmission infrastructure appropriations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sunscreen Ingredients Market
Chemicals
Elemental Fluorine Market
Chemicals
Deicing Fluid Market
Chemicals
Caustic Soda Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
CHPTAC Market
Chemicals
Periodic Acid Market
Chemicals
Valeryl Chloride Market
Chemicals
Thiourea Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Copper Oxychloride Market
Chemicals
P-Ethylphenol Market
Chemicals
Myclobutanil Market
Chemicals
Canada Methanol Market
Chemicals
United States Construction Chemicals Market
Chemicals
Saudi Arabia Construction Chemicals Market