
 Europe Methanol Market | 2026-2036
Europe Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Methanol Market Insights
Biomethanol is realigning conventional product economics as petrochemical buyers evaluate carbon-intensity metrics in procurement contracts. OCI N.V. leverages its Rotterdam bio-methanol terminal to anchor low-carbon supply chains into German chemical clusters. HELM Proman Methanol AG sustains integrated production and trading positions across Northwest Europe. Mitsubishi Gas Chemical Company Inc. competes through specialized high-purity grades for electronics and pharmaceutical solvent applications.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily via steam reforming of natural gas or coal gasification, with emerging routes through carbon dioxide hydrogenation using renewable power; it serves as a fundamental chemical building block for formaldehyde, acetic acid, and methyl tert-butyl ether synthesis, while gaining traction as a marine fuel and hydrogen carrier. Steam reforming dominates installed European capacity, though carbon dioxide hydrogenation represents the fastest-growing production method as electrolyzer costs decline and green hydrogen supply scales. Feedstock applications command the largest volume share, while fuel-grade methanol for maritime bunkering captures expanding margin pools at Rotterdam and Hamburg.
The EU Green Deal and Fit for 55 regulatory framework mandate emissions reductions that reshape methanol demand toward certified low-carbon variants, while ECHA REACH registration requirements govern chemical safety and market access for imported product. EMA fuel quality standards and IMO marine fuel regulations create compliance thresholds that differentiate certified biomethanol from conventional supply. Stakeholders must monitor carbon border adjustment mechanism implementation and renewable fuel of non-biological origin certification timelines to position procurement and investment decisions.
Market Dynamics
The EU Green Deal and Fit for 55 package are compressing the carbon-intensity window for chemical feedstocks, forcing methanol buyers to requalify suppliers against certified low-carbon benchmarks and rewiring procurement criteria across German and Dutch chemical clusters.
Growth Catalysts
- EU Green Deal:Mandatory emissions reductions under the Fit for 55 framework are pulling chemical manufacturers toward certified biomethanol supply chains, with Rotterdam-Antwerp port infrastructure enabling large-scale import and bunkering operations.
- Maritime fuel transition:IMO marine fuel regulations are creating compliance thresholds that differentiate certified biomethanol from conventional supply, with Rotterdam and Hamburg capturing expanding margin pools for fuel-grade methanol.
- Electrolyzer cost decline:Carbon dioxide hydrogenation using renewable power represents the fastest-growing production method as green hydrogen supply scales and electrolyzer economics improve across Northwestern Europe.
Market Restraints
- Natural gas price volatility:Steam reforming dominates installed European capacity, leaving producers exposed to input cost swings that compress margins and deter capacity expansion.
- Supply concentration risk:Production gravity centers on a limited set of integrated petrochemical complexes, creating vulnerability to unplanned outages or feedstock disruptions.
- Carbon border adjustment mechanism:CBAM implementation timelines create regulatory friction for imported methanol, complicating procurement decisions for buyers sourcing from non-EU suppliers.
Strategic Opportunities
- Baltic Sea bunkering corridor:Underpenetrated marine fuel infrastructure in Poland and the Baltic states offers white space for low-carbon methanol distribution networks serving emerging green shipping lanes.
- Renewable fuel of non-biological origin certification:RFNBO timelines under EU delegated acts are creating a regulatory tailwind for power-to-methanol projects that can demonstrate renewable hydrogen origin.
- Electronics-grade solvent demand:High-purity methanol for semiconductor and pharmaceutical applications commands premium positioning as supply chains decarbonize.
Industry Challenges
- REACH registration complexity:ECHA chemical safety requirements govern market access for imported product, with compliance timelines extending 18-24 months for new supply sources.
- Carbon accounting standardization:Inconsistent lifecycle assessment methodologies across certification schemes complicate buyer verification and supplier qualification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Methanol Market |
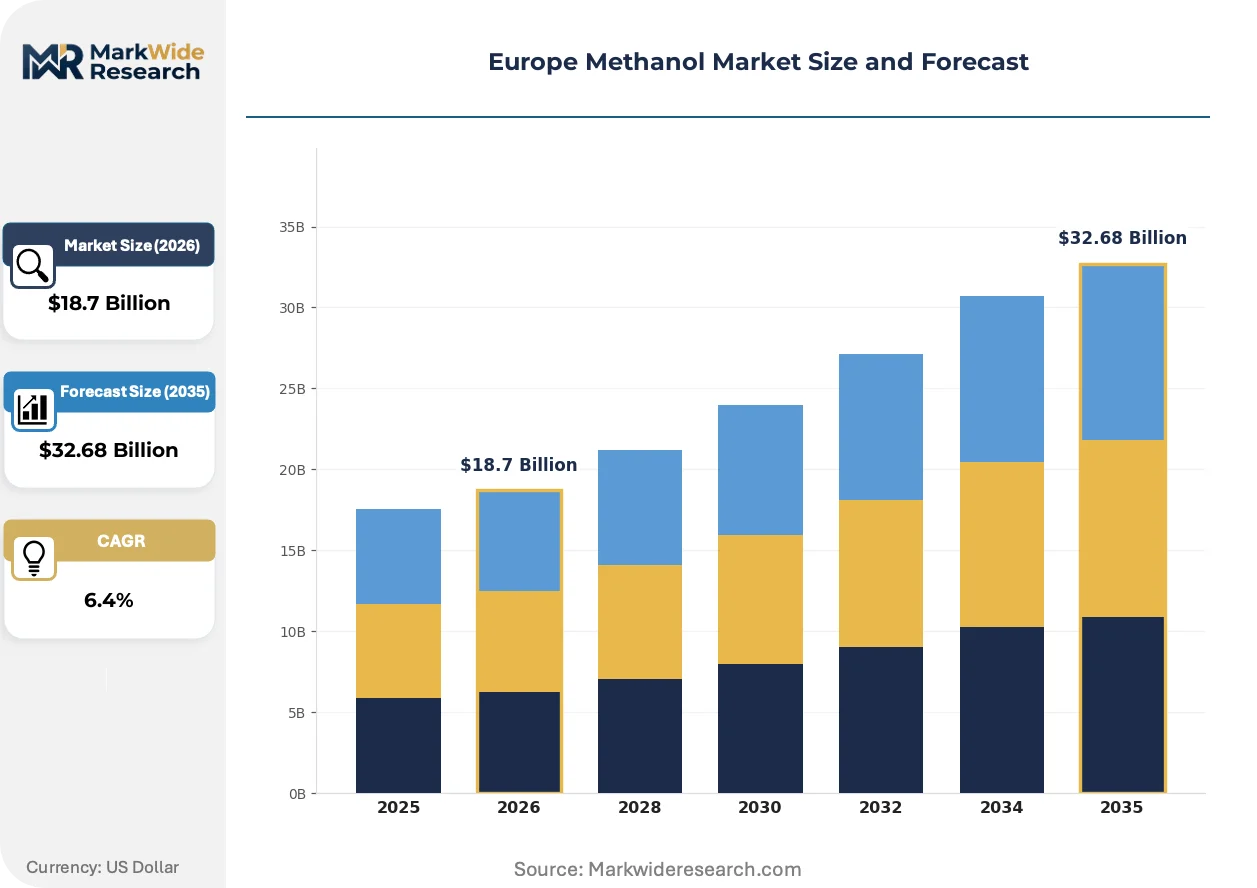
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Reforming, Partial Oxidation, Carbon Dioxide Hydrogenation, Methane Reforming End User: Automotive, Chemical Manufacturing, Energy, Construction Application: Solvent, Fuel, Feedstock, Antifreeze Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | OCI N.V., European Energy, Methanex Corporation, Mitsubishi Gas Chemical Company Inc., Celanese Corporation, HELM Proman Methanol AG, LyondellBasell Industries B.V., Metafrax Chemicals, BASF SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Methanol Market Trends and Innovations
Carbon dioxide hydrogenation is rewriting the production economics of European methanol, collapsing the cost gap between fossil and renewable routes while EMA fuel quality standards and IMO marine regulations reshape demand segmentation.
Power-to-methanol technology is rewriting conventional capacity economics by enabling modular, grid-connected production units that bypass pipeline feedstock dependencies. Chemical clusters in the Netherlands and Belgium are piloting integrated electrolyzer-reactor systems. This distributed architecture is rewriting the geographic logic of supply security, allowing buyers to source from multiple small-scale producers rather than concentrated reforming complexes.
EU delegated acts on renewable fuels of non-biological origin are tightening certification requirements for hydrogen-derived methanol, with compliance deadlines compressing investment timelines for project developers. EMA fuel quality standards now incorporate carbon-intensity thresholds that differentiate premium biomethanol grades. German chemical buyers are responding by embedding certified low-carbon clauses into long-term procurement contracts.
Carbon-intensity metrics are displacing volume-scale as the primary procurement criterion for formaldehyde and acetic acid synthesis buyers. Spot market liquidity for conventional methanol is thinning as annual contracts with certified supply guarantees capture larger share of offtake. Dutch port terminals are adapting by segregating storage and blending infrastructure to handle parallel conventional and low-carbon product streams.
Europe Methanol Market Segmentation
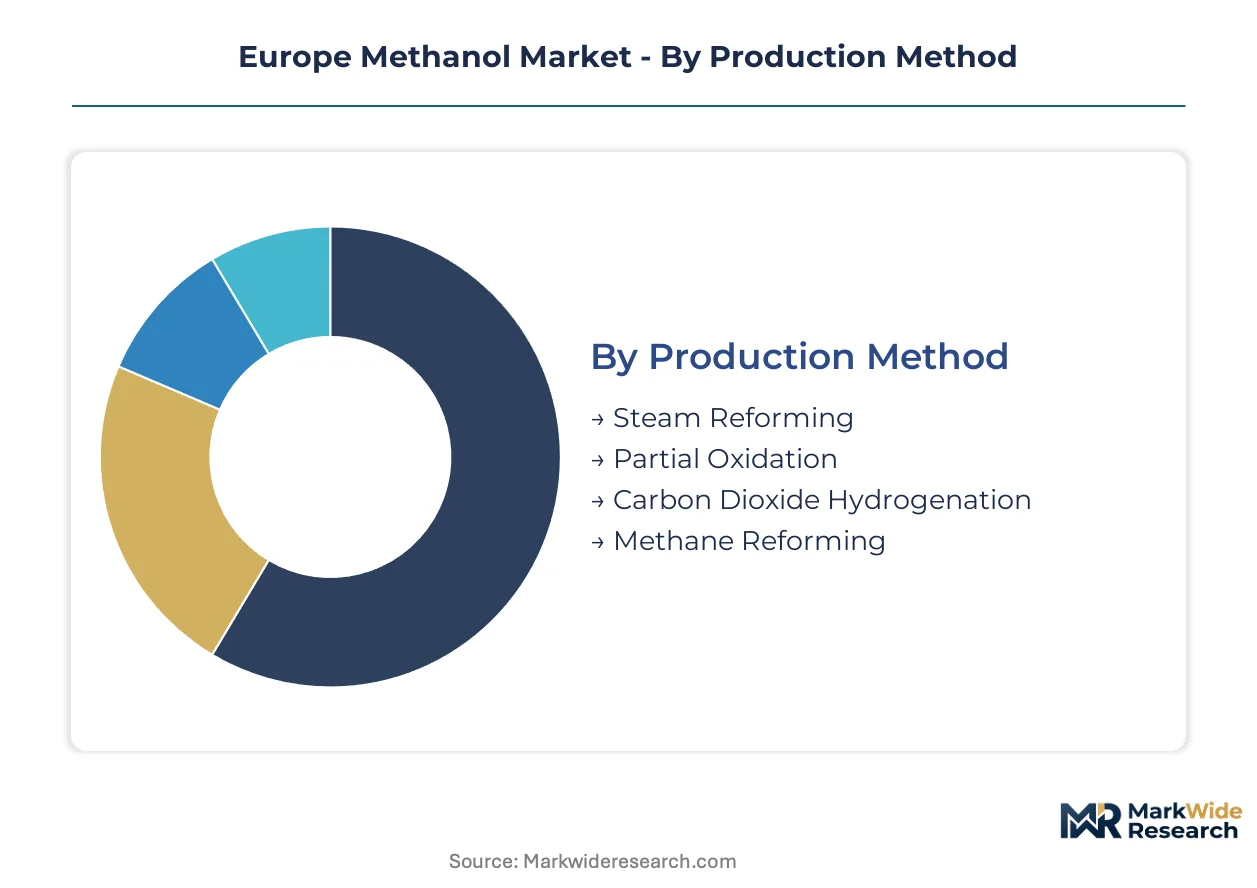
Methanol segmentation in Europe reflects diverging cost structures between incumbent fossil routes and emerging low-carbon alternatives. Procurement criteria now weight carbon intensity alongside purity specifications, reshaping how buyers evaluate production methods and end-use applications.
Production Method:
Volume-scale production still favors conventional reforming, yet premium positioning accrues to certified low-carbon routes as electrolyzer economics improve.
- Steam Reforming:Natural gas-fed steam methane reforming dominates installed European capacity, supplying formaldehyde and acetic acid synthesis clusters across Germany and the Netherlands. Rotterdam-Antwerp infrastructure anchors import volumes, though producers remain exposed to input cost volatility that compresses margins during price spikes.
- Carbon Dioxide Hydrogenation:Power-to-methanol using renewable hydrogen and captured CO₂ is climbing the fastest as electrolyzer costs decline and EU delegated acts on renewable fuels of non-biological origin create compliance tailwinds. Dutch chemical clusters pilot modular, grid-connected units that bypass pipeline dependencies.
- Partial Oxidation:Heavy feedstock gasification routes serve specialized industrial applications with tolerance for higher carbon intensity.
- Methane Reforming:Coal-based and biomass gasification variants retain niche positioning in regions with stranded feedstock access.
Today's leader: Steam Reforming. Tomorrow's challenger: Carbon Dioxide Hydrogenation.
End User:
Chemical manufacturing absorbs the largest volume flows, while maritime energy buyers command expanding margin pools at Rotterdam and Hamburg.
- Chemical Manufacturing:Formaldehyde and acetic acid synthesis anchor methanol demand across German industrial clusters, with ECHA REACH registration requirements governing market access for imported product. Buyers embed certified low-carbon clauses into long-term procurement contracts as the EU Green Deal compresses emissions windows.
- Energy:IMO marine fuel regulations create compliance thresholds for fuel-grade methanol bunkering, with Rotterdam capturing expanding margin pools and Hamburg developing parallel infrastructure. EMA fuel quality standards now incorporate carbon-intensity differentiation.
- Automotive:Fuel cell and internal combustion applications for methanol remain developmental, constrained by infrastructure gaps and competing battery-electric pathways.
- Construction:Formaldehyde-based resins for engineered wood products sustain steady offtake from building materials manufacturers.
Chemical Manufacturing commands current volume dominance. Energy is gaining share fastest on regulatory-driven fuel switching.
Application:
Feedstock applications generate scale economics, while fuel and solvent segments capture premium positioning through certification requirements.
- Feedstock:Formaldehyde, acetic acid, and methyl tert-butyl ether synthesis consume the largest methanol volumes across Northwestern European chemical clusters, with procurement shifting toward certified low-carbon supply guarantees.
- Solvent:High-purity grades for semiconductor and pharmaceutical applications command premium positioning as electronics-grade specifications tighten.
- Fuel:Maritime bunkering and blending applications expand as IMO regulations and EU Fit for 55 mandates reshape marine fuel economics.
- Antifreeze:De-icing and coolant formulations sustain steady demand from automotive and aviation sectors with moderate growth trajectory.
Feedstock retains volume leadership. Fuel is expanding most quickly on regulatory tailwinds.
Distribution Channel:
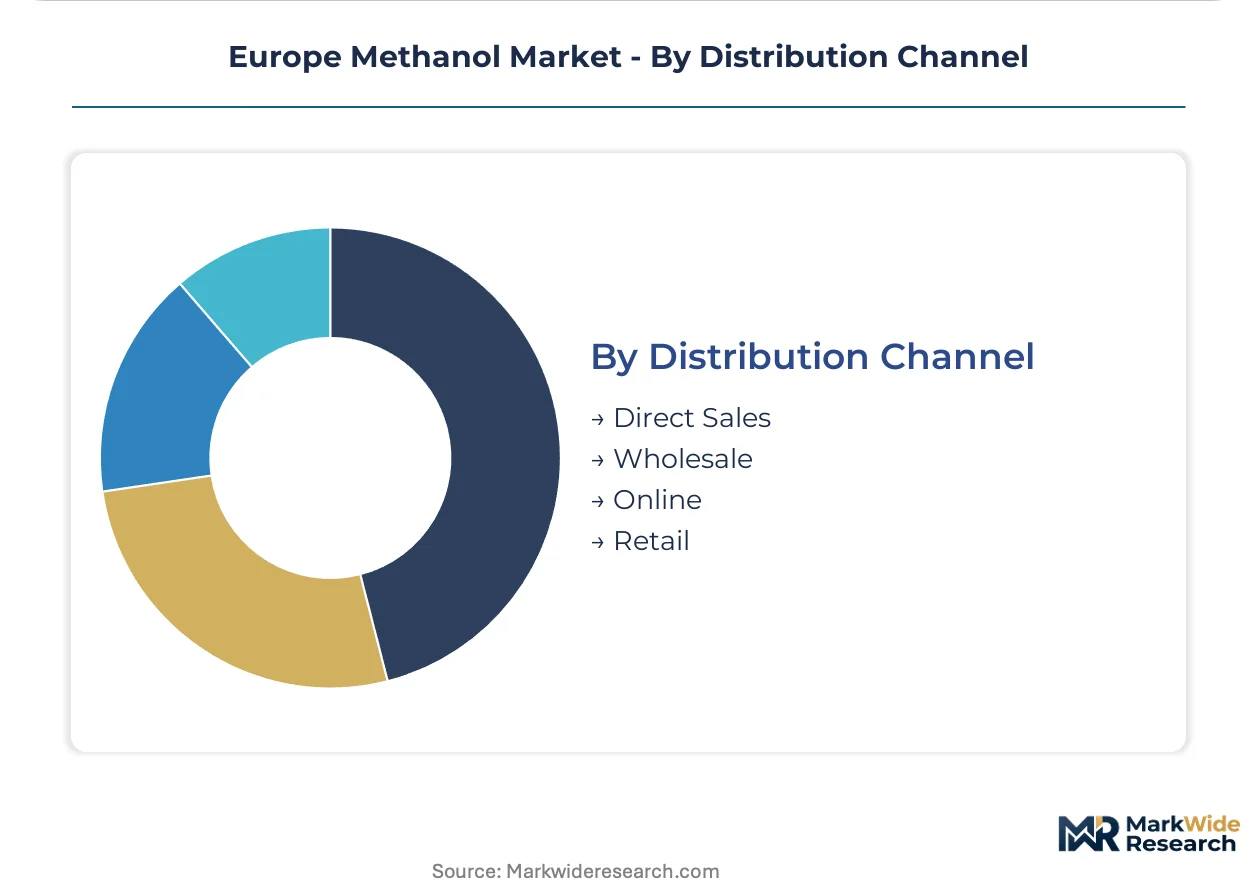
Direct sales capture contract-scale chemical offtake, while wholesale and terminal infrastructure enables spot market flexibility for fuel-grade buyers.
- Direct Sales:Long-term supply agreements dominate chemical manufacturing procurement, with annual contracts incorporating certified low-carbon clauses displacing spot market liquidity.
- Wholesale:Rotterdam and Antwerp terminal operators segregate storage infrastructure to handle parallel conventional and biomethanol streams for bunkering and blending customers.
- Online:Digital procurement platforms emerge for spot market transactions, though REACH registration complexity limits new supplier entry.
- Retail:Packaged methanol for specialty solvent and laboratory applications sustains niche distribution through chemical supply houses.
Direct Sales anchors chemical sector relationships. Wholesale is scaling fastest on maritime fuel demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-Antwerp port infrastructure anchors European methanol trade flows, with chemical clusters in Germany and the Netherlands absorbing the largest feedstock volumes. The EU Green Deal is compressing carbon-intensity thresholds across Northwestern Europe, rewiring procurement patterns toward certified low-carbon supply chains.
Germany
Formaldehyde and acetic acid synthesis clusters in North Rhine-Westphalia and Lower Saxony drive methanol consumption for chemical manufacturing. The EU Fit for 55 package mandates emissions reductions that force requalification of suppliers against certified low-carbon benchmarks. Ludwigshafen and Marl chemical parks embed certified supply clauses into long-term procurement contracts.
Netherlands
Rotterdam terminal infrastructure enables large-scale biomethanol import and bunkering operations for maritime fuel buyers. EMA fuel quality standards incorporate carbon-intensity thresholds that differentiate premium biomethanol grades. Dutch chemical clusters pilot modular power-to-methanol units that bypass pipeline feedstock dependencies.
Belgium
Antwerp port facilities support blending and distribution for fuel-grade methanol serving North Sea shipping lanes. The EU Green Deal accelerates investment in low-carbon methanol production capacity across Flanders industrial zones. Ghent and Antwerp chemical complexes adapt storage infrastructure to segregate conventional and certified low-carbon product streams.
France
Formaldehyde-based resins for engineered wood products sustain steady methanol offtake from construction materials manufacturers in Grand Est and Hauts-de-France. ECHA REACH registration requirements govern market access for imported product with compliance timelines extending 18-24 months. Le Havre port develops parallel infrastructure for conventional and biomethanol handling.
Poland
Underpenetrated marine fuel infrastructure in Baltic Sea ports offers white space for low-carbon methanol distribution networks. IMO marine fuel regulations create compliance thresholds that favor certified biomethanol over conventional supply. Gdańsk and Szczecin terminals evaluate storage expansion to capture emerging green shipping lane demand.
Europe Methanol Market Competitive Landscape
Global majors compete with regional champions across production scale and carbon-certification capabilities. The vendor base spans integrated petrochemical conglomerates, specialized methanol traders, and emerging power-to-methanol developers. Three archetypes dominate: legacy reforming operators with Rotterdam-Antwerp terminal positions, electrolyzer-integrated project developers capturing RFNBO premiums, and high-purity specialists serving electronics and pharmaceutical solvent markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves as electrolyzer economics improve.
Among integrated chemical conglomerates, BASF SE and LyondellBasell Industries B.V. occupy positions that exemplify the legacy reforming archetype with established supply chain infrastructure. OCI N.V. represents the emerging low-carbon transition, anchoring biomethanol terminal capabilities that align with EU Green Deal procurement requirements. These three entities illustrate the competitive tension between incumbent scale advantages and certified low-carbon positioning.
| Leading Market Players |
|---|
| OCI N.V. |
| European Energy |
| Methanex Corporation |
| Mitsubishi Gas Chemical Company Inc. |
| Celanese Corporation |
| HELM Proman Methanol AG |
| LyondellBasell Industries B.V. |
| Metafrax Chemicals |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Carbon dioxide hydrogenation is collapsing the cost gap between fossil and renewable methanol routes while simultaneously fragmenting supply concentration across Northwestern Europe. This production-method transition rewires procurement economics as modular power-to-methanol units bypass traditional pipeline dependencies and Rotterdam-Antwerp terminal monopolies.
Pricing Analysis
Natural gas price pass-through dominates conventional methanol pricing, exposing steam reforming operators to margin compression during input cost spikes while carbon-certified biomethanol commands premium positioning. Contract-based long-term offtake structures anchor chemical manufacturing procurement, with certified low-carbon clauses and volume scale serving as primary price differentiation drivers. Price erosion runs through conventional grades as EU Green Deal compliance thresholds harden, while fuel-grade buyers at Rotterdam and Hamburg show least price sensitivity due to regulatory-driven fuel switching mandates.
Supply Chain Analysis
Reverse-logistics flows for captured carbon dioxide and green hydrogen feedstock are rewiring upstream supply architecture for power-to-methanol projects. Production concentrates in the Netherlands, Belgium, and Germany, with Dutch chemical clusters drawing from offshore wind electrolyzer arrays and industrial CO₂ capture streams. Supply chain risk centers on single-source electrolyzer equipment dependencies from Chinese and German manufacturers. Distribution runs through Rotterdam-Antwerp terminal infrastructure for conventional volumes, while modular production units enable direct pipeline connections to German chemical parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe methanol market functions as a regulatory compounder where EU Fit for 55 emissions mandates are accelerating demand recalibration toward certified low-carbon supply chains.
For Market Incumbents: Anchor terminal infrastructure advantages at Rotterdam and Antwerp by segregating storage for parallel conventional and biomethanol streams. Invest in backward integration into electrolyzer partnerships to secure renewable hydrogen feedstock access. Defend against power-to-methanol entrants by embedding decade-long certified supply clauses into German chemical buyer contracts. For New Entrants and Emerging Players: Baltic Sea port operators represent the most penetrable buyer archetype for low-carbon methanol distribution networks. Target Poland and the Baltic states where underpenetrated bunkering infrastructure meets emerging green shipping lane demand. Pursue joint venture structures with local terminal developers to bypass 18-24 month ECHA REACH registration barriers. For Investors and Strategic Acquirers: Roll-up economics work for electrolyzer-integrated project developers because RFNBO certification timelines are compressing investment windows and fragmenting operational scale across multiple small-scale units. Prioritize power-to-methanol platforms with demonstrated renewable hydrogen offtake agreements. Monitor EU delegated act implementation on renewable fuels of non-biological origin as the inflection signal for certification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Supply | Secures renewable hydrogen access for Rotterdam chemical clusters under EU Green Deal compliance. |
| Long-term Supply Agreement with Certified Clauses | Locks German formaldehyde producers into low-carbon methanol offtake ahead of CBAM implementation. |
| Joint Venture for Baltic Sea Terminal Expansion | Captures emerging green shipping lane demand at Gdańsk and Szczecin ports. |
| Green Certification Program for RFNBO Compliance | Enables premium positioning for power-to-methanol units under EU delegated acts. |
| Capacity Expansion at Antwerp Blending Facilities | Segregates conventional and biomethanol storage to serve differentiated marine fuel grades. |
Research Methodology
Multiple input streams — executive interviews with methanol plant managers and procurement leads at German chemical OEMs, trade data from Cefic and customs authorities, and SEC filings from integrated petrochemical conglomerates — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured operational perspectives from Rotterdam terminal operators, Dutch distribution channel partners, and technical R&D directors at electrolyzer-integrated project developers. Secondary validation drew from ECHA REACH registration databases, EMA fuel quality standard disclosures, and IMO marine regulation implementation tracking.
Historical production and trade flows were cross-referenced against panel input from industry stakeholders to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include production method tier, end-use industry concentration, and regional port infrastructure access. CAGRs were derived from supply-demand balance projections incorporating electrolyzer cost decline curves and regulatory compliance timeline assumptions. Forecast inputs incorporated carbon border adjustment mechanism phase-in schedules and renewable fuel certification adoption rates.
Inputs from ECHA registration databases and port authority throughput statistics were available through the study window; gaps in power-to-methanol project development timelines introduce uncertainty bands around capacity addition assumptions. Practitioners should monitor EU delegated act finalization on renewable fuels of non-biological origin and electrolyzer equipment delivery schedules for early signals of supply inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Penoxsulam Market
Chemicals
1-Methylimidazole Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Benzenoid Market
Chemicals
Linear Mercaptans Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Thioacetic Acid Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Global Glycol Ether Market
Chemicals
Global Methylene Chloride Market
Chemicals
Valeryl Chloride Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market