
 Chitosan-Based Biomaterials Market | 2026-2036
Chitosan-Based Biomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan-Based Biomaterials Market Outlook
China is fragmenting chitosan biomaterial supply chains as domestic processors expand deacetylation capacity and challenge established European suppliers. Heppe Medical Chitosan GmbH leverages vertical integration from crustacean sourcing to pharmaceutical-grade purification, sustaining quality premiums in wound healing applications. KitoZyme S.A. anchors non-animal chitosan production through fungal fermentation, differentiating its portfolio for vegan cosmetics and halal pharmaceutical markets.
Chitosan-based biomaterials comprise deacetylated chitin polymers with molecular weights ranging from 50 to 2,000 kDa and degrees of deacetylation between 70% and 95%, processed through alkaline hydrolysis or enzymatic methods to yield biocompatible, antimicrobial matrices for controlled release and tissue scaffolding. Chitosan gels command premium positioning in drug delivery as formulators exploit tunable viscosity and mucoadhesive properties for nasal and ocular administration. Wound healing applications compete on absorption capacity and hemostatic performance, with chitosan powders dominating agricultural formulations where cost sensitivity shapes procurement.
FDA biocompatibility ISO 10993 testing requirements govern US market entry for implantable chitosan devices, while REACH registrations in Europe constrain raw material sourcing from non-compliant Asian suppliers. China's NMPA has tightened medical device classification rules for tissue-engineering scaffolds, extending approval timelines for novel formulations. Stakeholders must monitor regulatory divergence between jurisdictions as divergent biocompatibility standards reshape competitive access and localization requirements.
Market Dynamics
The EU Medical Device Regulation is compressing certification timelines for implantable chitosan scaffolds, forcing manufacturers to front-load biocompatibility testing investments and consolidate supplier relationships before 2027 enforcement deadlines.
Growth Catalysts
- Pharmaceutical drug delivery systems:Clinicians are prioritizing biodegradable polymer alternatives for controlled-release formulations, with chitosan gels displacing synthetic matrices in nasal and ocular administration routes.
- REACH registration compliance:European raw material sourcing constraints are filtering non-compliant Asian suppliers, creating protected market access for certified European processors.
- Fungal fermentation methods:Non-animal chitosan production is unlocking vegan cosmetics and halal pharmaceutical certifications previously inaccessible to crustacean-derived supply chains.
Market Restraints
- Crustacean shell supply volatility:Seasonal fishing yields and aquaculture disease outbreaks create input cost instability for alkaline hydrolysis processors dependent on shrimp and crab waste streams.
- China deacetylation capacity expansion:Domestic processors are eroding European quality premiums through scale-driven cost compression in agricultural-grade chitosan powders.
- ISO 10993 testing burden:FDA biocompatibility requirements for implantable devices impose 18-24 month premarket notification timelines that freeze capital deployment for novel formulations.
Strategic Opportunities
- Tissue-engineering scaffold classification:China's NMPA medical device rule changes are extending approval timelines, creating first-mover advantage for European firms with existing dossier templates.
- Wound healing hemostatic powders:Military and emergency medicine procurement channels are expanding absorption capacity specifications beyond civilian hospital standards.
- 3D bioprinting convergence:Crosslinking chitosan with collagen and alginate is enabling vascularized tissue constructs for organ-on-chip applications.
Industry Challenges
- Pharmaceutical-grade purification expertise:The talent pool for endotoxin removal and molecular weight fractionation remains concentrated in German and Belgian research clusters.
- Dual certification complexity:Simultaneous FDA and EMA dossier preparation requires redundant toxicology studies that strain mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan-Based Biomaterials Market |
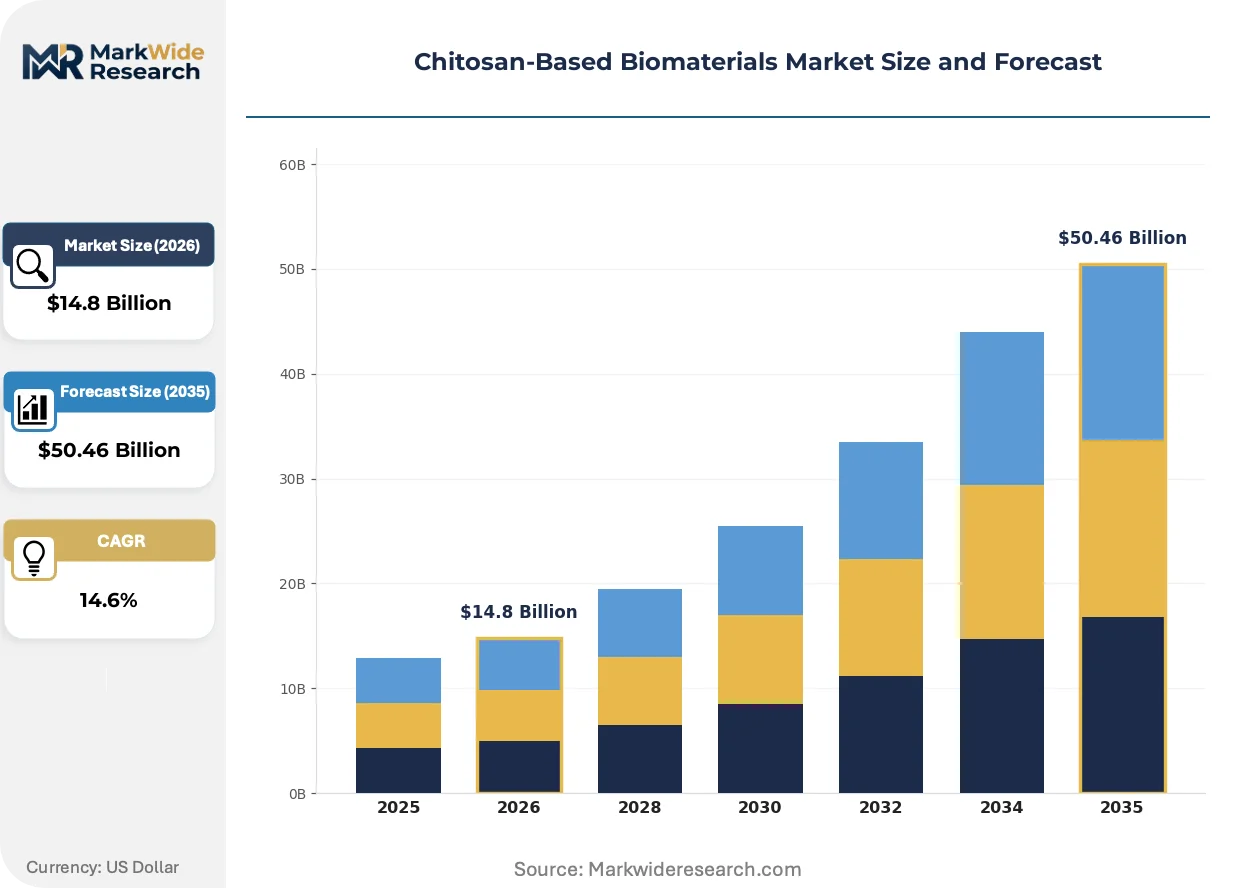
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $50.46 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitosan Flakes, Chitosan Powders, Chitosan Films, Chitosan Gels End User: Pharmaceuticals, Agriculture, Food Industry, Cosmetics Application: Drug Delivery, Wound Healing, Water Treatment, Tissue Engineering Form: Granules, Solutions, Coatings, Tablets |
| Companies Covered | Heppe Medical Chitosan GmbH, BioLog Heppe GmbH, KitoZyme S.A., United Chitotechnologies Inc., Advanced Biopolymers AS, Biophrame Technologies, Meron Biopolymers, Qingdao Yunzhou Biochemistry Co., Primex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan-Based Biomaterials Market Strategic Shifts
Enzymatic deacetylation methods are displacing alkaline hydrolysis as the dominant processing technology, reshaping cost structures and enabling molecular weight precision previously unattainable through chemical routes.
Enzymatic processing is collapsing the cost gap between pharmaceutical-grade and technical-grade chitosan production. Contract manufacturers in Belgium and the Netherlands are adopting fungal-derived enzyme cocktails at commercial scale. This compression is enabling mid-tier suppliers to enter drug delivery markets previously reserved for vertically integrated specialists.
REACH registration deadlines for polymer intermediates are accelerating supplier consolidation across European raw material channels. ECHA compliance costs are filtering smaller Asian traders from the import market. German wound dressing manufacturers are responding by locking multi-year supply agreements with certified domestic processors.
Hospital procurement departments are unbundling hemostatic performance specifications from bundled surgical supply contracts. Standalone chitosan powder tenders are displacing integrated kit purchasing in German and French trauma centers. This disintermediation is most visible in metropolitan hospital networks seeking direct supplier relationships for custom absorption profiles.
Chitosan-Based Biomaterials Market Segmentation
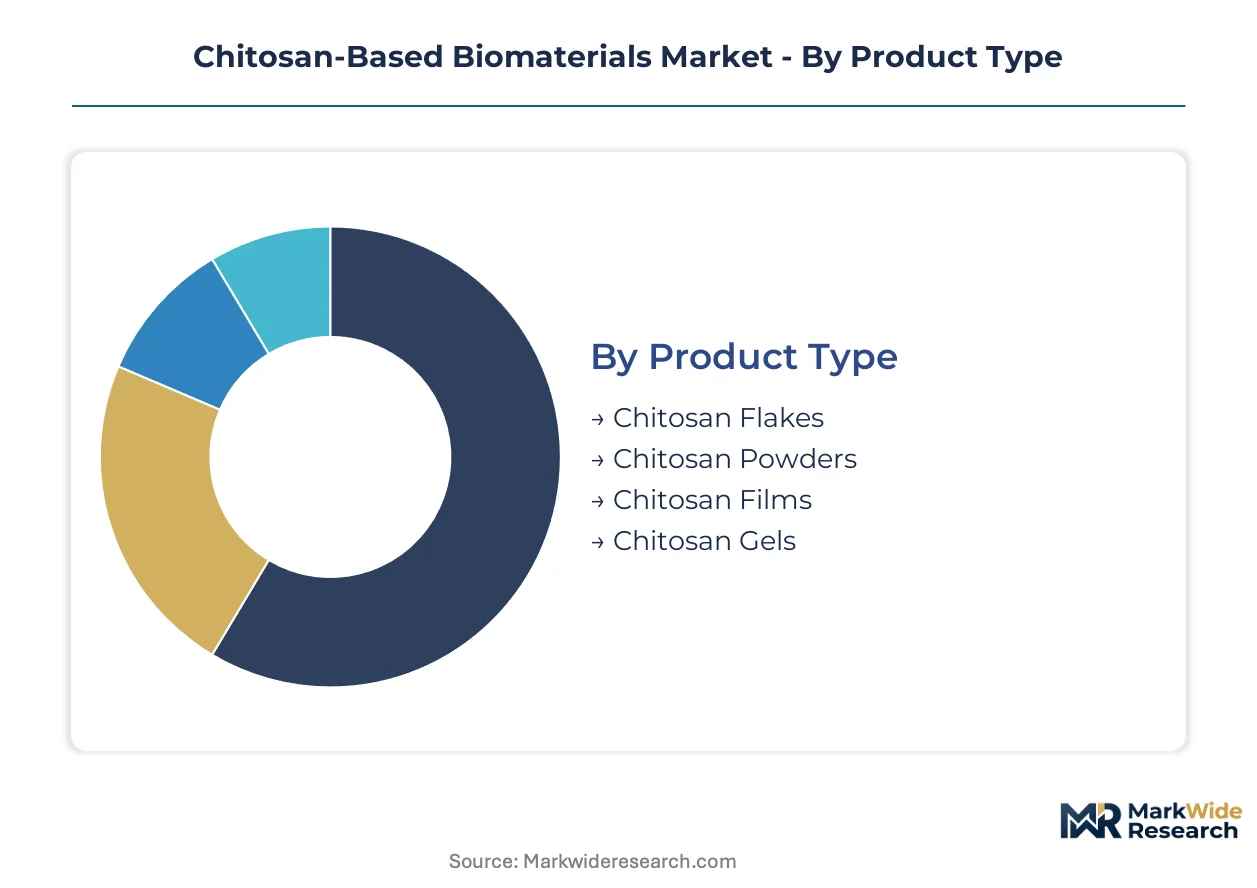
Segmentation in chitosan biomaterials reveals how molecular weight distribution and processing methods create divergent margin profiles across pharmaceutical versus agricultural channels. Formulators select product types based on viscosity requirements and endotoxin thresholds that vary sharply by end-use application.
Product Type:
Chitosan flakes turn over fastest in agricultural blending operations, while pharmaceutical-grade gels require extended stability testing that stretches inventory cycles.
- Chitosan Gels:Tunable viscosity matrices with mucoadhesive properties enable nasal and ocular drug delivery. Demand concentrates in German pharmaceutical clusters where REACH-registered suppliers command certification premiums for implantable device formulations.
- Chitosan Powders:Absorption-optimized grades dominate wound healing hemostats and agricultural formulations. Procurement in French trauma centers is disintermediating from bundled surgical kits toward standalone tenders specifying absorption capacity thresholds.
- Chitosan Flakes:Intermediate processing form for industrial-scale deacetylation operations serving agricultural and water treatment sectors.
- Chitosan Films:Barrier membranes for tissue engineering scaffolds requiring controlled biodegradation rates in vascularized construct applications.
Chitosan powders dominate installed base. Chitosan gels are where expansion concentrates.
End User:
Cost tiers separate pharmaceutical-grade purification investments from technical-grade commodity sales.
- Pharmaceuticals:Controlled-release formulations and tissue-engineering scaffolds require endotoxin removal and molecular weight fractionation. FDA ISO 10993 testing timelines freeze capital deployment for novel implantable devices.
- Agriculture:Biopesticide carriers and soil amendment applications prioritize cost-per-ton metrics over purity specifications.
- Cosmetics:Vegan certification requirements are accelerating fungal-derived chitosan adoption for halal and cruelty-free product lines.
- Food Industry:Edible film coatings and preservative applications utilize food-grade deacetylation protocols with lower molecular weight thresholds.
Pharmaceuticals capture value concentration. Agriculture absorbs volume scale.
Application:
Customer workflows differentiate between acute intervention settings and chronic administration protocols.
- Drug Delivery:Mucoadhesive gels for nasal and ocular routes displace synthetic polymer matrices. Formulators in Belgian contract manufacturing facilities are adopting enzymatic processing to collapse cost gaps between pharmaceutical and technical grades.
- Wound Healing:Hemostatic powders with absorption capacity specifications are expanding beyond civilian hospital standards into military and emergency medicine procurement channels.
- Tissue Engineering:Crosslinked scaffolds with collagen and alginate enable vascularized constructs for organ-on-chip applications.
- Water Treatment:Flocculation applications utilize lower-grade chitosan with broader molecular weight distribution tolerances.
Wound healing commands near-term procurement volume. Drug delivery is climbing the fastest.
Form:
Supply concentration in German and Belgian processing clusters shapes availability by physical presentation.
- Solutions:Ready-to-formulate liquid chitosan for pharmaceutical and cosmetics manufacturing with specified viscosity ranges.
- Granules:Free-flowing intermediate form for agricultural blending and water treatment bulk handling operations.
- Coatings:Pre-functionalized surface treatments for medical device integration and food packaging barrier layers.
- Tablets:Compressed dosage forms for direct oral administration and controlled-release matrix applications.
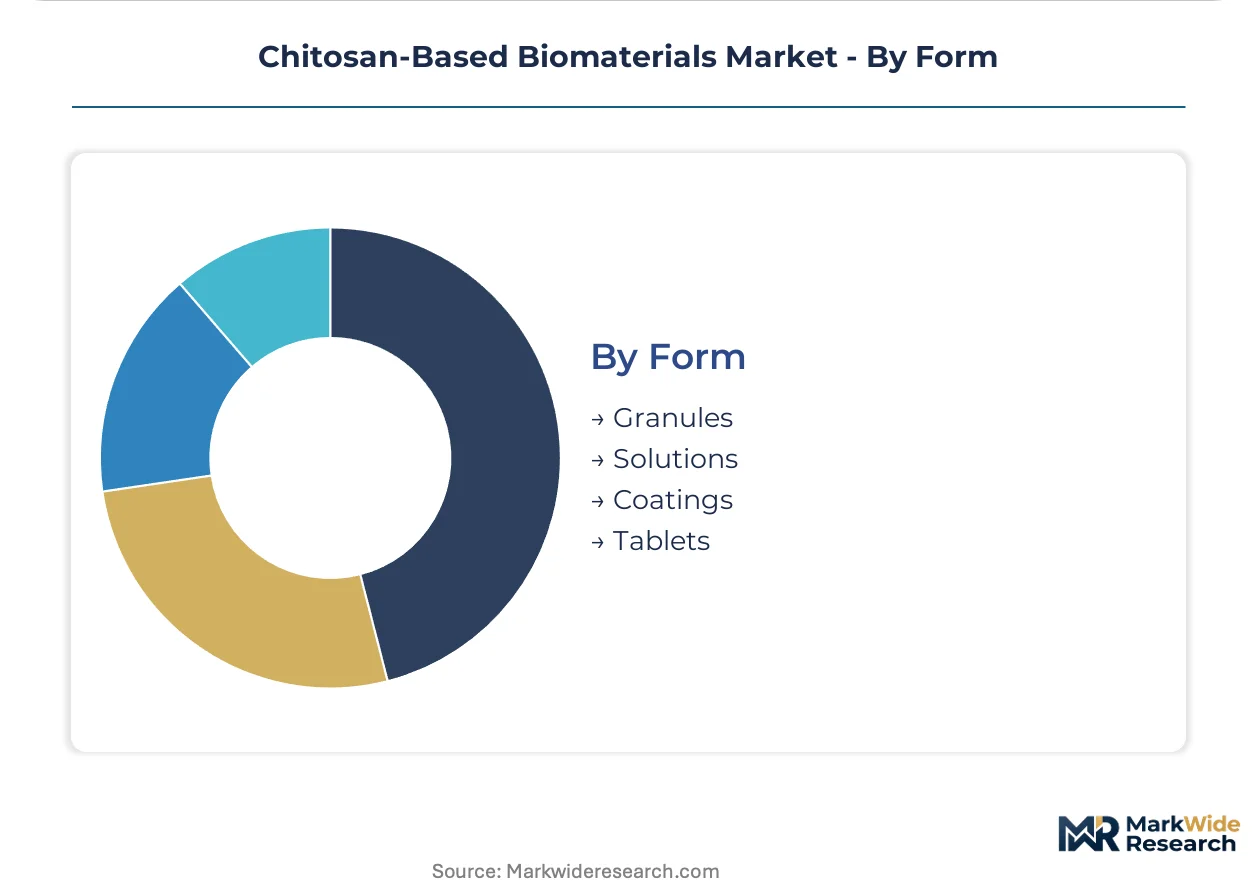
Solutions dominate pharmaceutical input channels. Coatings are gaining share fastest in device integration applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chitosan biomaterial processing clusters in Germany, Belgium, and the Netherlands anchor European supply capacity, while Chinese capacity expansion and US regulatory complexity reshape competitive access patterns.
Germany
Pharmaceutical-grade purification demand concentrates around Heppe Medical Chitosan GmbH and specialized research clusters in Saxony-Anhalt. ECHA REACH registrations for polymer intermediates filter non-compliant imports, protecting domestic processors. The Leipzig-Halle logistics corridor enables just-in-time delivery to wound dressing manufacturers.
China
Domestic deacetylation capacity expansion challenges European quality premiums in agricultural-grade powders. NMPA medical device classification rules for tissue-engineering scaffolds extend approval timelines for novel formulations. Yangtze River Delta processors scale alkaline hydrolysis operations for cost-driven export markets.
United States
Clinicians prioritize biodegradable polymer alternatives for controlled-release drug delivery formulations. FDA ISO 10993 biocompatibility testing requirements impose 18-24 month premarket notification timelines for implantable devices. Greater Boston and San Diego biotech clusters concentrate contract manufacturing demand.
Belgium
Fungal fermentation methods unlock vegan cosmetics and halal pharmaceutical certifications previously inaccessible to crustacean-derived supply chains. KitoZyme S.A. anchors non-animal chitosan production through proprietary enzyme technology. Ghent-Leuven research networks commercialize enzymatic deacetylation at industrial scale.
France
Hospital procurement departments disintermediate hemostatic powders from bundled surgical supply contracts. ANSM biocompatibility standards align with EMA guidance for implantable scaffolds. Paris and Lyon metropolitan trauma centers issue standalone tenders specifying absorption capacity thresholds.
Chitosan-Based Biomaterials Market Competitive Environment
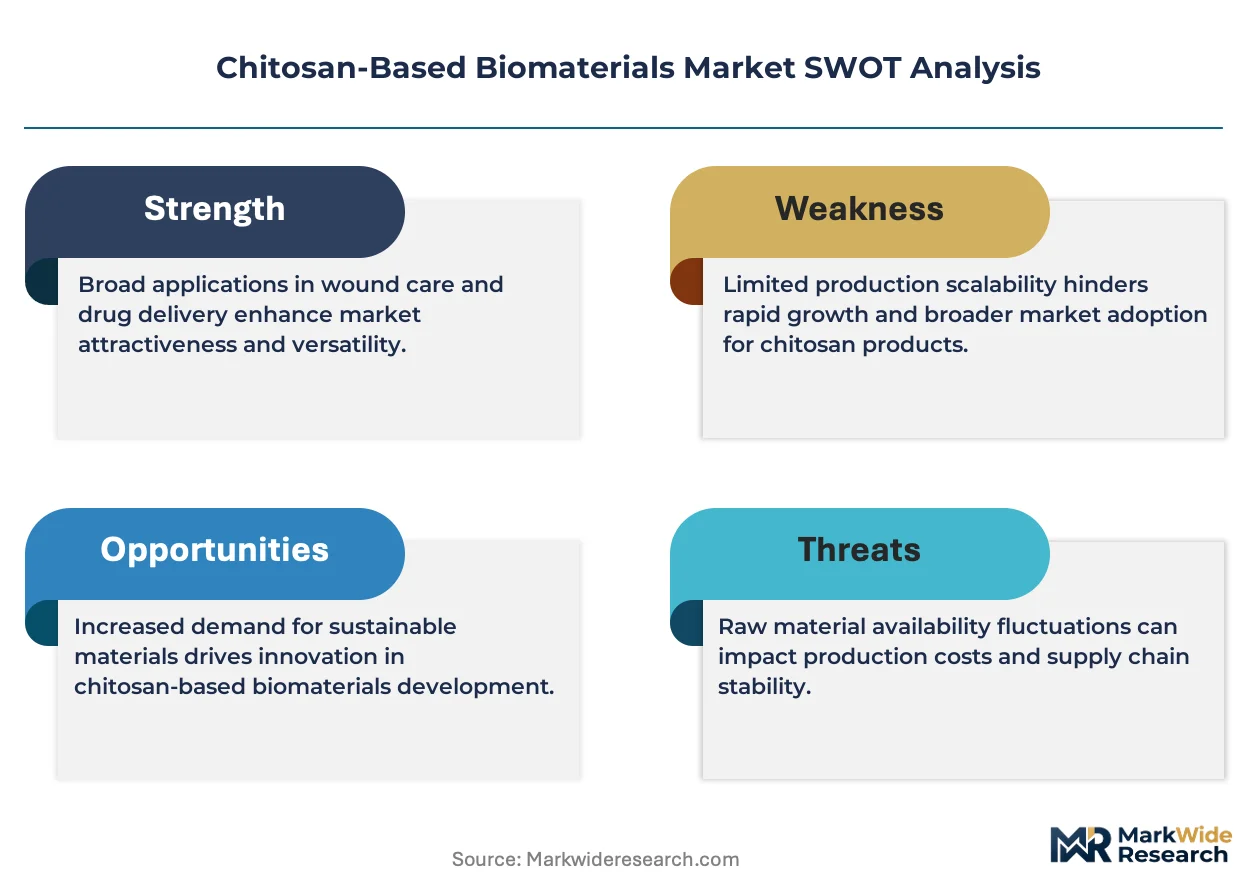
Platform integrators command the system tier; component specialists sit upstream. The vendor base separates into three functional layers: vertically integrated processors controlling crustacean sourcing through pharmaceutical purification, contract manufacturers adopting enzymatic methods to collapse grade cost gaps, and regional traders filtered by REACH compliance costs. Consolidation pressures concentrate among mid-cap specialists facing dual FDA-EMA certification burdens. Capacity expansion and strategic partnerships dominate competitive moves as firms secure multi-year supply agreements before 2027 EU MDR enforcement deadlines.
Among German GmbH-structured processors, Heppe Medical Chitosan GmbH and BioLog Heppe GmbH exemplify vertical integration archetypes spanning raw material sourcing to pharmaceutical-grade output. Belgian S.A.-incorporated KitoZyme S.A. represents the non-animal fermentation specialist tier, occupying a differentiated position in vegan and halal certification markets.
| Leading Market Players |
|---|
| Heppe Medical Chitosan GmbH |
| BioLog Heppe GmbH |
| KitoZyme S.A. |
| United Chitotechnologies Inc. |
| Advanced Biopolymers AS |
| Biophrame Technologies |
| Meron Biopolymers |
| Qingdao Yunzhou Biochemistry Co. |
| Primex |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta's deacetylation capacity expansion is compressing agricultural-grade chitosan powder margins, forcing European processors to defend pharmaceutical-grade premiums through REACH certification barriers and endotoxin removal expertise.
Pricing Analysis
REACH registration compliance dictates the pricing tier structure across European chitosan biomaterial channels. Pricing stratifies across pharmaceutical-grade, technical-grade, and agricultural-grade tiers, with FDA ISO 10993 certification and ECHA polymer intermediate registration serving as the primary price differentiation drivers. Cost compression in agricultural powders is intensifying because Chinese alkaline hydrolysis processors are scaling output for export markets. Agriculture absorbs volume scale with acute price sensitivity, while pharmaceutical drug delivery formulators prioritize endotoxin thresholds over unit cost.
Supply Chain Analysis
Crustacean shell supply volatility between Southeast Asian fishing grounds and European processing hubs dominates supply chain risk assessment for alkaline hydrolysis operators. Production gravity centers on Germany, Belgium, and the Netherlands for pharmaceutical-grade purification, while China anchors agricultural-grade powder output. Raw material procurement draws from shrimp aquaculture waste streams, crab shell aggregators, and fungal fermentation biomass for non-animal alternatives. Single-source vulnerability in crustacean waste concentration creates input cost instability during seasonal yield fluctuations. Distribution runs through specialized chemical distributors for pharmaceutical channels and bulk commodity traders for agricultural formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chitosan-based biomaterials sit in early-cycle expansion as enzymatic processing collapses cost gaps between pharmaceutical and technical grades, unlocking mid-tier supplier entry into drug delivery markets previously reserved for vertically integrated specialists.
For Market Incumbents: Harden supply agreements with REACH-registered crustacean processors before EU MDR enforcement deadlines compress certification timelines. Deepen backward integration into fungal fermentation capacity to offset shell supply volatility and capture vegan cosmetics demand. Prioritize endotoxin removal talent retention as Belgian contract manufacturers adopt enzymatic methods that erode traditional quality premiums. For New Entrants and Emerging Players: Non-animal chitosan production for halal pharmaceutical and vegan cosmetic certifications represents the most penetrable entry point, given crustacean-derived supply chains cannot access these certification-locked segments. Fungal fermentation methods in Belgian and Dutch research clusters offer technology licensing pathways that bypass capital-intensive alkaline hydrolysis infrastructure. Target enzymatic processing partnerships with Ghent-Leuven commercialization networks as a go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence between FDA ISO 10993 and EU MDR biocompatibility standards is creating protected market access for dual-certified processors. Acquisition targets should display existing dossier templates for implantable scaffolds and locked multi-year supply agreements with German wound dressing manufacturers. Monitor NMPA tissue-engineering scaffold approval timelines as the signal for Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Belgian contract manufacturers adopting fungal-derived enzyme cocktails collapse pharmaceutical-technical grade cost gaps. |
| REACH Registration Completion | ECHA compliance investments filter non-compliant Asian traders, protecting European processor market access. |
| EU MDR Certification Pathway | Front-loaded biocompatibility testing secures implantable scaffold market position before enforcement deadlines. |
| Fungal Fermentation Capacity Addition | Non-animal production unlocks vegan cosmetics and halal pharmaceutical certifications inaccessible to crustacean supply chains. |
| Hospital Procurement Direct Engagement | Standalone hemostatic powder tenders in German and French trauma centers disintermediate bundled surgical kit purchasing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, FDA 510(k) filings, and EU MDR technical documentation. Primary interviews engaged pharmaceutical formulators, wound dressing procurement managers at German hospital networks, chitosan purification plant engineers, and regulatory affairs specialists at Belgian fermentation facilities. Secondary validation drew from customs trade data for crustacean shell imports, SEC filings of listed biomaterial processors, and ANSM biocompatibility guidance documents. Bottom-up volume estimates from end-use application demand triangulated against top-down supply capacity assessments across German and Chinese processing clusters.
Forecast inputs span molecular weight distribution requirements by application, deacetylation degree specifications for pharmaceutical versus agricultural grades, enzymatic versus alkaline hydrolysis cost curves, and regional regulatory cluster adoption timelines. Segmentation modeling incorporates product type, end user industry, application workflow, and physical form dimensions alongside certification tier as an industry-specific stratification layer. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules across the analysis window.
Practitioners should monitor NMPA tissue-engineering scaffold classification revisions, ECHA polymer intermediate registration deadline compliance rates, and enzymatic processing cost compression trajectories for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
North America Chitosan Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Atelocollagen Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Hydrogel Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Heparin Market