
 Chitosan Oligosaccharides Market | 2026-2036
Chitosan Oligosaccharides Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan Oligosaccharides Market Outlook
Capital-intensity divergence between enzymatic bioreactor operators and traditional chemical hydrolysis plants is rotating competitive advantage toward firms with in-house fermentation capacity. Kunpoong Bio Co., Ltd. leverages integrated crustacean sourcing from South Korean aquaculture zones to secure feedstock consistency. Golden-Shell Pharmaceutical Co., Ltd. anchors its position through pharmaceutical-grade certification pipelines serving domestic drug manufacturers. Yaizu Suisankagaku Co., Ltd. specializes in ultra-low molecular weight fractions for functional food applications, occupying a premium tier in Japanese nutraceutical supply chains.
Chitosan oligosaccharides comprise short-chain beta-1,4-linked D-glucosamine oligomers, typically spanning 2–20 degrees of polymerization, produced through enzymatic or acidic depolymerization of chitosan derived from crustacean exoskeletons; these water-soluble biopolymers function primarily as bioactive ingredients with demonstrated prebiotic, antimicrobial, and film-forming properties. Powder formulations dominate bulk ingredient transactions due to superior stability during long-haul logistics, while liquid concentrates capture expanding demand from beverage fortification programs where rapid dissolution matters. Nutraceutical applications lead volume absorption as functional-food brands incorporate immune-modulation claims, whereas pharmaceutical-grade segments concentrate margin pools where endotoxin-controlled production commands certification premiums.
Japan's PMDA and South Korea's MFDS enforce distinct pharmacopeial standards for chitosan-derived excipients, compelling exporters to maintain parallel quality-management systems. China's NMPA and GB standards govern food-additive registrations, creating a dual-track compliance burden for cross-border suppliers. REACH registration requirements in Europe further filter market access for Asian producers lacking toxicological dossiers. Stakeholders must monitor regulatory divergence in purity metrics and novel-food approval pathways as jurisdictions tighten biopolymer safety frameworks.
Market Dynamics
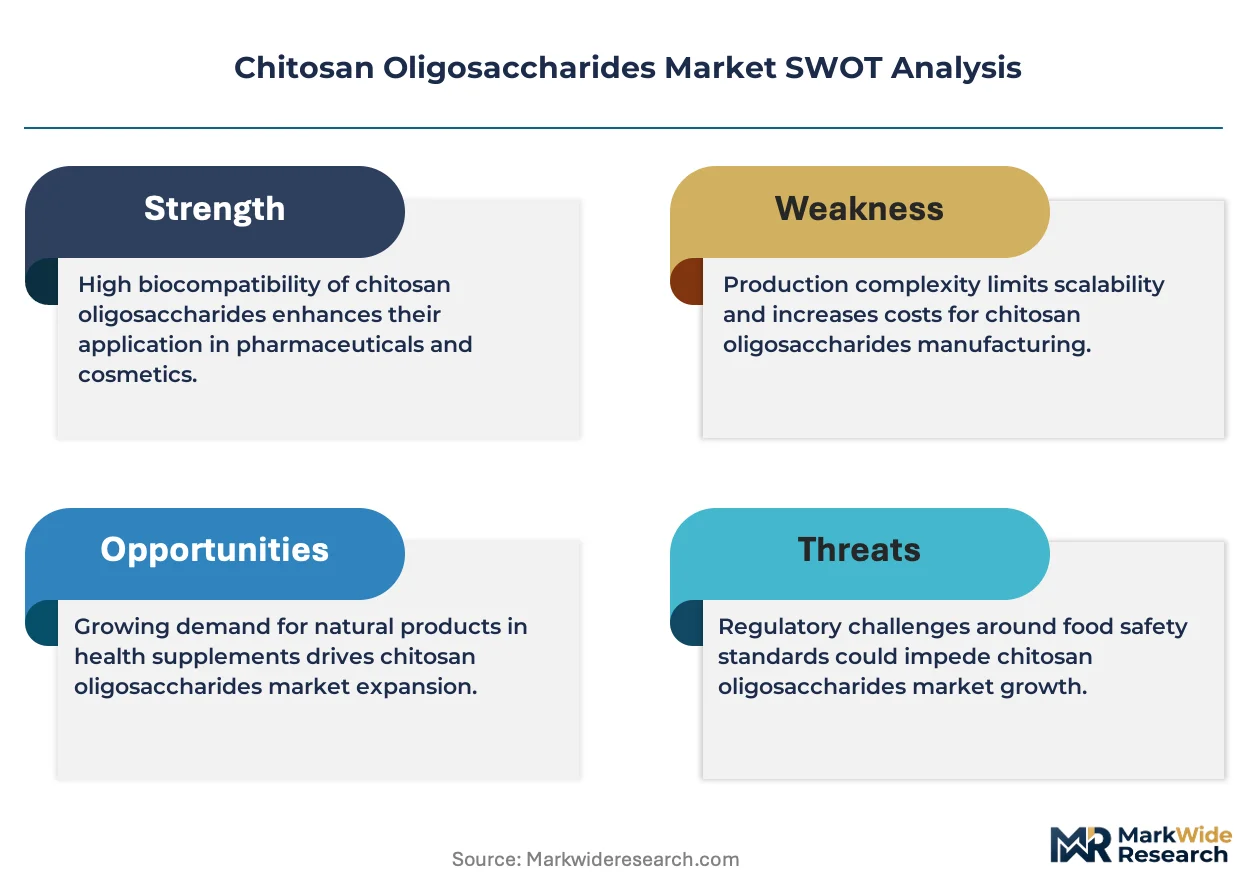
Enzymatic hydrolysis bioreactors are displacing acid-catalyzed depolymerization as the dominant production pathway, concentrating competitive advantage among firms with in-house fermentation capacity and crustacean supply chain control.
Growth Catalysts
- Prebiotic formulation demand:Functional food brands in Japan and South Korea are accelerating procurement of low-molecular-weight grades for gut-health positioning, pulling volume through nutraceutical channels.
- REACH registration completion:Asian producers securing toxicological dossiers for European market access are unlocking premium pricing tiers previously blocked by regulatory barriers.
- Pharmaceutical excipient certification:China's NMPA tightened purity thresholds for chitosan-derived ingredients, creating upgrade demand from domestic refiners seeking pharmaceutical-grade status.
Market Restraints
- Shrimp shell supply concentration:Coastal East Asian aquaculture zones dominate feedstock sourcing, exposing processors to climate-driven harvest volatility and seasonal price swings.
- Dual-track compliance burden:Exporters must maintain parallel quality-management systems for Japan's PMDA and South Korea's MFDS pharmacopeial standards, elevating fixed certification costs.
- Plant-based polymer substitution:Algal-derived oligosaccharides and fermentation-produced chitosan alternatives are capturing niche applications in vegan-certified product lines.
Strategic Opportunities
- Beverage fortification programs:Liquid concentrate formats are penetrating functional drink supply chains where rapid dissolution properties command formulation preference over powder grades.
- Endotoxin-controlled production:Pharmaceutical-grade segments offer margin expansion through certification premiums for injectable drug excipient applications.
- Biotech processing convergence:Integration of enzymatic hydrolysis with precision fermentation platforms enables custom degree-of-polymerization tuning for targeted bioactivity profiles.
Industry Challenges
- Enzyme engineering talent scarcity:Specialized biochemists capable of optimizing chitosanase specificity and reactor yield remain concentrated in university research programs rather than commercial operations.
- Capex intensity for bioreactor scale-up:Stainless steel fermentation vessels with automated process control systems require substantial upfront investment, disadvantaging smaller chemical hydrolysis incumbents.
- Novel-food approval timelines:European EFSA novel-food dossier preparation extends 18-24 months, delaying market entry for innovative molecular weight fractions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan Oligosaccharides Market |
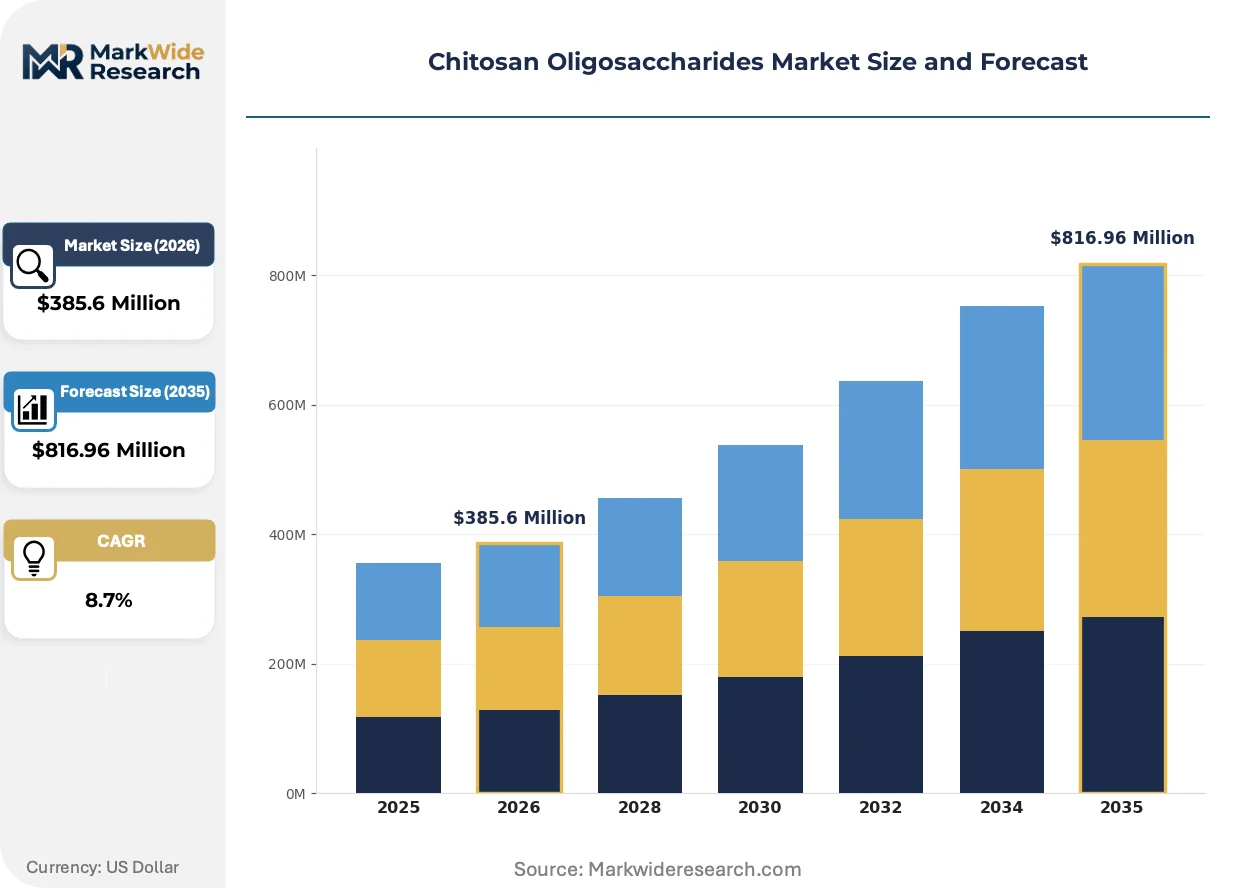
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Capsule Application: Nutraceuticals, Pharmaceuticals, Food Additives, Cosmetics End User: Food Industry, Healthcare Providers, Cosmetic Manufacturers, Research Institutions Distribution Channel: Online Stores, Health Stores, Supermarkets, Specialty Retailers |
| Companies Covered | Kunpoong Bio Co., Ltd., Golden-Shell Pharmaceutical Co., Ltd., Yaizu Suisankagaku Co., Ltd., Qingdao BZ Oligo Biotech Co., Ltd., Zhejiang New Fuda Ocean Biotech Co., Ltd., Weifang Sea Source Biological Products Co., Ltd., Qingdao Honghai Bio-tech Co., Ltd., Haidebei Marine Bioengineering Co., Ltd., Jiangsu Aoxin Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan Oligosaccharides Market Strategic Shifts
Production technology divergence and regulatory fragmentation are simultaneously compressing commodity margins and opening premium tiers, forcing strategic repositioning across the value chain.
Continuous-flow enzymatic reactors with immobilized chitosanase enzymes are fragmenting batch-process economics. Pharmaceutical excipient manufacturers in Japan are adopting these systems to reduce endotoxin variability and shorten validation cycles. The technology is fragmenting competitive positioning between capital-intensive biotech operators and legacy chemical processors unable to fund reactor conversions.
China's NMPA alignment with ICH Q3D elemental impurity guidelines is tightening heavy-metal thresholds for pharmaceutical-grade chitosan oligosaccharides. Domestic refiners are retrofitting purification trains with chelation and ion-exchange polishing steps to maintain excipient registration status. The policy shift most affects export-oriented Chinese suppliers serving MFDS-registered drug manufacturers in South Korea.
Formulator purchasing is consolidating around certified suppliers with dual PMDA-MFDS compliance documentation. Japanese functional food brands are bypassing trading houses to contract directly with enzymatic hydrolysis operators, compressing distributor margins. This pattern is most visible in Tokyo-Osaka nutraceutical manufacturing corridors where just-in-time ingredient delivery requirements favor integrated bioprocessors over merchant chemical traders.
Chitosan Oligosaccharides Market Segmentation
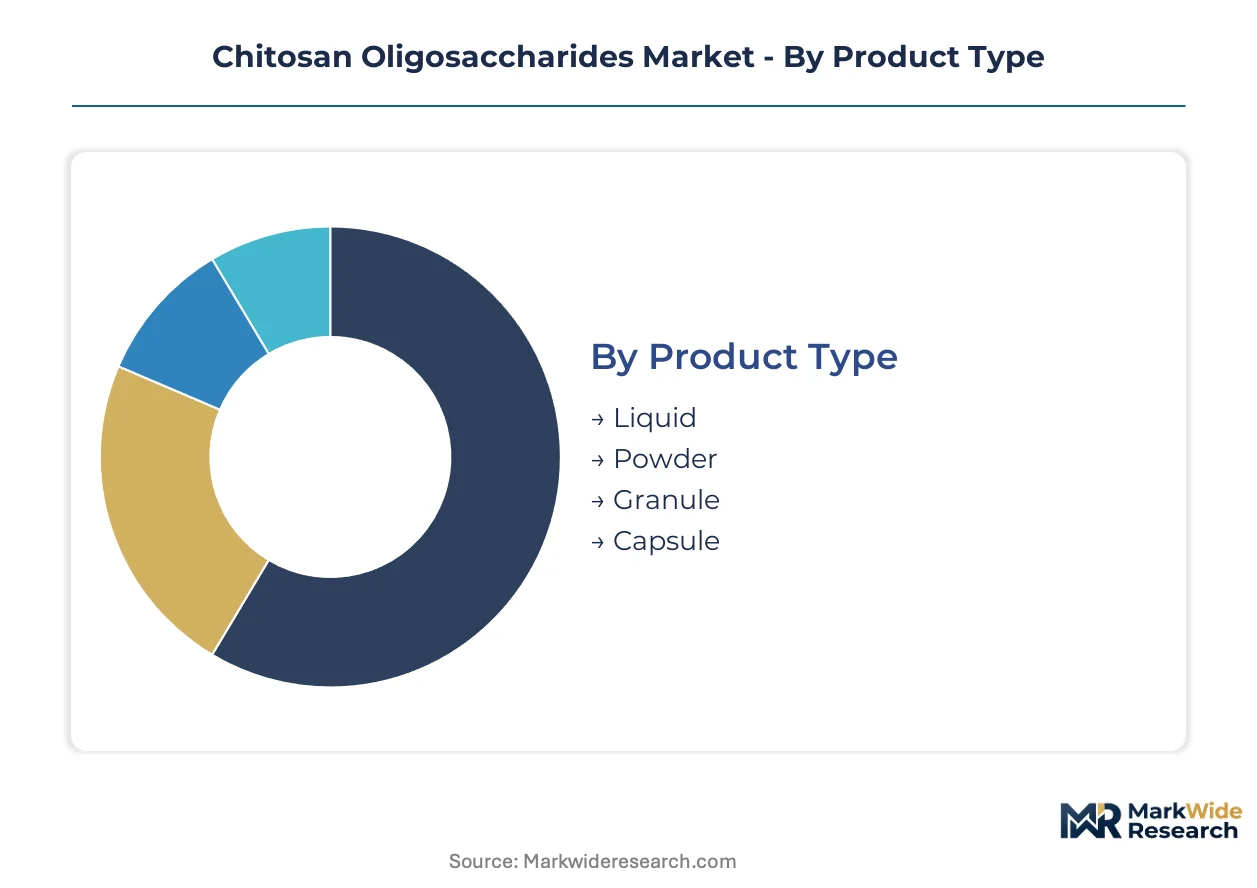
Segmentation in chitosan oligosaccharides reflects divergent purity requirements and formulation constraints across end-use verticals. Pharmaceutical and nutraceutical buyers impose distinct molecular weight specifications, while cosmetic and food additive purchasers prioritize solubility and sensory properties.
Product Type:
Substitution pressure from algal-derived alternatives and fermentation-produced chitosan variants weighs most heavily on commoditized powder grades, while enzymatically refined liquid concentrates maintain formulation lock-in through dissolution performance advantages.
- Powder:Dominates bulk ingredient transactions through superior stability during extended logistics cycles and lower moisture sensitivity. Demand concentrates in East Asian nutraceutical manufacturing corridors where functional food brands prioritize shelf-life extension over dissolution speed.
- Liquid:Water-soluble concentrates enable rapid incorporation into beverage fortification programs without reconstitution steps. Japanese functional drink formulators in Tokyo-Osaka manufacturing zones are accelerating procurement of low-molecular-weight liquid grades for gut-health positioning.
- Granule:Intermediate format offering controlled release properties for tablet compression and capsule filling operations. South Korean pharmaceutical excipient manufacturers favor granule grades for endotoxin-controlled production pipelines.
- Capsule:Pre-dosed delivery format capturing direct-to-consumer nutraceutical channels. Chinese domestic brands leverage capsule formats for immune-modulation claims in tier-one urban markets.
Powder anchors the volume base while liquid gains share at the steepest rate.
Application:
Margin stratification across application tiers separates certification-intensive pharmaceutical segments from volume-driven food additive categories, with nutraceuticals occupying the intermediate tier where bioactive claims command formulation premiums.
- Nutraceuticals:Functional food and dietary supplement applications lead volume absorption through immune-modulation and prebiotic positioning. Japanese and South Korean brands are expanding procurement of low-molecular-weight grades as gut-health claims penetrate mainstream retail channels.
- Pharmaceuticals:Injectable drug excipients and controlled-release formulations require endotoxin-controlled production with pharmacopeial certification. China's NMPA tightened purity thresholds, pushing domestic refiners toward enzymatic hydrolysis upgrades to maintain registration status.
- Food Additives:Preservative and film-forming applications in processed seafood and edible coatings. Coastal East Asian manufacturing clusters leverage proximity to shrimp-shell supply chains for cost-competitive feedstock access.
- Cosmetics:Moisture-retention and antimicrobial properties in skincare formulations. Premium tier brands in Japan specify ultra-low molecular weight fractions for functional positioning in high-end product lines.
Food additives absorb the highest shipment volumes while pharmaceuticals capture the widest margin spreads.
End User:
Customer sophistication tiers separate research institutions with custom specification requirements from commodity-scale food processors, with healthcare providers and cosmetic manufacturers occupying intermediate positions on technical capability and volume scale.
- Food Industry:Processed food manufacturers and beverage brands incorporating chitosan oligosaccharides for shelf-life extension and texture modification. East Asian coastal processors dominate procurement through integrated crustacean sourcing advantages.
- Healthcare Providers:Hospital systems and clinical nutrition suppliers specifying pharmaceutical-grade materials for enteral and parenteral applications. Japan's PMDA and South Korea's MFDS pharmacopeial standards compel parallel quality-management systems.
- Cosmetic Manufacturers:Skincare and personal care brands leveraging antimicrobial and film-forming properties. Tokyo-Osaka manufacturing corridors concentrate demand for premium-grade ultra-low molecular weight fractions.
- Research Institutions:Universities and biotech laboratories requiring custom degree-of-polymerization tuning for bioactivity studies. Specialized biochemist talent scarcity constrains commercial translation of research-grade specifications.
Food industry procurement anchors volume demand while research institutions command the highest per-kilogram pricing.
Distribution Channel:
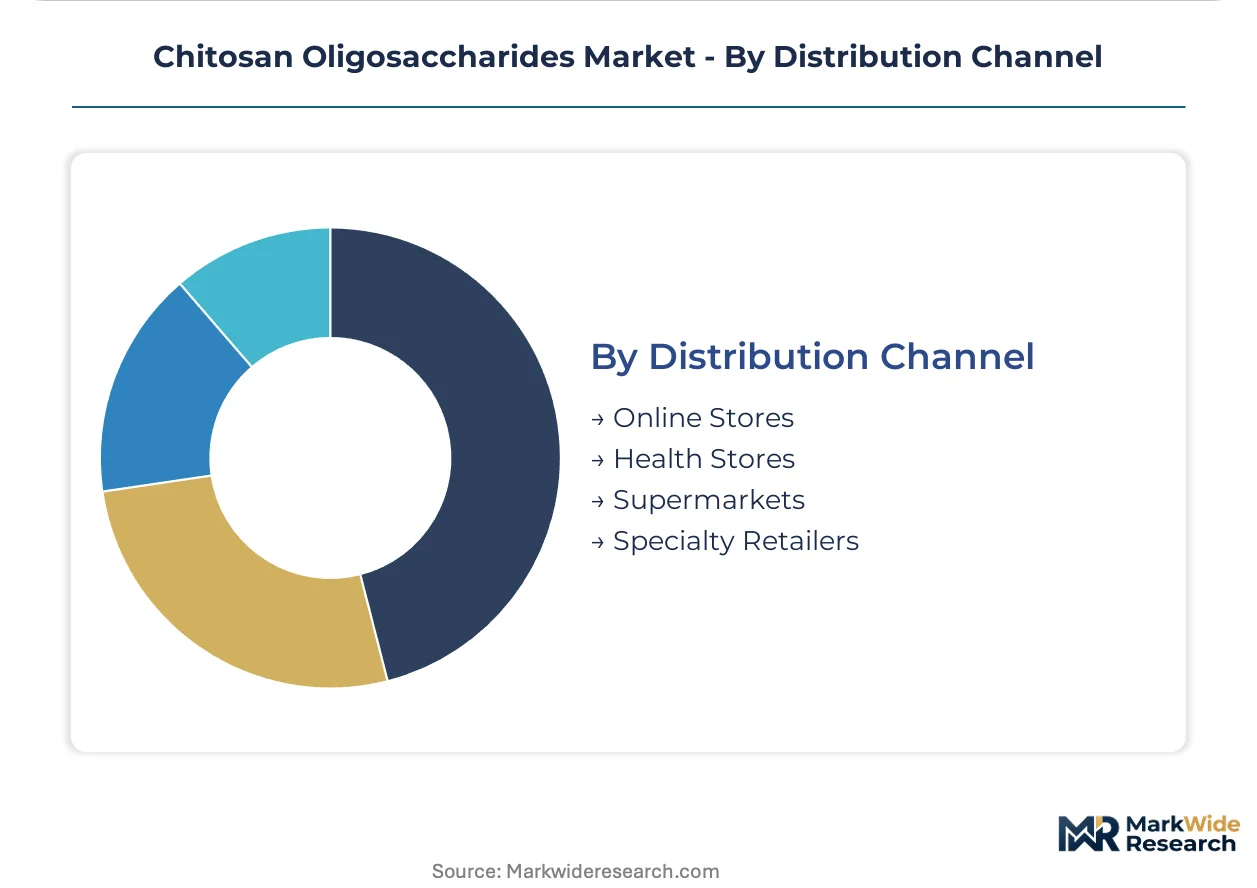
Channel fragmentation reflects the bifurcation between just-in-time manufacturing supply chains and direct-to-consumer wellness retail, with specialty intermediaries losing ground to integrated bioprocessor direct contracts.
- Online Stores:E-commerce platforms capturing direct-to-consumer nutraceutical and cosmetic sales. Chinese domestic brands leverage Tmall and JD.com for immune-modulation product distribution in tier-one cities.
- Health Stores:Specialized retail channels for premium dietary supplements and functional foods. Japanese consumers in urban centers drive demand for gut-health positioned low-molecular-weight formulations.
- Supermarkets:Mass-market retail penetration for food additive and basic nutraceutical applications. South Korean retail consolidation favors suppliers with MFDS-registered production documentation.
- Specialty Retailers:Professional-grade supply houses serving cosmetic manufacturers and research institutions. Distributor margins compress as Japanese formulators bypass trading houses for direct enzymatic hydrolysis operator contracts.
Supermarkets move the highest unit volumes while specialty retailers sustain the steepest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit the highest price elasticity as domestic refiners compete on volume, while Japanese pharmaceutical formulators absorb steep premiums for endotoxin-controlled grades. South Korean nutraceutical brands occupy the intermediate tier, trading cost against bioactive specificity.
China
Domestic refiners in Shandong and Zhejiang provinces are retrofitting acid-catalyzed plants with enzymatic bioreactors to meet NMPA's tightened purity thresholds for pharmaceutical excipients. The national regulator's alignment with ICH Q3D elemental impurity guidelines is forcing ion-exchange polishing upgrades. Qingdao and Weifang coastal clusters concentrate shrimp-shell processing capacity alongside biotech fermentation infrastructure.
Japan
PMDA pharmacopeial standards for chitosan-derived injectable excipients command certification premiums from Tokyo-Osaka pharmaceutical manufacturers. Functional food brands in the Kanto corridor are bypassing trading houses to contract directly with enzymatic hydrolysis operators for just-in-time delivery. Yaizu-based processors specialize in ultra-low molecular weight fractions for premium nutraceutical positioning.
South Korea
MFDS-registered drug manufacturers are consolidating procurement around suppliers with dual PMDA-MFDS compliance documentation to streamline cross-border supply chains. Kunpoong Bio leverages integrated crustacean sourcing from domestic aquaculture zones to secure feedstock consistency. Busan-Ulsan coastal manufacturing clusters overlap shrimp-shell supply chains with biotech processing capabilities.
United States
FDA oversight of dietary supplement GMPs filters market access for Asian producers lacking toxicological dossiers, though nutraceutical absorption lags East Asian penetration rates. REACH registration completion by select exporters is unlocking premium pricing tiers previously blocked by regulatory barriers. West Coast functional beverage formulators are testing liquid concentrate formats for rapid dissolution applications.
Germany
EFSA novel-food dossier requirements extend 18-24 months for innovative molecular weight fractions, delaying market entry for enzymatically refined grades. ECHA REACH enforcement maintains strict toxicological standards for chitosan-derived ingredients in cosmetic and food additive applications. Bavarian and North Rhine-Westphalian biotech clusters are piloting precision fermentation platforms for custom degree-of-polymerization tuning.
Chitosan Oligosaccharides Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with coastal East Asian producers commanding supply chain proximity advantages. The structure fragments between enzymatic bioreactor operators with in-house fermentation capacity and legacy chemical hydrolysis incumbents facing capex barriers to conversion. Three archetypes dominate: crustacean-integrated bioprocessors, pharmaceutical-grade certification specialists, and research-grade custom fractionators. Competitive moves concentrate on enzymatic technology licensing and backward integration into aquaculture feedstock control.
Among China-based fabricators, Qingdao BZ Oligo Biotech Co., Ltd. and Zhejiang New Fuda Ocean Biotech Co., Ltd. exemplify the scale-driven coastal processor archetype with Shandong and Zhejiang provincial anchoring. Kunpoong Bio Co., Ltd. represents the integrated Korean model with captive supply chain advantages. Golden-Shell Pharmaceutical Co., Ltd. occupies a certification-focused position serving domestic drug manufacturers with excipient-grade documentation pipelines.
| Leading Market Players |
|---|
| Kunpoong Bio Co., Ltd. |
| Golden-Shell Pharmaceutical Co., Ltd. |
| Yaizu Suisankagaku Co., Ltd. |
| Qingdao BZ Oligo Biotech Co., Ltd. |
| Zhejiang New Fuda Ocean Biotech Co., Ltd. |
| Weifang Sea Source Biological Products Co., Ltd. |
| Qingdao Honghai Bio-tech Co., Ltd. |
| Haidebei Marine Bioengineering Co., Ltd. |
| Jiangsu Aoxin Biotechnology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between enzymatic bioreactor operators and Japanese nutraceutical formulators lock in both crustacean feedstock access and pharmaceutical-grade price visibility against seasonal shrimp-shell volatility. These arrangements concentrate procurement power among coastal East Asian processors with integrated aquaculture ties while exposing spot-market buyers to harvest-driven price swings.
Pricing Analysis
After-sales certification documentation and technical service bundling drive lifetime value for pharmaceutical-grade suppliers serving MFDS-registered drug manufacturers. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-additive grades separates endotoxin-controlled excipients from standard powder formulations. Cost compression in commodity powder grades is intensifying because algal-derived substitutes are capturing vegan-certified applications. Food processors in Shandong province exhibit the highest price elasticity, while Tokyo-Osaka injectable drug formulators absorb steep premiums for dual PMDA-MFDS compliance.
Supply Chain Analysis
Strait of Malacca transit routes underpin logistics connectivity for crustacean feedstock moving from Southeast Asian aquaculture zones to Shandong and Zhejiang processing clusters. Supply concentration rests on China, South Korea, and Vietnam for shrimp-shell raw material, with enzymatic bioreactor equipment and chitosanase enzyme inputs drawing from Japanese and German specialty chemical suppliers. Single-source vulnerability around coastal East Asian harvest zones exposes processors to climate-driven supply interruptions. Distribution runs through direct contracts between enzymatic operators and Japanese functional food brands, bypassing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where dual PMDA-MFDS certification creates switching costs that lock pharmaceutical formulators into qualified supplier relationships. Network effects concentrate among integrated bioprocessors with backward control over crustacean sourcing and enzymatic refining capacity.
For Market Incumbents: Consolidate enzymatic bioreactor capacity in Busan-Ulsan and Qingdao coastal clusters to defend against fermentation-produced chitosan alternatives. Deepen captive supply relationships with South Korean and Chinese aquaculture operators while accelerating endotoxin-controlled production documentation for injectable excipient tier expansion. For New Entrants and Emerging Players: Custom degree-of-polymerization tuning for research institutions represents an underserved service layer where incumbent chemical hydrolysis plants lack technical biochemist staffing. Target North American functional beverage formulators with liquid concentrate rapid-dissolution formats, leveraging REACH registration gaps among established Asian suppliers as entry pathway. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors enzymatic bioreactor operators with in-house fermentation platforms over legacy acid-catalyzed incumbents. Long-term viability hinges on regulatory alignment across ICH Q3D, PMDA, and MFDS pharmacopeial clusters. Acquisition focus should center on coastal Chinese processors completing NMPA-mandated purification upgrades. Monitor EFSA novel-food approval timelines as inflection signal for European market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioreactor Scale-Up | Continuous-flow reactors with immobilized chitosanase reduce endotoxin variability for PMDA-registered drug manufacturers. |
| Backward Integration into Aquaculture | Kunpoong Bio's captive crustacean sourcing from South Korean coastal zones secures feedstock consistency against harvest volatility. |
| Dual Pharmacopeial Certification | Parallel PMDA-MFDS compliance documentation unlocks premium pricing tiers in Tokyo-Osaka and Busan-Ulsan pharmaceutical corridors. |
| Liquid Concentrate Format Development | Rapid-dissolution properties capture formulation preference from Japanese functional beverage brands in Kanto manufacturing zones. |
| REACH Registration Completion | Toxicological dossiers for European market access enable premium pricing previously blocked by ECHA regulatory barriers. |
Study Parameters
Desk research of NMPA pharmaceutical excipient registrations, MFDS drug master files, and East Asian customs trade data preceded structured interviews with enzymatic bioreactor plant managers, nutraceutical procurement leads at Japanese functional food brands, pharmaceutical excipient quality directors, and crustacean aquaculture supply coordinators. Secondary validation drew from PMDA pharmacopeial standards documentation, ICH Q3D elemental impurity guidelines, and EFSA novel-food dossier records. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and end-user segmentation dimensions.
Variance decomposition across enzymatic versus chemical hydrolysis production pathways, pharmaceutical-grade versus food-additive purity tiers, and coastal East Asian versus European regulatory clusters shaped analytical framework construction over the projection horizon. Modeled segmentation spanned product format, application vertical, molecular weight fraction, and regional certification status. CAGRs derived from production capacity build-out trajectories, feedstock harvest cycle patterns, and formulator procurement intensity indices.
Underlying assumptions cover NMPA enforcement continuity for ICH Q3D alignment, enzymatic bioreactor yield optimization curves, and crustacean aquaculture harvest stability, with deviation risk concentrated in EFSA novel-food approval timeline extensions and fermentation-produced chitosan substitution acceleration. Practitioners should keep alternative scenarios live as regulatory divergence in purity metrics and biopolymer safety frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Crocodile Peptide Market
Biomaterials
South America Collagen Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Bone Substitutes Market
Biomaterials
Bone Distractors Market
Biomaterials
US Heparin Market
Biomaterials
Self-Healing Materials Market