
 Global Extracellular Matrix Patches Market | 2026-2036
Global Extracellular Matrix Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extracellular Matrix Patches Market Foresight
Modular kit configurations is decoupling single-patch procurement from bundled surgical sets, forcing buyers to evaluate unit economics more granularly. Baxter leverages its hospital supply chain control to sustain contracted volume commitments across cardiovascular centers. Medtronic anchors its position through R&D intensity in bioresorbable scaffold designs. Aziyo Biologics specializes in hospital-specific consignment models that reduce implant waste.
Extracellular matrix patches comprise decellularized tissue scaffolds—typically collagen, elastin, and glycosaminoglycans preserved from xenogeneic or allogeneic sources—engineered to support host cell infiltration and guided tissue regeneration in surgical applications. Porcine-derived patches dominate current supply due to established collagen architecture compatibility with human wound healing, though amniotic segments are gaining fastest growth from reduced immunogenicity profiles in outpatient settings. Wound healing applications retain mature margin pools from chronic diabetic foot ulcer protocols, while cardiovascular repair segments attract premium positioning from structural heart procedure expansion.
FDA 21 CFR Part 1271 human cell and tissue regulations shape donor screening and processing standards for allogeneic patches entering US distribution. EMA's Medical Device Regulation and ISO 13485 quality management frameworks govern CE-marked patch conformity across European hospital procurement channels. Japan's PMDA enforces xenogeneic material safety testing that limits equine-source patch introductions. Stakeholders must monitor evolving biologic-device combination classification decisions that will determine regulatory pathway costs and market access timelines.
Market Dynamics
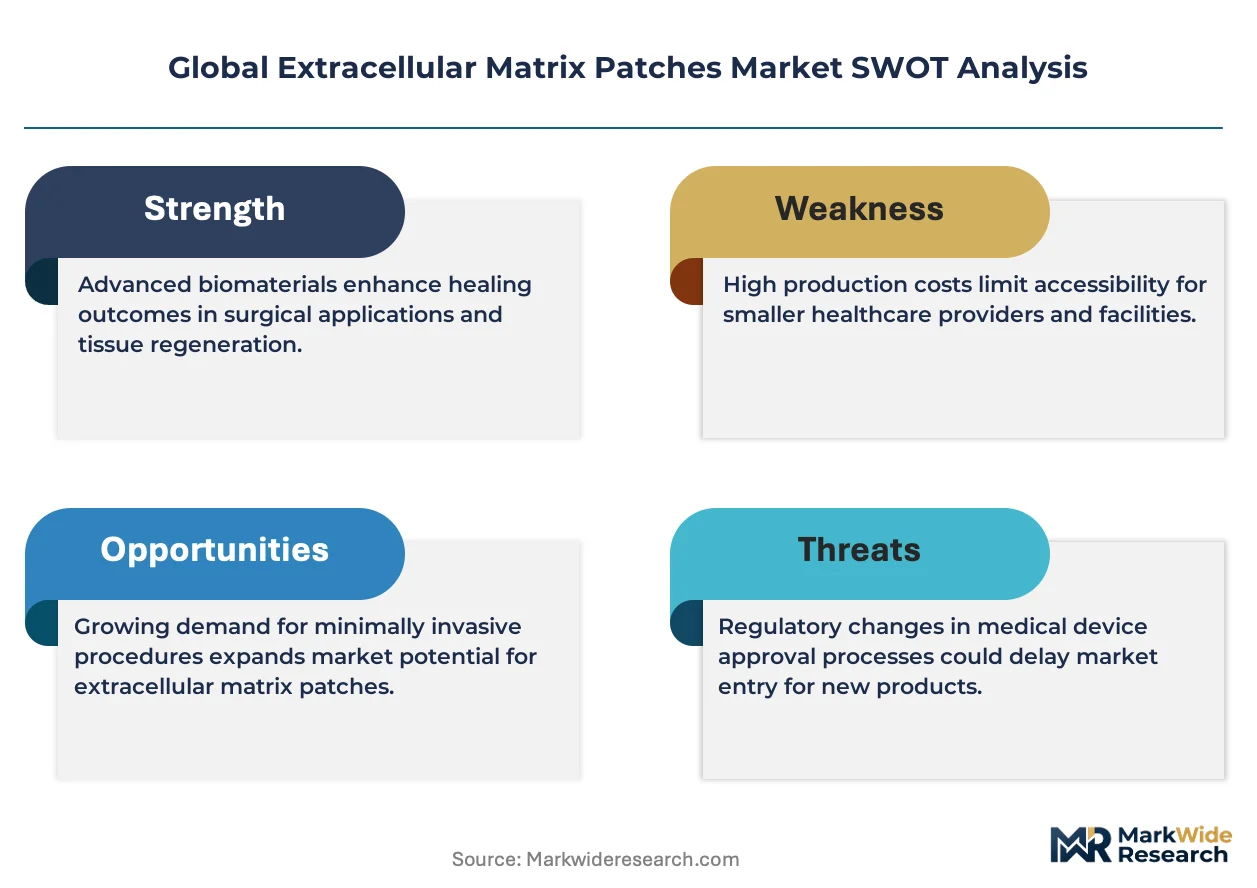
Modular kit configurations are decoupling single-patch procurement from bundled surgical sets, forcing hospital buyers to evaluate unit economics more granularly and reshaping contract negotiations across cardiovascular centers.
Growth Catalysts
- FDA 21 CFR Part 1271:Human cell and tissue regulations establish clear donor screening standards, accelerating allogeneic patch commercialization pathways for US hospital systems.
- Structural heart procedure expansion:Cardiovascular repair applications attract premium positioning as transcatheter valve replacements multiply procedural volumes in tertiary care centers.
- Amniotic tissue processing:Reduced immunogenicity profiles in outpatient wound healing settings are displacing synthetic alternatives in diabetic foot ulcer protocols.
Market Restraints
- Porcine collagen sourcing concentration:FDA clearance pathway tightening for xenogeneic biologics creates material scarcity risk in domestic supply chains dependent on US agricultural processing.
- Bioresorbable scaffold R&D intensity:Capital requirements for next-generation scaffold designs compress margin recovery timelines for mid-scale manufacturers.
- Equine-source patch exclusion:Japan's PMDA xenogeneic safety testing protocols block alternative collagen architectures from Asia-Pacific distribution.
Strategic Opportunities
- Hospital-specific consignment models:Inventory risk transfer arrangements reduce implant waste in high-volume cardiovascular centers while locking in exclusive supply relationships.
- Biologic-device combination classification:Evolving FDA determinations on product jurisdiction create first-mover advantages for sponsors mastering dual regulatory pathways.
- Chronic wound outpatient migration:Amniotic patch segments capture ambulatory surgical center volume as diabetic foot ulcer care decentralizes from inpatient settings.
Industry Challenges
- Decellularization technician scarcity:Specialized tissue processing expertise concentrates in legacy academic medical center labs, constraining manufacturing scale-up.
- ISO 13485 quality system implementation:Small patch processors face compliance timeline compression as European hospital procurement channels harden certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extracellular Matrix Patches Market |
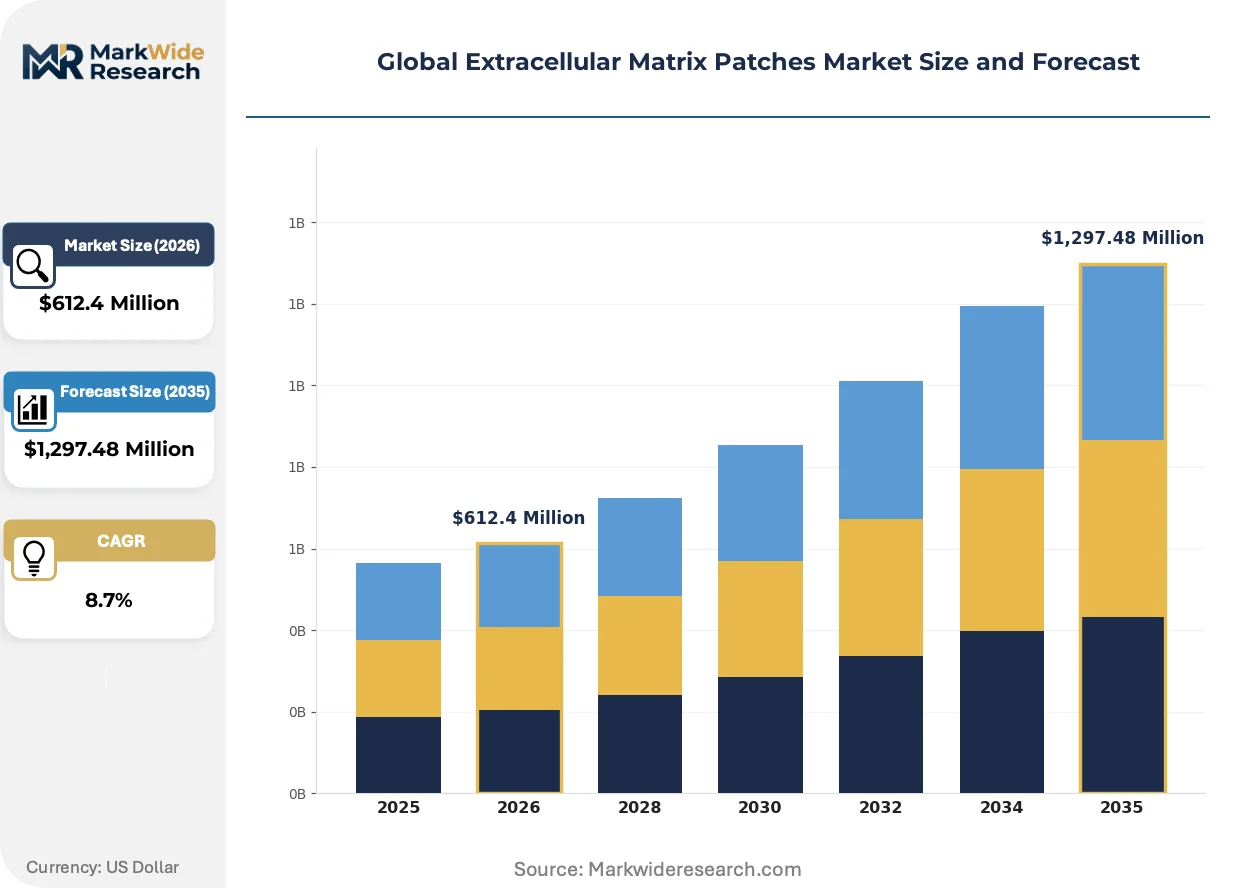
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcine, Bovine, Amniotic, Synthetic, Equine Application: Wound Healing, Cardiovascular Repair, Orthopedic Reconstruction, General Surgery, Cosmetic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Deployment: Inpatient, Outpatient, Emergency Care, Home Healthcare |
| Companies Covered | Medtronic, Baxter, Smith & Nephew, Cook Group, Coloplast Group, Aziyo Biologics, MTF Biologics, Boston Scientific Corporation, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extracellular Matrix Patches Market Shifts & Advancements
Active innovation across scaffold engineering, regulatory science, and procurement mechanics is compressing product lifecycles and redrawing competitive boundaries in tissue-derived repair materials.
Decellularized tissue scaffold technology is modularizing into component-based architectures that separate structural matrices from bioactive coatings. Cardiovascular device manufacturers are adopting these configurable platforms to accelerate iteration cycles for patient-specific anatomies. This modularization is compressing traditional integrated patch development timelines and enabling faster regulatory submission strategies.
EMA's Medical Device Regulation is recasting conformity assessment requirements for CE-marked patches entering European hospital procurement channels. Manufacturers must now maintain technical documentation across notified body jurisdictions with divergent interpretation practices. Cardiovascular applications face the steepest compliance burden as clinical evidence thresholds escalate for permanent implant classifications.
Consignment inventory arrangements are displacing traditional purchase-order procurement in high-volume cardiovascular centers. Hospital supply chains now demand vendor-managed stock with usage-based billing, transferring carrying cost risk to patch suppliers. This shift concentrates most visibly in United States integrated delivery networks where implant spend scrutiny has intensified under value-based care contracts.
Global Extracellular Matrix Patches Market Segmentation
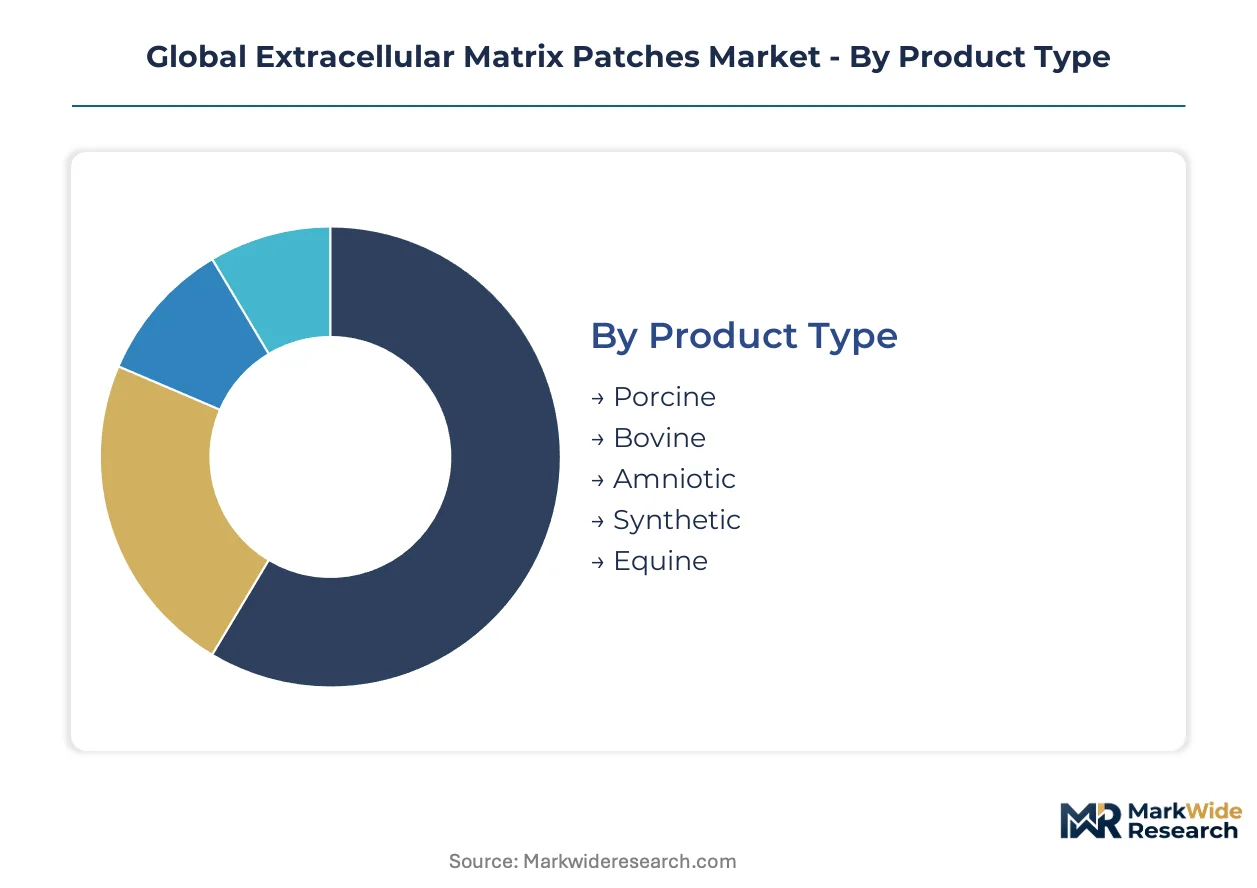
Extracellular matrix patch procurement varies sharply across tissue sources, clinical settings, and care delivery models. Supply chain configuration and regulatory pathway complexity create divergent margin structures within each segment category.
Product Type:
Porcine collagen sourcing concentrates in Midwest US agricultural processing corridors, creating geographic dependencies that shape manufacturer site selection and FDA inspection scheduling.
- Porcine:Decellularized porcine small intestinal submucosa and dermal matrices retain established collagen fiber orientation compatible with human wound healing biology. Demand concentrates in US cardiovascular centers where Baxter and Medtronic maintain contracted supply relationships; FDA tightening of xenogeneic clearance pathways threatens material availability.
- Amniotic:Dehydrated human amnion and chorion membranes processed from scheduled cesarean deliveries carry reduced immunogenicity profiles. Outpatient wound healing clinics in Germany and Japan drive procurement volume; reimbursement coding clarity accelerates ambulatory adoption.
- Bovine:Dermal collagen matrices from controlled cattle herds serve orthopedic reconstruction applications.
- Synthetic:Polymer-based scaffolds engineered from polylactic acid and polycaprolactone bypass xenogeneic regulatory hurdles.
- Equine:Horse-derived pericardium and tendon collagen remains excluded from Japanese distribution.
Porcine absorbs the bulk of installed capacity; amniotic is expanding most quickly.
Application:
Procedure reimbursement rates and clinical evidence thresholds stratify addressable market opportunity across surgical specialties.
- Cardiovascular Repair:Structural heart procedures including transcatheter valve replacements and congenital defect repairs command premium positioning. Tertiary care centers in the United States and Germany generate concentrated demand; bioresorbable scaffold R&D intensity elevates competitive barriers.
- Wound Healing:Chronic diabetic foot ulcer protocols leverage amniotic patch reduced immunogenicity for outpatient deployment. Medicare Advantage penetration in Florida and Texas drives volume; healing outcome metrics determine formulary inclusion.
- Orthopedic Reconstruction:Rotator cuff and Achilles tendon reinforcement applications serve sports medicine practices.
- General Surgery:Hernia repair and soft tissue reconstruction utilize porcine dermal matrices.
- Cosmetic Surgery:Aesthetic applications including breast reconstruction and facial contouring pursue elective reimbursement pathways.
Wound healing captures the steepest expansion trajectory; cardiovascular repair retains the highest average selling prices.
End User:
Procurement authority and inventory carrying capacity determine contract structure and pricing flexibility.
- Hospitals:Integrated delivery networks in the United States leverage implant spend consolidation to extract consignment arrangements and usage-based billing terms. Value-based care contracts intensify scrutiny across cardiovascular service lines.
- Ambulatory Surgical Centers:Freestanding outpatient facilities in Germany and Japan favor amniotic patch formats with simplified storage requirements.
- Specialty Clinics:Wound care centers and sports medicine practices drive diabetic foot ulcer volume.
- Research Institutions:Academic medical centers concentrate decellularization technician expertise.
Hospitals command the dominant procurement volume; ambulatory surgical centers are climbing the fastest.
Deployment:
Site-of-care migration and reimbursement site neutrality reshape patch utilization patterns.
- Inpatient:Tertiary cardiovascular centers perform complex structural heart procedures requiring multi-day admission monitoring. DRG-based reimbursement in the United States and Germany sustains procedure economics.
- Outpatient:Ambulatory surgical centers and wound clinics in Japan and the United States execute amniotic patch deployment under local anesthesia.
- Emergency Care:Trauma and burn centers utilize porcine matrices for immediate soft tissue coverage.
- Home Healthcare:Skilled nursing facilities manage chronic wound dressing changes.
Inpatient retains the majority of cardiovascular procedure volume; outpatient is gaining share fastest in wound healing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US agricultural processing corridors concentrate porcine collagen supply, while cardiovascular demand clusters in German tertiary centers and Japanese wound clinics. Production geography and consumption patterns diverge sharply across the three dominant markets.
United States
Integrated delivery networks in Texas and Florida drive amniotic patch procurement for outpatient diabetic foot protocols. FDA 21 CFR Part 1271 governs allogeneic donor screening standards, accelerating commercialization timelines for processed human tissue. Minneapolis-St. Paul anchors cardiovascular device manufacturing clusters where bioresorbable scaffold R&D concentrates.
Germany
Tertiary cardiovascular centers in Bavaria and North Rhine-Westphalia generate concentrated demand for structural heart repair materials. EMA Medical Device Regulation recasts CE-marking conformity assessments, escalating clinical evidence thresholds for permanent implant classifications. The Munich medical technology corridor hosts notified body operations that shape patch certification pathways.
Japan
Ambulatory surgical centers in Tokyo and Osaka favor amniotic formats with simplified cold-chain requirements. PMDA xenogeneic safety testing protocols block equine-source collagen from distribution, preserving market share for porcine and allogeneic alternatives. The Kansai region concentrates wound healing clinic networks capturing decentralized diabetic care volume.
United Kingdom
London and Southeast England academic medical centers retain decellularization technician expertise that constrains broader manufacturing scale-up. MHRA post-Brexit regulatory divergence from EMA frameworks creates parallel compliance burdens for patch sponsors. The Cambridge biotech cluster advances scaffold engineering research with limited commercial manufacturing footprint.
India
Specialty cardiac centers in Maharashtra and Karnataka import porcine matrices for congenital defect repairs amid limited domestic tissue processing infrastructure. CDSCO biologic-device combination classification uncertainty delays market entry for novel scaffold formats. Hyderabad's pharmaceutical manufacturing base explores contract tissue processing partnerships with US sponsors.
Global Extracellular Matrix Patches Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels, creating tiered competitive dynamics. Hospital supply chain control concentrates among three diversified medical technology groups, while mid-scale biologics processors defend niche positions through tissue sourcing relationships. Two strategic archetypes dominate: integrated device conglomerates leveraging procurement scale, and specialized tissue processors with decellularization expertise. Competitive moves center on consignment inventory arrangements and regulatory pathway mastery for biologic-device combinations.
Within the diversified conglomerate tier, Medtronic and Baxter exemplify scale-driven positioning through hospital supply chain integration. Aziyo Biologics occupies a specialist position representing the focused tissue processor archetype. These three anchors illustrate the competitive spectrum from procurement-controlled volume plays to sourcing-dependent niche strategies.
| Leading Market Players |
|---|
| Medtronic |
| Baxter |
| Smith & Nephew |
| Cook Group |
| Coloplast Group |
| Aziyo Biologics |
| MTF Biologics |
| Boston Scientific Corporation |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States concentrate procurement authority for extracellular matrix patches, forcing suppliers toward consignment-based pricing models that transfer inventory carrying costs from hospital buyers to manufacturers.
Pricing Analysis
Margin tightening in cardiovascular repair segments reflects bioresorbable scaffold R&D intensity that compresses recovery timelines for mid-scale manufacturers. Contract-based long-term offtake agreements dominate hospital system procurement, with price differentiation resting on FDA clearance tier and consignment arrangement depth. Cost-down pressure on amniotic patch formats accelerates because Medicare Advantage penetration intensifies formulary scrutiny. Ambulatory surgical centers exhibit highest price sensitivity from reimbursement site neutrality rules, while tertiary cardiovascular centers accept premium positioning for structural heart applications.
Supply Chain Analysis
Regional distribution centers in Midwest US agricultural corridors anchor porcine collagen sourcing, with hub-and-spoke patterns radiating toward Minneapolis-St. Paul manufacturing clusters. Supply draws from United States, Germany, and Japan for decellularized tissue scaffolds, with raw material dependencies centering on porcine small intestinal submucosa, human amniotic membrane, and bioresorbable polymer feedstocks. Single-source vulnerability concentrates in legacy academic medical center labs where decellularization technician expertise constrains manufacturing scale-up. Distribution runs through hospital system consignment arrangements and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 1271 compliance costs erect a barrier-to-entry moat that favors incumbent tissue processors with established donor screening infrastructure and quality management systems.
For Market Incumbents: To counter bioresorbable scaffold R&D intensity from diversified device conglomerates, deepen decellularization technician pipelines through academic medical center partnerships and secure exclusive porcine sourcing agreements across Midwest agricultural processing corridors. Lock in hospital system volume through vendor-managed inventory with usage-based billing terms that transfer carrying cost risk. For New Entrants and Emerging Players: The premium-economy price gap in amniotic wound healing patches opens white-space entry for outpatient clinic networks in Japan and Germany seeking simplified cold-chain formats. Target ambulatory surgical center procurement channels with dehydrated membrane configurations that bypass complex hospital GPO negotiations. Pursue reimbursement coding clarity as the primary go-to-market lever. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized tissue processors with captive decellularization expertise in United States geographies. Long-term viability over the projection horizon rests on regulatory pathway mastery for biologic-device combinations rather than commodity patch manufacturing. Monitor FDA classification determinations on scaffold-device jurisdiction as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 1271 Compliance Investment | Donor screening infrastructure secures allogeneic patch commercialization pathways for US hospital systems. |
| Hospital System Consignment Partnership | Usage-based billing transfers inventory risk while locking exclusive supply relationships in cardiovascular centers. |
| Bioresorbable Scaffold R&D Program | Structural heart procedure expansion demands next-generation materials with controlled resorption profiles. |
| Amniotic Tissue Processing Scale-Up | Outpatient wound healing migration in Germany and Japan drives volume for dehydrated membrane formats. |
| Academic Medical Center Technician Pipeline | Decellularization expertise concentration constrains manufacturing expansion without targeted workforce development. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across hospital procurement managers, biomedical engineers, GPO contracts directors, and tissue processing technicians. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level outputs. FDA 510(k) databases, EMA CE marking registries, hospital procurement databases, and GPO contract repositories supplied secondary validation layers.
Reconciliation of supply-side capacity data with demand-side procedure volume estimates shaped the analytical framework across the analysis window. Segmentation dimensions modeled include tissue source, application specialty, end-user facility type, and deployment setting. CAGRs derived from fitted growth curves incorporating regulatory approval timelines, reimbursement policy shifts, and hospital capital expenditure cycles.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Chitosan Market
Biomaterials
Scaffold Materials Market
Biomaterials
Heparin Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Global Collagen and HA Based Biomaterial Market