
 Biomimetic Peptides Market | 2026-2036
Biomimetic Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Biomimetic Peptides Market Analytics
Peptide-as-a-service licensing models are decoupling molecular ownership from commercial rights, reshaping how biotech firms monetize discovery platforms. PeptiDream leverages its proprietary peptide discovery engine to sustain long-term partnership revenues with global pharmaceutical clients. Lonza Group anchors high-volume GMP peptide manufacturing capacity across Switzerland and North America, while Bachem Holding AG specializes in complex solid-phase synthesis for clinical-stage therapeutic candidates.
Biomimetic peptides are synthetic or recombinant amino acid sequences that replicate native protein fragments, typically synthesized via solid-phase peptide synthesis with purity thresholds exceeding 95% for pharmaceutical applications. These molecules modulate cellular signaling pathways, enabling targeted therapeutic intervention with lower immunogenic risk than full-length biologics. Therapeutic peptides command the largest value share due to oncology and metabolic disease pipelines, while cosmeceuticals represent the fastest-expanding application as consumers shift toward clinically validated topical actives. Solid-phase synthesis retains dominance in commercial production, though recombinant technology is gaining traction for longer sequences requiring post-translational modifications.
FDA peptide drug approval frameworks and EMA's evolving biosimilar guidance for synthetic peptides jointly determine regulatory pathways and market access timelines for developers. REACH compliance in Europe and EPA manufacturing discharge standards in the United States add compliance layers that favor scaled producers with dedicated environmental management systems. Stakeholders must monitor how FDA's emerging peptide-specific quality guidelines reshape manufacturing specifications and competitive moats for contract development organizations.
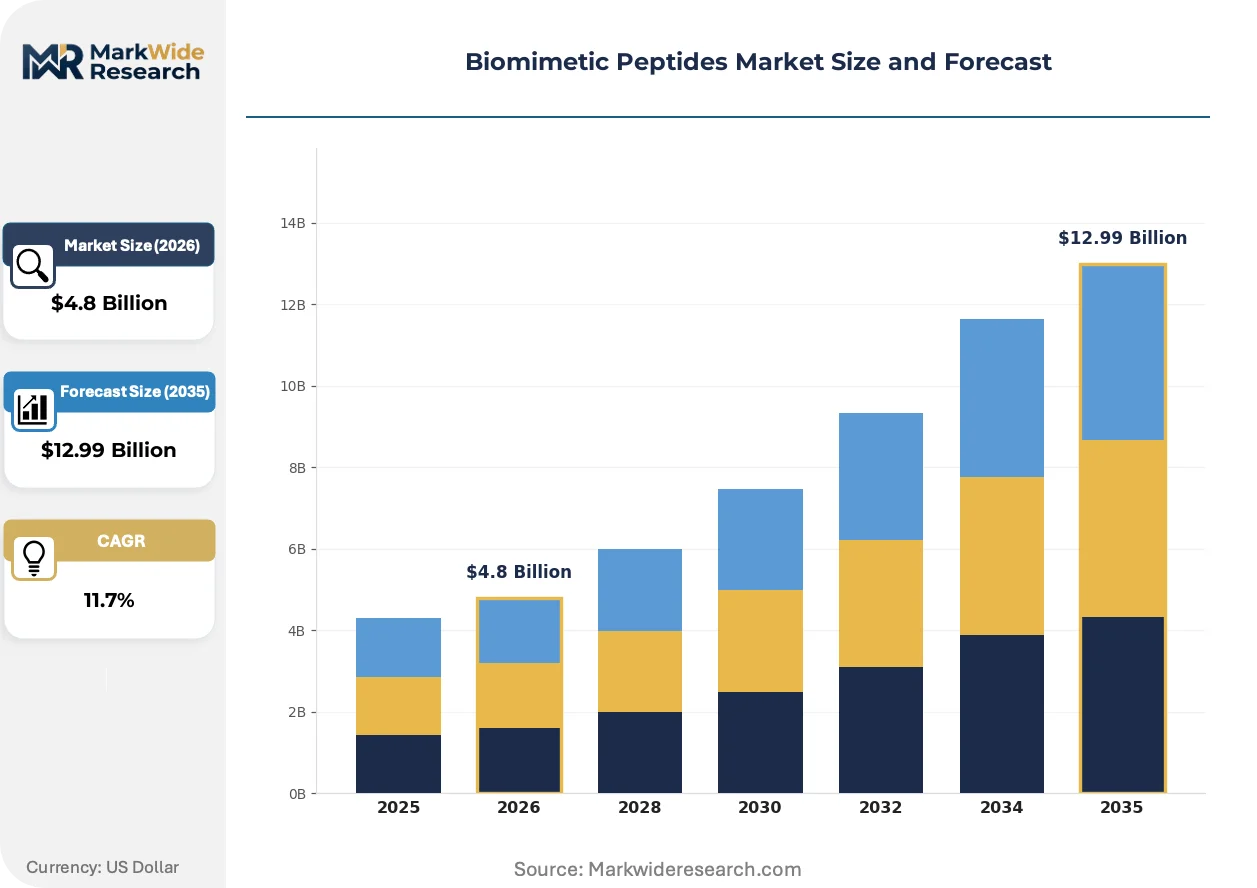
Market Dynamics
Solid-phase peptide synthesis capacity is concentrating among scaled contract manufacturers as cosmeceutical formulators and pharmaceutical developers outsource production to secure 95%+ purity thresholds without capital-intensive in-house facilities.
Growth Catalysts
- FDA Expanded Approval Pathways:The FDA's streamlined peptide drug frameworks compress clinical-to-commercial timelines, accelerating therapeutic pipeline monetization for developers.
- Retinoid Displacement in Topicals:Skin-bioactive peptides are capturing premium cosmeceutical shelf space as consumers reject irritation-prone retinoids for clinically validated alternatives.
- Peptide-as-a-Service Licensing:Discovery platform licensing decouples molecular IP from commercial rights, generating recurring revenue for biotech firms without manufacturing risk.
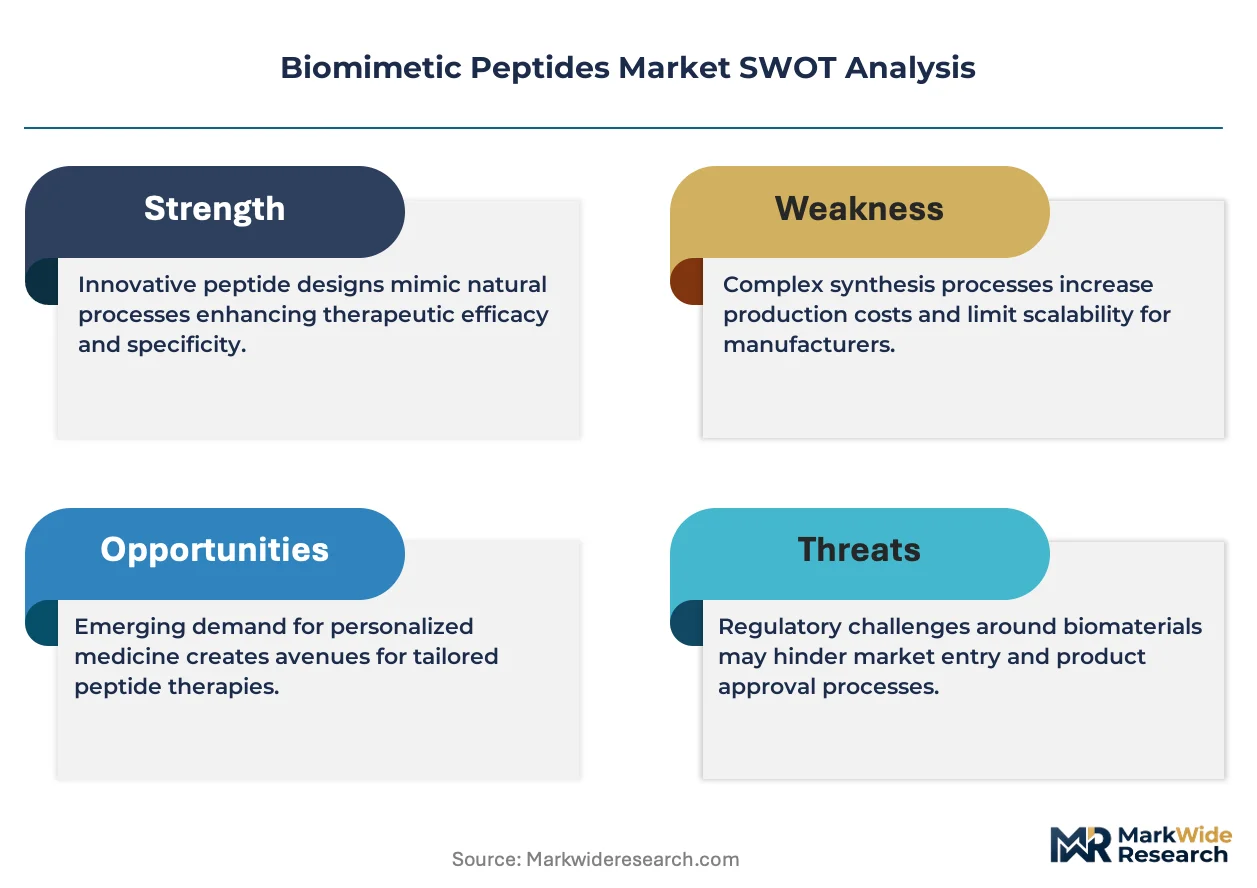
Market Restraints
- Amino Acid Input Volatility:Protected amino acid precursors face price swings tied to fine chemical supply chains concentrated in Chinese and Indian manufacturing hubs.
- Swiss-North American Manufacturing Concentration:High-volume GMP peptide capacity clusters in Switzerland and the United States, creating geographic single-point-of-failure exposure for global supply security.
- Recombinant Technology Substitution:Microbial expression systems threaten solid-phase dominance for sequences exceeding 50 amino acids requiring post-translational modifications.
Strategic Opportunities
- Underpenetrated Metabolic Disease Pipelines:GLP-1 analog expansion creates demand for novel agonist scaffolds in obesity and diabetes therapeutic development.
- EMA Biosimilar Guidance Evolution:Emerging European regulatory clarity for synthetic peptide biosimilars opens abbreviated approval pathways for follow-on developers.
- AI-Driven Sequence Optimization:Machine learning convergence with combinatorial chemistry accelerates hit-to-lead timelines for previously intractable protein targets.
Industry Challenges
- Specialized Chemist Talent Scarcity:Solid-phase synthesis expertise resides among aging practitioner cohorts with limited pipeline of trained successors entering peptide manufacturing.
- Multi-Jurisdiction Compliance Burden:Simultaneous FDA peptide quality guidelines, REACH chemical registration, and EPA discharge standards strain quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomimetic Peptides Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Peptides, Structural Peptides, Antimicrobial Peptides, Signal Peptides Application: Drug Development, Cosmeceuticals, Wound Healing, Nutraceuticals Technology: Solid-Phase Synthesis, Liquid-Phase Synthesis, Recombinant Technology, Chemical Synthesis End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Organizations |
| Companies Covered | Amgen, Bachem Holding AG, Lonza Group, DSM-Firmenich, PeptiDream, PolyPeptide Laboratories, Corden Pharma, Merck KGaA, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomimetic Peptides Market Evolving Landscape
Automation, regulatory clarity, and procurement restructuring are compressing development timelines while fragmenting traditional buyer-supplier relationships across the value chain.
Automated solid-phase peptide synthesizers are automating resin loading, deprotection cycles, and cleavage protocols that previously demanded manual intervention. Mid-sized cosmeceutical formulators in South Korea and Germany are adopting these systems at accelerating pace to bring peptide actives in-house. This shift is automating quality control bottlenecks while reducing per-batch labor costs by half.
REACH chemical registration requirements in Europe are forcing peptide manufacturers to document substance identity, impurity profiles, and environmental fate data for commercial volumes. The regulation imposes registration fees and testing burdens that favor producers with dedicated regulatory affairs teams. Therapeutic-grade peptide suppliers serving EU markets are consolidating testing partnerships to share compliance costs.
Formulators are unbundling discovery, manufacturing, and regulatory submission across specialized vendors rather than retaining integrated pipelines. Premium skincare brands now license sequences from discovery platforms, contract GMP synthesis to Lonza or Bachem, and outsource stability testing separately. This procurement fragmentation concentrates most visibly in United States and Japanese markets where brand risk tolerance for multi-vendor coordination exceeds European caution.
Biomimetic Peptides Market Segmentation
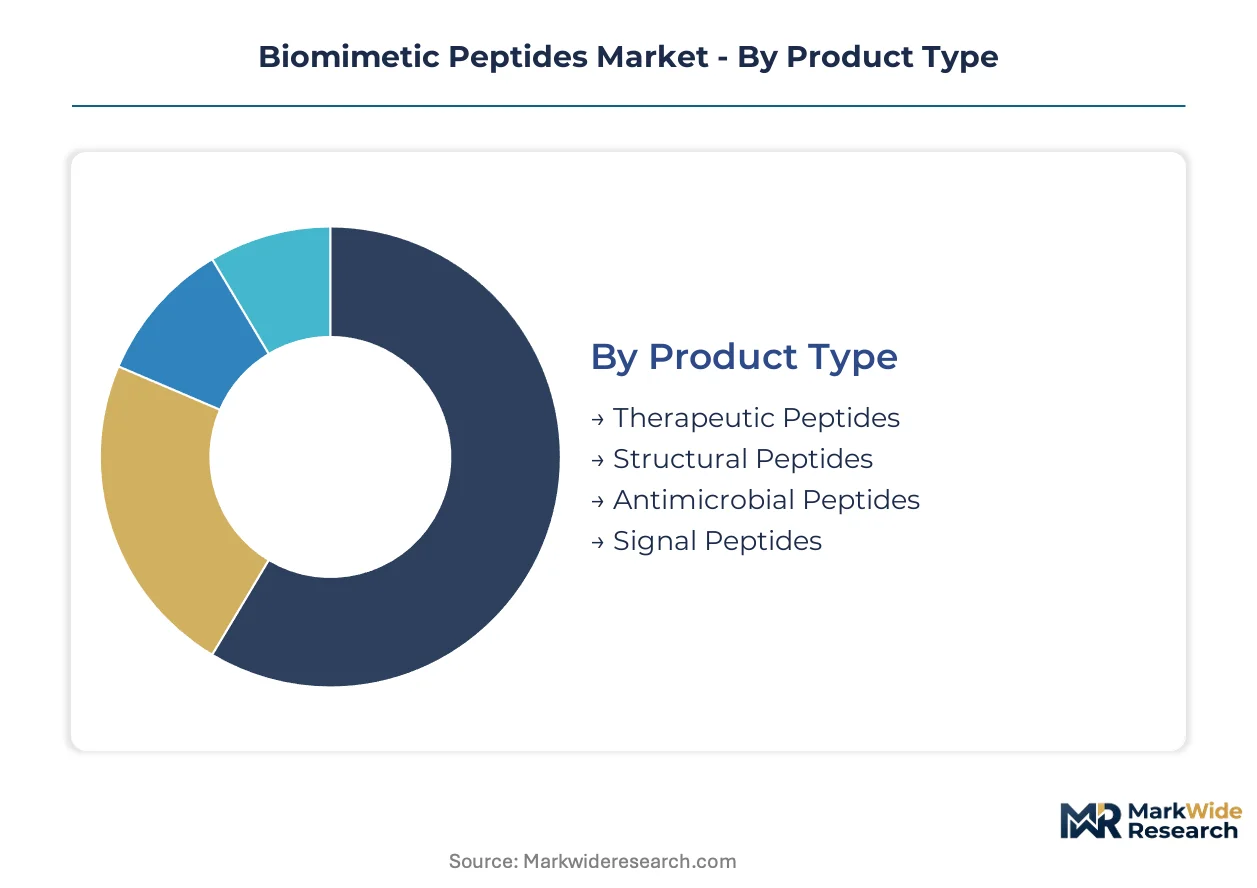
Biomimetic peptide developers navigate four intersecting taxonomies that determine manufacturing investment, regulatory pathway selection, and partnership structures. Each dimension carries distinct margin profiles and technical barriers that reshape competitive positioning across the value chain.
Product Type:
Therapeutic peptides anchor volume leadership while structural peptides command premium pricing for specialized tissue engineering applications.
- Therapeutic Peptides:Synthetic sequences engineered for metabolic disease and oncology intervention, typically 10-50 amino acids with defined secondary structures. Demand concentrates in United States pharmaceutical pipelines where FDA peptide approval pathways compress development timelines for diabetes and obesity drug candidates.
- Structural Peptides:Collagen-mimetic and elastin-like sequences that scaffold tissue regeneration matrices. Japanese and German medical device manufacturers drive premium pricing for GMP-grade structural peptides in orthopedic and dermal filler applications, with purity thresholds exceeding 98% for implantable indications.
- Antimicrobial Peptides:Cationic sequences disrupting bacterial membranes without resistance development.
- Signal Peptides:Short N-terminal sequences directing protein trafficking and cellular localization.
Today's leader: Therapeutic Peptides. Tomorrow's challenger: Structural Peptides.
Application:
Drug development absorbs the largest capital deployment while cosmeceuticals generate the steepest margin expansion for peptide suppliers.
- Drug Development:Clinical-stage therapeutic candidates requiring IND-enabling toxicology and GMP manufacturing scale. United States biotechnology clusters in Boston and San Diego concentrate demand for GLP-1 analog and peptide-drug conjugate development, with contract manufacturers qualifying dedicated peptide synthesis suites.
- Cosmeceuticals:Topical formulations leveraging cell-signaling peptides for anti-aging and barrier repair. South Korean and French premium skincare brands displace retinoids with clinically validated peptide actives, sourcing sequences through platform licensing rather than internal discovery.
- Wound Healing:Chronic ulcer and surgical closure applications requiring antimicrobial and pro-angiogenic peptide combinations.
- Nutraceuticals:Oral bioactive peptides for gut health and immune modulation with less stringent purity requirements.
Drug development commands current revenue concentration. Cosmeceuticals are gaining share fastest.
Technology:
Solid-phase synthesis retains commercial dominance while recombinant technology encroaches on longer-sequence applications.
- Solid-Phase Synthesis:Stepwise amino acid coupling on insoluble resin supports with automated cycle management. Swiss and North American contract manufacturers anchor global capacity for 95%+ purity therapeutic peptides, with Lonza and Bachem operating multi-kilogram GMP suites.
- Recombinant Technology:Microbial or mammalian expression systems for sequences exceeding 50 amino acids requiring post-translational modifications. Chinese biotech firms expand recombinant peptide capacity for complex glycopeptides, threatening solid-phase economics at scale.
- Liquid-Phase Synthesis:Solution-phase coupling for shorter diagnostic and research-grade sequences.
- Chemical Synthesis:Hybrid approaches combining solid-phase assembly with solution-phase fragment condensation.
Solid-phase synthesis maintains installed base leadership. Recombinant technology represents the fastest-growing trajectory.
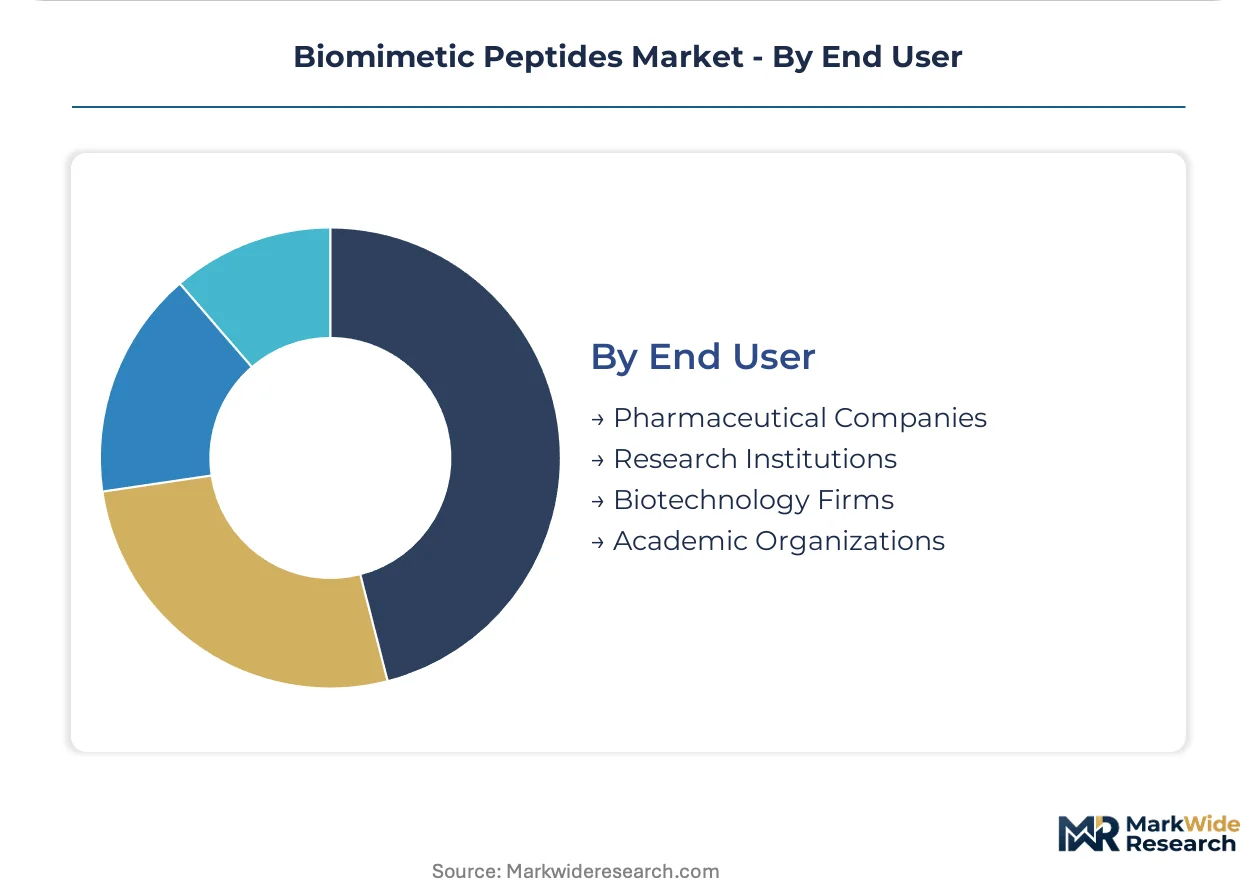
End User:
Pharmaceutical companies drive specification intensity while biotechnology firms accelerate platform licensing adoption.
- Pharmaceutical Companies:Integrated drug developers requiring end-to-end peptide CMC packages from discovery through commercial validation. United States and Japanese pharmaceutical buyers impose stringent supplier qualification protocols, auditing contract manufacturers for FDA compliance and environmental management systems.
- Biotechnology Firms:Venture-backed discovery platforms monetizing peptide libraries through partnership structures. PeptiDream and similar entities generate recurring revenue from pharmaceutical licensing without manufacturing capital deployment, concentrating in Tokyo and San Diego innovation clusters.
- Research Institutions:Academic and government laboratories sourcing catalog peptides for mechanistic studies.
- Academic Organizations:University core facilities with in-house solid-phase synthesizers for exploratory sequences.
Pharmaceutical companies anchor contract manufacturing volumes. Biotechnology firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland commands premium peptide manufacturing margins while Chinese biotech firms scale recombinant capacity at aggressive cost structures. The United States concentrates therapeutic discovery pipelines. South Korean cosmeceutical brands drive formulation innovation. Japanese medical device manufacturers anchor structural peptide demand. German chemical suppliers dominate protected amino acid precursor distribution.
United States
FDA peptide drug approval pathways compress clinical-to-commercial timelines for diabetes and obesity therapeutic candidates. The agency's emerging quality guidelines reshape manufacturing specifications for contract development organizations. Boston and San Diego biotech clusters anchor both therapeutic discovery and contract manufacturing capacity for GLP-1 analog development.
Switzerland
Swissmedic regulatory frameworks enforce stringent GMP standards that validate premium pricing for high-purity therapeutic peptides. REACH chemical registration requirements in neighboring EU markets impose documentation burdens favoring producers with dedicated regulatory affairs teams. Lonza Group and Bachem Holding AG operate multi-kilogram GMP synthesis suites serving global pharmaceutical clients from Basel-region facilities.
China
Microbial expression systems for complex glycopeptides threaten solid-phase synthesis economics at commercial scale. The country's national pharmaceutical regulator accelerates biosimilar approval pathways for metabolic disease therapeutics. Shanghai and Suzhou biotech corridors expand recombinant peptide manufacturing capacity with government-backed precision medicine initiatives.
South Korea
Premium skincare brands displace retinoids with clinically validated peptide actives in anti-aging formulations. MFDS cosmetic safety regulations mandate rigorous stability testing for bioactive topical ingredients. Seoul-based formulators license discovery platform sequences rather than maintaining internal peptide chemistry capabilities.
Japan
PMDA medical device approval pathways drive demand for 98%+ purity structural peptides in orthopedic and dermal filler applications. METI industrial policy supports domestic peptide manufacturing autonomy for critical therapeutic supply chains. Osaka and Tokyo medical device manufacturers concentrate procurement of collagen-mimetic sequences for tissue engineering matrices.
Biomimetic Peptides Market Competitive Landscape
Top-tier vendors anchor high-volume GMP manufacturing, while mid-scale discovery platforms monetize molecular IP without production assets. The vendor base stratifies across three functional tiers: integrated pharmaceutical developers, specialized contract manufacturers, and platform-licensing biotech entities. Two strategic archetypes dominate competitive positioning—scale-driven synthesis specialists and IP-rich discovery engines. Capacity expansion and strategic partnership structures represent the dominant competitive moves reshaping supplier relationships.
Among Swiss-headquartered manufacturers, Lonza Group and Bachem Holding AG occupy positions exemplifying the scale-driven archetype with established multi-kilogram GMP capabilities. PeptiDream represents the platform-licensing model, generating recurring partnership revenues without manufacturing capital deployment. These three entities collectively illustrate how molecular ownership and commercial production rights have decoupled across the value chain, with geographic concentration in Basel and Tokyo innovation clusters reinforcing competitive moats.
| Leading Market Players |
|---|
| Amgen |
| Bachem Holding AG |
| Lonza Group |
| DSM-Firmenich |
| PeptiDream |
| PolyPeptide Laboratories |
| Corden Pharma |
| Merck KGaA |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Protected amino acid precursor costs cascade through Swiss and North American manufacturing hubs into three-tier pricing structures that separate GMP-grade therapeutic peptides from cosmeceutical actives and research-grade catalog sequences. Chinese and Indian fine chemical suppliers anchor upstream input pricing, while downstream buyers in United States pharmaceutical pipelines absorb premium markups for FDA-validated purity thresholds.
Pricing Analysis
Capacity additions in China are reshaping price floors for recombinant glycopeptides while solid-phase synthesis retains premium positioning in Basel and Boston manufacturing corridors. Three-tier pricing structure across premium, standard, and economy levels separates 98%+ purity implantable structural peptides from 95% therapeutic-grade sequences and sub-90% research catalog offerings. Cost compression in mid-purity cosmeceutical grades is intensifying because South Korean formulators are bringing automated synthesis in-house. Biotechnology firms licensing discovery platforms exhibit lowest price sensitivity; mid-sized European formulators face acute margin pressure from REACH registration fee burdens.
Supply Chain Analysis
Dual-sourcing qualification mandates from United States pharmaceutical buyers are fragmenting procurement across Lonza's Swiss suites, Bachem's North American facilities, and emerging Chinese recombinant capacity. Geographic supply concentration clusters in Switzerland, the United States, and China for high-volume GMP manufacturing. Raw material dependencies center on protected amino acid precursors from Chinese and Indian fine chemical hubs, specialty resins for solid-phase synthesis, and microbial expression vectors for recombinant production. Single-source vulnerability persists for complex post-translational modification capabilities concentrated in Basel-region facilities. Distribution runs through qualified contract manufacturing agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between Swissmedic-validated premium manufacturing and Chinese cost-optimized recombinant scale, with regulatory approval timelines in the United States creating the decisive margin differential.
For Market Incumbents: Anticipate recombinant technology substitution for sequences exceeding 50 amino acids by securing backward integration into microbial expression capabilities or exclusive partnerships with Chinese biotech firms. Defend margin position through dedicated environmental management systems that preempt EPA discharge standard enforcement actions against smaller competitors. Prioritize certification investment in FDA peptide-specific quality guidelines ahead of formal rulemaking to lock in incumbent supplier qualification status.
For New Entrants and Emerging Players: Mid-sized German cosmeceutical formulators represent the most penetrable buyer archetype, as REACH compliance burdens strain their quality management systems and create procurement opening for specialized testing partners. Target automated solid-phase synthesizer deployment to capture in-house production demand from South Korean skincare brands seeking to reduce per-batch labor costs. Pursue platform licensing rather than manufacturing scale as the go-to-market angle, monetizing discovery engines through recurring partnership revenues without GMP capital deployment.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized chemist talent scarcity intersects with multi-jurisdiction compliance burdens that favor scaled producers with dedicated regulatory affairs teams. Long-term viability favors entities controlling both discovery platform IP and qualified manufacturing capacity across multiple regulatory jurisdictions. Watch for EMA biosimilar guidance finalization as the inflection signal that triggers acquisition premiums for synthetic peptide follow-on developers with abbreviated approval pathway positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide-as-a-Service Licensing Agreement | PeptiDream's partnership model generates recurring revenue without manufacturing capital risk. |
| Automated Solid-Phase Synthesizer Deployment | South Korean formulators halve per-batch labor costs while automating quality control bottlenecks. |
| GMP Manufacturing Scale-Up | Lonza's multi-kilogram suites in Basel anchor global supply for FDA-validated therapeutic candidates. |
| REACH Compliance Partnership | Testing cost-sharing consortia enable mid-scale EU suppliers to maintain market access. |
| Recombinant Capacity Expansion | Chinese microbial expression systems threaten solid-phase economics for glycopeptide sequences. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and cosmeceutical formulator R&D directors with secondary validation against FDA peptide drug approval filings, EMA biosimilar guidance documents, ClinicalTrials.gov pipeline databases, and REACH chemical registration records. Bottom-up peptide synthesis capacity assessments and top-down therapeutic pipeline value projections were triangulated for convergence.
Historical reference periods anchored demand modeling across the projection horizon, with segmentation dimensions spanning product type, application, synthesis technology, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to disclosed contract manufacturing volumes and platform licensing revenue patterns. Forecast inputs incorporated GLP-1 analog pipeline progression rates and automated synthesizer adoption curves among mid-sized formulators.
Underlying measurement precision varies by segment; therapeutic peptides with disclosed FDA approval pathways carry tighter precision than early-stage cosmeceutical actives where formulation switching rates remain unobserved. Forecasts reflect assumptions about regulatory pathway stability and amino acid precursor supply continuity. Deviation in FDA peptide-specific quality guideline timing or Chinese environmental enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Scaffold Materials Market
Biomaterials
Mushroom Materials Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Chitosan Films Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Heparin Market
Biomaterials
Chitosan Supplements Market
Biomaterials
United Kingdom Collagen Market