
 Chitosan Oligosaccharides and Glucosamine Market | 2026-2036
Chitosan Oligosaccharides and Glucosamine Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan Oligosaccharides and Glucosamine Market Insights
Pharmaceutical-grade purity specifications are collapsing the gap between commodity chitosan and high-value oligosaccharide derivatives. Primex leverages its Nordic marine sourcing to sustain premium-grade supply chains for European nutraceutical formulators. KitoZyme anchors its position through fungal fermentation platforms that bypass crustacean supply volatility. Golden-Shell Pharmaceutical dominates Asian pharmaceutical-grade output with integrated shellfish processing operations in Zhejiang province.
Chitosan oligosaccharides and glucosamine comprise depolymerized chitin derivatives with degree of polymerization typically below 20 and molecular weight ranges of 1-10 kDa for bioactive applications, functioning primarily as immunomodulatory agents, cartilage matrix precursors, and film-forming biopolymers in controlled-release formulations. Glucosamine sulfate maintains the largest revenue pool among product types due to established osteoarthritis therapeutic protocols, while chitosan oligosaccharides represent the fastest-expanding category as agricultural biostimulant applications gain regulatory traction in the EU and Brazil. Dietary supplements occupy the mature volume position, whereas cosmetics formulation—particularly topical creams leveraging chitosan's moisture-retention properties—commands superior margin profiles.
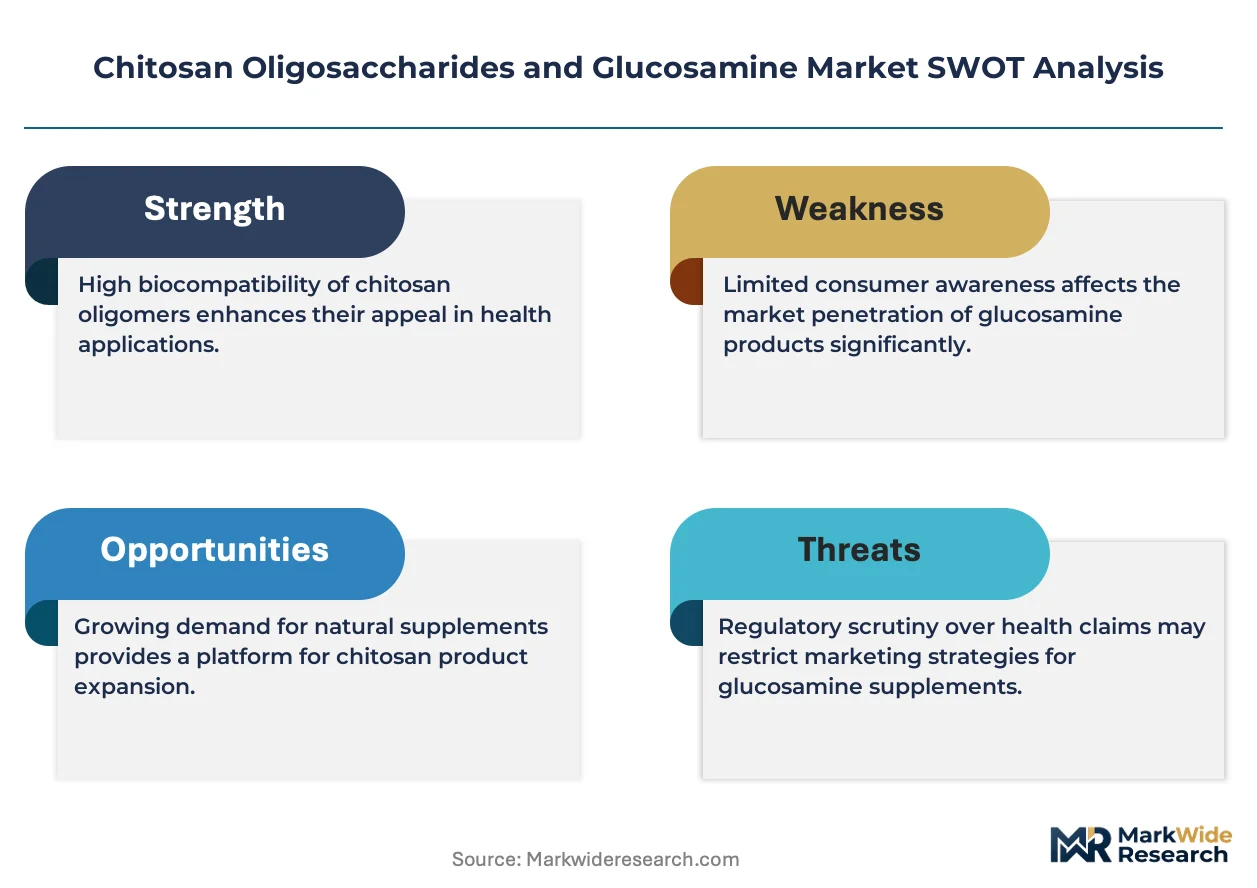
FDA dietary supplement cGMP standards and EFSA novel food authorization pathways shape product development timelines and market access requirements for new entrants. Japan's PMDA maintains distinct pharmaceutical-grade specifications that filter which glucosamine derivatives qualify for reimbursement under national health coverage. China's NMPA and SAMR jointly enforce chitosan source labeling rules that trace back to specific crustacean or fungal origins. Stakeholders must monitor evolving bioavailability validation requirements across these regulatory regimes to prioritize formulation investments.
Market Dynamics
Pharmaceutical-grade purity specifications are collapsing the gap between commodity chitosan and high-value oligosaccharide derivatives, forcing feedstock suppliers to upgrade extraction and depolymerization capabilities. METI-backed biomaterial clusters in Japan and EU Green Deal bio-based mandates are tightening procurement standards simultaneously.
Growth Catalysts
- EU Green Deal bio-based mandates:Member state feedstock requirements now favor marine-derived chitosan over synthetic alternatives, expanding addressable supply for European nutraceutical formulators.
- Japan METI cluster funding:Domestic glucosamine derivative production receives direct subsidy support, accelerating pharmaceutical-grade capacity expansion in Osaka and Kobe industrial zones.
- Agricultural biostimulant regulatory traction:EFSA novel food authorization pathways and Brazil's ANVISA biostimulant frameworks are opening crop protection applications for low-molecular-weight chitosan oligosaccharides.
Market Restraints
- Crustacean supply volatility:Seasonal fishing quotas in Southeast Asian waters create raw material discontinuities that fungal fermentation platforms bypass but at higher unit economics.
- PMDA pharmaceutical-grade filtration:Japan's reimbursement restrictions exclude glucosamine derivatives failing specific bioavailability thresholds, shrinking qualified supplier pools.
- Collagen peptide substitution:Hydrolyzed collagen alternatives capture joint health shelf space in North American retail channels, pressuring glucosamine sulfate volume positioning.
Strategic Opportunities
- Brazil agricultural biostimulant registration:ANVISA's evolving biostimulant category offers first-mover positioning for chitosan oligosaccharide suppliers targeting soybean and sugarcane cultivation.
- Cosmetics moisture-retention formulation:Topical cream applications leveraging chitosan's film-forming properties command superior margin profiles compared to dietary supplement commoditization.
- Controlled-release pharmaceutical convergence:Integration of chitosan oligosaccharides with lipid nanoparticle delivery systems creates differentiated positioning for targeted therapeutic developers.
Industry Challenges
- cGMP certification timelines:FDA dietary supplement manufacturing standards impose 18-24 month validation periods that delay new entrant market access and tie up working capital.
- Degree of polymerization standardization:Absence of harmonized ISO methods for molecular weight distribution measurement creates batch inconsistency disputes between suppliers and pharmaceutical formulators.
- Dual-origin traceability systems:China's NMPA and SAMR joint enforcement of crustacean versus fungal source labeling requires redundant supply chain documentation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan Oligosaccharides and Glucosamine Market |
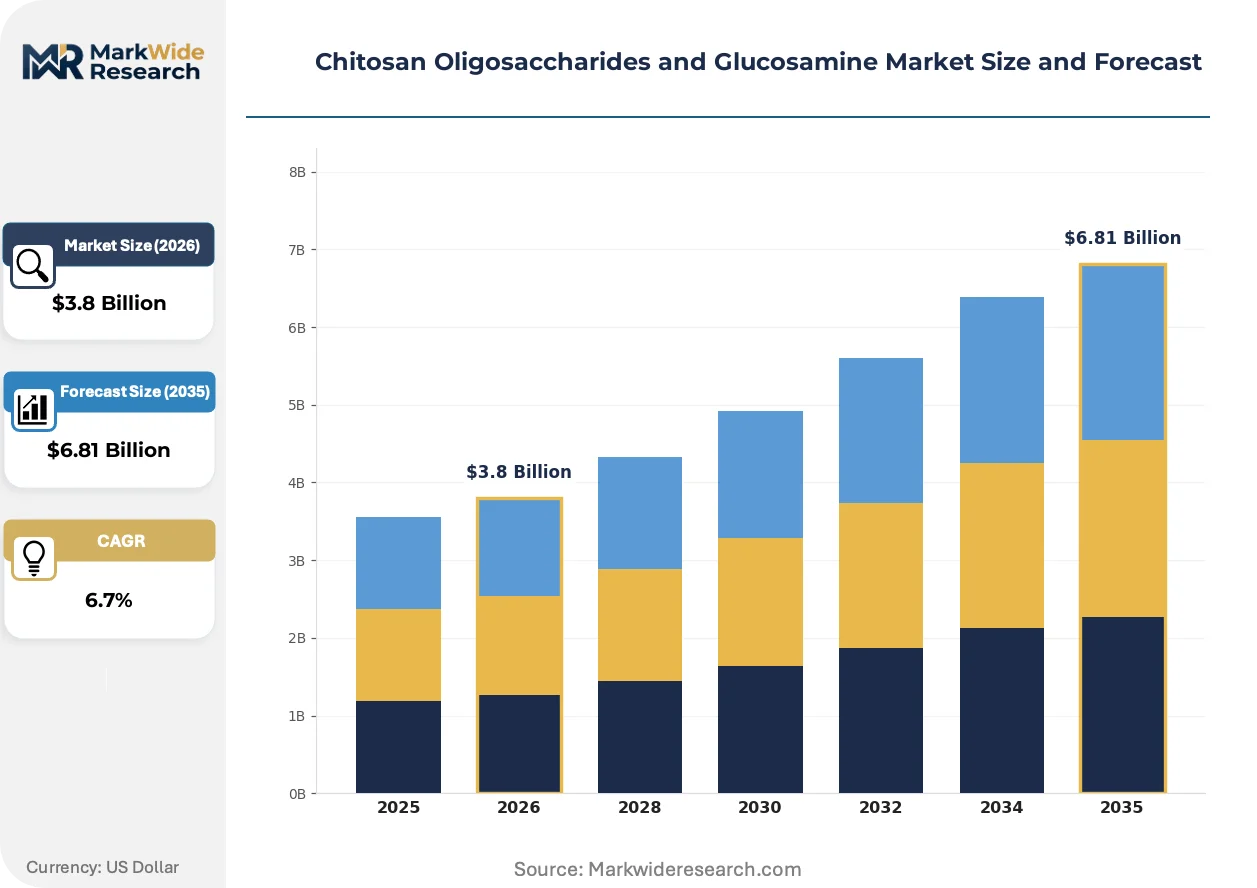
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitosan Oligosaccharides, Glucosamine Sulfate, Glucosamine Hydrochloride, N-Acetyl Glucosamine, Chitosan Derivatives Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Agriculture Additives, Animal Nutrition, Food Preservatives End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Personal Care Producers, Agrochemical Firms, Veterinary Providers, Food & Beverage Entities Formulation Type: Powder, Capsule, Liquid, Tablet, Topical Cream, Injectable |
| Companies Covered | Primex, KitoZyme, GTC Bio Corporation, Heppe Medical Chitosan, Panvo Organics, Advanced Biopolymers, Amicogen, Golden-Shell Pharmaceutical, Bioiberica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan Oligosaccharides and Glucosamine Market Trends and Innovations
Enzymatic depolymerization technologies are reshaping production economics by enabling precise molecular weight control previously achievable only through chemical hydrolysis. This precision unlocks application-specific grade stratification that chemical methods cannot replicate.
Enzymatic chitosan hydrolysis is decomposing the traditional trade-off between yield and purity that constrained commercial viability of low-polymerization grades. Agricultural biostimulant manufacturers in Brazil and the Netherlands are adopting fungal-derived enzyme cocktails at pilot scale. This technology is decomposing barriers between commodity feedstock suppliers and premium pharmaceutical-grade producers by democratizing access to controlled depolymerization.
EFSA novel food authorization pathways are compressing product development timelines for chitosan oligosaccharide entrants seeking European market access. The industrial consequence is accelerated formulation investment ahead of regulatory clarity, with suppliers pre-positioning toxicology dossiers. Dietary supplement categories face the tightest authorization scrutiny, forcing developers to pivot toward cosmetic and agricultural applications where regulatory friction remains lower.
Direct procurement relationships between pharmaceutical formulators and marine processing operations are displacing layered distributor networks that historically captured margin without adding technical value. This channel compression concentrates volume with vertically integrated suppliers capable of certifying purity from catch to final powder. The pattern is most visible in Zhejiang province and Nordic coastal regions where integrated shellfish processing infrastructure supports traceability requirements.
Chitosan Oligosaccharides and Glucosamine Market Segmentation
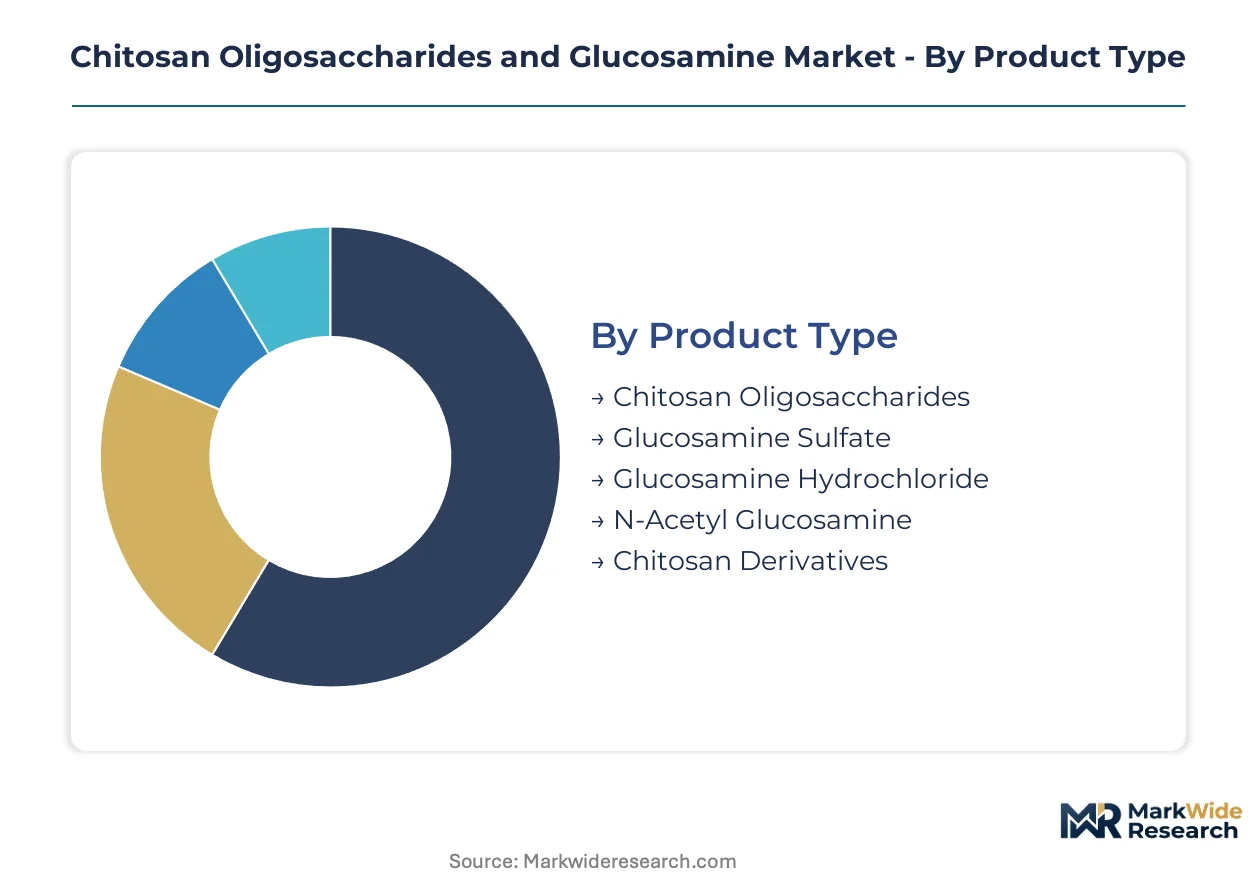
Segmentation in this market reveals divergent margin architectures across product grades and application tiers. Pharmaceutical-grade specifications command pricing multiples over commodity feedstock derivatives, while regulatory authorization pathways fragment accessible demand pools by geography.
Product Type:
Domestic production clusters in Japan and China anchor supply for glucosamine derivatives, whereas chitosan oligosaccharide output concentrates in Nordic marine processing zones and Zhejiang shellfish operations for export-led pharmaceutical formulation.
- Chitosan Oligosaccharides:Depolymerized chitin with degree of polymerization below 20 and molecular weight of 1-10 kDa for bioactive applications. Japanese METI-backed biomaterial clusters and EU Green Deal bio-based mandates are accelerating procurement by pharmaceutical manufacturers for targeted delivery systems.
- Glucosamine Sulfate:Established osteoarthritis therapeutic protocols maintain this as the largest revenue pool among product types. North American retail channels face substitution pressure from hydrolyzed collagen alternatives, compressing volume positioning in joint health segments.
- Glucosamine Hydrochloride:Alternative salt form with distinct solubility profiles for capsule and tablet manufacturing.
- N-Acetyl Glucosamine:Derivative form targeting cosmetics moisture-retention applications and skin barrier function formulations.
- Chitosan Derivatives:Modified grades including carboxymethyl and quaternary ammonium variants for specialized film-forming and antimicrobial applications.
Glucosamine sulfate commands the established base. The steepest expansion runs through chitosan oligosaccharides.
Application:
Margin profiles stratify sharply across this dimension, with cosmetics formulation commanding superior returns compared to dietary supplement commoditization and agricultural biostimulant applications gaining regulatory traction in Brazil and the EU.
- Dietary Supplements:Mature volume position facing FDA cGMP certification timelines of 18-24 months that delay new entrant market access. EFSA novel food authorization pathways impose the tightest scrutiny on this category, forcing developers toward alternative applications.
- Pharmaceuticals:Controlled-release formulations leverage chitosan oligosaccharide integration with lipid nanoparticle delivery systems. Japan's PMDA maintains distinct pharmaceutical-grade specifications that filter qualifying derivatives for national health coverage reimbursement.
- Cosmetics:Topical creams exploit chitosan's moisture-retention and film-forming properties for premium positioning.
- Agriculture Additives:Low-molecular-weight grades gain ANVISA biostimulant framework traction in Brazilian soybean and sugarcane cultivation.
- Animal Nutrition:Feed-grade applications for joint health in companion animals and livestock.
- Food Preservatives:Antimicrobial film coatings and shelf-life extension applications.
Dietary supplements anchor volume throughput. Pharmaceuticals and agricultural additives are climbing the fastest.
End User:
Procurement patterns distinguish between formulators requiring full traceability documentation and those accepting commodity-grade supply, with direct relationships between pharmaceutical manufacturers and marine processing operations displacing layered distributor networks.
- Pharmaceutical Manufacturers:Require pharmaceutical-grade purity specifications that collapse the gap between commodity chitosan and high-value oligosaccharide derivatives. China's NMPA and SAMR joint enforcement of source labeling rules demands redundant supply chain documentation infrastructure.
- Nutraceutical Companies:European formulators favor marine-derived chitosan under EU Green Deal bio-based mandates, expanding addressable supply from Nordic coastal operations.
- Personal Care Producers:Cosmetics manufacturers prioritize moisture-retention formulation capabilities.
- Agrochemical Firms:Brazilian operators target first-mover positioning in ANVISA's evolving biostimulant category.
- Veterinary Providers:Companion animal joint health applications.
- Food & Beverage Entities:Natural preservative and packaging film applications.
Nutraceutical companies sustain the volume foundation. Pharmaceutical manufacturers are gaining share fastest.
Formulation Type:
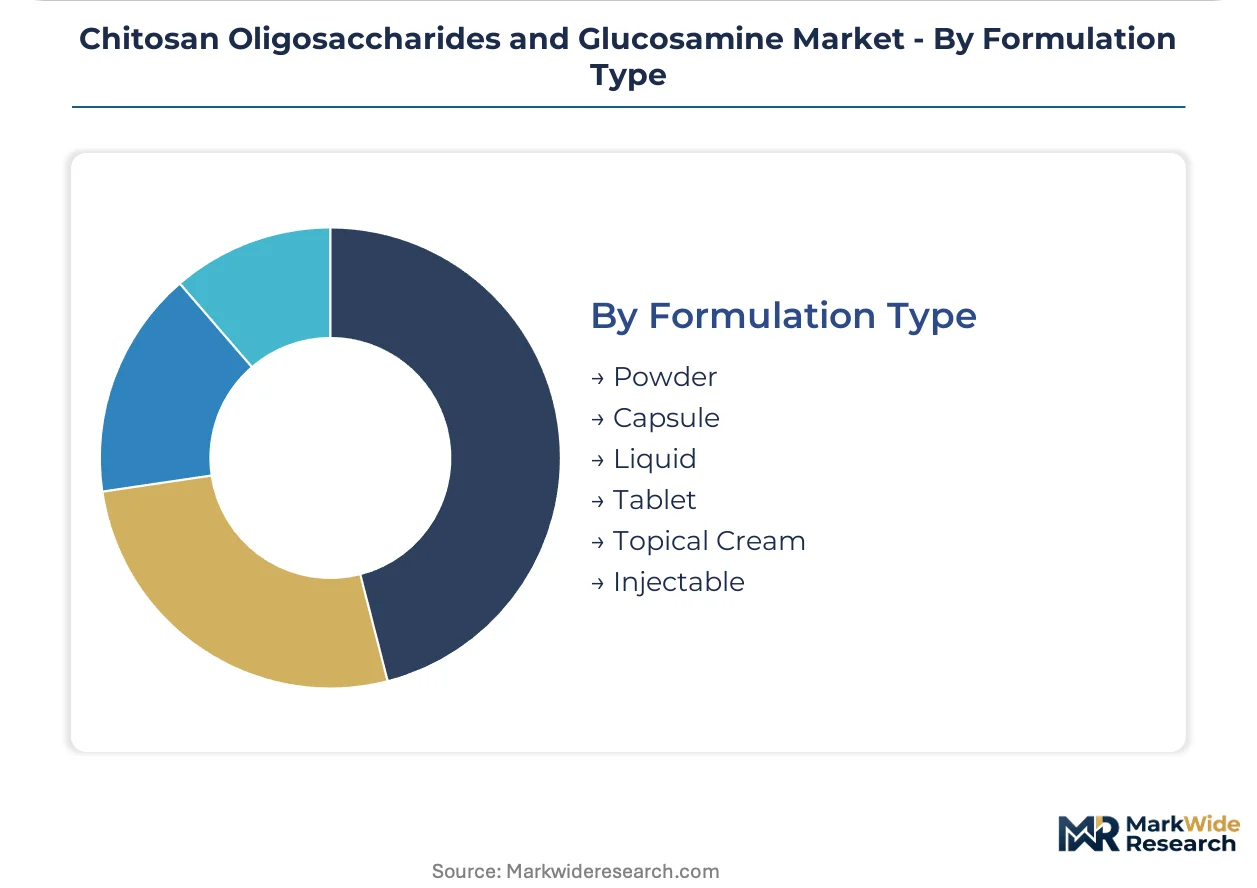
Delivery format selection determines regulatory pathway complexity, with injectable and topical cream formulations facing distinct bioavailability validation requirements compared to oral solid dosage forms.
- Powder:Bulk active pharmaceutical ingredient and agricultural biostimulant input form. Degree of polymerization standardization disputes between suppliers and formulators create batch inconsistency challenges absent harmonized ISO methods.
- Capsule:Dominant oral delivery format for glucosamine sulfate in joint health protocols.
- Liquid:Solution formulations for pediatric and geriatric compliance segments.
- Tablet:Compressed solid dosage requiring specific excipient compatibility.
- Topical Cream:Film-forming applications leverage chitosan's moisture-retention properties for superior margin profiles in cosmetics channels.
- Injectable:Parenteral formulations for pharmaceutical-grade chitosan oligosaccharides in controlled-release delivery systems.
Capsule and tablet formats command the established base. Topical cream and injectable applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led supply chains from marine processing zones dominate trade flows, with import dependency structuring demand patterns in pharmaceutical manufacturing clusters. Nordic coastal operations and Zhejiang shellfish processors anchor outbound volumes toward European nutraceutical formulators and Japanese pharmaceutical manufacturers.
China
Zhejiang province houses integrated shellfish processing infrastructure that certifies purity from catch to final powder for pharmaceutical-grade output. NMPA and SAMR jointly enforce crustacean versus fungal source labeling rules that demand redundant supply chain documentation infrastructure. Qingdao and Dalian marine biotechnology clusters are expanding depolymerization capacity to serve domestic pharmaceutical formulators and export markets.
Japan
Osaka and Kobe industrial zones receive direct METI subsidy support for domestic glucosamine derivative production capacity expansion. PMDA maintains distinct pharmaceutical-grade specifications that filter qualifying derivatives for national health coverage reimbursement, shrinking qualified supplier pools. The Kansai biomaterial cluster concentrates enzymatic depolymerization pilot operations for agricultural biostimulant applications.
United States
FDA dietary supplement cGMP standards impose 18-24 month validation periods that delay new entrant market access and tie up working capital. North American retail channels face hydrolyzed collagen substitution pressure in joint health segments, compressing glucosamine sulfate volume positioning. Boston and San Diego pharmaceutical corridors are pre-positioning toxicology dossiers ahead of EFSA novel food authorization pathway clarity.
Germany
EU Green Deal bio-based mandates favor marine-derived chitosan over synthetic alternatives, expanding addressable supply for European nutraceutical formulators. ECHA REACH compliance requirements structure feedstock procurement standards across member states. Hamburg marine biotechnology operations leverage Nordic sourcing partnerships to sustain premium-grade supply chains.
Brazil
ANVISA's evolving biostimulant category offers first-mover positioning for chitosan oligosaccharide suppliers targeting soybean and sugarcane cultivation. São Paulo agrochemical corridors are adopting fungal-derived enzyme cocktails at pilot scale for agricultural applications. Campinas and Ribeirão Preto industrial zones concentrate formulation investment for crop protection derivatives.
Chitosan Oligosaccharides and Glucosamine Market Competitive Landscape
Concentration sits with vertically integrated marine processors and fungal fermentation platforms that bypass crustacean supply volatility. The competitive terrain splits between Nordic coastal operations certifying pharmaceutical-grade purity and Asian integrated shellfish processors controlling traceability from raw material to final powder. Two strategic archetypes dominate: marine-source vertically integrated suppliers and fermentation-based alternative feedstock platforms. Capacity expansion in enzymatic depolymerization and direct procurement relationships displacing layered distributor networks constitute the dominant competitive moves.
Within the marine-source tier, Primex leverages Nordic coastal positioning to sustain premium-grade supply chains for European nutraceutical formulators. KitoZyme anchors the fermentation-based archetype through fungal platforms that circumvent seasonal raw material discontinuities. Golden-Shell Pharmaceutical occupies a position exemplifying Asian integrated processing dominance with Zhejiang-based operations. These three represent the structural split between geographic sourcing strategies and alternative feedstock technologies reshaping competitive positioning.
| Leading Market Players |
|---|
| Primex |
| KitoZyme |
| GTC Bio Corporation |
| Heppe Medical Chitosan |
| Panvo Organics |
| Advanced Biopolymers |
| Amicogen |
| Golden-Shell Pharmaceutical |
| Bioiberica |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Nordic marine processors and European nutraceutical formulators lock in supply access and price visibility for pharmaceutical-grade chitosan oligosaccharides, insulating buyers from spot market volatility in crustacean feedstock markets while embedding quality certification costs into fixed pricing schedules.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Pharmaceutical-grade purity specifications and EFSA novel food authorization status command substantial premiums over feed-grade derivatives. Cost compression in commodity chitosan tiers is intensifying because fungal fermentation platforms are expanding supply volumes. Dietary supplement manufacturers exhibit the highest price sensitivity, whereas pharmaceutical formulators prioritize bioavailability validation over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese pharmaceutical manufacturers facing PMDA reimbursement filtration risks, while European nutraceutical formulators favor just-in-time procurement under EU Green Deal bio-based mandates. Supply concentrates in China, Norway, and Japan. Production draws from crustacean shell waste, fungal mycelium biomass, and enzymatic depolymerization reagents. Single-source vulnerability runs through Southeast Asian fishing quota disruptions. Distribution runs through direct procurement relationships displacing layered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic depolymerization technologies are disrupting production economics and regulatory access pathways simultaneously, compressing development timelines for pharmaceutical-grade entrants and fragmenting competitive positioning between marine-source and fermentation-based supply archetypes.
For Market Incumbents: Fortify pharmaceutical-grade certification moats by accelerating backward integration into enzymatic depolymerization capacity in Osaka and Kobe industrial zones. Deepen captive supply of fungal fermentation platforms to circumvent crustacean quota volatility threatening margin stability.
For New Entrants and Emerging Players: Lead with agricultural biostimulant applications in Brazil's ANVISA regulatory window, where authorization friction remains lower than dietary supplement pathways. Target cosmetics moisture-retention formulations for premium positioning with shorter validation cycles than pharmaceutical routes.
For Investors and Strategic Acquirers: Nordic coastal processors with integrated shellfish operations and EFSA dossier pre-positioning represent the most defensible acquisition archetype. Monitor EFSA novel food authorization grant velocity as the inflection signal distinguishing premium-grade suppliers from commodity feedstock operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Depolymerization Scale-Up | Enables precise molecular weight control for pharmaceutical-grade specifications previously achievable only through chemical hydrolysis. |
| Backward Integration into Fungal Fermentation | Bypasses crustacean supply volatility while meeting EU Green Deal bio-based mandates for sustainable feedstock sourcing. |
| EFSA Novel Food Dossier Investment | Pre-positions toxicology documentation ahead of regulatory clarity for accelerated European market access. |
| Direct Procurement Relationship Development | Displaces layered distributor networks to capture margin and certify traceability from catch to final powder. |
| Cosmetics Formulation Partnership | Exploits superior margin profiles in topical cream applications leveraging chitosan's film-forming properties. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical formulation, nutraceutical manufacturing, and agricultural biostimulant development. Primary interviews captured perspectives from regulatory affairs leads at EFSA and PMDA, procurement directors at European nutraceutical formulators, and technical R&D directors at enzymatic depolymerization technology providers. Secondary validation drew from FDA cGMP guidance documents, EFSA novel food authorization registers, METI cluster funding disclosures, and customs trade data for chitosan derivative flows. Bottom-up volume modeling triangulated against top-down value estimates across product grade tiers and application segments.
Across the analysis window, forecasts employed a segmented analytical framework spanning product type, application, end user, and formulation format dimensions. CAGRs were derived from regression analysis against historical authorization pathway timelines and capacity expansion announcements. Key inputs included enzymatic depolymerization technology adoption curves and PMDA reimbursement qualification rates for pharmaceutical-grade derivatives.
Forecasts assume regulatory continuity in EFSA novel food pathways and PMDA pharmaceutical-grade specifications; material policy shifts would require re-modeling. Crustacean supply disruptions, collagen peptide substitution acceleration, or ISO standardization breakthroughs for degree of polymerization measurement constitute primary revision triggers. Revision becomes warranted when fungal fermentation platform economics cross cost-parity thresholds with marine-source production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Biomaterials Market
Biomaterials
Chitosan Market
Biomaterials
Bone Substitutes Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Global Collagen and HA Based Biomaterial Market