
 China Sports Drink Market | 2026-2036
China Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
China Sports Drink Market Outlook
Natural sweeteners is pivoting away from artificial additives across China's sports drink sector. Nongfu Spring leverages its deep spring water sourcing network to anchor premium positioning in mineral-enhanced variants. Eastroc Beverage dominates energy-format shelf space through convenience store exclusivity in southern provinces. Genki Forest differentiates via zero-sugar formulations that appeal to calorie-conscious fitness communities.
A sports drink is a functional beverage engineered with electrolytes, carbohydrates, and minerals to replenish fluids and nutrients lost during physical exertion, typically formulated with osmolality between 250 and 330 mOsm/kg for rapid gastric emptying. Isotonic products lead volume sales by matching body fluid concentration, while hypotonic variants capture growth among endurance athletes seeking faster absorption without caloric load. Online retail channels expand fastest as live-stream commerce platforms reshape how fitness enthusiasts in tier-two cities discover specialized formulations.
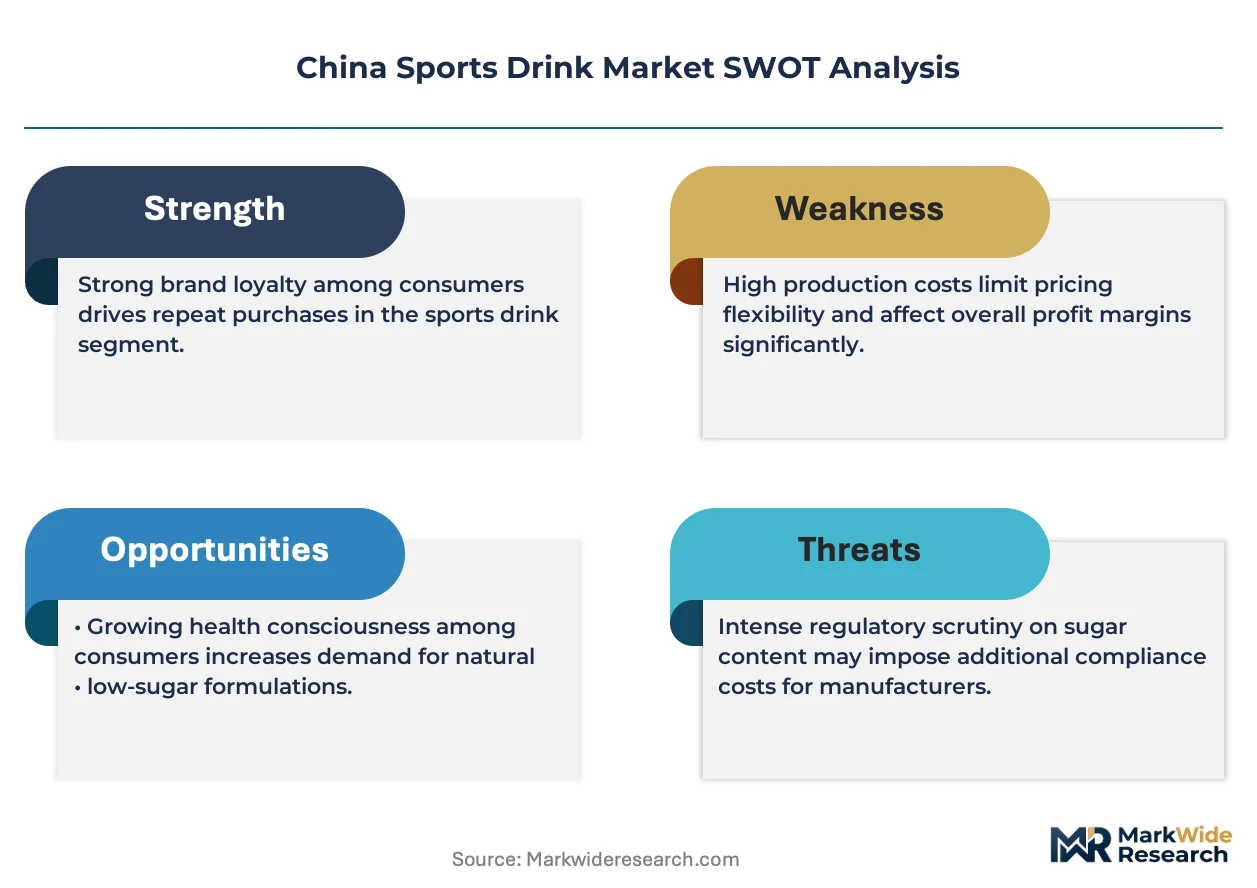
SAMR enforces GB standards that mandate electrolyte thresholds and additive disclosures, compelling reformulation investments from domestic producers. The country's national food safety regulator conducts randomized shelf audits that elevate compliance costs for smaller entrants. China's dual carbon goals pressure bottlers to adopt recycled PET and lightweight packaging, reshaping procurement criteria across the supply base. Stakeholders must track how evolving GB revisions around sugar content ceilings will redirect R&D spending toward natural flavor systems.
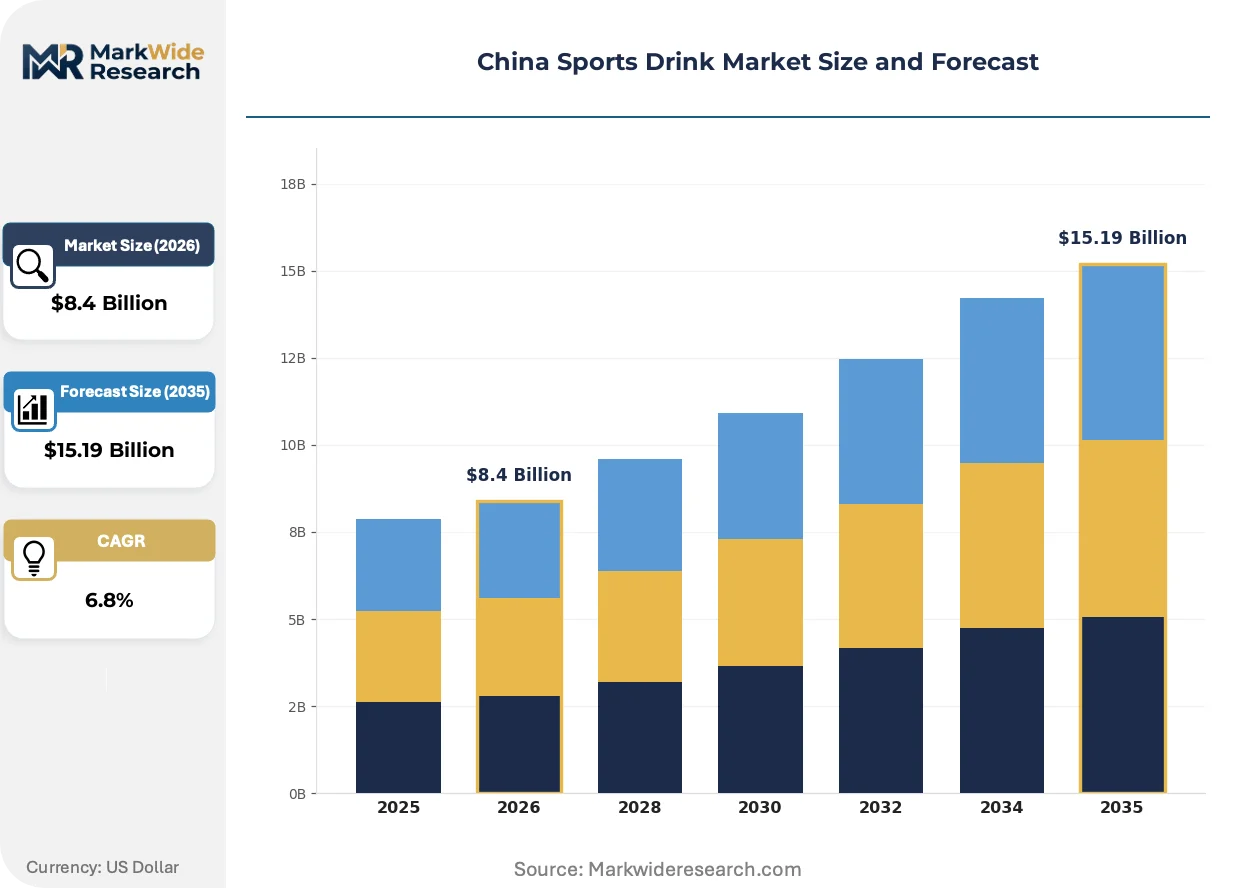
Market Dynamics
China's dual carbon goals are forcing bottlers to reconfigure supply chains around recycled PET sourcing and lightweight packaging formats, elevating procurement costs while reshaping competitive positioning between mineral-water legacy players and zero-sugar challengers.
Growth Catalysts
- GB standards enforcement:SAMR-mandated electrolyte thresholds and additive disclosure rules accelerate reformulation investments from domestic producers, raising barriers against unqualified entrants.
- Fitness community expansion:Calorie-conscious athletes in tier-two cities drive demand for specialized isotonic and hypotonic formulations through live-stream commerce discovery.
- Eastroc Beverage:Convenience store exclusivity in southern provinces creates channel lock-in that accelerates energy-format adoption among urban commuters.
Market Restraints
- Sugar content ceilings:Evolving GB revisions around carbohydrate thresholds force costly R&D pivots toward natural flavor systems, compressing margin structures for mid-tier producers.
- Spring water sourcing concentration:Premium mineral-enhanced variants depend on captive deep-water reserves concentrated in specific provincial clusters, creating supply vulnerability.
- Artificial sweetener substitution:Stevia and monk fruit extracts face technical limitations in masking bitterness at higher electrolyte loads, constraining formulation flexibility.
Strategic Opportunities
- Western province penetration:Underpenetrated inland markets beyond eastern coastal provinces offer whitespace for isotonic products targeting emerging fitness infrastructure.
- Live-stream commerce integration:TikTok Shop and Douyin fitness influencer channels enable direct-to-consumer discovery that bypasses traditional convenience store gatekeepers.
- Lightweight packaging mandates:Dual carbon goals create regulatory tailwinds for rPET adoption that rewards early movers with preferred supplier status from state-owned retail chains.
Industry Challenges
- Food safety auditor scarcity:SAMR's randomized shelf audit protocols require specialized compliance personnel that smaller regional bottlers struggle to recruit and retain.
- Legacy formulation integration:Transitioning existing production lines from artificial to natural sweetener systems demands capital-intensive equipment retrofits without guaranteed volume recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sports Drink Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Energy Customer Type: Professional Athletes, Fitness Enthusiasts, Casual Users, Kids Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Clubs Flavor: Fruit Punch, Lemon-Lime, Berry, Tropical |
| Companies Covered | Red Bull, Suntory C.C. Lemon, Gatorade, Genki Forest, Eastroc Beverage, Mizone, Nongfu Spring, Powerade, Pocari Sweat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sports Drink Market Strategic Shifts
Live-stream commerce platforms are compressing brand discovery cycles while GB regulatory revisions force simultaneous reformulation across multiple technical dimensions, creating a market where agility in natural ingredient sourcing separates survivors from casualties.
Electrolyte micro-encapsulation technology is absorbing volatility in mineral bioavailability during extended shelf storage. Endurance athletes in Beijing and Shanghai training facilities are adopting these stabilized formulations at accelerating rates. The technology is absorbing market share from conventional ionic solutions by enabling cleaner-label claims without sacrificing osmolality precision.
GB standards revision cycles around sugar content ceilings are compressing formulation timelines for domestic producers. SAMR's draft disclosure requirements for non-nutritive sweeteners force parallel development tracks for natural alternatives. Premium mineral-enhanced variants face the steepest compliance costs as they must simultaneously satisfy electrolyte thresholds and clean-label positioning.
Calorie-conscious procurement patterns among young professional athletes are disintermediating traditional convenience store discovery. Fitness communities in Hangzhou and Chengdu now source specialized hypotonic formulations through Douyin influencer recommendations rather than retail shelf browsing. This behavioral shift concentrates brand-building investment toward content creation capabilities rather than slotting fee negotiations.
China Sports Drink Market Segmentation
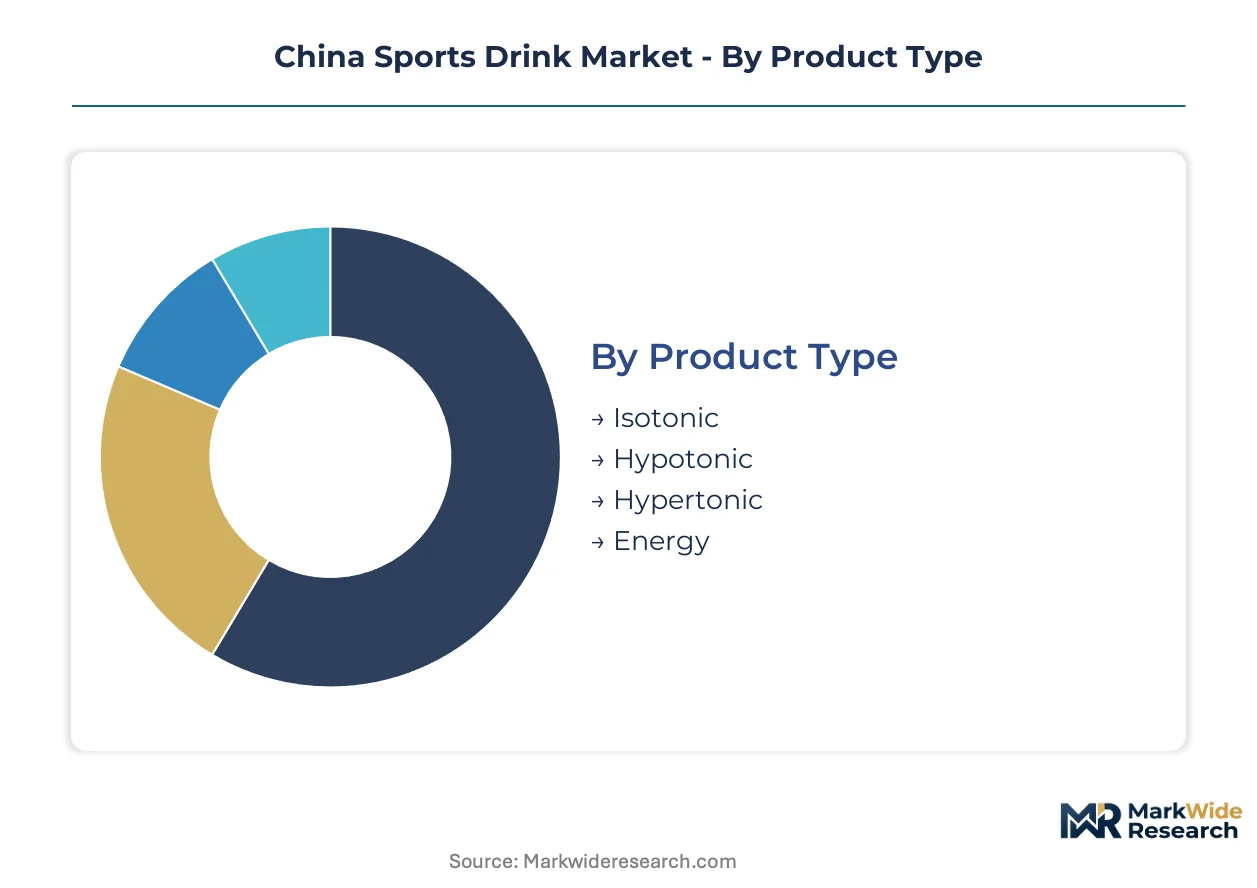
Segmentation in China's sports drink market reveals how GB standards and dual carbon goals force divergent upgrade paths across formulation types and channel strategies. Manufacturers must align R&D investments with distinct electrolyte thresholds and packaging mandates that vary by customer sophistication and regional enforcement intensity.
Product Type:
Reformulation cycles accelerate as SAMR tightens electrolyte disclosure rules, pushing bottlers toward precision osmolality engineering that separates legacy portfolios from next-generation offerings.
- Isotonic:Formulated at 250-330 mOsm/kg to match body fluid concentration, enabling rapid gastric emptying without digestive stress. Demand concentrates in Shanghai and Beijing training facilities where professional athletes require balanced sodium-potassium replenishment during high-intensity sessions. SAMR's electrolyte thresholds favor these established formulations with documented absorption kinetics.
- Hypotonic:Lower osmolality solutions prioritize fluid absorption speed over caloric density, targeting endurance athletes in Hangzhou and Chengdu who train in humid conditions. The segment climbs fastest as calorie-conscious fitness communities disintermediate traditional retail discovery through Douyin influencer channels.
- Hypertonic:Concentrated carbohydrate-electrolyte matrices designed for post-exercise glycogen replenishment rather than mid-activity hydration.
- Energy:Caffeine-amino acid hybrids positioned for mental alertness alongside physical performance, dominant in southern province convenience store networks.
Isotonic sits at the top of the volume ranking, with hypotonic climbing the fastest as live-stream commerce reshapes discovery patterns.
Customer Type:
Procurement sophistication tiers separate institutional buyers with compliance departments from individual consumers navigating clean-label claims through social commerce.
- Professional Athletes:Institutional procurement teams at Beijing and Shanghai training centers mandate batch-level electrolyte certification and additive disclosure documentation that exceeds baseline GB requirements.
- Fitness Enthusiasts:Calorie-tracking consumers in tier-two cities drive zero-sugar variant adoption through community-validated influencer recommendations rather than traditional advertising.
- Casual Users:Occasional exercisers seeking taste-forward refreshment with nominal functional claims, price-sensitive and channel-agnostic.
- Kids:Parent-governed purchases constrained by sugar content ceilings and school vending machine restrictions, forcing natural sweetener adaptation.
Professional athletes command the premium pricing tier, while fitness enthusiasts expand most quickly through digital channel migration.
Distribution Channel:
Channel configuration determines compliance burden intensity, with state-owned retail chains imposing rPET mandates that reshape supplier qualification criteria.
- Supermarkets:State-owned chains in eastern coastal provinces enforce dual carbon packaging standards that disqualify non-rPET suppliers from shelf access.
- Convenience Stores:Southern province networks maintain exclusivity arrangements with energy-format specialists, creating channel lock-in that resists digital disruption.
- Online Retail:Douyin and TikTok Shop platforms compress discovery cycles through fitness influencer content, expanding fastest in tier-two cities beyond traditional retail penetration.
- Health Clubs:On-premise vending at Beijing and Shanghai facilities favors isotonic formulations with institutional electrolyte certification.
Convenience stores retain the largest volume footprint, though online retail gains share fastest as live-stream commerce penetrates inland provinces.
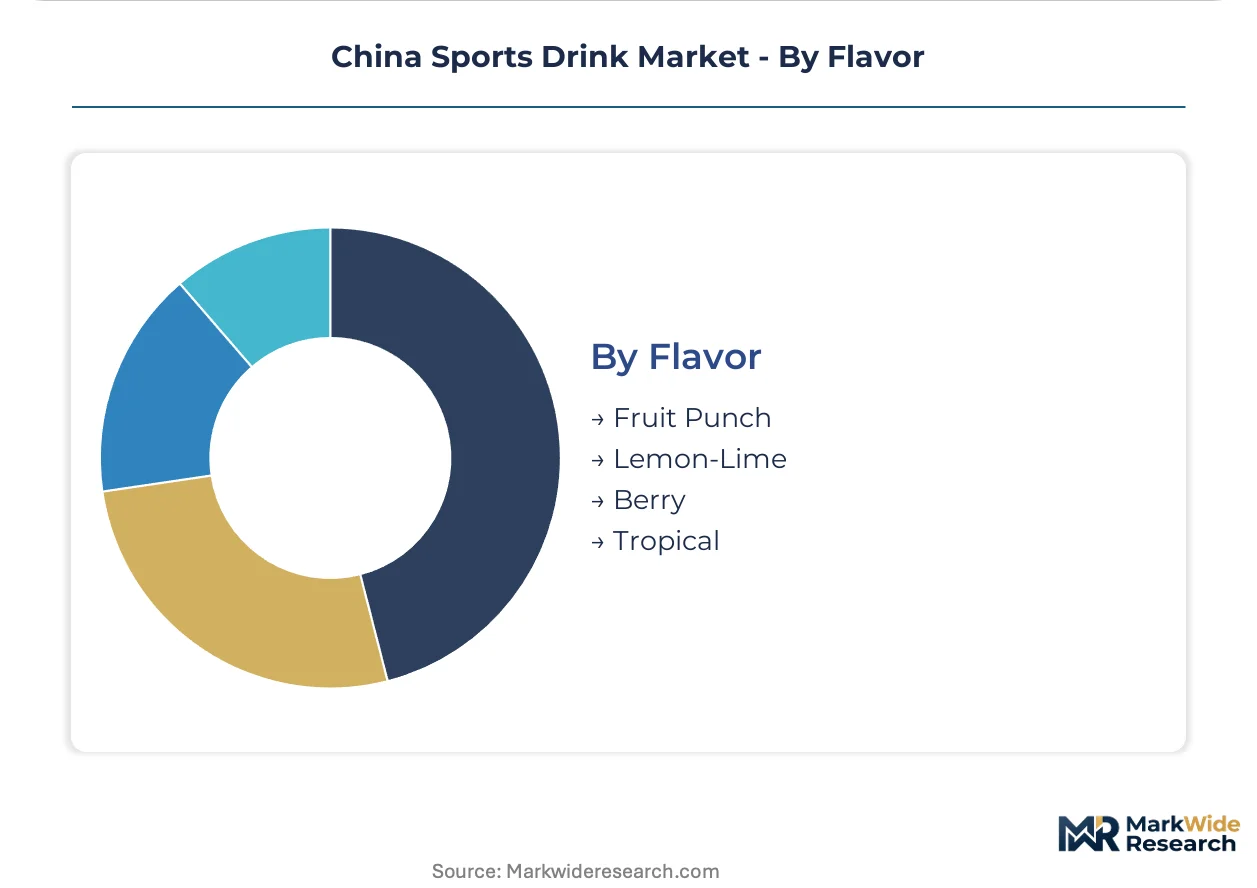
Flavor:
Natural flavor system investments concentrate in variants capable of masking electrolyte bitterness without artificial additive dependencies that trigger GB disclosure requirements.
- Fruit Punch:Synthetic flavor legacy formulations face steepest reformulation pressure as SAMR draft rules expand additive disclosure mandates.
- Lemon-Lime:Citrus profiles leverage natural citric acid buffers that align with clean-label positioning without sacrificing taste stability.
- Berry:Anthocyanin-derived color systems from domestic agricultural clusters support premium mineral-enhanced variant positioning.
- Tropical:Pineapple-coconut blends targeting casual users in southern provinces with taste-forward refreshment profiles.
Lemon-lime dominates volume through formulation versatility, while berry variants expand most quickly as natural colorant supply chains mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing corridors anchor China's sports drink production capacity, with formulation labs clustering around Shanghai's beverage innovation ecosystem. Provincial GB enforcement intensity varies across eastern coastal, central, and western zones, creating divergent compliance cost structures that reshape regional competitive positioning.
Shanghai
Professional athlete training facilities in Pudong and Minhang districts drive institutional procurement of certified isotonic formulations. SAMR conducts randomized shelf audits with elevated frequency in this municipality, compelling bottlers to maintain dedicated compliance teams. Live-stream commerce studios in Xuhui district broadcast fitness influencer content that redirects consumer discovery toward specialized hypotonic variants.
Beijing
State-owned retail chains in Chaoyang and Haidian enforce dual carbon packaging mandates that disqualify non-rPET suppliers from shelf access. National sports training centers in Shunyi district mandate batch-level electrolyte certification exceeding baseline GB requirements. Domestic producers headquarter R&D functions here to maintain proximity to SAMR regulatory consultation channels.
Guangdong Province
Convenience store networks in Guangzhou and Shenzhen maintain exclusivity arrangements with energy-format specialists, creating channel lock-in across southern province retail corridors. Pearl River Delta bottling infrastructure supports lightweight packaging retrofits demanded by provincial environmental enforcement. Humid climate conditions drive endurance athlete preference for faster-absorption hypotonic formulations.
Sichuan-Chongqing
Emerging fitness infrastructure in Chengdu and Chongqing creates whitespace demand for isotonic products previously concentrated in coastal markets. Provincial GB enforcement operates at lower intensity than eastern counterparts, allowing mid-tier producers to test reformulated natural sweetener systems before nationwide rollout. Douyin influencer networks penetrate these inland markets faster than traditional retail distribution.
Zhejiang Province
Hangzhou's e-commerce ecosystem hosts live-stream commerce platforms that compress brand discovery cycles for calorie-conscious fitness communities. Nongfu Spring leverages captive deep spring water reserves in provincial clusters to anchor premium mineral-enhanced positioning. Provincial environmental bureaus pilot recycled PET procurement incentives that reward early supply chain reconfigurations.
China Sports Drink Market Competitive Environment
Reformulation investments dominate the current landscape as GB standard revisions force simultaneous technical pivots across electrolyte thresholds and natural sweetener systems. The vendor base separates into three tiers: mineral-water legacy players with captive spring reserves, zero-sugar challengers with influencer-driven discovery models, and energy-format specialists with convenience store channel lock-in. Strategic archetypes include compliance-forward premium positioners, digital-native direct-to-consumer brands, and scale-driven mass-market bottlers. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with producers extending formulation expertise across isotonic, hypotonic, and energy sub-categories while penetrating western provinces beyond traditional coastal strongholds.
Among international beverage conglomerates, Gatorade and Red Bull exemplify archetypal approaches to functional hydration positioning. Gatorade represents the institutional certification tier, with formulation portfolios engineered to satisfy professional athlete procurement standards. Red Bull anchors the energy-format specialization vector, occupying shelf space through mental alertness positioning alongside physical performance claims. Domestic challengers including Nongfu Spring and Genki Forest occupy distinct archetype positions—Nongfu Spring exemplifies mineral-water legacy leverage through deep spring sourcing networks, while Genki Forest represents zero-sugar challenger dynamics via calorie-conscious community validation. Eastroc Beverage sits within the southern province channel lock-in archetype, with convenience store exclusivity arrangements that resist digital disruption.
| Leading Market Players |
|---|
| Red Bull |
| Suntory C.C. Lemon |
| Gatorade |
| Genki Forest |
| Eastroc Beverage |
| Mizone |
| Nongfu Spring |
| Powerade |
| Pocari Sweat |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between SAMR-compliant mineral-enhanced variants and commodity isotonic formulations manifests in both procurement premiums and captive spring water sourcing networks. Price stratification across premium, standard, and economy tiers reflects electrolyte disclosure documentation depth and dual carbon packaging compliance status.
Pricing Analysis
Input-cost pass-through from stevia and monk fruit extract procurement is intensifying margin compression in zero-sugar segments. Three-tier pricing structure across premium, standard, and economy levels separates batch-certified institutional supply from mass-market convenience store SKUs. Pricing pressure stems from GB revision cycles forcing parallel natural sweetener development tracks. Casual users in tier-two cities exhibit highest price sensitivity, while professional athlete procurement teams absorb premiums for electrolyte certification documentation.
Supply Chain Analysis
SAMR additive disclosure mandates and dual carbon packaging standards operate as qualification gates that disqualify non-compliant suppliers from state-owned retail chain access. Manufacturing concentrates in China, with formulation labs clustering around Shanghai's beverage innovation ecosystem and Pearl River Delta bottling infrastructure. Raw material dependencies include deep spring water reserves, rPET feedstock, and natural sweetener agricultural supply chains. Single-source vulnerability concentrates in captive provincial water clusters. Distribution runs through state-owned supermarket networks, convenience store exclusivity arrangements, and Douyin live-stream commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China sports drink demand compounds through successive GB standard revision cycles, with SAMR's electrolyte threshold mandates and sugar content ceiling drafts accelerating reformulation investment requirements.
For Market Incumbents: Cement channel control through rPET compliance investment that secures preferred supplier status from state-owned retail chains. Lock in captive spring water reserves through provincial lease extensions before mid-tier competitors achieve GB certification. Natural sweetener technical limitations and energy-format shelf space competition from southern province specialists constitute primary threats. For New Entrants and Emerging Players: Begin with underpenetrated western province fitness infrastructure in Chengdu and Chongqing where GB enforcement intensity remains lower than coastal counterparts. Target calorie-conscious fitness communities in Hangzhou and Chengdu through Douyin influencer content rather than convenience store slotting fee competition. Live-stream commerce integration enables direct-to-consumer discovery that bypasses incumbent channel gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR compliance costs and dual carbon packaging mandates exceed mid-tier producer capital access. Long-term viability favors mineral-water legacy players with captive spring reserves or zero-sugar challengers with proven influencer-driven customer acquisition. Watch for GB sugar content ceiling finalization as inflection indicator that redirects R&D spending toward natural flavor system specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | Parallel development tracks for natural sweetener systems satisfy SAMR draft disclosure requirements ahead of GB revision finalization. |
| Spring Water Reserve Lock-in | Provincial lease extensions anchor premium mineral-enhanced positioning against supply vulnerability from concentrated deep-water clusters. |
| rPET Supply Chain Reconfiguration | Recycled PET adoption secures preferred supplier status from state-owned retail chains enforcing dual carbon packaging mandates. |
| Live-stream Commerce Integration | Douyin and TikTok Shop platforms compress brand discovery cycles for fitness communities in tier-two cities beyond traditional retail penetration. |
| Western Province Distribution Buildout | Chengdu and Chongqing market entry captures whitespace demand from emerging fitness infrastructure with lower compliance cost structures. |
Study Parameters
Direct dialogue with beverage formulation scientists, SAMR compliance officers, convenience store category buyers, and live-stream commerce platform operators grounds qualitative assessment in operational reality. Secondary validation draws from GB standards documentation, SAMR enforcement bulletins, provincial environmental bureau circulars, and customs records of natural sweetener imports. Bottom-up demand modeling across customer segments triangulates against top-down category value estimates.
Segment-level projections across product type, customer sophistication tier, distribution channel, and regional enforcement intensity populate the analytical framework over the projection horizon. CAGRs derive from electrolyte threshold adoption curves, natural sweetener substitution rates, and live-stream commerce penetration patterns in inland provinces. Hypotonic formulation adoption among endurance athletes and rPET procurement incentive rollouts constitute key forecast inputs.
Several conditions sit outside the modeled scope, including abrupt SAMR enforcement intensity shifts, spring water reserve depletion timelines, and trade policy disruptions affecting natural sweetener agricultural supply chains. Forecasts reflect assumptions around GB revision implementation pacing and dual carbon goal provincial allocation formulas. A model refresh is warranted upon material change in SAMR sugar content ceiling finalization or state-owned retail chain rPET mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
North America Sports Drink Market