
 Sports Training Market | 2026-2036
Sports Training Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Training Market Analysis
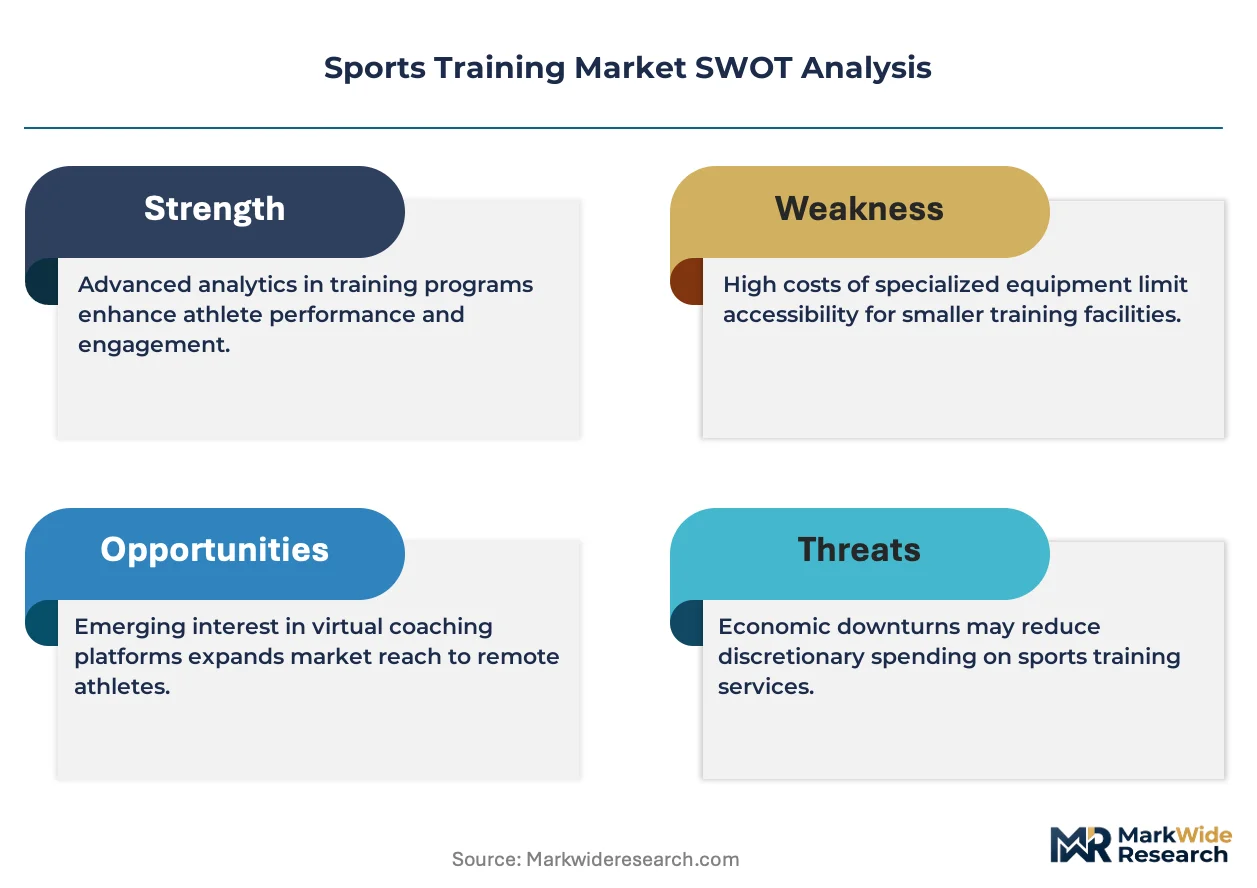
Capital-intensity divergence between hardware-heavy wearable manufacturers and lean software analytics providers is unwinding competitive boundaries across the sports training ecosystem. WHOOP sustains premium positioning through vertically integrated biometric sensor production and subscription analytics. Orreco differentiates by specializing in recovery science and menstrual cycle tracking for female athletes. Skillz navigates regulatory complexity by anchoring its platform in skill-based mobile gaming rather than traditional wagering.
Sports training encompasses structured physical conditioning, technical skill development, and tactical preparation delivered through coached instruction, digital platforms, or self-directed protocols, typically quantified via heart rate variability, power output, movement velocity, or sport-specific performance benchmarks to optimize physiological adaptation and competitive readiness. Online Coaching and Hybrid Training represent the fastest-expanding Training Method categories as asynchronous digital delivery reduces geographic constraints and lowers per-session marginal cost. Strength Training dominates Equipment-related spending, with free weights and resistance bands commanding durable margin pools due to minimal technology obsolescence and broad accessibility across amateur and professional user tiers.
FDA oversight of wearable medical claims, FCC certification for wireless biometric transmission, and state-level athletic commission regulations governing coaching credentials collectively shape product development pathways and market access requirements for sports technology vendors. NCAA governance of student-athlete compensation and training hour limitations creates distinct demand parameters separate from professional league structures. Stakeholders must monitor evolving data privacy frameworks governing athlete biometric collection as jurisdictional fragmentation between federal health privacy standards and emerging state laws complicates platform deployment strategies.
Market Dynamics
Wearable biometric sensors and AI-powered performance analytics are compressing the traditional coach-athlete relationship into algorithmic feedback loops, forcing training providers to restructure service delivery around data subscription models rather than hourly instruction.
Growth Catalysts
- NCAA governance reforms:Student-athlete compensation rules and expanded training hour allowances are redirecting university athletic budgets toward specialized coaching infrastructure and recovery technology procurement.
- Biometric sensor miniaturization:Continuous glucose monitors and EMG patches are migrating from clinical settings to consumer sports applications, opening physiological tracking to amateur endurance athletes.
- India:The PLI scheme for wearable electronics manufacturing is attracting component assembly operations, reducing landed costs for heart rate variability monitors across South Asian markets.
Market Restraints
- Input cost volatility:Rare earth magnet prices for precision motion-capture sensors fluctuate with Chinese export quotas, squeezing hardware margins for resistance-training equipment manufacturers.
- Regulatory friction:FDA 510(k) clearance requirements for devices making medical-grade recovery claims extend product launch timelines by 14-22 months versus wellness-classified competitors.
- Technical limitation:Optical heart rate monitors fail during high-impact combat sports and underwater training, forcing redundant sensor architectures that inflate bill-of-materials costs.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA streamlined medical device registration pathways in 2023, reducing market entry friction for recovery-focused wearables targeting football academies.
- Technology convergence:Generative AI coaching assistants integrated with computer-vision movement analysis are enabling automated technique correction without human coach presence.
- Regulatory tailwind:The EU AI Act's risk classification framework creates compliance moats for European sports analytics platforms that pre-certify algorithmic training recommendations.
Industry Challenges
- Skill gap in data interpretation:Collegiate coaching programs graduate staff proficient in biomechanics but deficient in Python-based analytics pipelines, creating implementation bottlenecks for sensor deployments.
- Capex intensity:Force plate installations and 3D motion-capture suites require $180,000-$400,000 facility investments that amortize poorly across seasonal high school athletic programs.
- Integration complexity:Legacy athlete management systems from the 2010s lack API compatibility with modern biometric data streams, forcing expensive middleware development or manual data reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Training Market |
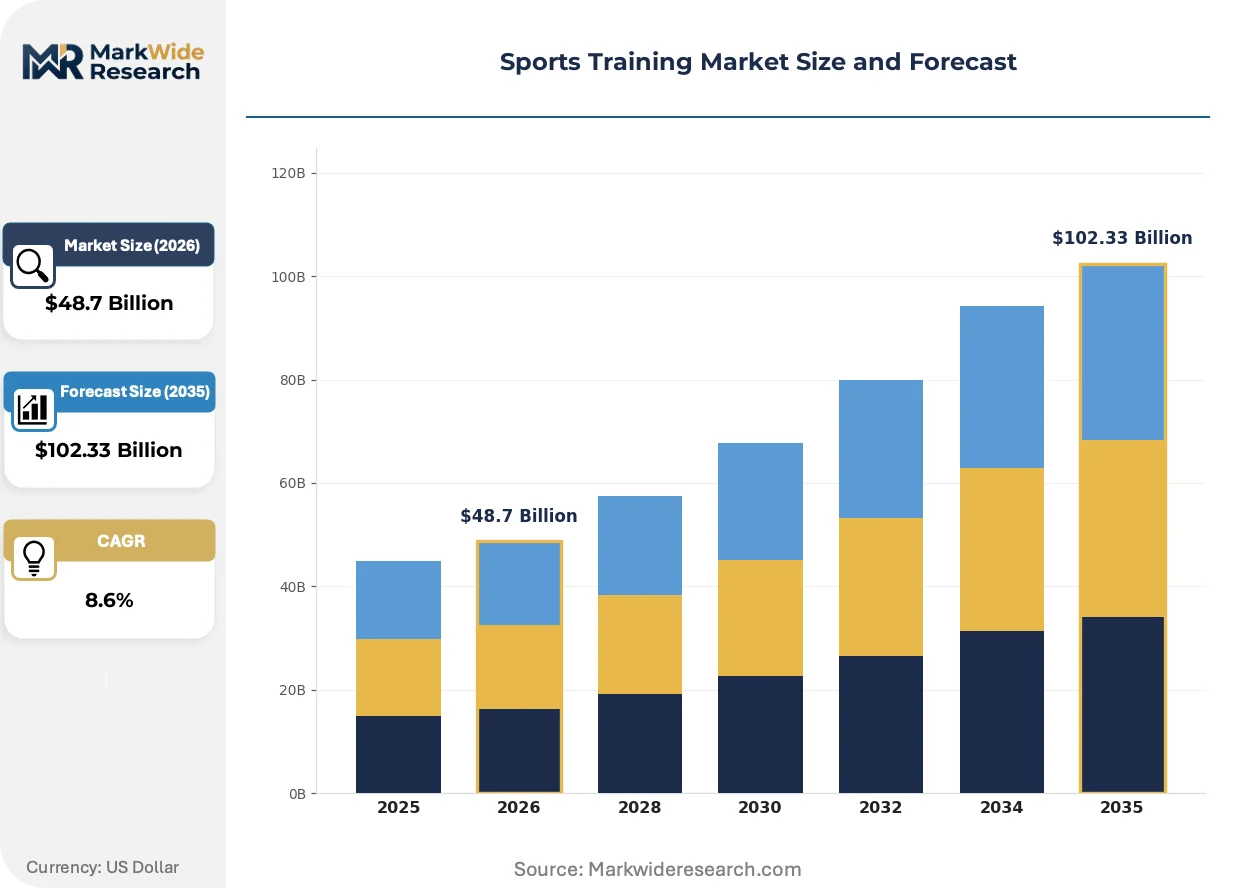
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Strength Training, Endurance Training, Flexibility Training, Speed Training Training Method: Personal Coaching, Group Sessions, Online Coaching, Hybrid Training Equipment: Free Weights, Resistance Bands, Cardio Machines, Bodyweight Equipment Target Audience: Athletes, Fitness Enthusiasts, Seniors, Youth |
| Companies Covered | Oracle, DraftKings, WHOOP, Bolt6, Athletes Unlimited, Sportable, Skillz, Owl AI, Orreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Training Market Emerging Trajectories
Algorithmic personalization is dissolving the one-size-fits-all training template, replacing standardized periodization with real-time physiological responsiveness that adapts load and recovery within single sessions.
Computer-vision movement analysis is supplanting wearable-dependent kinematic tracking in team sports environments. NBA and Premier League franchises are deploying markerless camera systems that capture sprint mechanics and jump landing forces without athlete compliance burdens. This technology is compressing the market for chest-strap heart rate monitors in group training contexts where individual sensor management proved operationally unwieldy.
GDPR's biometric data classification and emerging US state privacy laws are fragmenting athlete data governance frameworks. Platforms storing EU athlete physiological data must implement data residency requirements and explicit consent architectures that increase compliance overhead. Professional cycling teams and football clubs with transnational rosters are responding by segmenting data infrastructure geographically rather than maintaining unified global databases.
Athlete procurement of coaching services is fragmenting from institutional contracts toward direct-to-consumer subscription models. Individual professionals in tennis and golf are bypassing academy affiliations to retain AI-assisted remote coaches, while collegiate programs face retention pressure from private platforms offering personalized regimens. This behavioral shift is most visible in the United States, where NIL compensation enables student-athletes to purchase supplemental training outside university-controlled channels.
Sports Training Market Segmentation
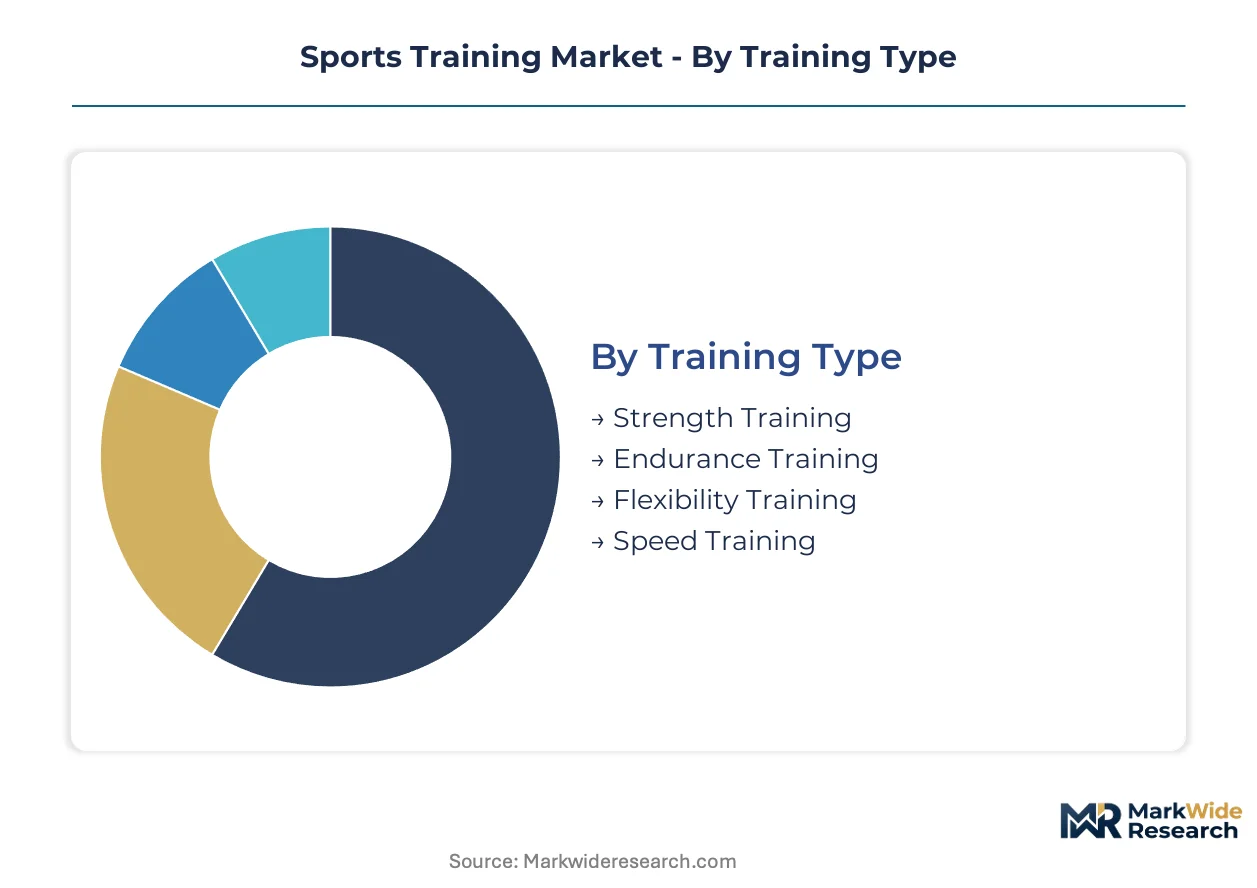
Segmentation in sports training reveals divergent commercial logics: hardware procurement cycles differ fundamentally from service subscription economics, while amateur and professional user tiers demand incompatible feature sets and price points.
Training Type:
Channel distribution varies sharply—strength and endurance modalities flow through institutional bulk contracts to collegiate athletic departments, while flexibility and speed training reach consumers via direct-to-consumer app subscriptions and boutique studio memberships.
- Strength Training:Free weights, resistance machines, and compound movement protocols dominate equipment capital expenditure at university athletic facilities. NCAA Division I programs in the United States allocate substantial annual budgets to Olympic lifting platforms and variable resistance systems, driven by football and basketball program demands for explosive power development.
- Endurance Training:Periodized cardiovascular conditioning using heart rate zones, lactate threshold testing, and VO2 max protocols. Demand concentrates among amateur triathletes and marathon runners in Germany and Australia, where aging populations pursue age-group competition and wearable-enabled self-coaching reduces dependence on club memberships.
- Flexibility Training:Mobility protocols and range-of-motion protocols delivered through yoga, Pilates, and dynamic stretching regimens. Boutique studios in London and Los Angeles bundle these with recovery services.
- Speed Training:Sprint mechanics, acceleration drills, and neuromuscular coordination protocols. Elite football academies in Brazil and sprint programs in Jamaica represent concentrated institutional demand.
By volume, Strength Training leads institutional procurement. By growth pace, Endurance Training is expanding most quickly through consumer wearable integration.
Training Method:
Cost tier stratification separates premium personalized instruction from mass-accessible digital delivery, with hybrid models capturing margin expansion by combining algorithmic personalization with periodic human oversight.
- Personal Coaching:One-on-one instruction with customized periodization and real-time biomechanical correction. High-net-worth individuals in the United Arab Emirates and Singapore sustain premium pricing for celebrity coach retainers, with session rates reflecting coach certification tier and facility amenity packages.
- Online Coaching:Asynchronous program delivery via mobile applications with video demonstration libraries and messaging-based feedback loops. Indian and Indonesian markets show rapid uptake among price-sensitive urban professionals seeking flexibility around work schedules.
- Group Sessions:Semi-private instruction with 4-12 participants sharing a coach's attention. CrossFit affiliates and Barry's Bootcamp locations in the United Kingdom and Canada utilize this model for yield optimization.
- Hybrid Training:Blended delivery combining in-person assessment with remote program adjustment and digital check-ins. Corporate wellness contracts in Japan and South Korea increasingly specify this structure for executive populations.
By volume, Group Sessions dominate membership counts. By growth pace, Hybrid Training is gaining share fastest as employers and insurers subsidize flexible engagement models.
Equipment:
Technology obsolescence risk and replacement cycle length differentiate margin profiles—minimal-electronics categories amortize over decades while sensor-embedded equipment faces 3-5 year functional deprecation.
- Free Weights:Barbells, dumbbells, kettlebells, and weight plates with standardized dimensions for Olympic and powerlifting competition. Municipal recreation centers across Poland and Czech Republic continue expanding free weight zones as durable infrastructure with minimal maintenance overhead.
- Resistance Bands:Elastic variable-resistance tools for portability and rehabilitation applications. Post-surgical physical therapy protocols in Sweden and Denmark specify these for home exercise compliance.
- Cardio Machines:Treadmills, ellipticals, rowing ergometers, and stationary bicycles with integrated entertainment systems. Commercial gym chains in Mexico and Argentina face financing constraints on fleet refresh cycles.
- Bodyweight Equipment:Pull-up bars, dip stations, suspension trainers, and parallettes for calisthenics progression. Outdoor fitness parks in Barcelona and Sydney deploy these for public health initiatives.
By volume, Free Weights lead shipment tonnage. By growth pace, Bodyweight Equipment shows steepest expansion trajectory as municipal budgets prioritize outdoor infrastructure.
Target Audience:
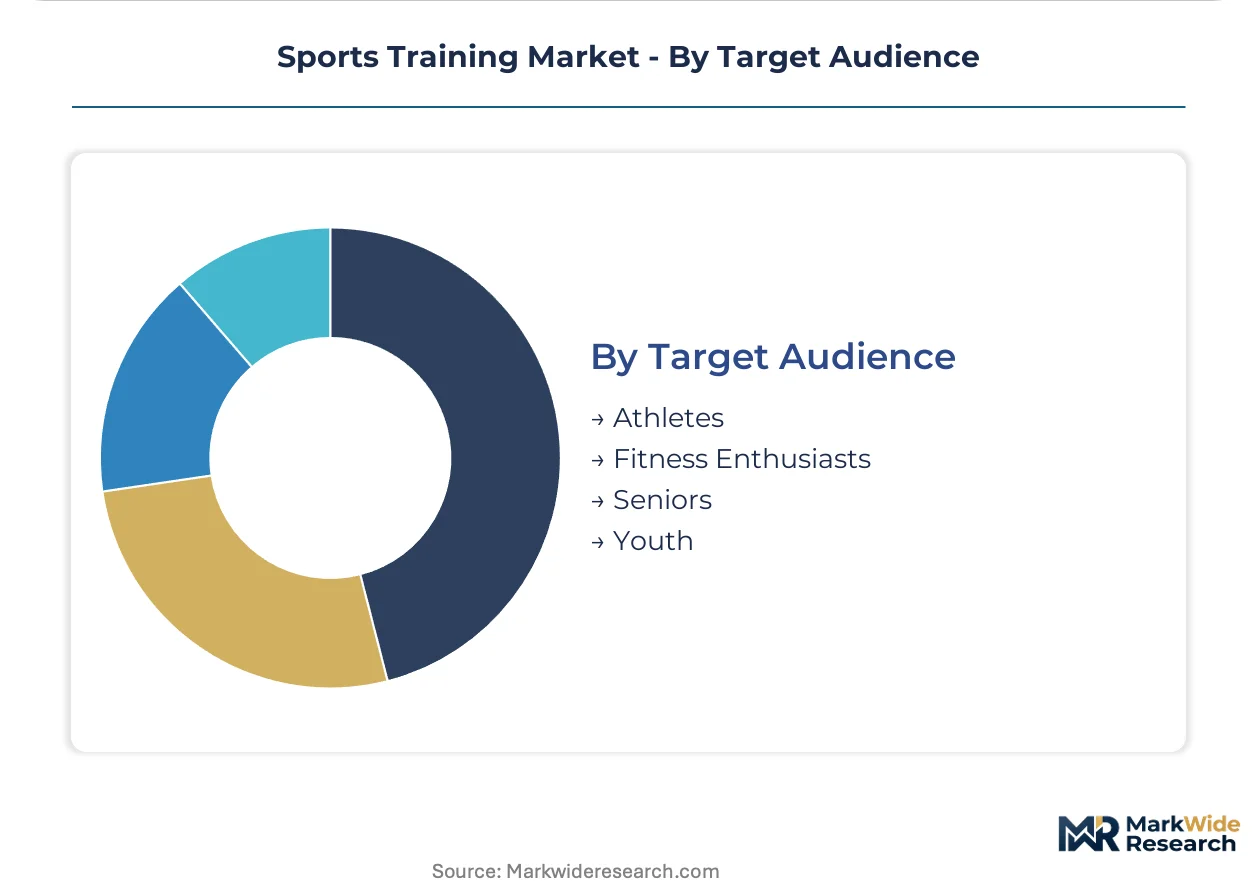
Application context dictates feature prioritization—performance metrics for competitive populations versus safety architecture and social engagement for recreational and senior segments.
- Athletes:Competitive professionals, collegiate scholarship holders, and age-group amateurs pursuing sanctioned competition. National Olympic committees in Italy and Spain fund centralized training centers with integrated sports science support.
- Fitness Enthusiasts:Non-competitive regular exercisers seeking aesthetic or general health outcomes. Boutique studio memberships in New York and Chicago show high churn susceptibility to economic downturns.
- Seniors:Adults 65+ pursuing fall prevention, bone density maintenance, and chronic condition management. Medicare Advantage plans in Florida and Arizona increasingly cover SilverSneakers-equivalent programming.
- Youth:School-age children in organized sports or physical education contexts. Private academies in Shanghai and Beijing face regulatory scrutiny on training intensity limits for minors.
By volume, Fitness Enthusiasts represent the largest addressable population. By growth pace, Seniors is climbing the fastest as longevity economics reshape healthcare-adjacent spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Amateur endurance athletes in Germany and Australia absorb premium wearable pricing for self-coaching autonomy, while municipal recreation centers in Poland and Czech Republic prioritize durable free-weight infrastructure with minimal maintenance overhead.
United States
NCAA governance reforms redirect university athletic budgets toward specialized coaching infrastructure and recovery technology procurement. FDA 510(k) clearance requirements for medical-grade recovery claims extend product launch timelines by 14-22 months versus wellness-classified competitors. Collegiate athletic programs in Texas and Florida drive substantial investment in Olympic lifting platforms and variable resistance systems.
Germany
Aging amateur triathletes and marathon runners pursue age-group competition through wearable-enabled self-coaching that reduces dependence on club memberships. GDPR's biometric data classification mandates explicit consent architectures and data residency requirements for platforms storing athlete physiological data. Sports science clusters in Munich and Cologne support centralized training centers with integrated performance analytics.
Brazil
Elite football academies concentrate institutional demand for sprint mechanics and neuromuscular coordination protocols. ANVISA streamlined medical device registration pathways in 2023, reducing market entry friction for recovery-focused wearables. São Paulo and Rio de Janeiro host dense networks of private academies facing regulatory scrutiny on training intensity limits for youth athletes.
India
Price-sensitive urban professionals in Bangalore and Mumbai seek flexibility through asynchronous online coaching around work schedules. The PLI scheme for wearable electronics manufacturing attracts component assembly operations, reducing landed costs for heart rate variability monitors. Private academies in Delhi-NCR expand specialized coaching infrastructure for cricket and badminton development programs.
Japan
Corporate wellness contracts increasingly specify hybrid training structures combining in-person assessment with remote program adjustment for executive populations. METI standards shape product development pathways for sensor-embedded equipment entering consumer markets. Sports technology clusters in Tokyo and Osaka develop force plate installations and 3D motion-capture suites for professional baseball and sumo training facilities.
Sports Training Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive boundaries unwinding between hardware-heavy wearable manufacturers and lean software analytics providers. WHOOP sustains premium positioning through vertically integrated biometric sensor production and subscription analytics, while Orreco differentiates by specializing in recovery science and menstrual cycle tracking for female athletes. Skillz navigates regulatory complexity by anchoring its platform in skill-based mobile gaming rather than traditional wagering. Dominant competitive moves include M&A activity consolidating sensor hardware with analytics platforms, and strategic partnerships embedding coaching algorithms into corporate wellness channels.
Within the integrated hardware-software tier, WHOOP and Orreco represent contrasting specialization strategies—one pursuing breadth across biometric verticals, the other drilling deep into female athlete physiology. Skillz occupies a distinct regulatory-arbitrage position, exemplifying how platform architecture choices preempt jurisdictional friction. Bolt6 and Sportable anchor the computer-vision movement analysis segment, where markerless camera systems displace wearable-dependent kinematic tracking in team sports environments. DraftKings and Athletes Unlimited sit within the content-engagement layer, though their strategic postures diverge toward wagering-adjacent entertainment versus league-operating models. Oracle, despite its enterprise software origins, represents the data infrastructure play—positioning cloud and analytics capabilities as substrate for sports training platform deployments.
| Leading Market Players |
|---|
| Oracle |
| DraftKings |
| WHOOP |
| Bolt6 |
| Athletes Unlimited |
| Sportable |
| Skillz |
| Owl AI |
| Orreco |
| Others |
Supply Flow & Price Mechanics
Long-term subscription contracts with collegiate athletic departments lock in both sensor hardware supply and predictable analytics revenue streams, insulating wearable manufacturers from spot-market volatility in rare earth magnet pricing while binding buyers to multi-year platform commitments.
Pricing Analysis
After-sales subscription tiers for AI-powered performance analytics drive lifetime value far beyond initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments by data granularity and coaching integration depth. Pricing pressure stems from open-source computer-vision alternatives eroding premium positioning. Collegiate programs show lowest price sensitivity; amateur endurance athletes absorb premium wearable pricing for self-coaching autonomy.
Supply Chain Analysis
China and Taiwan anchor precision sensor fabrication and microelectronics assembly for biometric wearables. Rare earth magnet supply draws from Chinese export quotas; semiconductor components feed from Taiwanese foundries. Single-source vulnerability concentrates in rare earth processing. Distribution runs through direct-to-consumer channels and institutional bulk contracts to university athletic departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports training sits in early-cycle expansion as NCAA governance reforms unlock institutional procurement budgets previously constrained by amateurism rules. Biometric sensor miniaturization extends physiological tracking from clinical settings to consumer applications.
For Market Incumbents: Consolidate sensor hardware production with analytics platform capabilities through selective acquisition of computer-vision specialists. Anchor defensive positioning in FDA 510(k) clearance moats that extend launch timelines for wellness-classified competitors. Prioritize backward integration into rare earth magnet sourcing to offset Chinese export quota volatility. For New Entrants and Emerging Players: Lead with recovery-science specialization for female athletes, where menstrual cycle tracking remains underdeveloped. Target Brazil's football academies through ANVISA's streamlined medical device registration pathways. Deploy hybrid training models combining asynchronous digital delivery with periodic in-person assessment. For Investors and Strategic Acquirers: Sports analytics platforms with pre-certified EU AI Act algorithmic recommendations present asymmetric upside. Long-term viability hinges on data residency architecture compliance across fragmented GDPR and emerging US state privacy frameworks. Monitor FDA clearance timelines as inflection indicator for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding coaching algorithms into corporate wellness channels expands addressable employer-sponsored populations. |
| Acquisition of Specialist Firm | Computer-vision movement analysis capabilities displace wearable-dependent tracking in team sports environments. |
| Regulatory Pre-Certification | EU AI Act risk classification creates compliance moats for European sports analytics platforms. |
| Geographic Expansion | ANVISA's streamlined pathways reduce friction for recovery-focused wearables targeting Brazilian football academies. |
| Product Launch | Continuous glucose monitors migrating to consumer sports applications open physiological tracking to amateur endurance athletes. |
Methodological Framework
The analysis maps wearable hardware, AI analytics platforms, and coaching service delivery, each validated through sports science directors, athletic department procurement officers, and platform engineering leads. Primary interviews with NCAA compliance administrators, Olympic committee funding officers, and wearable product managers combined with secondary validation against FDA 510(k) filings, FCC certification databases, and collegiate athletic budget disclosures. Bottom-up shipment modeling and top-down expenditure analysis triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. Segmentation dimensions modeled include training modality, delivery method, equipment technology intensity, and competitive tier. CAGRs derive from fitted growth curves applied to hardware replacement cycles and subscription renewal rates. Forecast inputs incorporate NCAA governance reform implementation pace and biometric sensor miniaturization adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained collegiate budget expansion or stable rare earth magnet supply would require recalibration. Forecasts reflect assumptions around regulatory clearance timelines and data privacy framework evolution. Recalibration cycles align with material shifts in NCAA compensation rules and FDA device classification precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Wearable Fitness Technology Market
Sports & Fitness
UAE Weight Loss Market
Sports & Fitness
Mountain Bicycle Cassette Market
Sports & Fitness
Surfing Boards Market
Sports & Fitness
Europe Sports Analytics Market
Sports & Fitness
Swim Watches Market
Sports & Fitness
United States Sports Nutrition Market
Sports & Fitness
Sports Sponsorship Market
Sports & Fitness
Elliptical Trainers Market
Sports & Fitness
Fitness Platforms for Disabled Market
Sports & Fitness
North America Home Fitness Equipment Market
Sports & Fitness
Sports Software Market
Sports & Fitness
Water Polo Suits Market
Sports & Fitness
Global Interactive Fitness Market
Sports & Fitness
North America Sporting Goods Market
Sports & Fitness
Europe Ski Gear and Equipment Market