
 Active Nutrition Market | 2026-2036
Active Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Active Nutrition Market Analysis
The gap between clinically validated premium formulations and basic commodity powders is realigning how manufacturers allocate R&D budgets and shelf space. Glanbia PLC leverages its dairy-derived protein supply chain to sustain cost advantages in whey isolate production. Nestlé S.A. competes through pediatric and medical nutrition crossover expertise that extends into active-lifestyle positioning. Herbalife International of America, Inc. anchors its model on direct-selling channel control in emerging middle-income demographics.
Active nutrition encompasses scientifically formulated ingestible products designed to enhance physical performance, recovery, or body composition, typically containing protein isolates, amino acid profiles, or targeted micronutrient blends manufactured through spray-drying, extrusion, or cold-pressed bar formation. These products serve commercial purposes spanning athletic performance optimization, weight management protocols, and convenience-driven meal replacement for time-constrained consumers. Protein powders occupy the most mature margin pool with established supply chains, while energy bars command premium positioning through clean-label ingredient narratives and portability advantages. Sports drinks differentiate through electrolyte-specific formulations and on-premise fitness center distribution exclusivity that limits direct retail competition.
FDA oversees structure-function claim substantiation and Good Manufacturing Practice compliance for U.S.-distributed active nutrition products, while EFSA governs health claim authorization across European jurisdictions with stricter evidentiary thresholds. ISO 17025 laboratory accreditation and NSF Certified for Sport protocols shape demand by filtering non-compliant products from institutional procurement channels. Stakeholders must monitor evolving protein source sustainability disclosures and novel food ingredient approval pathways as regulatory scrutiny intensifies on alternative protein substrates.
Market Dynamics
Clean-label verification protocols and protein provenance tracking are compressing margins for commodity-grade suppliers while rewarding manufacturers with captive dairy processing infrastructure and third-party certification depth.
Growth Catalysts
- ISO 17025 laboratory accreditation:Institutional procurement channels now mandate accredited testing for banned substance screening, filtering non-compliant products from collegiate and professional sports contracts.
- Fitness center distribution exclusivity:On-premise placement agreements with Equinox, Life Time, and boutique studio chains lock out retail competitors and secure recurring revenue streams.
- Spray-drying technology advancement:Cold-process microfiltration preserves bioactive whey fractions, enabling premium positioning for isolate products against commodity concentrates.
Market Restraints
- Whey protein concentrate input volatility:Dairy commodity price swings tied to New Zealand and EU milk production cycles compress gross margins for non-vertically integrated blenders.
- EFSA health claim evidentiary thresholds:Stricter substantiation requirements for muscle maintenance and recovery claims delay European product launches by 18-24 months versus FDA structure-function pathways.
- Plant protein amino acid incompleteness:Pea and rice isolates require expensive complementary blending to match leucine thresholds, raising formulation costs versus dairy-derived alternatives.
Strategic Opportunities
- Medical nutrition crossover applications:Sarcopenia prevention and post-surgical recovery protocols in aging populations extend addressable demand beyond traditional athletic segments.
- Direct-to-consumer subscription models:Personalized flavor and macronutrient configurations bypass retail slotting fees and capture lifetime value through recurring revenue.
- EU Green Deal protein sustainability disclosures:Early adoption of carbon-footprint labeling creates differentiation in European markets ahead of mandatory requirements.
Industry Challenges
- NSF Certified for Sport timeline compression:Third-party testing backlogs and documentation requirements delay product launches for 6-9 months, misaligning with seasonal demand peaks.
- Flavor masking R&D expenditure:Alternative protein substrates require escalating investment in bitter compound suppression and texture engineering to achieve palatability parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Nutrition Market |
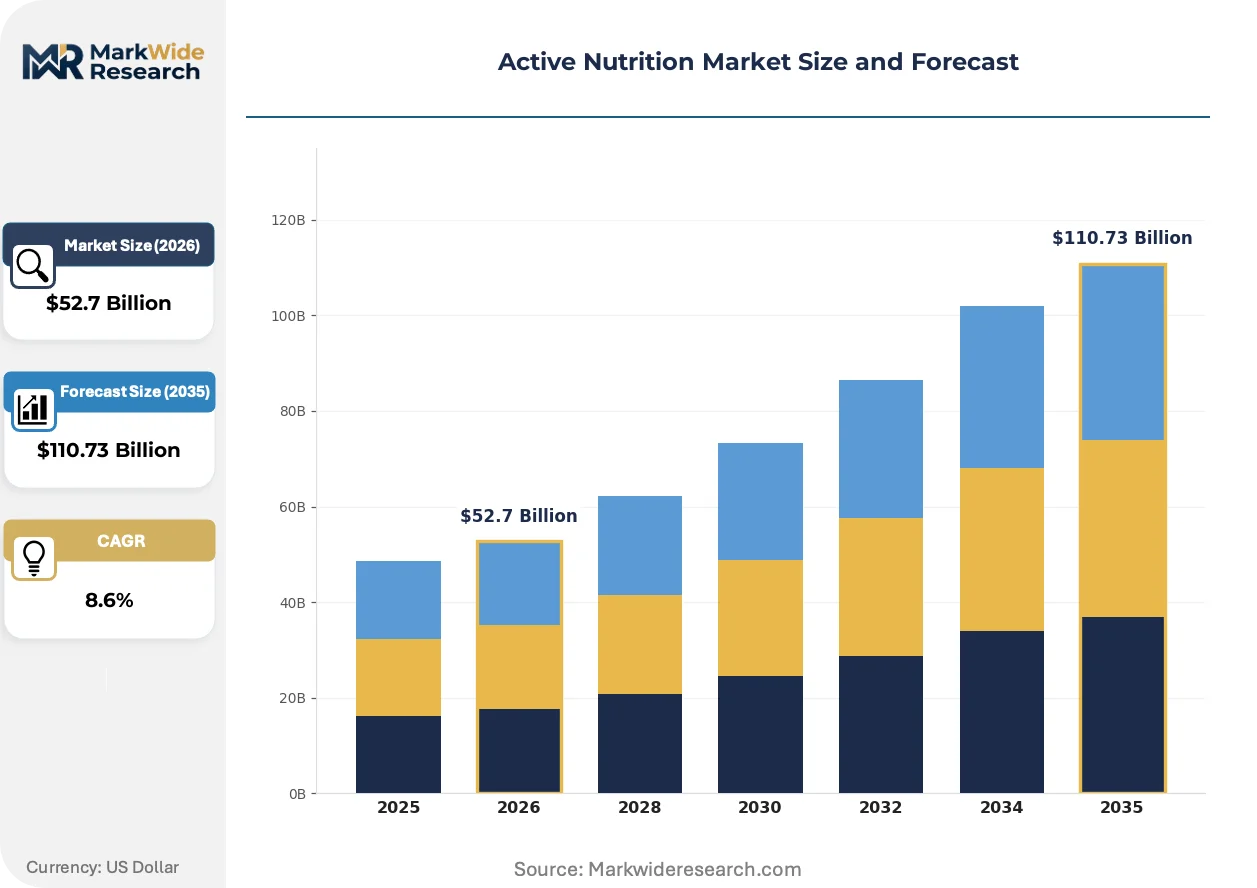
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Meal Replacements, Sports Drinks Application: Weight Management, Muscle Gain, Endurance Training, Post-Workout Recovery Customer Type: Athletes, Fitness Enthusiasts, Casual Users, Bodybuilders Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Fitness Centers |
| Companies Covered | Mondelez International, Inc., Herbalife International of America, Inc., Glanbia PLC, Kellanova, Amway Corp., Nestlé S.A., General Mills, Inc., GNC Holdings, LLC, PepsiCo Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Nutrition Market Emerging Trajectories
Precision fermentation and cellular agriculture are disrupting traditional protein supply chains, while regulatory frameworks race to accommodate novel ingredient pathways and sustainability disclosure mandates.
Precision fermentation-derived whey proteins are consolidating alternative protein development timelines by bypassing agricultural intermediaries entirely. Perfect Day and Remilk have scaled lactoglobulin production to commercial volumes, attracting formulation partnerships from CPG manufacturers seeking supply security. This technology is consolidating R&D budgets away from plant protein texture engineering toward bio-identical dairy replication.
EFSA novel food ingredient approval pathways are tightening evidentiary requirements for fermentation-derived and insect-based protein substrates. The 2023 updated guidance demands 90-day toxicology studies and allergen cross-reactivity assessments that add €2-4 million to regulatory submission costs. European startups are responding by sequencing U.S. market entry through GRAS self-determination before tackling European authorization.
Subscription-based personalized nutrition is displacing mass-market SKUs among affluent urban consumers with wearable-integrated metabolic tracking. Whoop and Oura ring data now directly inform protein timing and amino acid ratio recommendations through integrated app ecosystems. This shift is most visible in London, New York, and Singapore, where boutique subscription services command 40-60% premiums over retail equivalents.
Active Nutrition Market Segmentation
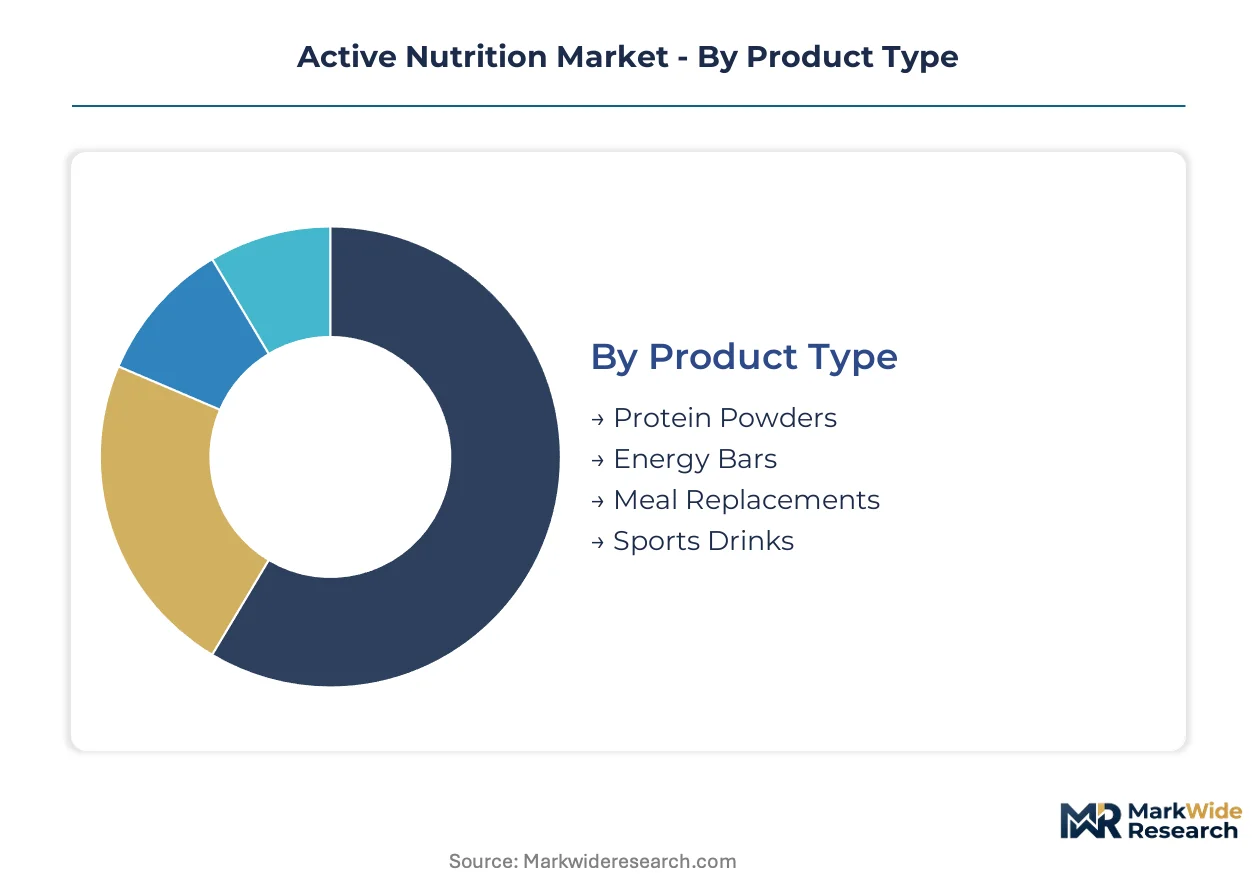
Active nutrition manufacturers calibrate formulation intensity and certification depth to match distinct usage contexts. Segment boundaries increasingly blur as protein powders enter medical nutrition protocols and energy bars displace conventional snacks in mainstream retail.
Product Type:
Standalone consumption formats dominate home-use scenarios, while embedded nutrition systems integrate into institutional foodservice and clinical recovery programs.
- Protein Powders:Whey isolates and micellar casein concentrates serve as the foundational substrate for personalized macro stacking. Demand clusters in United States home-gym setups and CrossFit affiliate boxes where scoop-based dosing precision matters.
- Energy Bars:Cold-pressed formulations with date-based binding and nut butter matrices command portability premiums. Clean-label positioning drives placement in Whole Foods Market and Erewhon retail sets across California and New York metro corridors.
- Meal Replacements:Complete amino acid profiles with vitamin premixes target time-compressed professionals seeking breakfast substitution.
- Sports Drinks:Electrolyte-specific osmolality tuning differentiates isotonic formulations for intra-workout hydration from hypotonic recovery variants.
Volume placements concentrate in Protein Powders; the faster expansion belongs to Energy Bars.
Application:
Cost tier stratification separates clinical-grade dosing precision from mass-market convenience positioning.
- Weight Management:Calorie-controlled portion systems with satiety-enhancing fiber matrices require FDA structure-function claim substantiation. Medical nutrition crossover into bariatric surgery pre-op protocols is gaining share fastest in Medicare-eligible demographics.
- Muscle Gain:Leucine-threshold formulations at 2.5-3g per serving target mTOR pathway activation for resistance training populations.
- Endurance Training:Carbohydrate-protein ratios at 3:1 or 4:1 optimize glycogen resynthesis for marathon and triathlon participants.
- Post-Workout Recovery:Tart cherry extract and curcumin anti-inflammatory adjuncts differentiate premium positioning from basic protein replenishment.
Revenue concentrates in Muscle Gain applications; steepest expansion trajectory sits with Post-Workout Recovery as aging populations adopt sarcopenia prevention protocols.
Customer Type:
Application maturity separates established competitive sets from emerging whitespace opportunities.
- Athletes:NSF Certified for Sport and Informed Sport third-party testing mandates govern collegiate and Olympic procurement channels. Institutional contracts with NCAA programs and USA Weightlifting concentrate demand in Colorado Springs and Indianapolis training centers.
- Fitness Enthusiasts:Peloton and Barry's Bootcamp membership cohorts drive subscription-based personalized nutrition adoption in urban coastal markets.
- Casual Users:Convenience-driven trial conversion from conventional snacks requires flavor engineering investment to mask alternative protein bitterness.
- Bodybuilders:Contest-prep segmentation demands ultra-low carbohydrate isolates with artificial sweetener systems for pre-stage leanness protocols.
Customer concentration sits with Fitness Enthusiasts; Casual Users represent the fastest-climbing penetration opportunity as gym culture normalizes among non-competitive populations.
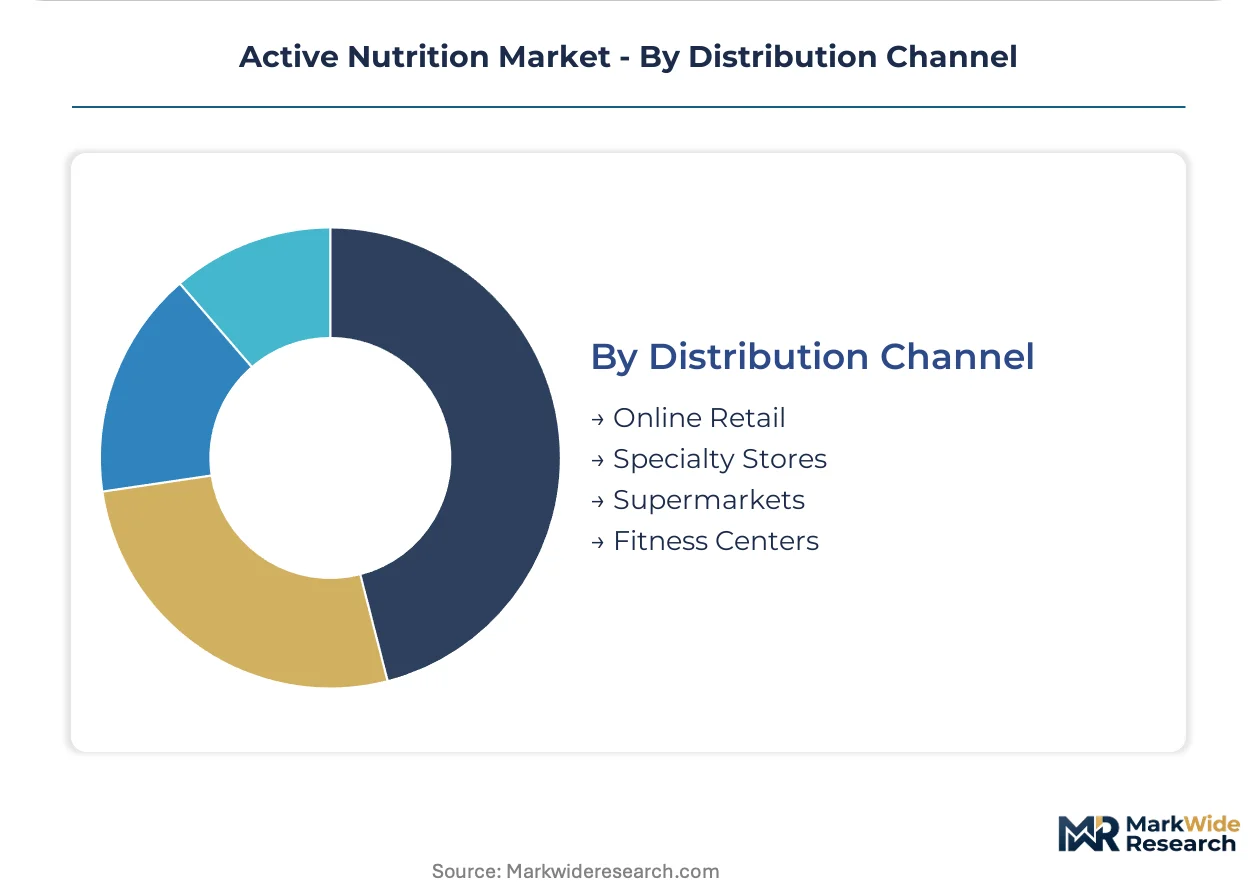
Distribution Channel:
Supply concentration in captive retail networks creates margin compression for undifferentiated wholesale placements.
- Online Retail:Direct-to-consumer subscription models bypass slotting fees and capture lifetime value through flavor personalization algorithms. Amazon and brand-owned Shopify storefronts dominate United States volume, while Zalando and Holland & Barrett control European e-commerce flow.
- Specialty Stores:GNC and Vitamin Shoppe footprint rationalization has shifted shelf space toward private-label exclusives and premium imported brands.
- Supermarkets:Mass-market velocity requirements favor multi-serve value formats over single-serve premium positioning.
- Fitness Centers:Equinox and Life Time on-premise exclusivity agreements lock out retail competitors and secure recurring revenue through member auto-replenishment.
Volume gravity centers on Online Retail; Fitness Centers command the steepest margin expansion as exclusivity agreements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American active nutrition demand through its concentration of CrossFit headquarters and altitude training facilities that drive protein formulation testing.
United States
Home-gym equipment purchases and boutique fitness membership growth sustain powder consumption across suburban markets. FDA structure-function claim pathways enable faster product launches than European alternatives. Indianapolis hosts NCAA training center procurement contracts that mandate NSF Certified for Sport verification.
Germany
Clean-label certification adoption and sustainability disclosure requirements reshape retail shelf standards. EFSA health claim substantiation rules delay muscle maintenance product introductions by 18-24 months. Munich and Cologne clusters concentrate dairy processing infrastructure for whey isolate production.
United Kingdom
Subscription-based personalized nutrition services penetrate affluent London and Manchester demographics with wearable-integrated recommendations. FSA enforcement of novel food regulations tightens scrutiny on fermentation-derived proteins. Reading and Cambridge biotech corridors attract precision fermentation startups seeking GRAS-equivalent pathways.
China
Fitness center expansion in tier-one cities and sports participation policy targets broaden addressable consumer bases. SAMR registration requirements for imported protein products create compliance bottlenecks at ports. Shanghai and Shenzhen manufacturing zones scale domestic contract production for regional brand supply.
Australia
Endurance sports participation rates and outdoor training culture sustain electrolyte-specific sports drink demand. TGA therapeutic claim regulations restrict recovery positioning for non-registered products. Melbourne and Sydney metropolitan areas concentrate specialty retail distribution and direct-to-consumer fulfillment infrastructure.
Active Nutrition Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and supply chain control dimensions. The vendor base stratifies between multinational nutrition conglomerates with dairy processing infrastructure and direct-selling specialists with captive distribution networks. Three archetypes dominate: vertically integrated dairy processors, medical nutrition crossover operators, and channel-controlled direct sellers. Competitive moves concentrate on exclusive fitness center placement agreements and precision fermentation technology licensing.
Within the dairy-derived protein tier, Glanbia PLC and Nestlé S.A. exemplify scale advantages through captive processing infrastructure and pediatric nutrition expertise extension. Herbalife International of America, Inc. occupies a distinct position anchoring direct-selling channel control in emerging middle-income demographics. These three represent divergent strategic paths: upstream supply security, medical crossover positioning, and distribution network ownership.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| Herbalife International of America, Inc. |
| Glanbia PLC |
| Kellanova |
| Amway Corp. |
| Nestlé S.A. |
| General Mills, Inc. |
| GNC Holdings, LLC |
| PepsiCo Inc |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty retailers have consolidated shelf space across United States sports nutrition channels, compressing slotting fee leverage for undifferentiated suppliers while rewarding brands with captive manufacturing infrastructure and certification depth that commands price premiums.
Pricing Analysis
Outcome-based pricing anchors premium tiers to verified performance claims, with NSF Certified for Sport and Informed Sport badges supporting 25-40% markups over uncertified equivalents. Three-tier pricing structure across premium isolate, standard concentrate, and economy blend levels separates leucine-threshold formulations from commodity powders. Cost compression in plant protein tiers is intensifying because amino acid complementary blending raises formulation expenses versus dairy alternatives. Casual Users exhibit highest price sensitivity, while institutional procurement through NCAA programs and Olympic training centers prioritizes certification grade over unit cost.
Supply Chain Analysis
Regional distribution centers in Indianapolis, Denver, and Los Angeles anchor hub-and-spoke fulfillment patterns for direct-to-consumer subscription services. Manufacturing concentrates in United States dairy belt corridors, New Zealand whey processing zones, and Netherlands precision fermentation clusters. Raw material flows draw from milk protein isolate feedstocks, leucine premix additives, and natural flavor masking compounds. Single-source vulnerability in New Zealand whey concentrate exposes margin volatility to Oceania milk production cycles. Distribution runs through Amazon fulfillment networks, Equinox on-premise exclusivity agreements, and GNC specialty retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA structure-function claim substantiation and NSF Certified for Sport verification protocols have erected compliance moats that filter commodity competitors from institutional procurement channels, concentrating margin capture among accredited manufacturers.
For Market Incumbents: Cement certification depth as a defensive barrier by accelerating ISO 17025 laboratory partnerships and securing exclusive fitness center placement agreements with Life Time and Equinox networks. Precision fermentation entrants from Perfect Day and Remilk threaten dairy-derived cost advantages, requiring backward integration into captive whey processing or technology licensing to preserve margin structure. For New Entrants and Emerging Players: Enter via medical nutrition crossover applications targeting sarcopenia prevention in Medicare-eligible demographics, where clinical-grade dosing precision commands premium positioning absent from saturated athletic segments. Subscription-based personalized nutrition in London and Singapore urban corridors offers the most penetrable whitespace, with wearable-integrated metabolic tracking enabling 40-60% pricing premiums over retail equivalents through flavor personalization algorithms. For Investors and Strategic Acquirers: NSF Certified for Sport backlog clearance acceleration is the leading indicator that regulatory capacity constraints are easing, enabling faster product launch velocity and inventory turnover improvement. Five-to-ten year viability favors precision fermentation technology licensors and vertically integrated dairy processors with captive supply security, with early-stage fermentation scale-up milestones signaling inflection toward bio-identical protein cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Perfect Day partnerships enable supply security bypassing agricultural commodity cycles entirely. |
| Fitness Center Exclusivity Agreements | Equinox and Life Time placements lock out retail competitors through member auto-replenishment. |
| ISO 17025 Laboratory Partnership | Accredited testing opens institutional procurement channels for collegiate and professional sports contracts. |
| Medical Nutrition Crossover Development | Sarcopenia prevention protocols extend addressable demand beyond traditional athletic user bases. |
| Direct-to-Consumer Subscription Launch | Personalized flavor algorithms bypass slotting fees and capture lifetime value through recurring revenue. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with sports nutrition formulators, NCAA procurement officers, GNC category buyers, and precision fermentation R&D directors. FDA structure-function claim databases, NSF Certified for Sport product registries, EFSA health claim submission logs, and Amazon category velocity reports provided validation benchmarks. Bottom-up volume modeling from SKU-level production data reconciled against top-down market sizing from dairy processor capacity disclosures.
Data-stream reconciliation across protein powder, energy bar, and sports drink segments enabled cross-format demand elasticity estimation throughout the projection horizon. Segmentation dimensions included product type, application purpose, customer archetype, and distribution channel, with regional regulatory cluster effects modeled separately. CAGRs derived from historical volume trajectories adjusted for certification penetration rates and fitness center membership growth correlations.
Revisions become necessary when EFSA novel food approval timelines extend beyond current baselines, precision fermentation scale-up accelerates cost parity timelines, or dairy commodity volatility exceeds historical bands. Forecasts reflect documented assumptions on regulatory pathway efficiency and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market