
 Europe Protein Based Sports Drinks Market | 2026-2036
Europe Protein Based Sports Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Protein Based Sports Drinks Market Insights
The Europe protein based sports drinks category is recalibrating around a widening split between premium functional formulations with clinical-grade protein dosing and commodity-tier products competing on price per serving. Glanbia PLC leverages its dairy protein supply chain dominance to anchor premium positioning across Northern European markets. Myprotein competes aggressively on direct-to-consumer channel control and flavor innovation velocity. PepsiCo Inc. sustains mass-market reach through supermarket and convenience store distribution networks that smaller brands cannot replicate.
Europe protein based sports drinks are formulated beverages delivering complete or partial protein profiles—typically whey, casein, or plant-derived isolates at concentrations ranging from ten to thirty grams per serving—designed to support muscle protein synthesis and recovery following physical exertion. Ready-to-drink formats lead volume sales due to on-the-go consumption patterns, while powder segments capture higher margin pools through subscription and bulk purchase economics. Online retail channels are displacing traditional health stores as the primary growth vector, particularly among fitness enthusiasts and casual users seeking personalized nutrition stacks.
EFSA health claim assessments, EU Food Information to Consumers Regulation labeling mandates, and national food safety authority oversight across Germany, France, and the United Kingdom collectively elevate compliance costs while filtering out unsubstantiated performance claims. These frameworks reward companies with invested clinical validation infrastructure and penalize entrants relying on generic marketing. Stakeholders must monitor evolving novel protein source approvals and sustainability-linked procurement standards as the next determinants of competitive access.
Market Dynamics
EFSA novel food approval timelines and EU health claim substantiation requirements are compressing formulation pipelines while rewarding brands with invested clinical infrastructure across European protein based sports drinks manufacturing.
Growth Catalysts
- Fitness enthusiast penetration:Gym membership density in Germany and the Netherlands exceeds continental averages, creating concentrated demand for post-workout recovery formulations with elevated protein dosing.
- EFSA health claim frameworks:Approved protein-related claims under Regulation (EC) No 1924/2006 enable compliant brands to differentiate on verified muscle maintenance messaging versus generic performance marketing.
- Plant protein processing advances:Fermentation-derived and precision-extracted pea and fava isolates achieve amino acid completeness rivaling dairy derivatives, expanding addressable vegan and flexitarian consumer pools.
Market Restraints
- Whey protein concentrate volatility:Dairy input costs fluctuate with European milk quota abolition aftereffects and seasonal production swings, compressing margin stability for whey-dependent formulations.
- Supply concentration in Irish-Dutch dairy processing:A limited corridor of specialized fractionation facilities controls premium protein isolate output, creating bottleneck vulnerability for brands without captive supply arrangements.
- EU Food Information to Consumers Regulation:Mandatory front-of-pack nutritional labeling and allergen disclosure requirements elevate packaging complexity and compliance audit costs for multi-SKU portfolios.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit sub-30% sports nutrition retail coverage versus Western European benchmarks, presenting first-mover expansion potential for direct-to-consumer brands with localized flavor profiles.
- EU Green Deal procurement alignment:Sustainability-linked public and institutional purchasing criteria reward brands with verified regenerative agriculture sourcing and carbon-labeled supply chains.
- Hybrid retail-digital convergence:Click-and-collect integration with pharmacy and fitness center networks merges impulse accessibility with subscription economics, capturing omnichannel shoppers in France and Italy.
Industry Challenges
- Novel protein source approval timelines:EFSA safety assessments for emerging ingredients like precision-fermented proteins or insect-derived isolates extend 18-24 months, delaying product launch windows.
- Cross-border formulation standardization:Divergent national implementations of EU food law create packaging and labeling fragmentation, forcing redundant SKU adaptations for Germany, France, and United Kingdom markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Protein Based Sports Drinks Market |
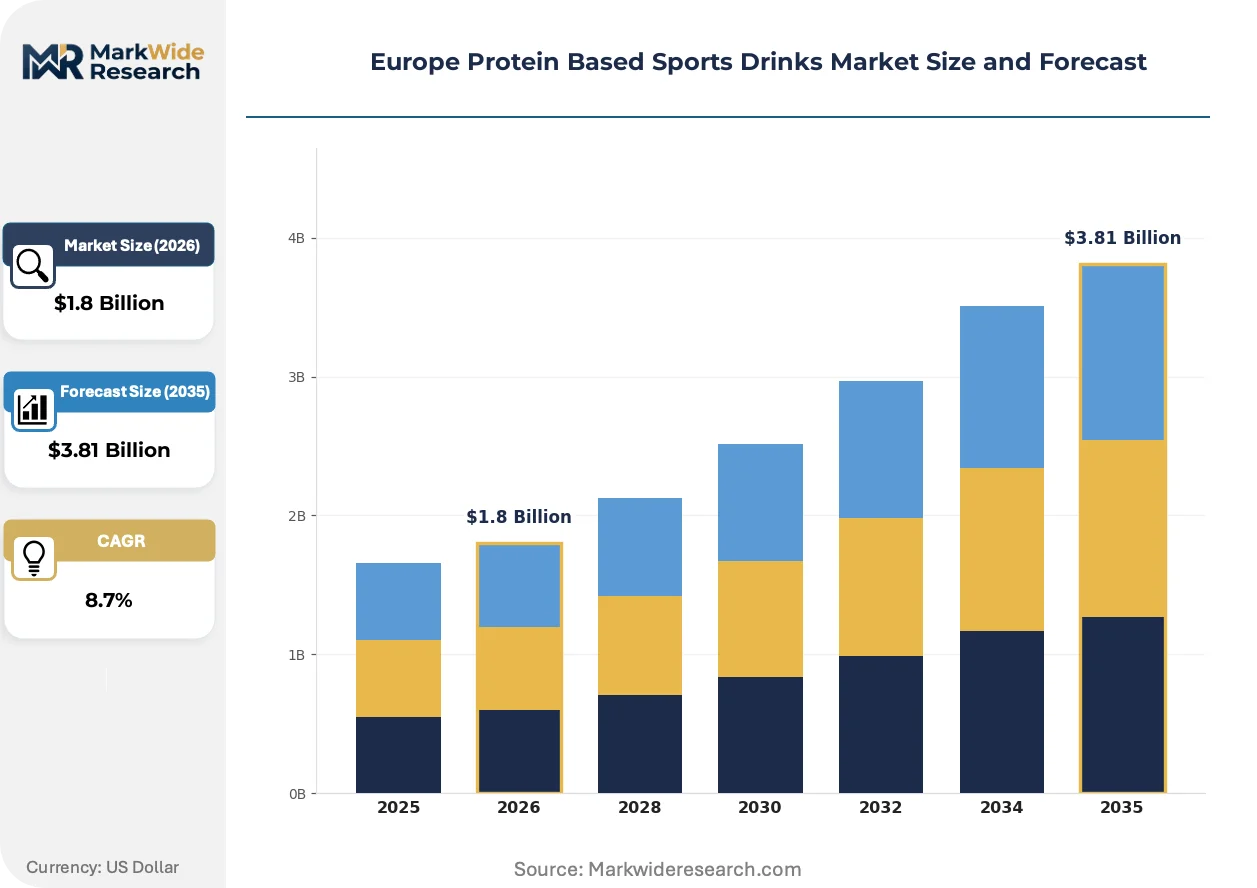
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
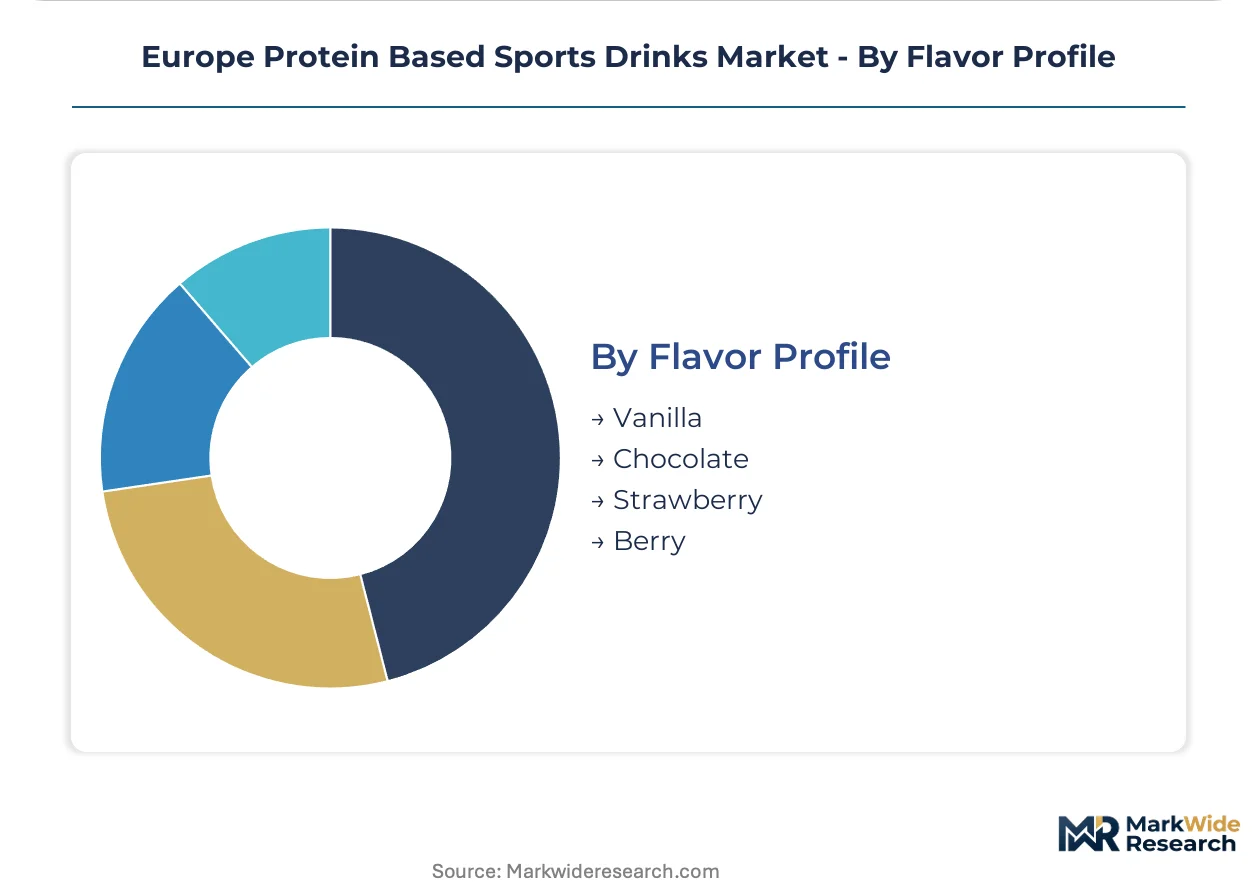
| Segmentation | Product Type: Ready-to-Drink, Powder, Concentrate, Gel Distribution Channel: Online Retail, Supermarkets, Health Stores, Convenience Stores Consumer Type: Fitness Enthusiasts, Athletes, Casual Users, Bodybuilders Flavor Profile: Vanilla, Chocolate, Strawberry, Berry |
| Companies Covered | Glanbia PLC, PepsiCo Inc., Nestlé S.A., Myprotein, THG plc, Abbott Laboratories, The Vita Coco Company Inc., Farmers Co-operative Dairy Limited, Protein2o Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Protein Based Sports Drinks Market Trends and Innovations
European protein based sports drinks are bifurcating between clinical-grade precision nutrition and mass-market convenience, with technology and regulatory forces compressing the viable middle tier.
Precision fermentation-derived proteins are achieving commercial scale in European manufacturing facilities. Specialty ingredient suppliers in Denmark and the Netherlands are commissioning capacity for whey-identical proteins produced without animal agriculture. This capability is integrating into premium brand positioning strategies that command shelf space separation from commodity dairy-derived alternatives.
EFSA's evolving guidance on novel food safety assessments is tightening substantiation thresholds for bioactive peptide claims. Manufacturers must now submit comprehensive toxicological dossiers and human intervention data before marketing recovery-enhancing formulations. Northern European markets with established clinical research infrastructure are adapting faster than Southern European competitors with weaker in-house validation capabilities.
Subscription-based personalized nutrition stacks are displacing single-SKU purchases among committed fitness enthusiasts. Digital platforms in Germany and the United Kingdom aggregate training data, dietary logs, and biomarker inputs to generate algorithm-matched protein delivery schedules. This behavioral shift concentrates lifetime value with vertically integrated brands while eroding traditional retail channel loyalty.
Europe Protein Based Sports Drinks Market Segmentation
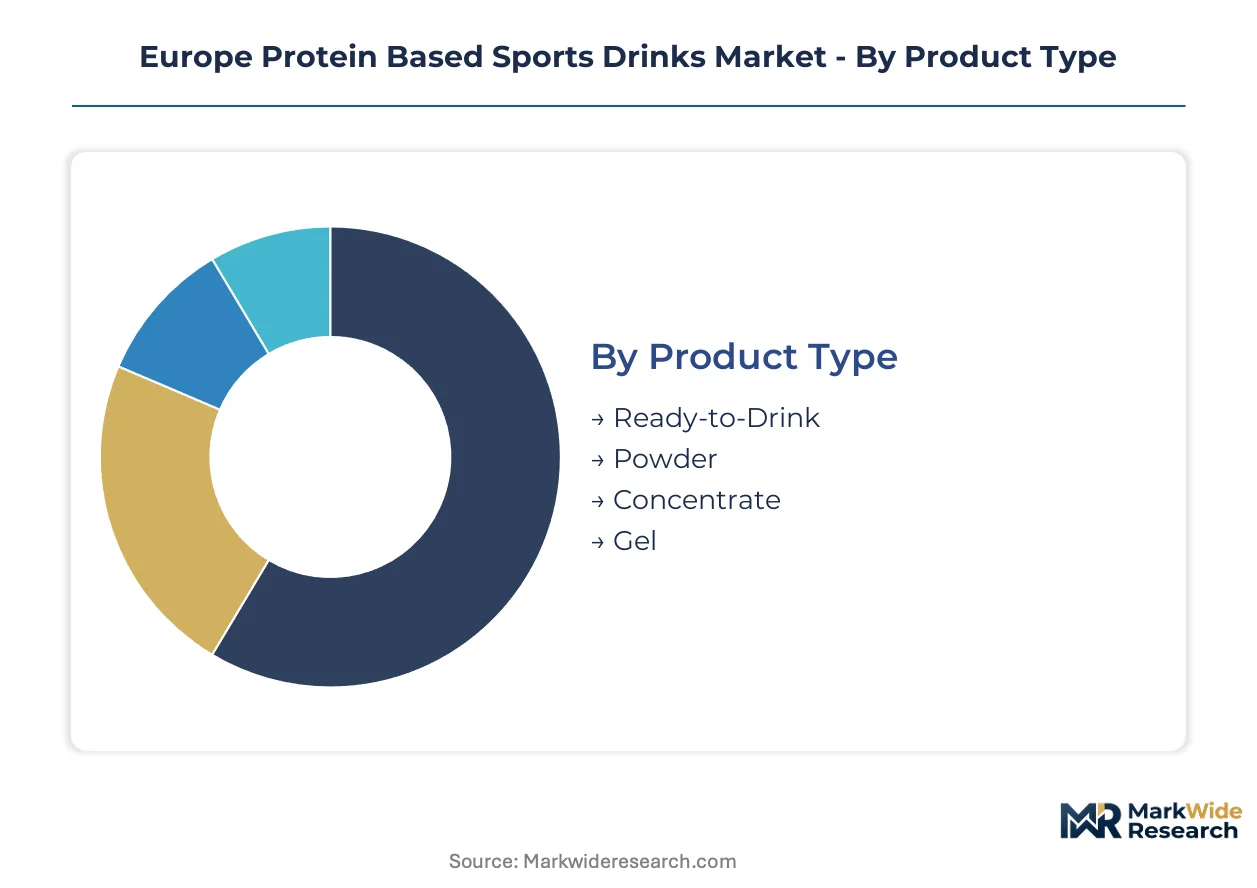
Segmentation in European protein sports drinks reveals how supply chain configuration and consumption context shape competitive positioning. Manufacturers must align formulation, packaging, and channel strategy to distinct usage moments and buyer sophistication levels.
Product Type:
Supply concentration in liquid manufacturing infrastructure tilts competitive advantage toward brands with captive bottling capacity or long-term co-manufacturing contracts.
- Ready-to-Drink:Pre-mixed beverages in shelf-stable or refrigerated formats, typically delivering 20-30g protein per 330-500ml serving. Demand concentrates in German gym chains and Dutch fitness center vending networks, where grab-and-go recovery protocols dominate post-workout behavior. EFSA labeling compliance for ready-to-drink formats elevates packaging costs versus powder alternatives.
- Powder:Dry protein isolates and concentrates requiring consumer reconstitution, offering bulk purchase economics and flavor customization. French and United Kingdom direct-to-consumer subscription platforms are displacing retail for committed users seeking personalized dosing stacks. Powder segments capture higher lifetime value through auto-replenishment models.
- Concentrate:Hyper-concentrated liquid or semi-liquid formulations requiring dilution, occupying niche positioning for travel and field-based athletic use.
- Gel:Viscous protein delivery systems in sachet or pouch formats, targeting endurance athletes with rapid gastric emptying requirements during competition.
Today's leader: Ready-to-Drink. Tomorrow's challenger: Powder.
Distribution Channel:
Margin compression in traditional retail is accelerating channel diversification toward digital-native acquisition models.
- Online Retail:Direct-to-consumer platforms, marketplace aggregators, and subscription services. German fitness enthusiasts and United Kingdom casual users drive the steepest expansion trajectory here, drawn to algorithmic personalization and bulk pricing unavailable in physical retail.
- Supermarkets:Mass-market shelf placement reaching occasional users and family purchasers. French and Italian supermarket chains are expanding sports nutrition aisles, though space allocation favors established brands with trade marketing budgets.
- Health Stores:Specialized retailers with trained staff and premium positioning. Netherlands and Belgium health store networks retain loyalty among supplement-sophisticated consumers seeking clinical-grade formulations.
- Convenience Stores:Impulse-oriented locations capturing unplanned recovery purchases near gyms and transit hubs.
Online Retail commands growth investment; Health Stores defend margin extraction.
Consumer Type:
Application intensity determines protein dosing requirements and willingness to pay for clinical validation.
- Fitness Enthusiasts:Regular gym attendees pursuing body composition goals through structured training. German metropolitan areas show highest penetration, with demand clustering around 20-25g post-workout servings and flavor rotation preferences.
- Athletes:Competitive and semi-professional performers with periodized nutrition protocols. United Kingdom team sports and Dutch cycling federations drive institutional procurement with batch-tested certification requirements.
- Casual Users:Health-conscious individuals incorporating protein drinks as meal replacements or wellness rituals.
- Bodybuilders:High-volume consumers prioritizing protein density per serving and cost-per-gram economics over convenience.
Fitness Enthusiasts anchor volume scale; Athletes command premium pricing.
Flavor Profile:
Regional taste preferences and clean-label expectations are reshaping formulation pipelines across Northern and Southern Europe.
- Vanilla:Neutral base flavor with highest blending versatility for smoothie customization. German and Scandinavian markets show persistent preference for vanilla as a staple SKU.
- Chocolate:Indulgence-positioned variant bridging sports nutrition and confectionery expectations. French consumers demonstrate strongest chocolate preference, influencing formulation sweetness profiles.
- Strawberry:Fruit-forward positioning targeting female demographic expansion and yogurt-alternative occasions.
- Berry:Antioxidant-associated flavor cluster with natural colorant compatibility for clean-label positioning.
Vanilla and Chocolate defend baseline SKUs; Berry formulations gain share fastest among flexitarian entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's gym penetration rates exceed French benchmarks by a significant margin, while the United Kingdom channels sports nutrition demand through distinct direct-to-consumer platforms. These divergent demand patterns shape how protein sports drinks circulate across the continent.
Germany
Fitness center density in North Rhine-Westphalia and Bavaria drives concentrated post-workout consumption, with metropolitan gym chains stocking refrigerated ready-to-drink formats. The Federal Ministry of Food and Agriculture enforces strict novel food notification requirements for emerging protein sources. Cologne and Düsseldorf host specialized dairy fractionation facilities that supply isolate inputs to regional bottling operations.
United Kingdom
Subscription-based personalized nutrition platforms capture committed fitness enthusiasts seeking algorithm-matched protein dosing schedules. The Food Standards Agency coordinates with Trading Standards on health claim substantiation for muscle maintenance messaging. London and Manchester anchor direct-to-consumer fulfillment networks that displace traditional health store channels.
France
Supermarket sports nutrition aisle expansion reaches occasional users and family purchasers in Île-de-France and Auvergne-Rhône-Alpes. ANSM oversees borderline product classifications between food supplements and beverages. Lyon-based flavor houses supply chocolate and vanilla formulations calibrated to French sweetness preferences.
Netherlands
Cycling federation procurement and fitness center vending networks sustain institutional demand for batch-tested formulations. The Netherlands Food and Consumer Product Safety Authority enforces EU Food Information to Consumers Regulation labeling mandates. Specialized health store networks in Amsterdam and Rotterdam retain loyalty among supplement-sophisticated consumers.
Poland
Sub-30% sports nutrition retail coverage relative to Western European benchmarks creates first-mover expansion potential for localized direct-to-consumer entrants. The Chief Sanitary Inspectorate implements national food safety oversight aligned with EFSA frameworks. Warsaw and Krakow emerging fitness center construction indicates demand infrastructure development.
Europe Protein Based Sports Drinks Market Competitive Landscape
Top-tier vendors anchor premium functional positioning, while mid-scale competitors compete on direct-to-consumer channel control and flavor velocity. The market structure consolidates around dairy protein supply chain dominance, direct-to-consumer platform ownership, and mass-market distribution reach. Three archetypes predominate: integrated dairy processors with captive isolate output, digital-native nutrition brands with subscription economics, and multinational beverage conglomerates with supermarket and convenience store penetration. Competitive moves center on EFSA health claim validation investments and hybrid retail-digital channel convergence.
Within the integrated processing tier, Glanbia PLC and Nestlé S.A. exemplify supply chain anchored positioning. Myprotein occupies the digital-native archetype with direct-to-consumer platform control. PepsiCo Inc. represents mass-market reach through established retail networks that smaller competitors cannot replicate.
| Leading Market Players |
|---|
| Glanbia PLC |
| PepsiCo Inc. |
| Nestlé S.A. |
| Myprotein |
| THG plc |
| Abbott Laboratories |
| The Vita Coco Company Inc. |
| Farmers Co-operative Dairy Limited |
| Protein2o Inc. |
| Others |
Pricing and Supply Chain Analysis
Fitness enthusiasts in Germany and the Netherlands anchor demand concentration that rewards subscription-based pricing models over transactional retail. This buyer archetype's preference for personalized nutrition stacks creates pricing power for brands with captive digital platforms, while squeezing commodity-tier competitors dependent on supermarket shelf placement.
Pricing Analysis
Bundled subscription services commanding monthly auto-replenishment contracts separate premium pricing from unbundled single-unit supermarket sales. Three-tier pricing structure across premium clinical-grade, standard lifestyle, and economy mass-market levels tracks protein dosing precision and EFSA claim validation investment. Pricing pressure stems from whey protein concentrate input volatility following European milk quota reforms, compressing margins for dairy-dependent formulations. Casual users purchasing through French and Italian supermarket channels exhibit highest price sensitivity, while United Kingdom athletes seeking batch-tested certification accept substantial premiums.
Supply Chain Analysis
Specialized dairy fractionation workforce availability in Ireland, the Netherlands, and Germany anchors European protein isolate manufacturing. Raw material dependencies center on whey and casein streams from Irish-Dutch processing corridors, alongside emerging fermentation-derived inputs from Danish and Dutch biotechnology facilities. Single-source vulnerability concentrates in a limited corridor of premium isolate fractionation plants, creating bottleneck exposure for brands lacking captive supply arrangements. Distribution runs through hybrid retail-digital convergence models, with click-and-collect pharmacy networks and direct-to-consumer fulfillment centers displacing traditional health store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European protein sports drinks rests on fermentation-derived protein cost curves declining against traditional dairy inputs, alongside fitness enthusiasts trading up to precision-dosed subscription tiers.
For Market Incumbents: Extend EFSA health claim validation infrastructure to defend premium positioning against emerging precision-fermentation entrants. Deepen backward integration into Irish-Dutch dairy fractionation capacity or commission captive fermentation facilities in Denmark to secure isolate supply. Channel control through pharmacy network partnerships in France and Italy preserves impulse accessibility against digital-native competitors.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms in Poland and Romania offer the most penetrable white-space, where sub-30% sports nutrition retail coverage lags Western European benchmarks. Localized flavor profiles calibrated to Eastern European taste preferences, combined with algorithm-matched dosing schedules, bypass entrenched supermarket distribution advantages. Target fitness center vending procurement in Warsaw and Krakow emerging gym infrastructure.
For Investors and Strategic Acquirers: Beverage conglomerates with mass-market distribution networks are the most active acquirer in this space, seeking digital-native nutrition brands to fill premium portfolio gaps. Long-term viability favors targets with vertical integration into fermentation-derived protein supply or established EFSA novel food approval dossiers. Watch EFSA guidance evolution on precision-fermented protein safety assessments as the inflection signal for manufacturing technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Validation Investment | Enables verified muscle maintenance messaging under Regulation (EC) No 1924/2006, differentiating premium formulations from generic competitors. |
| Precision Fermentation Capacity Commissioning | Danish and Dutch biotechnology facilities achieve whey-identical proteins without animal agriculture, commanding shelf separation from commodity dairy. |
| Direct-to-Consumer Platform Launch | German and United Kingdom algorithmic personalization aggregates training data and biomarker inputs to capture lifetime value from fitness enthusiasts. |
| Eastern European Geographic Expansion | Poland and Romania's emerging gym infrastructure and sub-30% retail penetration reward first-mover subscription brands with localized flavor development. |
| Hybrid Retail-Digital Convergence | Click-and-collect integration with French pharmacy and Italian fitness center networks merges impulse accessibility with subscription economics. |
Research Methodology
Multiple input streams — executive interviews with sports nutrition brand managers, procurement discussions with gym chain operators, and regulatory consultations with EFSA affairs specialists — were reconciled against secondary validation from EU Food Information to Consumers Regulation filings, EFSA novel food approval databases, and national trade data from German, French, and United Kingdom customs authorities. Bottom-up SKU-level volume aggregation and top-down category spend estimates were triangulated to constrain forecast variance.
Cross-referencing historical consumption patterns against panel input from category buyers at major European retailers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, consumer application intensity, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for EFSA approval timeline impacts and protein source substitution elasticity. Forecast inputs incorporated gym membership density trajectories and fermentation capacity buildout announcements.
The model assumes a particular technology adoption path; alternative pathways for precision-fermented protein scaling would alter the outlook if EFSA safety assessment timelines compress or dairy input volatility subsides. Forecasts reflect documented assumptions about fitness enthusiast penetration rates and subscription platform adoption curves. Material deviation in EFSA novel food approval velocity or EU Green Deal procurement alignment triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
ACF Supplements Market