
 Europe Weight Management Supplement Market | 2026-2036
Europe Weight Management Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Weight Management Supplement Market Foresight
The Europe weight management supplement category is recalibrating around a widening split between premium clinically-validated formulations and commodity-priced generic alternatives. Herbalife Nutrition leverages its direct-selling network to sustain high-touch customer relationships across Southern Europe. Glanbia PLC anchors its position through backward integration into whey protein isolate production. Nestlé Health Science differentiates via science-backed medical positioning in pharmacy channels.
Weight management supplements comprise orally consumed products containing bioactive compounds—protein isolates, thermogenic agents, fiber matrices, or micronutrient blends—formulated to modulate energy balance, satiety signaling, or substrate metabolism. Protein supplements dominate current value generation due to entrenched gym culture and sports nutrition crossover, while meal replacements capture accelerating interest from time-constrained urban professionals seeking portion-controlled solutions. Fat burners occupy a mature, margin-compressed niche where regulatory scrutiny of stimulant content intensifies.
EFSA nutrition and health claims assessments, EU MDR borderline determinations for medical food positioning, and national pharmacy regulator classifications collectively constrain permissible efficacy messaging and channel access. The EU Green Deal packaging requirements and CSRD sustainability disclosures add compliance layers to formulation and supply chain decisions. Stakeholders must monitor evolving EFSA opinions on novel ingredients and pre-empt stricter member-state advertising codes before committing to regional launch strategies.
Market Dynamics
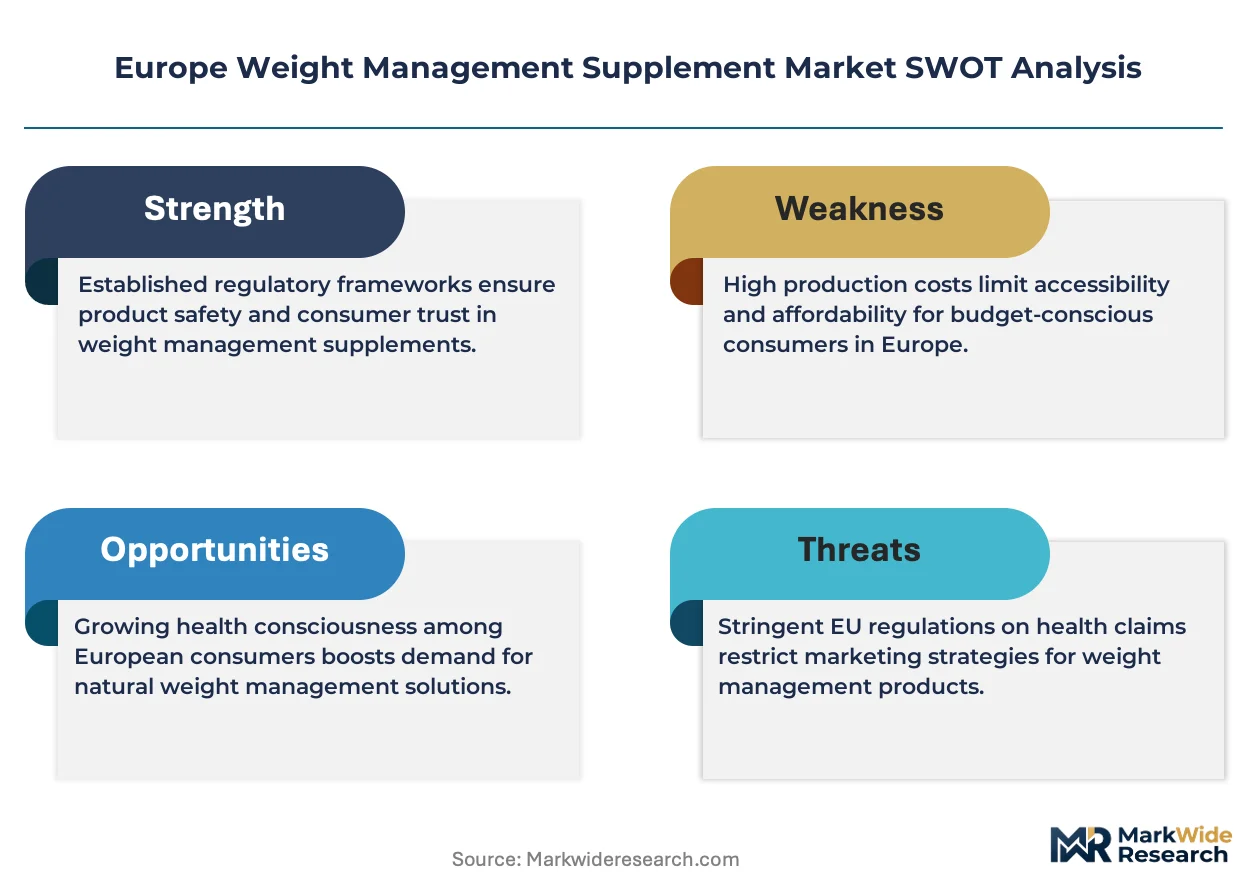
The EU's Nutrition and Health Claims Regulation enforcement is bifurcating the competitive landscape between EFSA-validated premium formulations and unverified commodity products, forcing brand architecture and channel decisions before product launch.
Growth Catalysts
- Fitness culture penetration:Amateur athletes and recreational gym-goers across Spain and Italy are expanding the addressable base beyond traditional dieters, creating volume pull for protein isolates and meal replacements.
- EFSA positive opinions:Approved health claims for specific fiber matrices and protein satiety effects are unlocking pharmacy channel access and premium pricing power for compliant formulations.
- Urban time compression:Time-constrained professionals in Paris, London, and Berlin are adopting portion-controlled meal replacements as substitutes for prepared food, driving repeat purchase frequency.
Market Restraints
- Whey protein input volatility:Dairy commodity price swings and concentrated Irish-Dutch processing capacity create margin pressure for brands without backward integration into isolate production.
- EFSA claim rejection backlog:Pending scientific opinions on novel botanical thermogenics are freezing marketing language and delaying launches for ingredient suppliers.
- Generic substitution:Unbranded white-label protein powders and fiber supplements are capturing price-sensitive demand through e-commerce direct-to-consumer channels.
Strategic Opportunities
- Poland and Romania expansion:Underpenetrated pharmacy and fitness channels in Eastern European markets offer first-mover positioning before regulatory harmonization fully converges.
- CSRD sustainability disclosure:Early compliance with EU Green Deal packaging requirements and supply chain transparency mandates is creating differentiation among institutional buyers.
- Medical food borderline positioning:EU MDR determinations for metabolic syndrome adjacency are opening clinician-recommended segments for brands with clinical trial investment.
Industry Challenges
- Formulation-to-claim synchronization:R&D teams must align novel ingredient development with EFSA opinion timelines, compressing product development cycles and increasing regulatory risk capital.
- Cross-border e-commerce compliance:Divergent national advertising codes and pharmacy classifications create friction for unified European digital distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Weight Management Supplement Market |
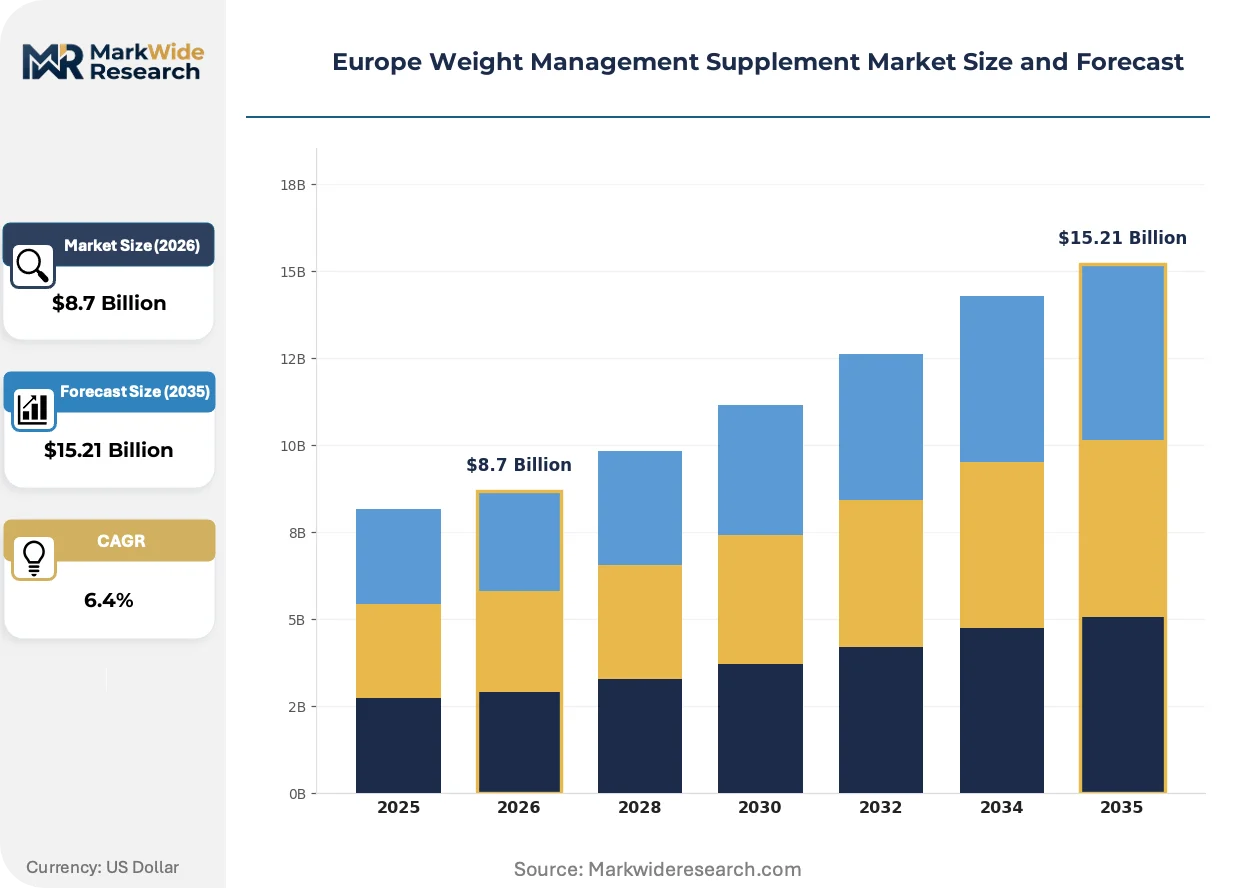
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Fat Burners, Meal Replacements, Appetite Suppressants Formulation: Powder, Capsule, Liquid, Bar Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Target Customer: Health Conscious Individuals, Athletes, Weight Loss Seekers, Seniors |
| Companies Covered | Herbalife Nutrition, Glanbia PLC, Nestlé Health Science, Amway Corp., General Nutrition Centers, Evlution Nutrition LLC, Bayer AG, Huel, YFood, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Weight Management Supplement Market Shifts & Advancements
Protein sourcing transparency and microbiome-targeted formulations are displacing legacy thermogenic positioning, while digital coaching integration is redefining the value proposition beyond the physical product.
Plant-protein blending technology is overtaking single-source whey dominance in sports nutrition formulations. German and Dutch formulators are adopting precision fermentation-derived proteins and optimized pea-rice amino acid profiles to match whey biological value. This shift is compressing reliance on dairy commodity cycles while opening vegan-certified premium segments.
EFSA's evolving guidance on gut health claims is tightening permissible messaging around microbiome modulation. Brands must now substantiate specific strain-function relationships rather than general digestive wellness positioning. French and Italian regulators are enforcing these standards most strictly, redirecting innovation investment toward clinical endpoint trials.
Subscription-based personalized nutrition programs are displacing transactional supplement purchases among urban professionals. Digital platforms combining biomarker testing, AI-generated meal plans, and auto-fulfilled product shipments are capturing lifetime value. This model concentrates adoption in London, Amsterdam, and Stockholm where digital health integration is highest.
Europe Weight Management Supplement Market Segmentation
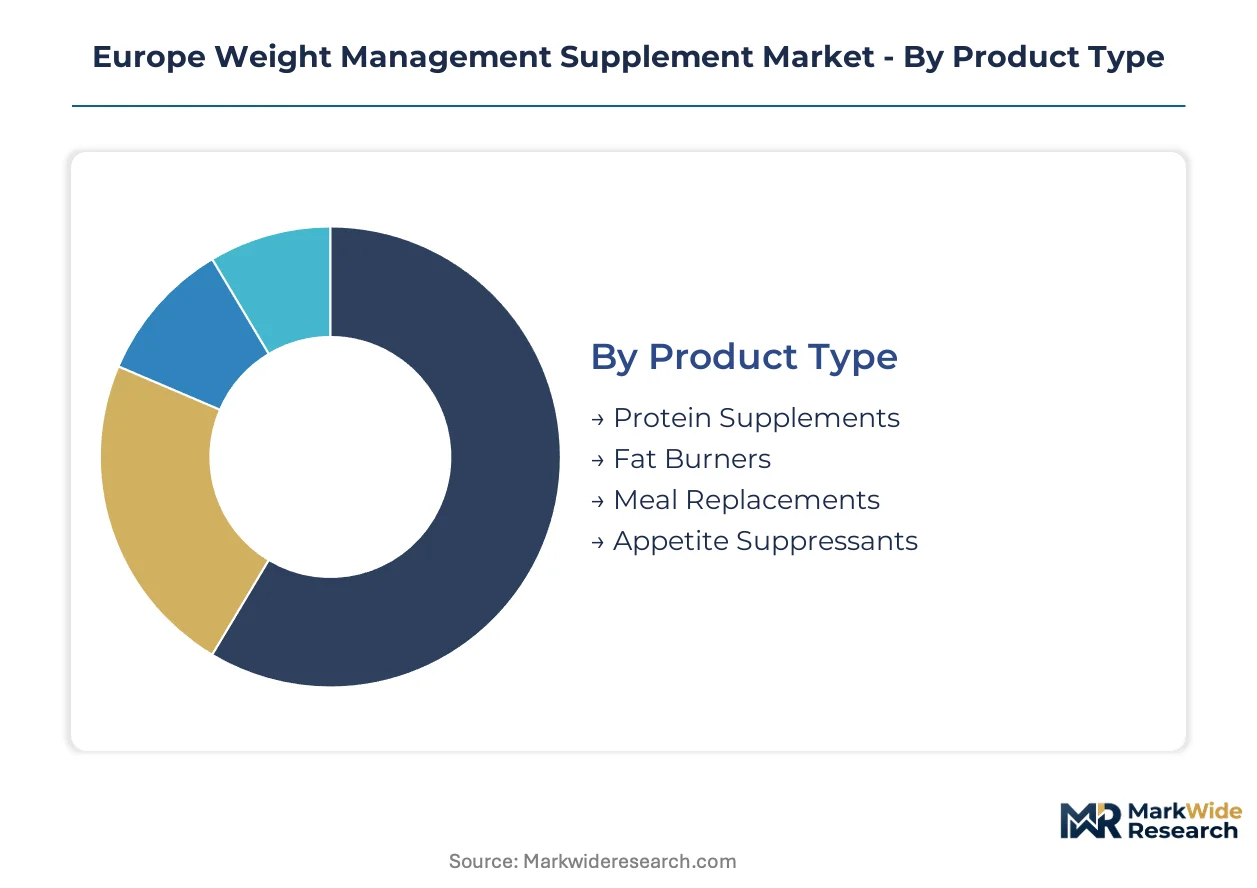
Europe's weight management supplement segmentation reflects divergent paths between gym-culture protein demand and pharmacy-positioned metabolic solutions. Product architecture, channel access, and customer lifecycle positioning determine margin capture across the region's fragmented regulatory landscape.
Product Type:
Volume concentrates in protein isolates while premium pricing accrues to clinically-substantiated meal replacements, bifurcating R&D investment between commodity scale and regulatory validation.
- Protein Supplements:Whey and plant-protein isolates formulated for muscle protein synthesis and satiety signaling. Demand clusters in German and Spanish gym cultures where amateur athletes drive repeat purchase cycles; EFSA-approved satiety claims unlock pharmacy tier pricing for compliant isolates.
- Meal Replacements:Micronutrient-fortified portion-controlled formulations delivering complete nutrition in caloric deficit. Paris and London professionals substitute these for prepared food during compressed work schedules; regulatory positioning as medical foods adjacent to metabolic syndrome management commands clinician recommendation channels.
- Fat Burners:Thermogenic and lipolytic agent blends facing intensified EFSA scrutiny on stimulant content and efficacy substantiation.
- Appetite Suppressants:Fiber matrices and botanical compounds modulating ghrelin signaling and gastric emptying rates.
Today's leader: Protein Supplements. Tomorrow's challenger: Meal Replacements.
Formulation:
Convenience-driven format preferences reshape manufacturing asset allocation and packaging compliance costs under EU Green Deal mandates.
- Powder:Bulk protein and meal replacement concentrates offering dose flexibility and cost efficiency. German and Dutch processing facilities dominate isolate production; sustainability disclosures on dairy sourcing and plant-protein carbon intensity increasingly influence B2B procurement decisions.
- Capsule:Precision-dosed thermogenics and appetite modulators requiring minimal excipient load. Italian and French regulators enforce strict stability testing for botanical actives; capsule format facilitates pharmacy shelf placement and clinician sampling programs.
- Liquid:Ready-to-drink protein and meal replacement solutions capturing on-the-go consumption occasions.
- Bar:Shelf-stable solid formats bridging snack replacement and sports nutrition use cases.
Format economics favor powder at volume; convenience premiums sustain liquid and bar expansion.
Distribution Channel:
Channel selection determines permissible efficacy messaging and customer relationship depth across Europe's divergent national advertising codes.
- Online Retail:Direct-to-consumer platforms enabling subscription models and personalized nutrition integration. Nordic urban markets show highest digital health adoption; cross-border e-commerce friction from divergent pharmacy classifications complicates unified European strategies.
- Pharmacies:Clinician-adjacent positioning for EFSA-validated formulations with approved health claims. French and Italian enforcement of medical food borderline determinations under EU MDR creates gatekeeper dynamics; pharmacy access commands 40-60% price premiums over mass retail equivalents.
- Supermarkets:Mass-market protein and meal replacement placement competing with private label alternatives.
- Health Stores:Specialty retail catering to enthusiast segments seeking novel ingredients and vegan certifications.
Pharmacy channel deepening in Western Europe; online retail capturing Eastern European expansion.
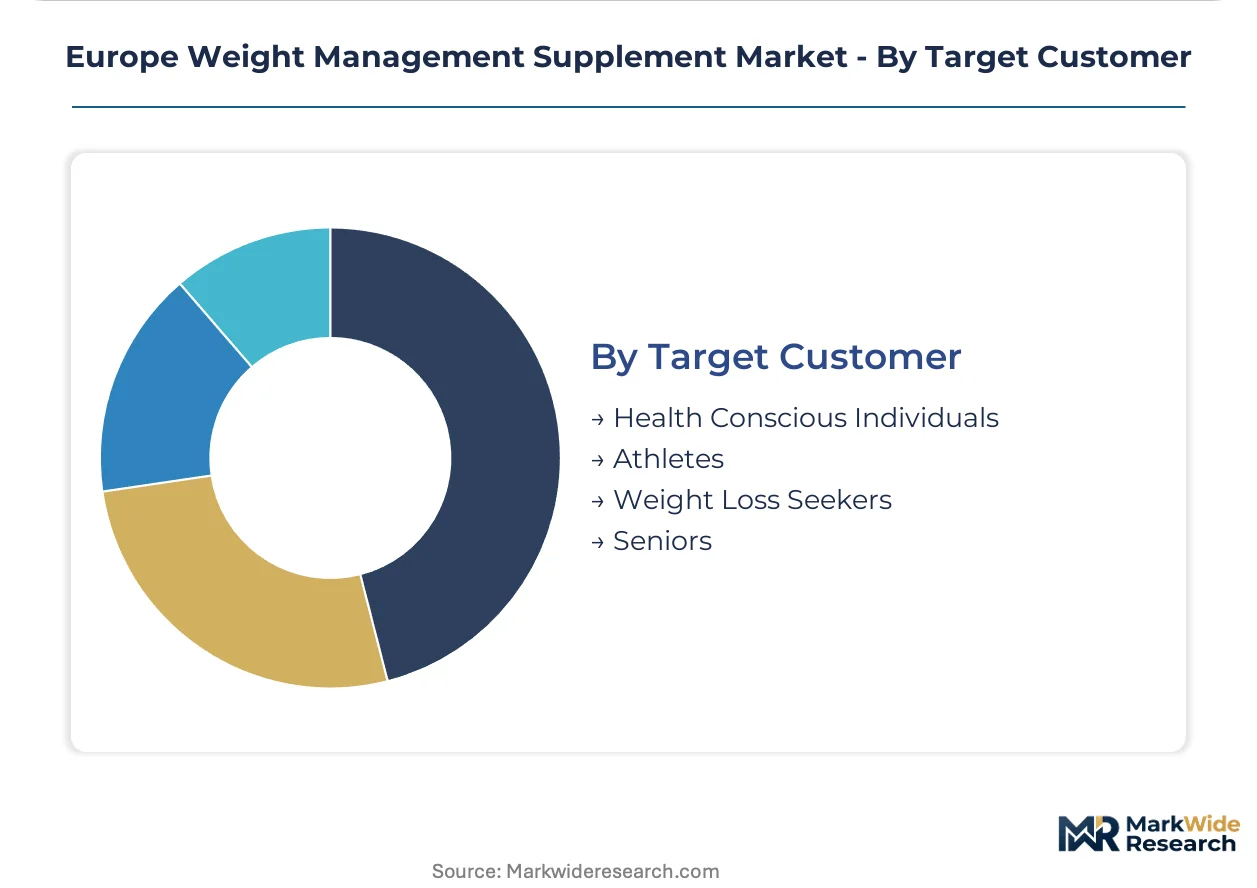
Target Customer:
Customer archetypes align product positioning with life stage priorities and regulatory risk tolerance for efficacy claims.
- Health Conscious Individuals:Preventive wellness seekers prioritizing clean label transparency and sustainability credentials. Amsterdam and Stockholm consumers lead demand for CSRD-aligned supply chain disclosures; this segment tolerates premium pricing for third-party certifications.
- Athletes:Performance-oriented amateurs and recreational competitors driving protein volume. Spanish and Italian fitness culture penetration expands addressable base beyond traditional bodybuilding demographics; Informed Sport and comparable anti-doping certifications determine brand eligibility.
- Weight Loss Seekers:Outcome-driven consumers seeking measurable body composition changes.
- Seniors:Sarcopenia prevention and metabolic health maintenance positioning for aging populations.
Athlete segment anchors current volume; senior positioning represents the steepest expansion trajectory as demographic shifts intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy-trained nutritionists and sports dietitians concentrate in Western European metropolitan clusters, anchoring professional recommendation networks that shape consumer purchasing across national borders.
Germany
Amateur strength athletes and CrossFit practitioners in Berlin and Hamburg drive protein isolate consumption at volumes exceeding Southern European markets. EFSA-approved satiety claims unlock pharmacy tier pricing for whey and plant-protein formulations. Bavarian dairy processing facilities around Munich supply isolate raw material to brands seeking backward integration.
United Kingdom
Subscription-based personalized nutrition platforms capture lifetime value among London financial services professionals seeking portion-controlled meal replacements. The Advertising Standards Authority enforces strict substantiation requirements for weight loss efficacy messaging. Manchester and Birmingham logistics hubs enable next-day fulfillment for direct-to-consumer protein brands.
France
Time-compressed executives in Paris substitute micronutrient-fortified meal replacements for prepared food during compressed work schedules. ANSM medical food borderline determinations under EU MDR create gatekeeper dynamics for pharmacy channel access. Lyon and Marseille manufacturing clusters specialize in capsule-format botanical formulations for clinician sampling programs.
Italy
Recreational cyclists and weekend athletes in Milan and Rome expand protein demand beyond traditional bodybuilding demographics. Italian regulators enforce EFSA gut health claim standards most strictly, redirecting innovation toward clinical endpoint trials. Northern Italian formulators lead precision blending of pea-rice amino acid profiles to match whey biological value.
Poland
Underpenetrated pharmacy and fitness channels in Warsaw and Kraków offer first-mover positioning before regulatory harmonization fully converges with Western European standards. Polish consumer protection authorities are adopting EFSA opinion frameworks for novel ingredient assessments. Poznań distribution centers serve as entry points for German and Dutch brands testing Eastern European expansion.
Europe Weight Management Supplement Market Competitive Landscape
Top-tier vendors anchor pharmacy and medical food positioning, while mid-tier commodity players compete on protein isolate scale and direct-to-consumer subscription mechanics. The competitive structure stratifies across EFSA-validated premium formulations, backward-integrated dairy processors, and digital-native personalized nutrition platforms. Two dominant competitive moves concentrate strategic activity: M&A targeting clinical trial capabilities and capacity expansion into precision fermentation-derived proteins.
Within the science-backed medical positioning tier, Nestlé Health Science and Bayer AG exemplify pharmaceutical-adjacent market entry. Herbalife Nutrition and Amway Corp. occupy positions in high-touch direct-selling networks across Southern Europe. Glanbia PLC anchors the backward-integrated processor archetype through captive whey protein isolate production.
| Leading Market Players |
|---|
| Herbalife Nutrition |
| Glanbia PLC |
| Nestlé Health Science |
| Amway Corp. |
| General Nutrition Centers |
| Evlution Nutrition LLC |
| Bayer AG |
| Huel |
| YFood |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging requirements and CSRD sustainability disclosures gate qualified supply and premium-tier pricing access, as brands lacking verified carbon-intensity documentation face exclusion from pharmacy procurement programs and institutional B2B contracts across German and French markets.
Pricing Analysis
Bundled subscription services versus unbundled transactional purchases split pricing architecture across the European weight management supplement landscape. Three-tier pricing structure across premium EFSA-validated formulations, standard gym-channel isolates, and economy white-label powders dominates, with certification grade and backward integration status as primary differentiation drivers. Pricing pressure stems from Irish-Dutch whey processing concentration and dairy commodity swings. Amateur athletes in Spain and Italy show highest price sensitivity, while pharmacy-positioned medical food buyers in Paris and London tolerate substantial premiums for clinician endorsement.
Supply Chain Analysis
Freight cost volatility from Baltic and North Sea routes compounds margin pressure for brands dependent on just-in-time isolate delivery to Central European markets. Supply concentrates in Ireland, the Netherlands, and Germany for whey protein isolate processing, with German and Dutch facilities leading precision fermentation capacity. Raw material dependencies include dairy whey streams, pea and rice protein concentrates, and novel botanical thermogenics. Single-source vulnerability from concentrated Irish-Dutch processing creates structural risk. Distribution runs through pharmacy wholesale networks in Western Europe and direct-to-consumer platforms in Eastern European expansion markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's weight management supplement market operates as a regulatory compounder, where EFSA claim validation timelines and EU MDR medical food determinations continuously reshape competitive moats and pricing power across member states.
For Market Incumbents: Anchor pharmacy channel positioning through accelerated EFSA opinion submissions for novel fiber matrices and protein satiety claims, defending against generic substitution threat from unbranded e-commerce competitors. Deepen backward integration into precision fermentation-derived proteins to offset dairy commodity volatility and secure vegan-certified premium segments before capacity scarcity intensifies. For New Entrants and Emerging Players: AI-driven personalized nutrition platforms offer technology-first wedge into underserved subscription segments among Amsterdam and Stockholm urban professionals, where digital health integration outpaces incumbent adaptation. Target Poland and Romania pharmacy networks before regulatory harmonization converges, deploying direct-to-consumer fulfillment with localized EFSA opinion pre-submissions as go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier formulators lacking clinical trial infrastructure but possessing captive isolate processing or Eastern European distribution assets. Long-term viability frames around regulatory validation capabilities and sustainability disclosure compliance as EU Green Deal mandates intensify. Watch EFSA opinion backlog resolution timelines as inflection signal for premium-tier pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Submission | Unlocks pharmacy tier pricing and clinician recommendation channels for compliant formulations. |
| Precision Fermentation Capacity Buildout | Reduces dairy commodity exposure while capturing vegan-certified premium segment demand. |
| CSRD Sustainability Compliance | Enables institutional B2B procurement access under EU Green Deal packaging mandates. |
| Eastern European Distribution Expansion | Secures first-mover positioning in underpenetrated Polish and Romanian pharmacy channels. |
| Digital Coaching Platform Integration | Captures lifetime value through subscription models displacing transactional supplement purchases. |
Research Methodology
Coverage spans Western and Eastern European markets, with primary inputs from each regulatory cluster and national pharmacy classification system. The research combines structured interviews with regulatory affairs directors at supplement formulators, pharmacy procurement managers in Paris and Berlin, sports nutrition brand managers, and EFSA scientific panel observers with secondary validation from EFSA opinion databases, EU MDR borderline determination records, national customs trade data, and CSRD sustainability disclosure filings. Bottom-up product-level volume estimates triangulate against top-down market sizing from channel shipment data.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, modeling segmentation dimensions including product type, formulation format, distribution channel, and target customer archetype alongside regulatory validation status as industry-specific dimension. CAGRs derive from fitted growth curves incorporating EFSA opinion pipeline timelines, fitness culture penetration rates by metropolitan cluster, and pharmacy channel expansion trajectories. Forecast inputs include dairy commodity price cycles, precision fermentation capacity buildout schedules, and EU Green Deal compliance cost assumptions.
The model holds under stable EFSA opinion processing timelines and continued EU MDR medical food borderline enforcement; deviation in regulatory harmonization speed or EFSA resource allocation would shift premium-tier pricing power and channel access assumptions materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Creatine Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
North America Sports Nutrition Market