
 Androstenedione Market | 2026-2036
Androstenedione Market Size, Share, and Industry Trends Forecast 2026-2036
Androstenedione Market Analysis
Plant-derived diosgenin from wild yam is shifting toward recombinant microbial fermentation as the dominant feedstock for androstenedione synthesis, compressing production costs and improving batch consistency. Indo Phyto Chemicals leverages its botanical extraction heritage to maintain supply relationships with traditional pharmaceutical manufacturers. Goto Pharmaceutical anchors its position through advanced steroid intermediate purification capabilities serving Japanese and export markets. Sigma-Aldrich Corporation dominates research-grade distribution channels with certified reference standards for analytical laboratories.
Androstenedione is a C19 steroid hormone and precursor to testosterone and estrone, synthesized industrially via microbial transformation of phytosterols or chemical degradation of diosgenin, with purity specifications typically exceeding 98.5% for pharmaceutical applications. The hormone replacement application segment sustains premium pricing due to compounding pharmacy demand and endocrinology clinic prescriptions. Tablet and capsule product formats lead volume distribution, while liquid formulations capture specialized anti-aging clinic channels. Fitness stores and online retail distribution channels face margin pressure from regulatory scrutiny of athletic performance claims.
FDA oversight of compounded bioidentical hormones and WADA prohibited-substance listings constrain market access for performance-oriented formulations, while EMA pharmacovigilance requirements shape European import standards. China's NMPA enforces GMP certification for active pharmaceutical ingredient exports, filtering supplier qualification for international buyers. Stakeholders must monitor evolving national anti-doping enforcement intensity and compounding pharmacy regulatory exemptions to anticipate demand shifts between clinical and consumer channels.
Market Dynamics
Pharmaceutical-grade microbial fermentation is compressing diosgenin extraction margins while FDA compounded bioidentical hormone exemptions sustain compounding pharmacy demand against WADA athletic-use prohibitions.
Growth Catalysts
- Compounding pharmacy exemptions:FDA Section 503A preserves physician-directed hormone replacement access for aging populations seeking bioidentical formulations outside mass-manufactured channels.
- Recombinant microbial fermentation:Engineered yeast strains transform phytosterols into androstenedione with batch-to-batch purity exceeding botanical extraction consistency.
- Japan's geriatric endocrinology demand:PMDA-approved hormone replacement protocols for sarcopenia and osteoporosis drive prescription volume through specialized clinics.
Market Restraints
- WADA prohibited substance listings:International Olympic Committee and national anti-doping agency enforcement blocks athletic performance marketing and retail distribution channels.
- Chinese API export concentration:NMPA GMP certification requirements filter qualified suppliers, creating single-source dependency risks for international pharmaceutical manufacturers.
- Soy and wild yam price volatility:Agricultural commodity swings for diosgenin feedstock compress margins for botanical extraction-dependent producers.
Strategic Opportunities
- Veterinary hormone therapy:Equine and companion animal endocrine disorders represent an underpenetrated application with lighter regulatory burden than human pharmaceutical pathways.
- EMA pharmacovigilance alignment:Harmonized European adverse event reporting standards create streamlined export qualification for compliant API manufacturers.
- Direct-to-clinic distribution:Anti-aging specialty clinics bypass traditional pharmacy intermediaries, capturing margin through membership-based hormone optimization programs.
Industry Challenges
- Steroid chemistry synthesis expertise:Microbial fermentation scale-up requires rare biochemical engineering talent with steroid biotransformation experience.
- Multi-jurisdiction compliance synchronization:Simultaneous FDA, EMA, and NMPA filing timelines strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Androstenedione Market |
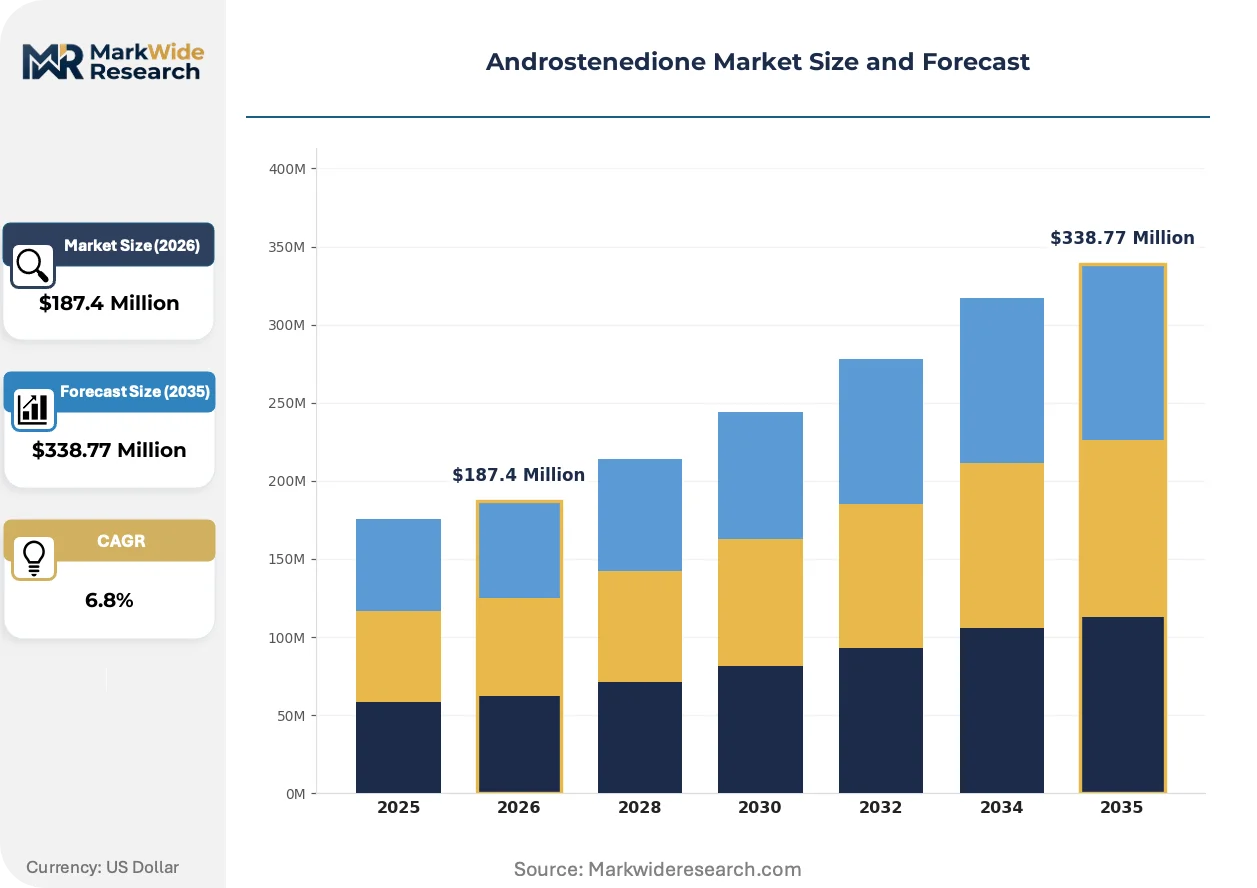
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Hormone Replacement, Athletic Performance, Weight Management, Anti-Aging Product Type: Tablets, Capsules, Powders, Liquid Distribution Channel: Online Retail, Pharmacies, Fitness Stores, Supermarkets End User: Athletes, Bodybuilders, Fitness Enthusiasts, Older Adults |
| Companies Covered | BIOVET, Indo Phyto Chemicals, Goto Pharmaceutical, Kaizon, Jiufu, Darui, Yongning Pharma, Dahua Pharmaceutical, Sigma-Aldrich Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Androstenedione Market Emerging Trajectories
Continuous bioprocessing and single-use fermentation systems are shortening steroid intermediate production cycles while regulatory data harmonization efforts compress cross-border approval timelines.
CRISPR-engineered Yarrowia lipolytica strains are integrating multi-enzyme pathways for direct phytosterol-to-androstenedione conversion. Japanese and South Korean API manufacturers are adopting these platforms to reduce solvent-intensive chemical steps. The technology is integrating upstream fermentation with downstream crystallization into continuous manufacturing lines that slash batch cycle times.
EMA's revised guideline on steroid hormone API starting materials is tightening botanical source documentation requirements. European import inspections now demand full supply chain traceability from diosgenin harvest to final intermediate. Compounding pharmacies in Germany and Switzerland are responding by qualifying recombinant fermentation suppliers with ISO 17025-certified analytical protocols.
Anti-aging clinic chains are consolidating procurement through preferred supplier agreements with vertically integrated API-to-formulation manufacturers. Traditional pharmaceutical distributors serving independent compounding pharmacies face volume erosion as clinic networks centralize purchasing. This concentration is most visible in Florida, Texas, and Arizona where cash-pay hormone optimization practices cluster.
Androstenedione Market Segmentation
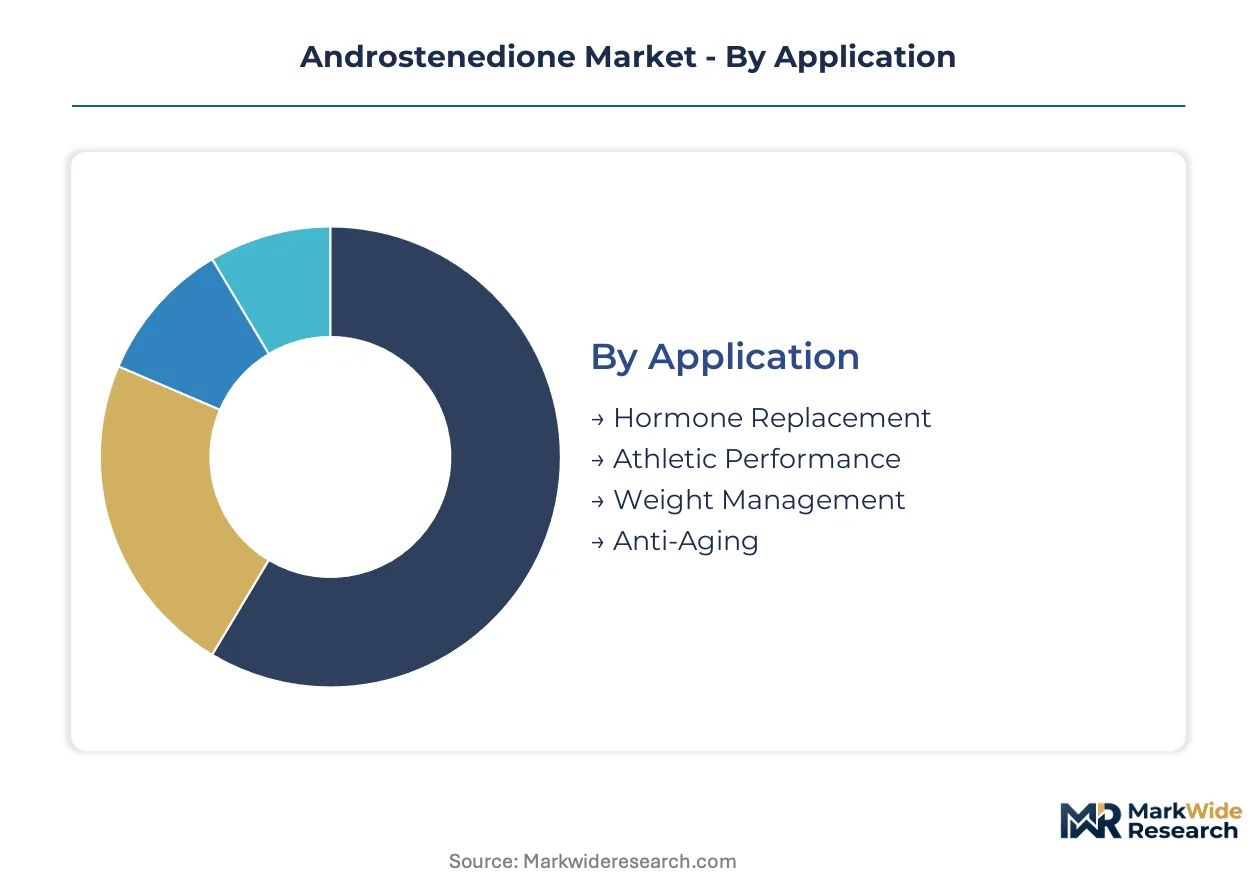
Androstenedione demand fragments sharply across regulatory boundaries and buyer risk profiles. Athletic performance channels face WADA prohibitions while hormone replacement applications operate under physician oversight with distinct compliance requirements.
Application:
Buyers in this category separate by medical necessity versus discretionary enhancement, with regulatory treatment diverging accordingly.
- Hormone Replacement:Physician-prescribed protocols for testosterone deficiency and estrogen modulation in aging populations. Compounding pharmacies in the United States and specialized endocrinology clinics in Japan concentrate procurement volume under FDA Section 503A exemptions and PMDA-approved sarcopenia protocols.
- Anti-Aging:Cash-pay optimization programs targeting biomarker-driven hormone balancing. Membership-based clinic networks in Florida, Texas, and Arizona are expanding fastest as direct-to-clinic procurement bypasses traditional pharmacy intermediaries.
- Athletic Performance:WADA-prohibited substance status blocks legitimate marketing channels. Enforcement intensity from national anti-doping agencies constrains retail availability.
- Weight Management:Metabolic modulation applications with limited clinical validation. Regulatory scrutiny from FDA and EMA limits formulation claims.
Volume sits with Hormone Replacement; growth tilts toward Anti-Aging.
Product Type:
Manufacturing cost structures and bioavailability requirements differentiate buyers between standardized oral formats and specialized delivery systems.
- Tablets:Compressed solid dosage forms with established dissolution profiles. Pharmaceutical manufacturers serving compounding pharmacies prioritize batch consistency and 98.5%+ purity specifications for endocrinology prescriptions.
- Capsules:Gelatin or vegetable-based shells enabling taste masking and variable fill weights. Anti-aging clinics in the United States favor capsule flexibility for customized dosing protocols.
- Liquid:Suspension or solution formats for sublingual or topical absorption. Specialized anti-aging channels capture premium pricing through compounding flexibility.
- Powders:Bulk active pharmaceutical ingredient for in-house formulation. Research laboratories and veterinary compounders dominate procurement with certified reference standard requirements.
Tablets command current volume; liquid formulations are climbing the fastest.
Distribution Channel:
Channel selection reflects buyer regulatory sophistication and product claim permissibility.
- Pharmacies:Licensed dispensaries with prescription verification and cold-chain capabilities. Compounding pharmacies in North America anchor pharmaceutical-grade volume through physician-directed hormone replacement.
- Online Retail:E-commerce platforms with variable quality assurance. Fitness-oriented claims trigger FTC scrutiny and payment processor restrictions in the United States.
- Fitness Stores:Brick-and-mortar supplement retailers facing margin compression from anti-doping enforcement. WADA prohibited-substance listings limit shelf placement.
- Supermarkets:Mass-market retail with minimal specialized inventory. General wellness positioning avoids hormone-specific claims.
Pharmacies concentrate volume; direct-to-clinic procurement is gaining share fastest.
End User:
Demographic risk tolerance and medical supervision access shape purchasing behavior.
- Older Adults:Aging populations seeking bioidentical hormone optimization through physician-supervised protocols. Medicare-eligible demographics in the United States and geriatric patients in Japan drive sustained prescription volume.
- Fitness Enthusiasts:Recreational athletes pursuing body composition goals with limited competitive scrutiny. Online research and peer recommendations influence channel selection.
- Bodybuilders:Competitive and amateur physique athletes facing explicit WADA testing. Underground sourcing predominates due to prohibited status.
- Athletes:Tested competitors subject to national anti-doping agency protocols. Legitimate market access is essentially closed.
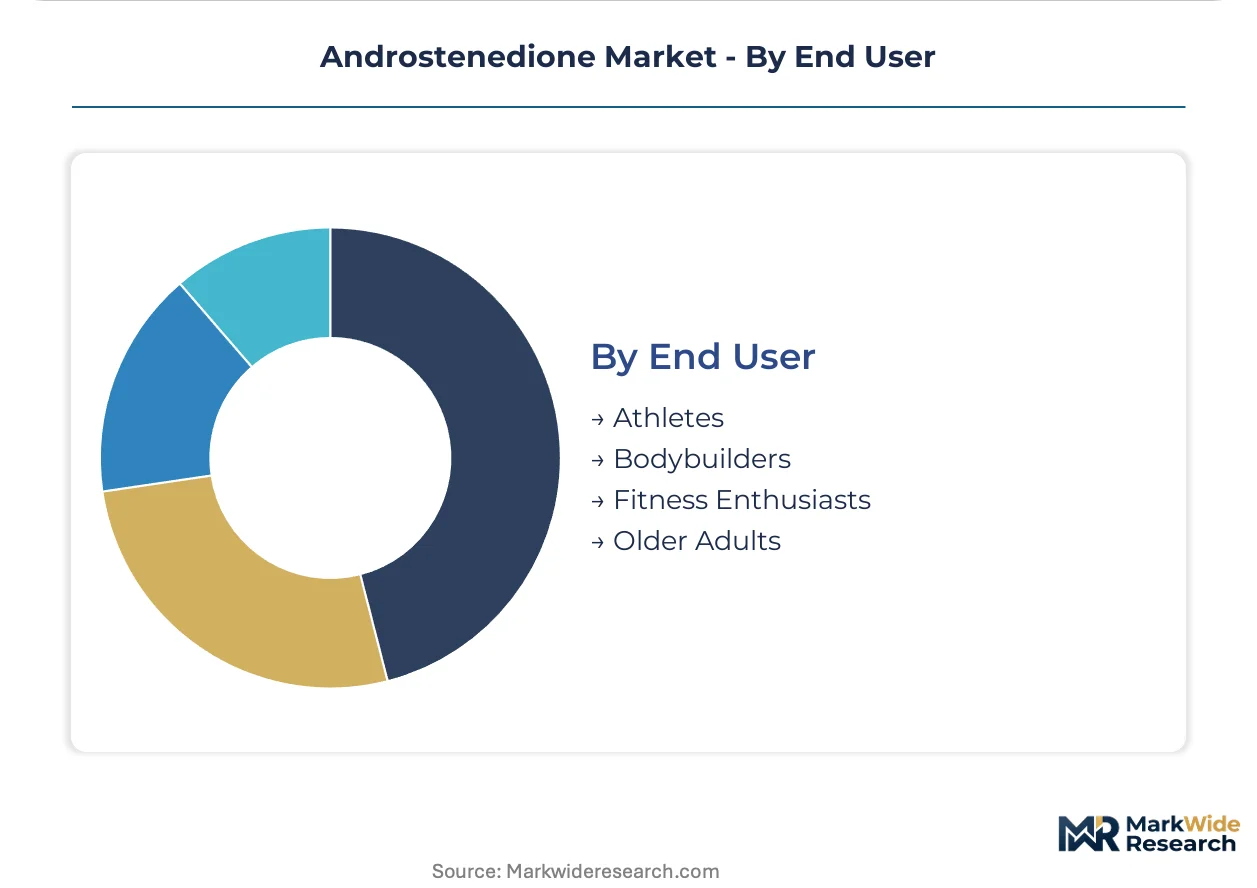
Older Adults dominate volume; Fitness Enthusiasts show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compounding pharmacy networks in the United States concentrate the largest share of pharmaceutical-grade procurement, while Japanese geriatric clinics and Chinese API manufacturing clusters shape supply-side dynamics across three continents.
United States
Anti-aging clinic chains in Florida, Texas, and Arizona drive cash-pay hormone optimization demand through membership-based programs. FDA Section 503A exemptions preserve physician-directed compounding access for bioidentical formulations. The Southwest corridor from Phoenix to Dallas anchors direct-to-clinic procurement consolidation.
Japan
PMDA-approved sarcopenia and osteoporosis protocols generate sustained prescription volume through specialized endocrinology clinics serving aging demographics. METI industrial biotechnology incentives accelerate microbial fermentation adoption for domestic API production. The Kansai region around Osaka houses advanced steroid intermediate purification facilities.
China
NMPA GMP certification requirements filter export-qualified suppliers, concentrating international buyer relationships in Zhejiang and Jiangsu province manufacturing clusters. Phytosterol feedstock processing dominates the Yangtze River Delta. Domestic demand for hormone replacement remains limited compared to export-oriented API production.
Germany
EMA pharmacovigilance alignment and revised steroid hormone API starting material guidelines drive recombinant fermentation supplier qualification. Compounding pharmacies in Bavaria and North Rhine-Westphalia respond with ISO 17025-certified procurement standards. The Frankfurt-Stuttgart corridor hosts analytical laboratory clusters serving European quality verification.
Switzerland
Swissmedic oversight of bioidentical hormone formulations supports premium positioning for compounding pharmacies serving cross-border patients from France and Italy. Basel-area pharmaceutical services firms specialize in steroid chemistry regulatory consulting. The Lake Geneva region concentrates anti-aging clinic networks with direct API sourcing relationships.
Androstenedione Market Vendor Landscape
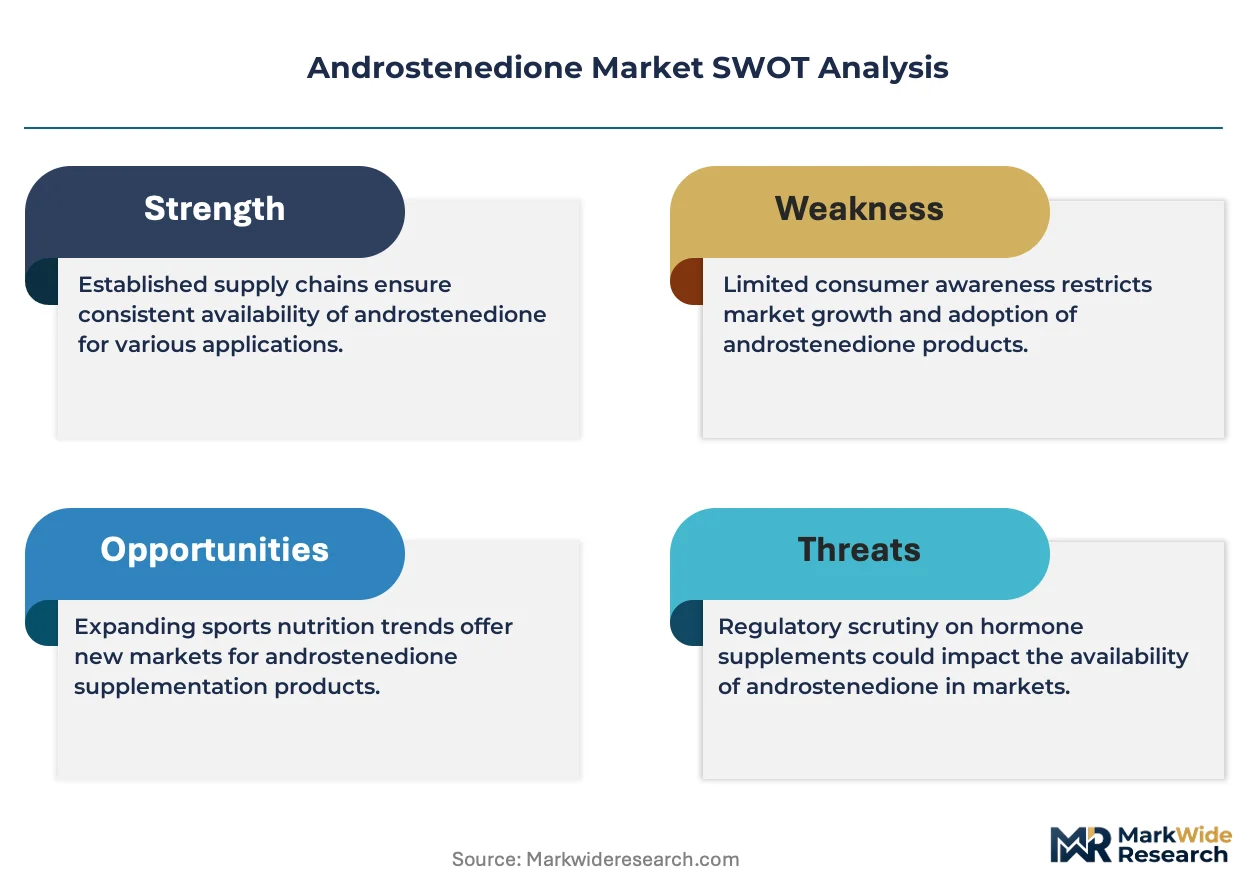
Strategic partnerships between API manufacturers and compounding pharmacy networks dominate the current landscape, reshaping distribution economics. The vendor base separates into three functional tiers: vertically integrated fermentation specialists, botanical extraction heritage firms, and research-grade distributors. Consolidation pressure favors players with captive microbial production platforms. Geographic expansion into veterinary hormone therapy and technology licensing for continuous bioprocessing represent the two dominant competitive vectors.
Among heritage botanical extractors, Indo Phyto Chemicals occupies a position representing traditional diosgenin supply relationships, while Goto Pharmaceutical exemplifies advanced purification capabilities serving Japanese export markets. Sigma-Aldrich Corporation anchors the research-grade distribution tier with certified reference standards for analytical laboratories. These three players illustrate how competitive positioning fragments across feedstock origin, processing sophistication, and end-market regulatory requirements.
| Leading Market Players |
|---|
| BIOVET |
| Indo Phyto Chemicals |
| Goto Pharmaceutical |
| Kaizon |
| Jiufu |
| Darui |
| Yongning Pharma |
| Dahua Pharmaceutical |
| Sigma-Aldrich Corporation |
| Others |
Supply Flow & Price Mechanics
Phytosterol feedstock price indices from China's Yangtze River Delta cascade through three distinct pricing tiers as microbial fermentation displaces botanical extraction, compressing margins for diosgenin-dependent producers while recombinant suppliers capture premium positioning through FDA and EMA certification.
Pricing Analysis
Volume concentrates in standard-grade tablets for compounding pharmacies, while margins accrue to liquid formulations serving anti-aging clinics. Pharmaceutical-grade purity specifications exceeding 98.5% command certification premiums against research-grade powders. Pricing pressure intensifies as Chinese API manufacturers expand fermentation capacity, eroding botanical extraction economics. Compounding pharmacies show lowest price sensitivity due to physician-directed reimbursement, while fitness-oriented online retail faces acute margin compression from payment processor restrictions.
Supply Chain Analysis
Reverse-logistics flows are negligible given single-use fermentation bioreactors and crystallization equipment, though solvent recovery systems in Japanese purification facilities reclaim organic reagents. Supply concentrates in China, Japan, and Germany, with Zhejiang province fermentation clusters feeding Osaka-area purification plants. The chain draws from soy and wild yam agricultural commodities, engineered yeast strains, and GMP-certified analytical reagents. Single-source dependency on NMPA-certified Chinese API exporters creates structural vulnerability. Distribution runs through compounding pharmacy networks and direct-to-clinic procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as fermentation scale-up capabilities determine who captures margin from phytosterol feedstock through finished formulation.
For Market Incumbents: Cement market position through captive microbial fermentation capacity in Zhejiang or Jiangsu provinces, insulating against NMPA export certification bottlenecks. Secure preferred supplier agreements with Florida and Texas anti-aging clinic chains before procurement consolidation accelerates. Threats include CRISPR-engineered strain licensing from South Korean biotech entrants and EMA starting-material documentation requirements favoring recombinant suppliers. For New Entrants and Emerging Players: Veterinary compounding pharmacies represent the most penetrable channel, with lighter FDA oversight than human hormone replacement and WADA-exempt positioning. Target equine endocrinology clinics in Kentucky and California with bulk powder formulations. Go-to-market leverage rests on ISO 17025-certified analytical protocols that satisfy European import inspections without legacy botanical supply chain investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fermentation specialists with stranded diosgenin extraction assets in India seeking microbial transformation pivots. Long-term viability hinges on five-to-ten-year regulatory alignment between FDA compounded bioidentical exemptions and EMA pharmacovigilance standards. Monitor WADA enforcement intensity against underground athletic distribution as the inflection signal for legitimate channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Fermentation Scale-Up | Engineered yeast platforms reduce solvent-intensive chemical steps in Osaka-area facilities. |
| GMP Certification Investment | NMPA qualification filters export access for Zhejiang and Jiangsu manufacturing clusters. |
| Direct-to-Clinic Distribution | Anti-aging networks in Florida and Texas bypass traditional pharmacy intermediaries. |
| Veterinary Formulation Development | Equine hormone therapy operates outside WADA prohibited-substance restrictions. |
| Continuous Bioprocessing Adoption | Single-use fermentation systems shorten batch cycles for Japanese API manufacturers. |
Methodological Framework
Independent corroboration across FDA 503A exemption filings, EMA pharmacovigilance databases, and NMPA GMP certification records underwrites the qualitative findings. Primary interviews with compounding pharmacy procurement managers, anti-aging clinic medical directors, steroid chemistry R&D directors, and regulatory affairs specialists at API manufacturers combined with secondary validation from customs trade data, SEC pharmaceutical filings, and WADA prohibited-substance monitoring reports. Bottom-up volume estimates from fermentation capacity installations and top-down demand triangulation from prescription audit data were reconciled.
Comparable historical periods anchored the forecast window to pre-pandemic baseline demand and post-regulatory-shift adjustment trajectories across the analysis window. Segmentation modeling incorporated application type, product format, distribution channel, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to phytosterol feedstock price elasticity and clinic network expansion rates. Forecast inputs included PMDA sarcopenia protocol adoption curves and anti-aging clinic membership growth in cash-pay markets.
Caveats apply where WADA enforcement intensity, FDA compounded bioidentical exemption revisions, or Chinese API export policy shifts could materially shift the outlook. Forecasts reflect assumptions about regulatory stability and fermentation technology diffusion rates. Practitioners should monitor EMA starting-material guideline implementation and NMPA GMP recertification timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Creatine Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
United States Sports Nutrition Market