
 Hydration Products Market | 2026-2036
Hydration Products Market Size, Share, and Industry Trends Forecast 2026-2036
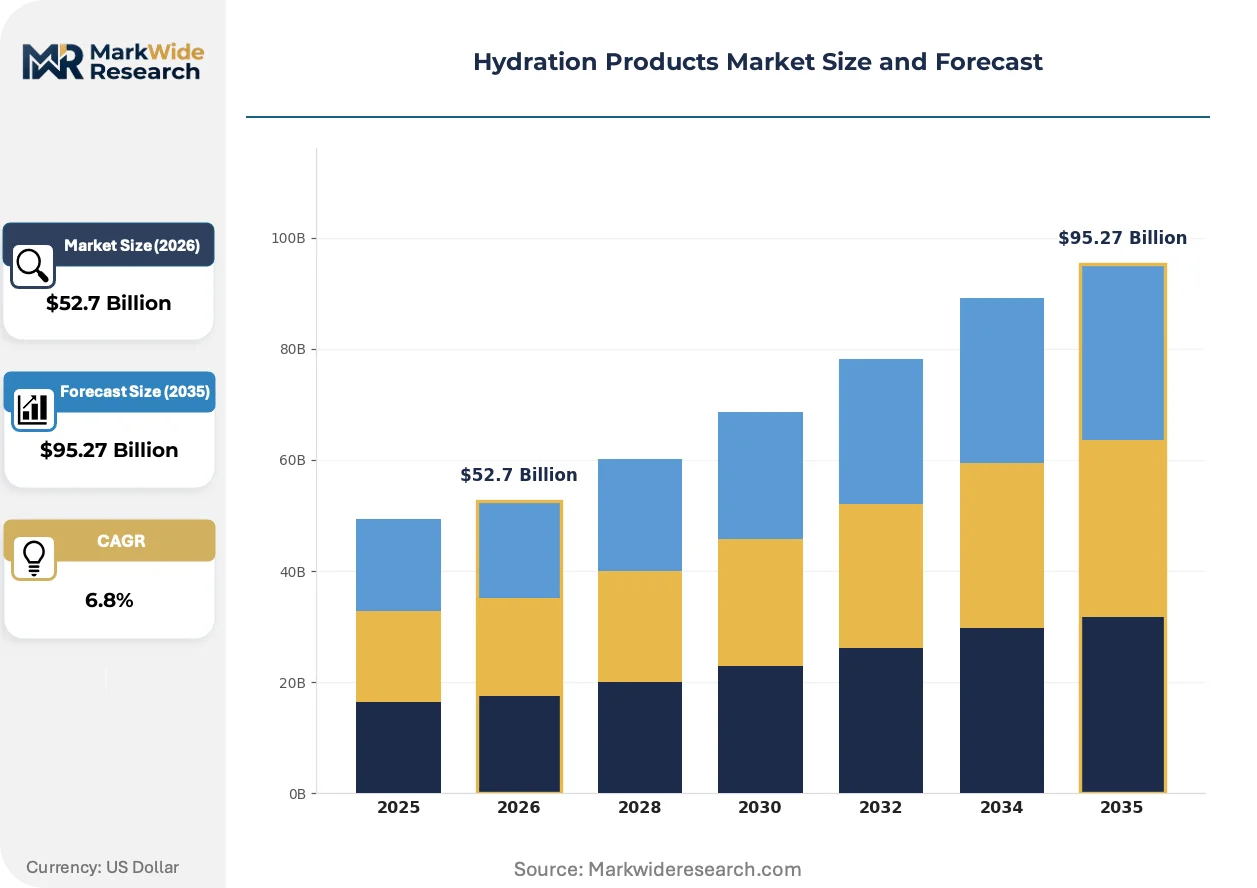
Hydration Products Market Outlook
Multi-source ingredient procurement is expanding across the hydration products sector as brands hedge against supply volatility in electrolyte minerals and natural flavor extracts. PepsiCo leverages its beverage manufacturing scale to control production costs across multiple continents. Danone anchors its portfolio in functional water and dairy-based hydration, competing on nutritional credibility rather than volume alone. Nestlé sustains global distribution reach through its existing bottled water infrastructure, extending shelf presence in convenience and grocery channels.
Hydration products encompass formulated beverages, concentrated powders, effervescent electrolyte tablets, and portable gel packs designed to replenish fluids, minerals, and carbohydrates lost through physical exertion or environmental exposure; these formulations typically specify sodium, potassium, magnesium, and chloride concentrations measured in milligrams per serving to ensure precise electrolyte replacement for athletic and clinical applications. Beverages occupy the largest revenue pool due to immediate consumption convenience and established retail placement, while electrolyte tablets represent the fastest-expanding segment driven by portability and reduced shipping weight. The end-user base fragments across athletes demanding performance-grade formulations, fitness enthusiasts seeking sugar-reduced options, and casual consumers purchasing flavored functional waters, with margin pools concentrating in specialty health shops and online retail channels where premium positioning commands price flexibility.
The US Food and Drug Administration governs nutrition labeling and health claim substantiation for hydration products sold in America, while the European Food Safety Authority evaluates electrolyte concentration thresholds for products marketed with dehydration-prevention claims in EU member states. These frameworks elevate compliance costs for cross-border brands but simultaneously create barriers that favor established players with dedicated regulatory affairs capacity. Stakeholders must monitor evolving sodium reduction mandates and emerging packaging sustainability requirements that will reshape both formulation priorities and supply chain configurations.
Market Dynamics
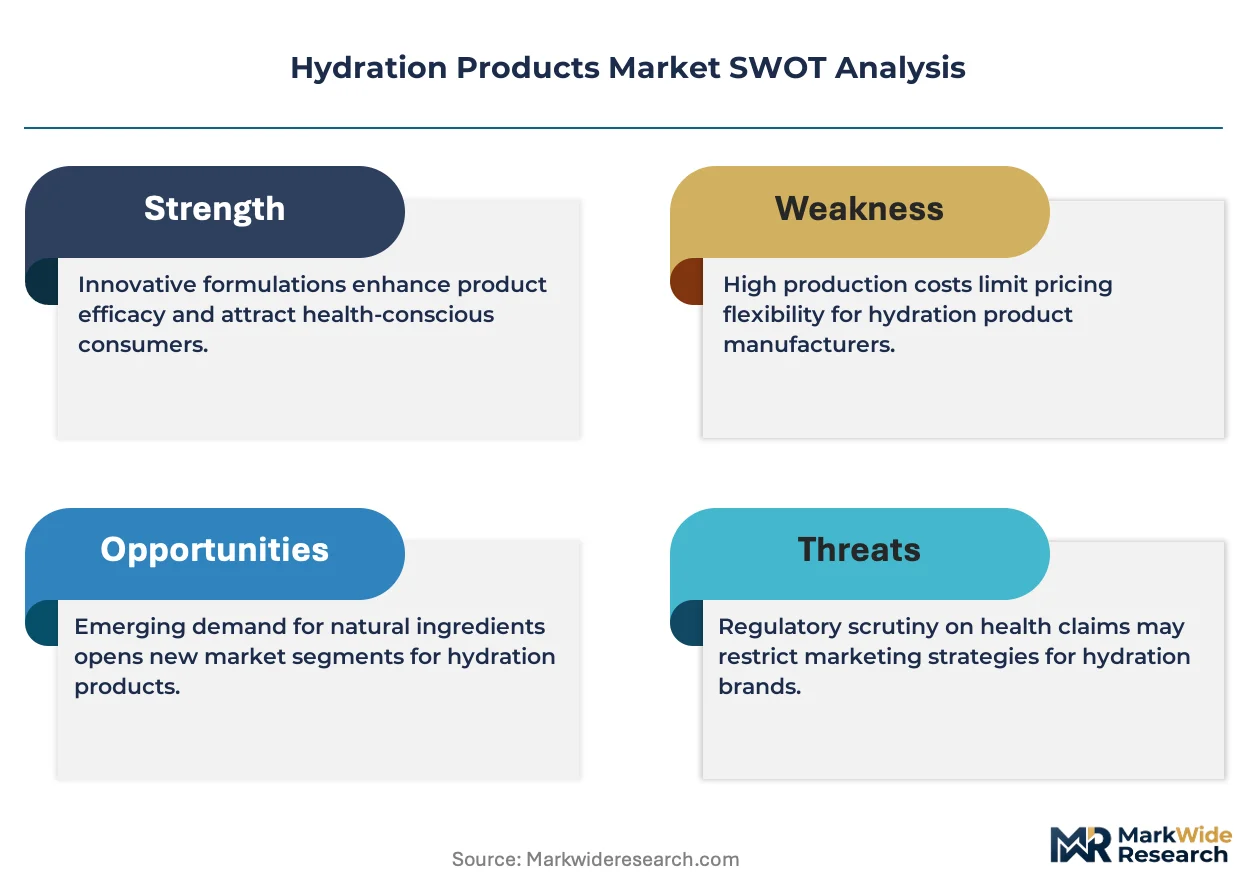
FDA labeling mandates for added sugars and sodium content are forcing reformulation across the hydration products sector, compressing margin structures while creating compliance barriers that favor established manufacturers with dedicated regulatory affairs capacity.
Growth Catalysts
- Amateur athlete adoption:Recreational runners and weekend cyclists are purchasing electrolyte tablets and gel packs at accelerating rates, expanding the addressable consumer base beyond elite performers.
- EPA water quality standards:Stricter municipal water testing protocols are driving consumers toward packaged functional beverages with certified mineral content.
- Portable format innovation:Single-serve powder sticks and effervescent tablets reduce shipping weight and retail shelf space requirements, unlocking convenience store distribution.
Market Restraints
- Electrolyte mineral volatility:Magnesium and potassium sourcing concentrates in Chile and Jordan, exposing brands to geopolitical supply disruptions and input cost spikes.
- Natural extract scarcity:Stevia and monk fruit supply chains face agricultural yield variability that constrains sugar-free formulation scaling.
- FDA substantiation requirements:Health claims related to dehydration prevention demand clinical evidence packages that smaller entrants cannot finance.
Strategic Opportunities
- Clinical hydration protocols:Hospital and long-term care facilities represent underpenetrated channels for medical-grade electrolyte solutions with precise sodium-potassium ratios.
- EU Green Deal packaging mandates:Biodegradable sachets and aluminum tube formats align with impending sustainability regulations, creating first-mover positioning for compliant suppliers.
- Direct-to-athlete subscription models:Personalized hydration plans based on sweat testing data capture recurring revenue from endurance sports participants.
Industry Challenges
- Formulation chemistry expertise:The sector faces acute shortages of food scientists capable of balancing electrolyte bioavailability with flavor stability in reduced-sugar matrices.
- Co-packer capacity constraints:Aseptic bottling lines for functional beverages require capital commitments that strain mid-tier brands seeking production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydration Products Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverages, Powders, Electrolyte Tablets, Gel Packs End User: Athletes, Fitness Enthusiasts, Casual Consumers, Children Packaging Type: Bottles, Sachets, Cans, Jugs Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Shops |
| Companies Covered | Abbott Laboratories, Primo Brands, PepsiCo, Danone, Nuun Hydration, The Coca-Cola Company, Nestlé, PURE Sports Nutrition, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydration Products Market Strategic Shifts
Precision personalization and sustainability certification are converging to reshape competitive positioning in hydration products, with technology-enabled customization displacing one-size-fits-all formulations across both retail and institutional channels.
Electrolyte micro-dosing technology enables real-time hydration monitoring through wearable-integrated feedback loops. Endurance athletes and occupational safety managers are adopting these systems to replace scheduled drinking protocols with biomarker-responsive intake. The technology is expanding into corporate wellness programs and military procurement specifications, compressing demand for conventional pre-formulated beverages.
EU F-Gas Regulation phase-down timelines are accelerating refrigeration infrastructure upgrades across European beverage distribution networks. Cold-chain-dependent functional waters face elevated compliance costs that favor ambient-stable formats including concentrated shots and freeze-dried cubes. German and Dutch retailers are prioritizing shelf-stable SKUs to avoid refrigerant-dependent display cases.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for core users. Amazon and specialized athletic platforms capture recurring orders from marathon trainers and team sport participants, eroding convenience store velocity for single-serve impulse purchases. This pattern concentrates most visibly in suburban United States markets with high fitness club density and reliable last-mile delivery infrastructure.
Hydration Products Market Segmentation
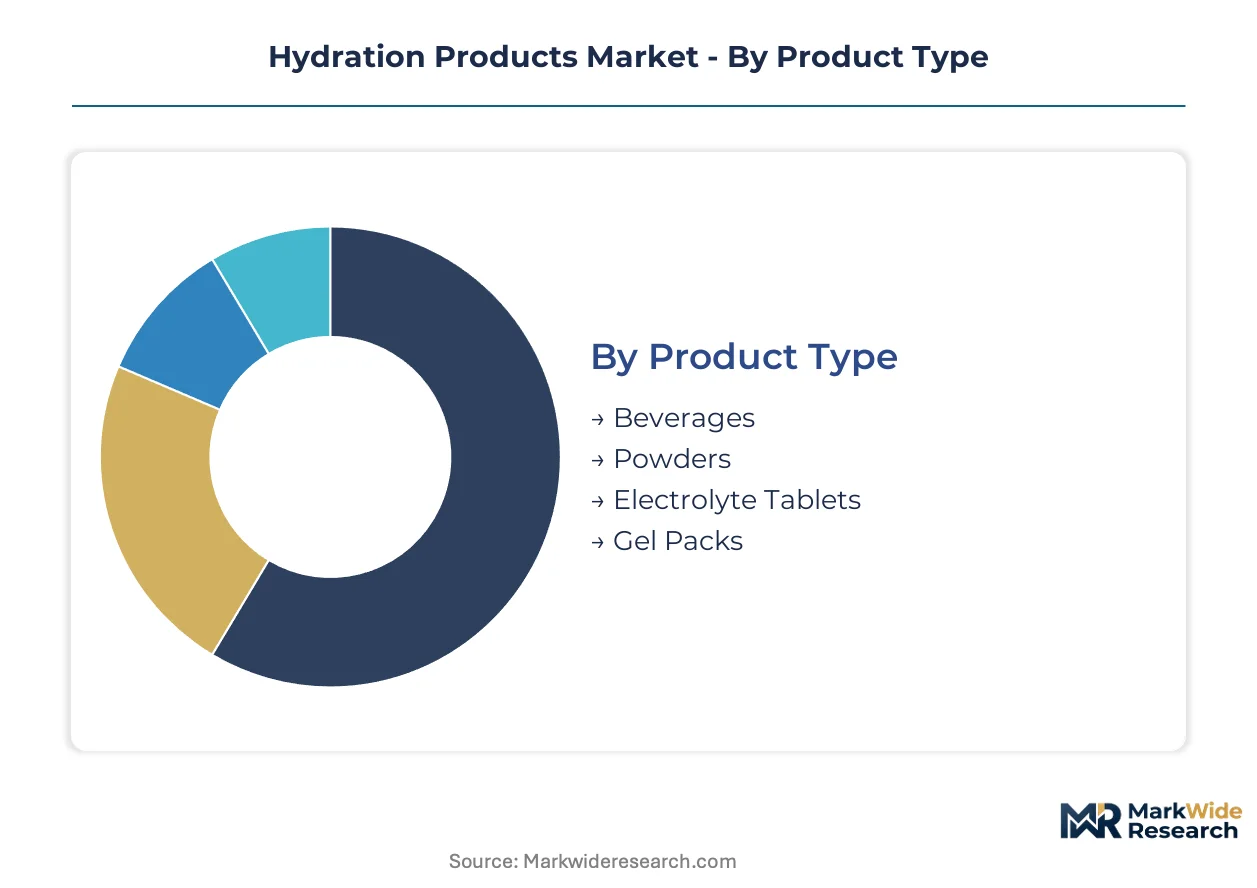
Hydration products fragment across formulation chemistry, consumption occasion, and channel economics. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape competitive strategy.
Product Type:
Formulation technology determines bioavailability, shelf stability, and shipping economics across the hydration spectrum.
- Beverages:Ready-to-drink formulations dominate revenue pools through immediate consumption convenience and established retail placement in grocery and convenience channels. Demand concentrates in the United States where fitness culture and premium positioning drive category expansion, though FDA labeling mandates for added sugars are compressing margin structures.
- Electrolyte Tablets:Effervescent and swallowable formats reduce shipping weight and unlock direct-to-consumer distribution. Amateur athletes and recreational runners are adopting these at accelerating rates, expanding the addressable base beyond elite performers while bypassing cold-chain dependencies.
- Powders:Concentrated formulations offer dose flexibility and reduced packaging mass for bulk purchasers. Sports teams and institutional buyers favor these for cost efficiency.
- Gel Packs:Semi-liquid carbohydrate-electrolyte matrices deliver rapid absorption during endurance events. Marathon and cycling segments sustain niche premium pricing.
Mature deployment sits with Beverages. Newer deployment is concentrated in Electrolyte Tablets.
End User:
User sophistication and performance requirements create tiered pricing power across consumer segments.
- Athletes:Performance-grade formulations with precise sodium-potassium ratios command premium positioning. Elite and amateur competitors alike drive demand for clinical-grade electrolyte replacement.
- Fitness Enthusiasts:Sugar-reduced and naturally flavored options attract gym members and home workout participants seeking functional benefits without caloric load.
- Casual Consumers:Flavored functional waters with mild electrolyte content serve everyday hydration occasions. This segment expands through supermarket and convenience store distribution.
- Children:Pediatric formulations with adjusted mineral concentrations and palatable flavors address parental concerns about sugar content and dehydration risk.
Volume leadership rests with Casual Consumers. Value capture concentrates with Athletes.
Packaging Type:
Material science and sustainability mandates are reshaping container economics and retail placement.
- Bottles:PET and rPET formats dominate immediate consumption channels despite recycling scrutiny. EPA water quality standards are driving consumers toward packaged options with certified mineral content.
- Sachets:Single-serve powder and liquid sticks reduce material intensity and enable subscription models. EU Green Deal packaging mandates favor biodegradable sachet innovations.
- Cans:Aluminum formats appeal to sustainability-conscious consumers and support carbonated functional waters. German retailers prioritize shelf-stable SKUs to avoid refrigerant-dependent display cases.
- Jugs:Bulk containers serve institutional buyers and high-volume households. Co-packer capacity constraints for aseptic filling limit mid-tier brand participation.
Environmental compliance pressure is heaviest on Bottles. Format innovation is accelerating fastest in Sachets.
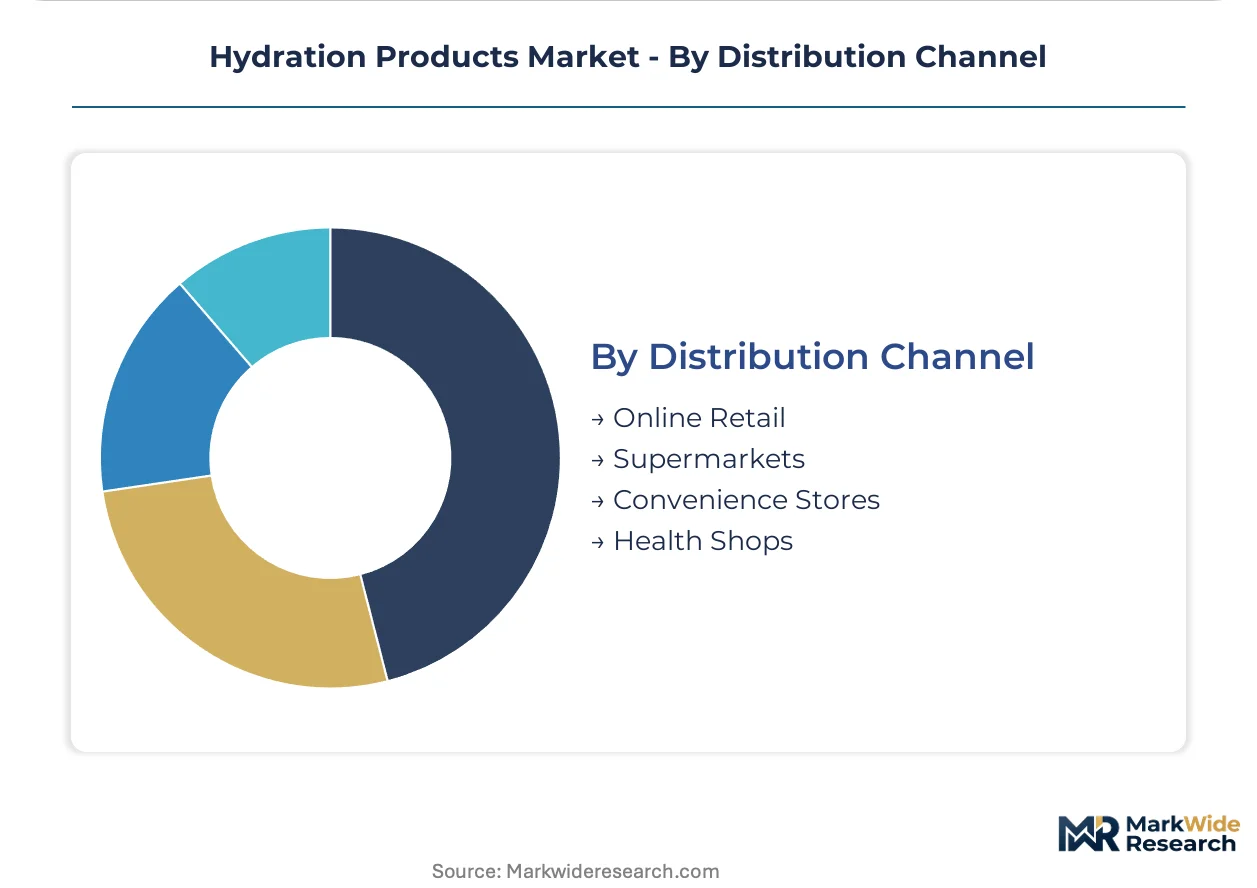
Distribution Channel:
Channel selection determines margin retention, consumer data access, and regulatory exposure.
- Online Retail:Amazon and specialized athletic platforms capture recurring orders through subscription models. Marathon trainers and team sport participants drive predictable replenishment cycles.
- Supermarkets:Mass merchandisers deliver volume through promotional pricing and seasonal placement. Casual consumers purchase flavored functional waters during routine grocery trips.
- Convenience Stores:Impulse-driven single-serve purchases face erosion from subscription displacement. Last-mile delivery infrastructure in suburban United States markets is compressing this channel's velocity.
- Health Shops:Specialty retailers command price flexibility through premium positioning and staff recommendation. Margin pools concentrate here for performance-grade formulations.
Recurring revenue infrastructure is strongest in Online Retail. Physical discovery remains anchored in Health Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hydration products concentrates most heavily in the United States, where fitness culture and premium positioning drive category expansion at rates exceeding other developed markets.
United States
Amateur athletes and recreational runners purchase electrolyte tablets and gel packs at accelerating rates, expanding the consumer base beyond elite performers. FDA labeling mandates for added sugars and sodium content are forcing reformulation across domestic manufacturers. Austin and Boulder anchor innovation clusters where direct-to-athlete subscription models capture recurring revenue from endurance sports participants.
Germany
German retailers prioritize shelf-stable hydration SKUs to avoid refrigerant-dependent display cases under EU F-Gas Regulation phase-down timelines. EFSA evaluates electrolyte concentration thresholds for products marketed with dehydration-prevention claims, elevating compliance costs for cross-border brands. The Rhine-Ruhr metropolitan region concentrates manufacturing scale for ambient-stable formats including concentrated shots and freeze-dried cubes.
United Kingdom
Fitness enthusiasts in London and Southeast England seek sugar-reduced and naturally flavored hydration options through specialty health shops and online retail channels. The UK Food Standards Agency governs nutrition labeling alongside EU-derived regulations still in transitional alignment. Manchester and Birmingham host emerging co-packer capacity for aseptic bottling lines serving mid-tier functional beverage brands.
Japan
Precision personalization technology enables real-time hydration monitoring through wearable-integrated feedback loops among Japanese endurance athletes and corporate wellness programs. METI standards influence functional food and beverage classification for electrolyte products with health claims. The Kanto region around Tokyo concentrates demand for clinical-grade electrolyte replacement formulations in both athletic and occupational safety applications.
Australia
EPA water quality standards drive consumers in Sydney and Melbourne toward packaged functional beverages with certified mineral content. The Therapeutic Goods Administration (TGA) regulates products crossing into medical-grade hydration protocols. Queensland and Western Australia sustain demand for portable formats including single-serve powder sticks that reduce shipping weight across vast distribution distances.
Hydration Products Market Competitive Environment
Portfolio diversification dominates the current landscape as established beverage conglomerates and specialized nutrition firms reposition around functional hydration. The vendor base clusters into three tiers: multinational conglomerates with beverage manufacturing scale, dedicated sports nutrition specialists, and private-label co-manufacturers serving retail channels. Strategic archetypes include scale-driven cost controllers competing on distribution reach, credibility-focused nutrition brands competing on formulation science, and agile format innovators capturing direct-to-consumer growth. M&A activity and capacity expansion for aseptic bottling lines represent the dominant competitive moves reshaping market structure.
Among multinational conglomerates, PepsiCo and Nestlé occupy positions defined by beverage manufacturing scale and existing bottled water infrastructure. Danone sits within the nutrition-credibility tier, anchoring portfolio strength in functional water and dairy-based hydration. Nuun Hydration exemplifies the format-innovation archetype, representing specialists who compete through portable electrolyte tablets and direct-to-athlete channels rather than mass retail velocity.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Primo Brands |
| PepsiCo |
| Danone |
| Nuun Hydration |
| The Coca-Cola Company |
| Nestlé |
| PURE Sports Nutrition |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Electrolyte micro-dosing technology and wearable-integrated feedback systems are displacing scheduled drinking protocols, simultaneously compressing margins on conventional pre-formulated beverages while concentrating supply relationships among sensor manufacturers and algorithm developers in Japan and the United States. This transition rewards brands capable of bundling hardware-enabled services with consumable replenishment, while penalizing pure-play beverage manufacturers locked into PET bottling economics and cold-chain distribution.
Pricing Analysis
Subscription bundling of personalized hydration plans with sweat-testing hardware separates recurring-revenue models from transactional retail pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and vertical integration depth, with FDA-substantiated clinical formulations commanding price flexibility against commodity sports drinks. Cost compression in standard-tier ready-to-drink beverages is intensifying because of co-packer capacity constraints and sodium-reduction reformulation expenses. Casual consumers purchasing flavored functional waters through supermarkets exhibit highest price sensitivity, while endurance athletes subscribing to direct-to-athlete platforms demonstrate lowest sensitivity due to performance-dependent purchase logic.
Supply Chain Analysis
Food scientist shortages in Germany and the Netherlands are constraining aseptic bottling line expansion for functional beverage co-manufacturers. Electrolyte mineral sourcing concentrates in Chile for magnesium and Jordan for potassium, exposing brands to geopolitical supply disruptions and input cost spikes. Stevia and monk fruit natural extract supply chains face agricultural yield variability that constrains sugar-free formulation scaling. Single-source vulnerability in effervescent tablet manufacturing equipment creates bottleneck risk for portable format innovators. Distribution runs through Amazon and specialized athletic platforms for subscription replenishment, while convenience store velocity erodes in suburban United States markets with reliable last-mile delivery infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision personalization technology is replacing legacy one-size-fits-all formulations, creating asymmetric opportunity for stakeholders capable of integrating biomarker-responsive intake systems with consumable supply.
For Market Incumbents: Extend regulatory affairs capacity to capture FDA substantiation requirements for dehydration-prevention claims, creating compliance barriers that exclude smaller entrants. Add aseptic bottling capacity in the Rhine-Ruhr metropolitan region to serve mid-tier functional beverage brands facing co-packer constraints. Vertical integration into electrolyte mineral sourcing through offtake agreements with Chilean and Jordanian suppliers mitigates geopolitical supply disruption risk.
For New Entrants and Emerging Players: EU Green Deal packaging mandates in Germany and the Netherlands open a window for biodegradable sachet and aluminum tube formats that align with impending sustainability regulations. Target clinical hydration protocols in hospital and long-term care facilities as the most penetrable channel for medical-grade electrolyte solutions with precise sodium-potassium ratios. Pursue direct-to-athlete subscription models based on sweat testing data to capture recurring revenue from endurance sports participants.
For Investors and Strategic Acquirers: Re-rating potential sits with format-innovation specialists given portable electrolyte tablet adoption acceleration among amateur athletes. Long-term viability favors companies integrating hardware-enabled personalization with consumable replenishment over pure-play beverage manufacturers. Watch electrolyte micro-dosing technology penetration in corporate wellness programs and military procurement specifications as inflection indicator for displacement of conventional pre-formulated beverages.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Expansion | FDA substantiation requirements for dehydration-prevention claims favor established players with dedicated compliance infrastructure. |
| Aseptic Bottling Line Investment | Rhine-Ruhr manufacturing scale captures mid-tier brand demand constrained by existing co-packer capacity limitations. |
| Biodegradable Packaging Transition | EU Green Deal compliance creates first-mover positioning for sachet and aluminum tube formats in German retail. |
| Direct-to-Athlete Subscription Launch | Sweat-testing data integration captures recurring revenue from marathon trainers in Austin and Boulder innovation clusters. |
| Clinical Channel Penetration | Hospital and long-term care facility partnerships unlock medical-grade electrolyte solutions with precise mineral ratios. |
Study Parameters
Independent corroboration across primary interviews with beverage formulation scientists, regulatory affairs directors, sports nutrition brand managers, and endurance athlete coaches, alongside secondary validation through FDA labeling guidance documents, EFSA electrolyte concentration evaluations, EPA water quality standards, and Amazon subscription velocity data, underwrites the qualitative findings. Bottom-up demand modeling from product-type and end-user segmentation triangulates against top-down macroeconomic indicators across the hydration products sector.
Comparable-period anchoring to historical adoption curves for sports nutrition and functional beverages establishes baseline trajectory assumptions across the projection horizon. The analytical framework models formulation technology, packaging format, distribution channel, and geographic regulatory cluster as core segmentation dimensions. CAGRs derive from volume-weighted growth rates applied to revenue pools, with electrolyte tablet portability trends and subscription displacement patterns serving as industry-specific forecast inputs.
Caveats apply where FDA sodium reduction mandates, EU F-Gas Regulation phase-down timelines, or electrolyte mineral supply disruptions could materially shift the outlook. Forecasts reflect assumptions about amateur athlete adoption rates and wearable technology integration trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Creatine Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Weight Management Products Market