
 Creatine Monohydrate Market | 2026-2036
Creatine Monohydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Creatine Monohydrate Market Analysis
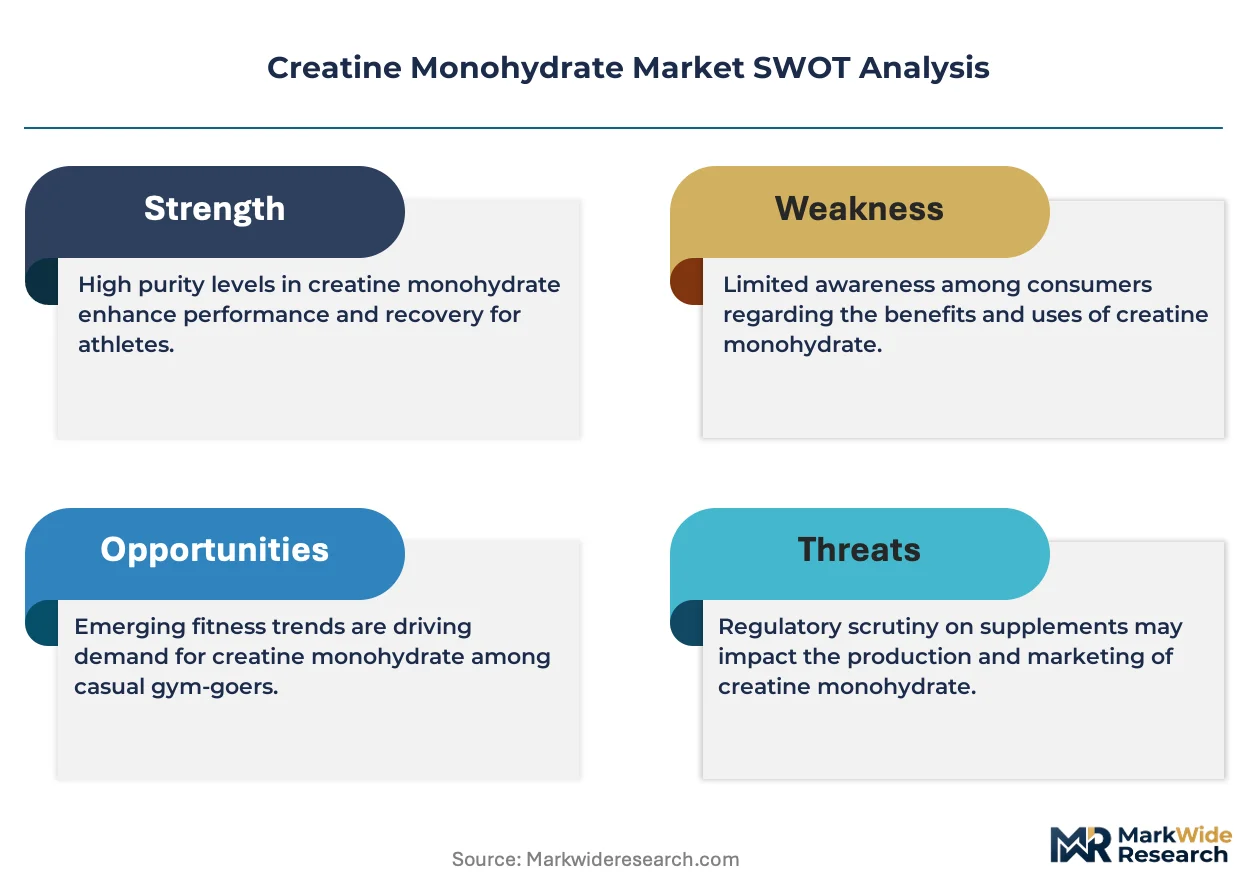
Fitness enthusiasts is bifurcating demand away from legacy bodybuilder-centric positioning toward broader wellness and cognitive performance claims. Transparent Labs leverages Creapure-sourced German manufacturing to anchor premium positioning in third-party tested formulations. Kaged Muscle competes through patented buffering technologies and Informed Sport certification that extends trust into collegiate and professional athletic channels. Optimum Nutrition dominates mass-market shelf presence through parent-company distribution infrastructure that controls placement in big-box retail and military exchanges.
Creatine monohydrate is a nitrogenous organic acid synthesized endogenously from arginine, glycine, and methionine, typically manufactured commercially via chemical synthesis or fermentation to yield a white crystalline powder with molecular formula C4H9N3O2 and minimum 99.9% purity in pharmaceutical-grade specifications. Its primary commercial purpose centers on rapid adenosine triphosphate regeneration in skeletal muscle tissue, supporting high-intensity exercise capacity and lean mass accretion. Powder formulations occupy the dominant volume position due to cost efficiency and dosing flexibility, while micronized variants command margin premiums through enhanced solubility and reduced gastrointestinal distress. Online retail channels represent the fastest-growing distribution vector, though specialty stores retain outsized influence in first-time buyer education and brand discovery.
The FDA's DSHEA framework and cGMP manufacturing requirements shape product labeling, adverse event reporting obligations, and facility inspection protocols for domestic and imported creatine supplements. NSF Certified for Sport and Informed Choice third-party testing standards increasingly function as de facto market access credentials for collegiate, military, and professional athletic procurement channels. Stakeholders must monitor evolving state-level age-restriction legislation and proposed FDA pre-market notification reforms that could reshape formulation transparency requirements and competitive barriers to entry.
Market Dynamics
Functional fitness enthusiasts now rival traditional strength athletes as the fastest-growing buyer archetype, forcing manufacturers to reposition formulations toward broader wellness and cognitive performance claims rather than legacy bodybuilder-centric marketing.
Growth Catalysts
- FDA's DSHEA framework:The dietary supplement regulatory structure enables rapid product iteration and market entry without pre-market approval, accelerating innovation cycles for domestic manufacturers.
- Micronization technology:Enhanced solubility processes reduce gastrointestinal distress and expand addressable populations beyond hardcore athletes to casual gym-goers and aging wellness consumers.
- China's NMPA dietary supplement registration pathway:Evolving GB standards for sports nutrition create compliant import channels that unlock access to the world's second-largest consumer base.
Market Restraints
- Raw material supply concentration:Pharmaceutical-grade creatine synthesis depends on concentrated chemical precursor supply chains concentrated in East Asian manufacturing hubs, exposing margins to input volatility.
- Fermentation process limitations:Biological production methods face yield ceilings and contamination risks that constrain output scaling relative to chemical synthesis alternatives.
- State-level age-restriction legislation:Proposed minimum purchase ages for performance supplements in multiple US jurisdictions threaten to compress the adolescent and young adult demographic entry funnel.
Strategic Opportunities
- Cognitive performance positioning:Emerging research on creatine's nootropic effects opens white space in professional and academic productivity segments beyond traditional exercise applications.
- Direct-to-consumer subscription models:Recurring revenue structures pioneered in US gym culture markets enable customer lifetime value expansion and inventory predictability.
- India's FSSAI sports nutrition category formalization:Regulatory clarity in the world's most populous nation creates first-mover advantages for compliant international entrants.
Industry Challenges
- Third-party certification timelines:NSF Certified for Sport and Informed Choice testing protocols require 8-12 week validation cycles that delay product launches and tie up working capital.
- Collegiate procurement compliance:Athletic department purchasing departments demand batch-specific documentation that strains legacy quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatine Monohydrate Market |
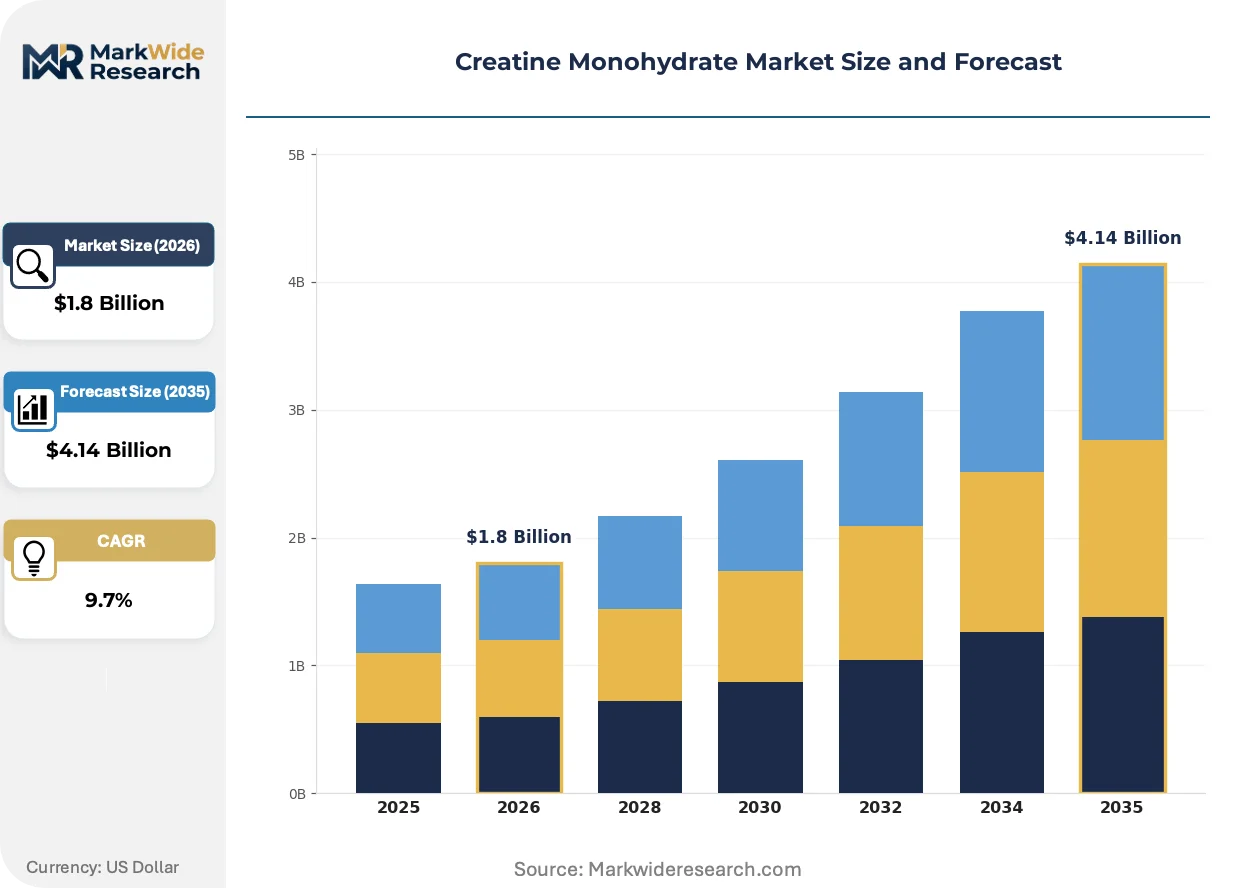
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Tablets, Chews End User: Athletes, Bodybuilders, Fitness Enthusiasts, Casual Users Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Gyms Form: Instantized, Micronized, Non-Micronized, Blended |
| Companies Covered | Transparent Labs, Legion Athletics, Thorne, Jocko Willink, Kaged Muscle, ATP Science, Optimum Nutrition, MyProtein, Switch Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatine Monohydrate Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how creatine reaches end-users, with purity signaling and channel specialization replacing commodity competition.
Micronized and buffered creatine variants are displacing standard monohydrate powder in premium positioning. Functional fitness enthusiasts and aging wellness consumers now prioritize solubility and stomach tolerance over raw cost efficiency. This shift compresses margin structures for undifferentiated bulk suppliers while rewarding German-manufactured Creapure-sourced formulations with pricing power.
China's evolving GB standards for sports nutrition are forcing reformulation transparency on imported products. The NMPA dietary supplement registration pathway now demands full ingredient disclosure and stability documentation that exceeds legacy self-certification norms. European manufacturers with existing pharmaceutical-grade documentation are best positioned to navigate this compliance escalation.
Specialty retail discovery is yielding to algorithm-driven online replenishment for repeat purchasers. First-time buyers still rely on brick-and-mortar education, but subscription direct-to-consumer models now capture the majority of volume in the United States. Military exchanges and collegiate bookstores remain holdout channels where in-person curation drives trial conversion.
Creatine Monohydrate Market Segmentation
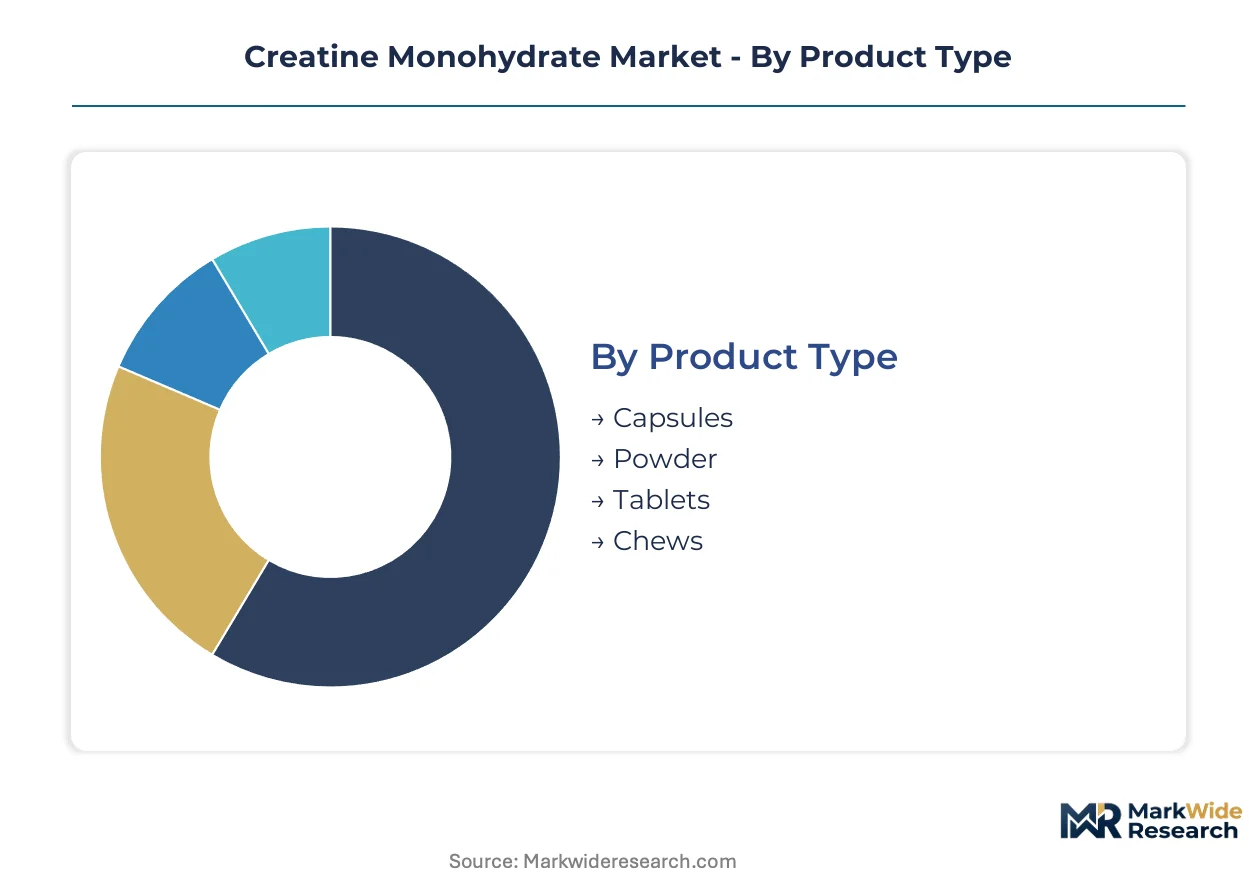
Creatine monohydrate segmentation reveals divergent supply chain configurations across product formats, with powder dominating domestic manufacturing while instantized variants depend on German and Chinese import channels. End-user bifurcation between performance athletes and wellness consumers forces parallel distribution architectures. Channel specialization now determines margin capture more than raw material sourcing.
Product Type:
Powder formulations anchor domestic production across the United States, Germany, and China, while capsules and novel formats rely disproportionately on contract manufacturing in India and Southeast Asian hubs. Export-led segments concentrate in pharmaceutical-grade synthesis corridors.
- Powder:Standard crystalline monohydrate manufactured via chemical synthesis or fermentation yields bulk material with 99.9% purity specifications. Demand concentrates in United States direct-to-consumer subscription channels, where cost-per-serving efficiency and dosing flexibility drive household penetration among functional fitness enthusiasts. Raw material supply concentration in East Asian hubs exposes margin volatility.
- Capsules:Pre-measured gelatin or vegetable cellulose shells encapsulate micronized powder for convenience-oriented users. Demand clusters in European markets where EFSA health claim regulations favor finished-dose formats with standardized labeling. German manufacturers leverage Creapure sourcing to command premium positioning.
- Tablets:Compressed formulations with binding agents for portability-focused consumers. Production concentrates in Indian pharmaceutical contract manufacturing facilities serving price-sensitive export markets.
- Chews:Flavored gummy matrices targeting adolescent and young adult demographics with taste-masked delivery. Manufacturing depends on confectionery-capable facilities in China and Brazil facing emerging state-level age-restriction compliance burdens.
Powder holds the largest share; momentum sits with chews as flavor technology and cognitive performance positioning expand addressable populations beyond traditional athletes.
End User:
Cost tier stratification separates premium pharmaceutical-grade positioning for competitive athletes from economy-tier formulations targeting casual wellness consumers. Margin structures diverge sharply across these archetypes.
- Athletes:Collegiate, professional, and Olympic competitors requiring NSF Certified for Sport or Informed Choice batch validation. Procurement concentrates in United States military exchanges and athletic department purchasing departments with documentation-intensive compliance protocols. Third-party certification timelines create eight-to-twelve-week validation cycles that strain working capital.
- Bodybuilders:Legacy strength sports participants prioritizing lean mass accretion and high-intensity capacity. Demand clusters in specialty retail discovery channels where in-person curation drives trial conversion and brand loyalty formation.
- Fitness Enthusiasts:Functional fitness practitioners and CrossFit participants representing the fastest-expanding buyer archetype. Demand concentrates in online subscription replenishment models pioneered in United States gym culture markets.
- Casual Users:Aging wellness consumers and cognitive performance seekers prioritizing solubility and stomach tolerance over raw cost efficiency. Micronized variants capture disproportionate share in this segment.
Bodybuilders retain the largest established share; fitness enthusiasts are climbing the fastest as wellness positioning displaces legacy strength-centric marketing.
Distribution Channel:
Volume concentration increasingly favors algorithm-driven replenishment, though geographic variation persists in first-touch discovery mechanisms. Channel economics determine working capital intensity and customer acquisition cost structures.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing majority volume in United States markets. Subscription models enable inventory predictability and lifetime value expansion. China's Tmall and JD Health platforms unlock access for compliant international entrants navigating NMPA registration pathways.
- Specialty Stores:Vitamin Shoppe, GNC, and independent supplement retailers retaining outsized influence in first-time buyer education. Brick-and-mortar discovery remains critical in Germany and France where pharmacist consultation shapes purchase decisions.
- Supermarkets:Mass-market shelf placement controlled by parent-company distribution infrastructure in big-box retail. Placement economics favor undifferentiated bulk suppliers with scale manufacturing in China.
- Gyms:On-site vending and pro-shop distribution capturing impulse replenishment from training-adjacent consumers. Military exchanges and collegiate bookstores represent holdout institutional channels with in-person curation requirements.
Specialty stores hold the largest share in established markets; online retail is gaining share fastest as subscription infrastructure matures.
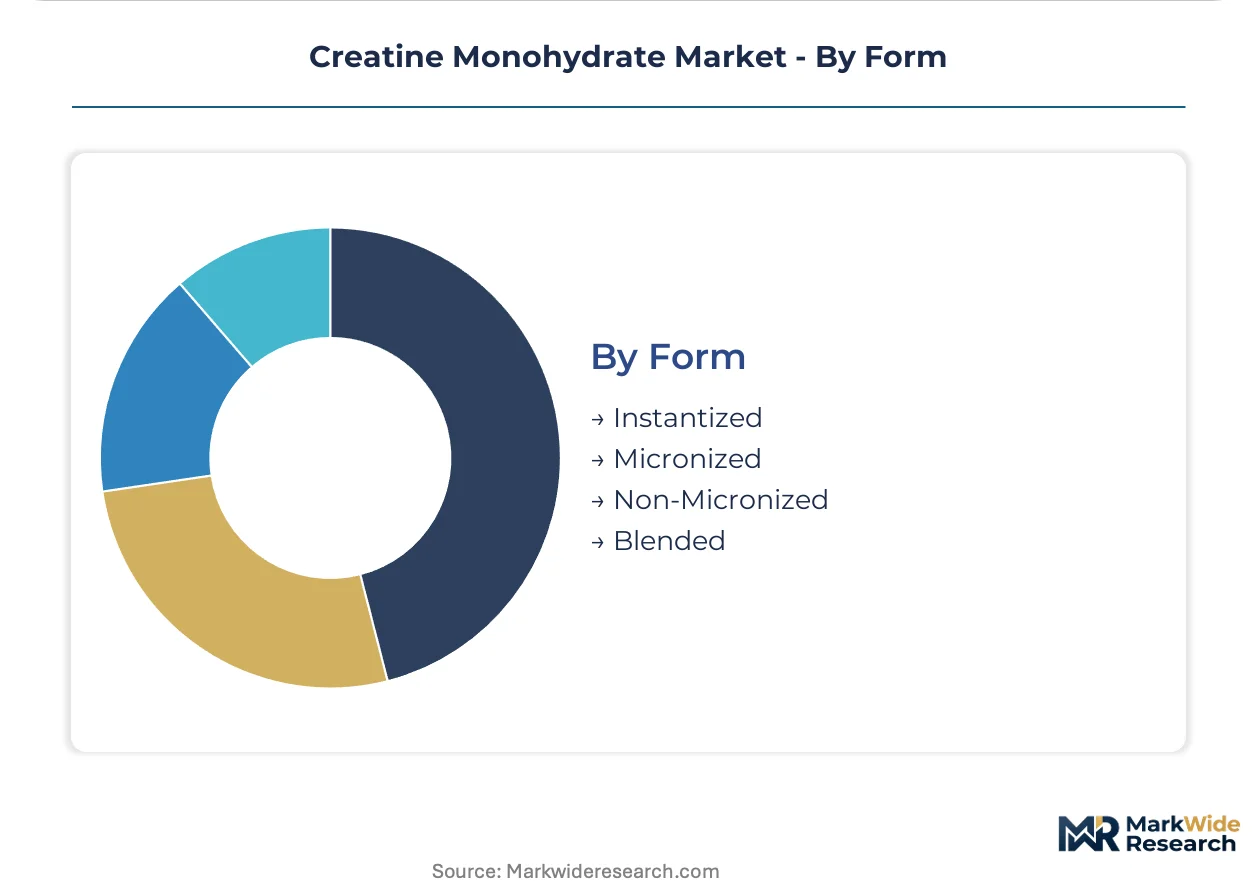
Form:
Supply concentration in pharmaceutical-grade synthesis corridors shapes competitive access to micronization and instantization technologies. Technology leadership determines solubility performance and gastrointestinal tolerance profiles.
- Micronized:Particle size reduction to 20 mesh or finer enhances dissolution kinetics and reduces osmotic gastrointestinal distress. German-manufactured Creapure-sourced formulations command pricing power in premium positioning. Demand concentrates among aging wellness consumers and female users historically excluded by tolerance barriers.
- Instantized:Surface-modified particles with hydrophilic coatings enabling cold-water dispersion without mechanical agitation. Production depends on specialized spray-drying capabilities concentrated in European and North American contract manufacturing facilities.
- Non-Micronized:Standard crystalline monohydrate with larger particle size and lower production cost. Demand clusters in price-sensitive bulk purchasing in developing markets and commercial gym distribution.
- Blended:Co-formulations with carbohydrates, electrolytes, or nootropic compounds targeting specific use cases. India's FSSAI sports nutrition category formalization creates first-mover advantages for compliant international entrants with blended product pipelines.
Non-micronized holds the largest share; micronized forms show the steepest expansion trajectory as solubility prioritization reshapes premium tier composition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade creatine synthesis clusters in East Asian chemical manufacturing corridors, with downstream formulation and brand development concentrating in North American and European consumer markets. This bifurcation creates distinct competitive dynamics across production and consumption geographies.
United States
Gym culture penetration and direct-to-consumer subscription infrastructure generate the world's deepest per-capita creatine consumption base. The FDA's DSHEA framework enables rapid product iteration without pre-market approval, accelerating domestic manufacturer innovation cycles. Military exchanges and collegiate bookstores in Texas, California, and Florida serve as institutional channels with in-person curation requirements.
Germany
EFSA health claim regulations favor finished-dose formats with standardized labeling, driving demand for capsule and precision-dosed products. Creapure-sourced manufacturing from AlzChem Trostberg GmbH anchors premium positioning through pharmaceutical-grade purity documentation. The Bavarian chemical cluster supplies precursor materials to European formulation facilities.
China
NMPA dietary supplement registration pathways and evolving GB standards for sports nutrition reshape compliance requirements for imported formulations. Domestic manufacturing concentrates in Jiangsu and Zhejiang provinces, where chemical synthesis facilities supply global raw material demand. Tmall and JD Health platforms unlock market access for compliant international entrants.
India
FSSAI sports nutrition category formalization creates first-mover advantages for compliant international entrants with blended product pipelines. Contract manufacturing facilities in Maharashtra and Gujarat produce tablets and capsules for price-sensitive export markets. Mumbai and Ahmedabad serve as distribution hubs for South Asian regional supply.
Australia
TGA therapeutic goods regulations impose stringent manufacturing practice standards on domestic and imported supplements. Demand clusters in Sydney and Melbourne fitness communities, where functional fitness enthusiasts drive micronized variant adoption. Local brands leverage proximity to Asian raw material sources for cost-competitive formulation.
Creatine Monohydrate Market Vendor Landscape
Concentration sits with parent-company distribution infrastructure controlling mass-market shelf placement, while specialty and premium tiers fragment across third-party tested and certified sport positioning. Three archetypes dominate: multinational CPG conglomerates with retail leverage, pure-play sports nutrition specialists with certification depth, and direct-to-consumer brands with subscription infrastructure. Competitive moves center on M&A for distribution access and strategic partnerships for raw material security.
Within the certification-forward specialist tier, Transparent Labs leverages Creapure-sourced German manufacturing to anchor premium positioning, while Kaged Muscle competes through patented buffering technologies and Informed Sport certification. Optimum Nutrition represents the scale-driven multinational archetype, dominating mass-market shelf presence through parent-company distribution infrastructure. These three exemplify how purity signaling and channel specialization now replace commodity competition in formulation science.
| Leading Market Players |
|---|
| Transparent Labs |
| Legion Athletics |
| Thorne |
| Jocko Willink |
| Kaged Muscle |
| ATP Science |
| Optimum Nutrition |
| MyProtein |
| Switch Nutrition |
| Others |
Supply Flow & Price Mechanics
NSF Certified for Sport and Informed Choice batch validation gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb certification costs that stratify market access while enabling premium capture in collegiate and professional athletic procurement channels. Pharmaceutical-grade purity documentation from German-manufactured Creapure-sourced formulations commands pricing power that undifferentiated bulk suppliers cannot replicate, compressing margin structures for commodity entrants.
Pricing Analysis
FDA's DSHEA framework dictates the pricing tier structure by enabling rapid product iteration without pre-market approval, which accelerates domestic manufacturer innovation cycles while allowing three-tier pricing structure across premium, standard, and economy levels to emerge organically. Price differentiation rests on certification grade and brand premium, with Creapure-sourced formulations capturing margin premiums against standard crystalline monohydrate. Cost compression in economy tiers is intensifying because raw material supply concentration in East Asian hubs exposes margins to input volatility. Casual users and aging wellness consumers show highest price sensitivity, while athletes requiring NSF Certified for Sport documentation exhibit lowest sensitivity due to procurement compliance mandates.
Supply Chain Analysis
Shanghai Port throughput and Ningbo-Zhoushan chemical terminal capacity underwrite global pharmaceutical-grade creatine raw material flows, with downstream formulation concentrating in North American and European consumer markets. Supply concentrates in Jiangsu and Zhejiang provinces of China, with secondary manufacturing corridors in Bavaria, Germany and Maharashtra, India. Chemical precursor dependencies include cyanamide, sarcosine, and methylamine feedstocks. Single-source vulnerability from concentrated East Asian synthesis exposes margins to geopolitical friction and logistics disruption. Distribution runs through direct-to-consumer subscription platforms for repeat volume, with specialty retail retaining first-touch discovery influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional fitness enthusiasts represent an early-cycle expansion story as wellness positioning displaces legacy strength-centric marketing, with cognitive performance claims opening white space beyond traditional exercise applications.
For Market Incumbents: Secure Creapure-sourced supply agreements and Informed Sport certification depth to defend against emerging direct-to-consumer brands with subscription infrastructure. Backward integration into pharmaceutical-grade synthesis capabilities in Germany or captive supply arrangements with AlzChem Trostberg GmbH anchors premium positioning. Channel control through military exchanges and collegiate bookstore procurement relationships protects against algorithm-driven replenishment disintermediation.
For New Entrants and Emerging Players: Lead with cognitive performance positioning targeting professional and academic productivity segments where nootropic claims face lower regulatory scrutiny than exercise performance marketing. India's FSSAI sports nutrition category formalization offers the most penetrable geography for compliant international entrants with blended product pipelines. Direct-to-consumer subscription models with batch-specific documentation transparency enable bypass of incumbent-controlled retail shelf space.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across micronization and instantization technology tiers as solubility prioritization reshapes premium tier composition. Long-term viability favors acquisition targets with existing pharmaceutical-grade documentation and NMPA registration pathway experience for China market access. Watch for inflection signals in state-level age-restriction legislation that would compress the adolescent demographic entry funnel and reshape addressable market calculations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmaceutical-Grade Synthesis | Captive supply of Creapure-sourced material from AlzChem Trostberg GmbH eliminates raw material volatility exposure. |
| NMPA Registration Pathway Completion | Full ingredient disclosure and stability documentation unlocks Tmall and JD Health platform access for China market entry. |
| Direct-to-Consumer Subscription Launch | Recurring revenue structures pioneered in United States gym culture markets enable customer lifetime value expansion. |
| Informed Sport Certification Investment | Eight-to-twelve-week validation cycles create procurement credentials for collegiate and professional athletic channels. |
| Cognitive Performance Product Line Extension | Nootropic positioning opens professional and academic productivity segments beyond traditional exercise applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with sports nutrition formulators, athletic department procurement managers, contract manufacturing facility directors, and specialty retail category buyers. Secondary validation drew from FDA cGMP inspection records, NSF Certified for Sport product listings, NMPA dietary supplement registration databases, and customs trade data for creatine monohydrate raw material flows. Bottom-up volume modeling from end-user segment penetration rates triangulated against top-down value estimates from parent-company revenue disclosures and channel-specific pricing intelligence.
Across the analysis window, the quantitative framework modeled segmentation dimensions including product format, end-user archetype, distribution channel, and pharmaceutical-grade versus food-grade purity tier. CAGRs were derived from historical consumption trajectory analysis adjusted for adoption curve inflection points in functional fitness and cognitive performance positioning. Forecast inputs incorporated NMPA registration pathway timeline assumptions and state-level age-restriction legislative probability weightings.
The analysis sits within stated boundaries; outcomes outside sustained DSHEA framework stability and continued China-United States trade flow normalization would require recalibration. Forecasts reflect documented assumptions regarding certification timeline standardization and raw material supply concentration persistence. Practitioners should keep alternative scenarios live as NMPA GB standards evolution and proposed FDA pre-market notification reforms advance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Creatine Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
United States Weight Management Market