
 South America Sports Drinks Market | 2026-2036
South America Sports Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
South America Sports Drinks Market Analytics
Beverage formulation talent is rotating toward electrolyte-specific expertise as manufacturers respond to regional heat-stress consumption patterns. The Coca-Cola Company leverages its bottling infrastructure to sustain distribution depth in Andean markets. Ambev anchors Brazilian production capacity through captive supply of purified water and mineral sourcing. AJE Group competes on price-accessible formats across Peru and Ecuador.
South America sports drinks are aqueous beverages containing dissolved carbohydrates, electrolytes, and flavoring agents formulated to osmolarity specifications between 250 and 350 mOsm/L for rapid gastric emptying during exertion. Isotonic formulations dominate volume as they match human plasma osmolarity, while protein-fortified variants capture expanding margin pools from post-workout recovery positioning. Fitness enthusiasts and health-conscious individuals drive category expansion, with supermarkets and convenience stores controlling the bulk of physical distribution throughput despite online retailer growth in metropolitan zones.
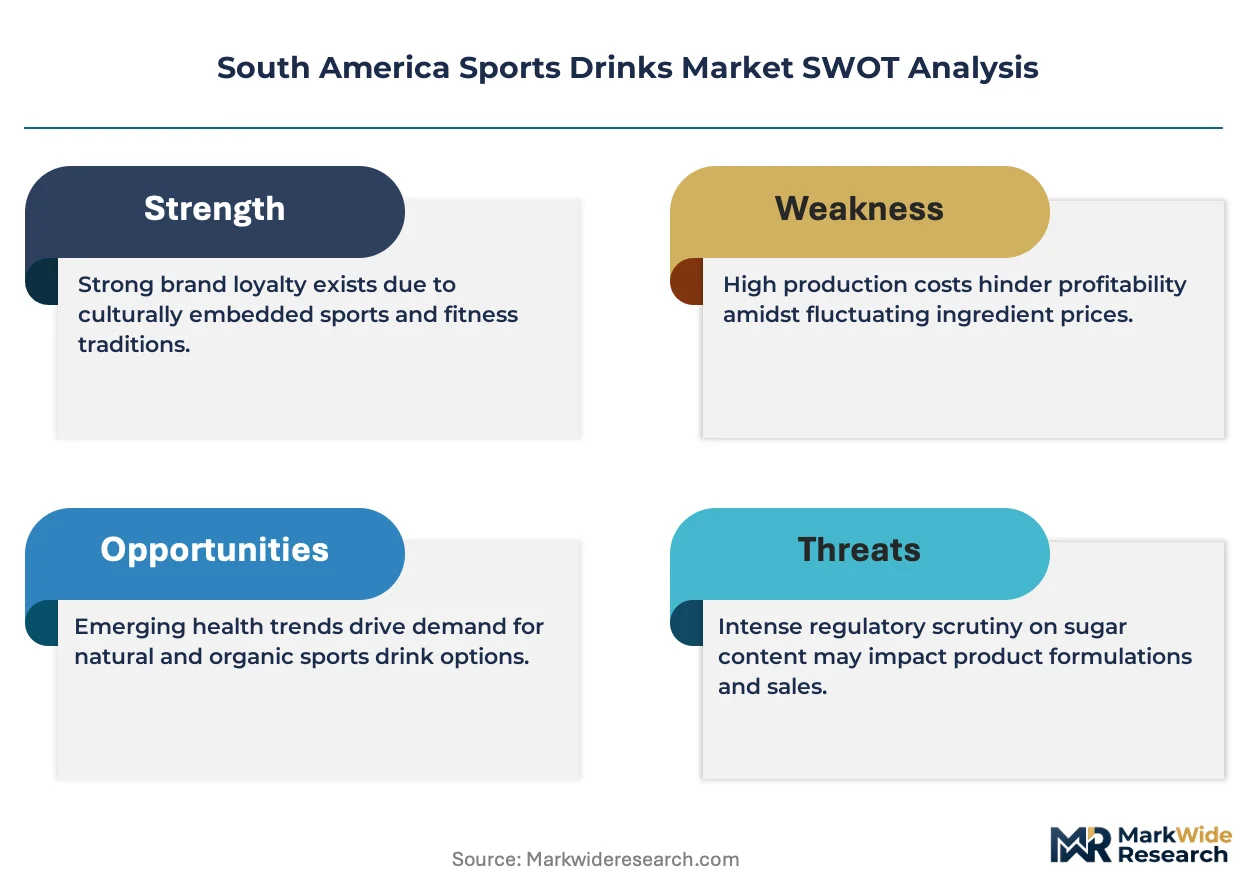
ANVISA governs electrolyte claim thresholds and additive permissions in Brazil, while Chile's national pharmaceutical regulator enforces parallel beverage labeling standards that shape cross-border formulation strategies. Argentina's food safety authority maintains distinct mineral-content disclosure rules that fragment compliance architectures for multinational producers. Stakeholders must monitor regulatory divergence between Mercosur harmonization talks and national-level enforcement tightening to anticipate reformulation costs and market access timelines.
Market Dynamics
ANVISA electrolyte-labeling mandates are compressing formulation timelines across Brazilian manufacturing plants while simultaneously elevating technical barriers for new entrants seeking shelf placement in the category's largest revenue corridor.
Growth Catalysts
- ANVISA Compliance Thresholds:Brazil's tightened mineral-content disclosure rules are forcing incumbent manufacturers to reformulate around documented electrolyte specifications, inadvertently raising quality floors that benefit established producers with captive R&D infrastructure.
- Heat-Stress Consumption Patterns:Recreational athletes in Brazil's interior states are consuming sports drinks during non-competitive exertion, expanding addressable occasions beyond organized athletics into occupational and leisure hydration.
- Isotonic Formulation Dominance:Plasma-matched osmolarity specifications between 250 and 350 mOsm/L are becoming the default technical standard, simplifying procurement decisions for institutional buyers in collegiate and amateur sports programs.
Market Restraints
- Purified Water Supply Concentration:Captive mineral sourcing and reverse-osmosis capacity in Brazil's southeastern corridor creates geographic dependency that amplifies cost volatility during regional drought cycles.
- Cross-Border Regulatory Fragmentation:Argentina's distinct mineral-content disclosure rules force parallel formulation tracks, inflating compliance architecture costs for producers serving multiple Mercosur markets.
- Natural Hydration Substitutes:Coconut water and fresh-fruit juice vendors in coastal Brazilian cities are capturing price-sensitive consumers through unregulated informal distribution networks.
Strategic Opportunities
- Secondary City Gym Penetration:Fitness center expansion in Curitiba, Belo Horizonte, and Porto Alegre is creating first-mover positioning for sports drink brands ahead of infrastructure maturation.
- Protein-Fortified Recovery Positioning:Post-workout consumption occasions remain underdeveloped relative to intra-workout hydration, offering margin expansion through functional ingredient differentiation.
- Convenience Store Channel Integration:Petrobras BR Distribuidora and Ipiranga retail networks are expanding refrigerated grab-and-go capacity along Brazil's federal highway system.
Industry Challenges
- Electrolyte-Specific Formulation Talent Scarcity:Beverage chemists with osmolarity optimization expertise command premium compensation in São Paulo's tight labor market, constraining R&D velocity for mid-tier producers.
- Refrigerated Distribution Capex Requirements:Cold-chain integrity mandates for isotonic stability necessitate fleet and storage infrastructure investments that strain working capital for regional challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Sports Drinks Market |
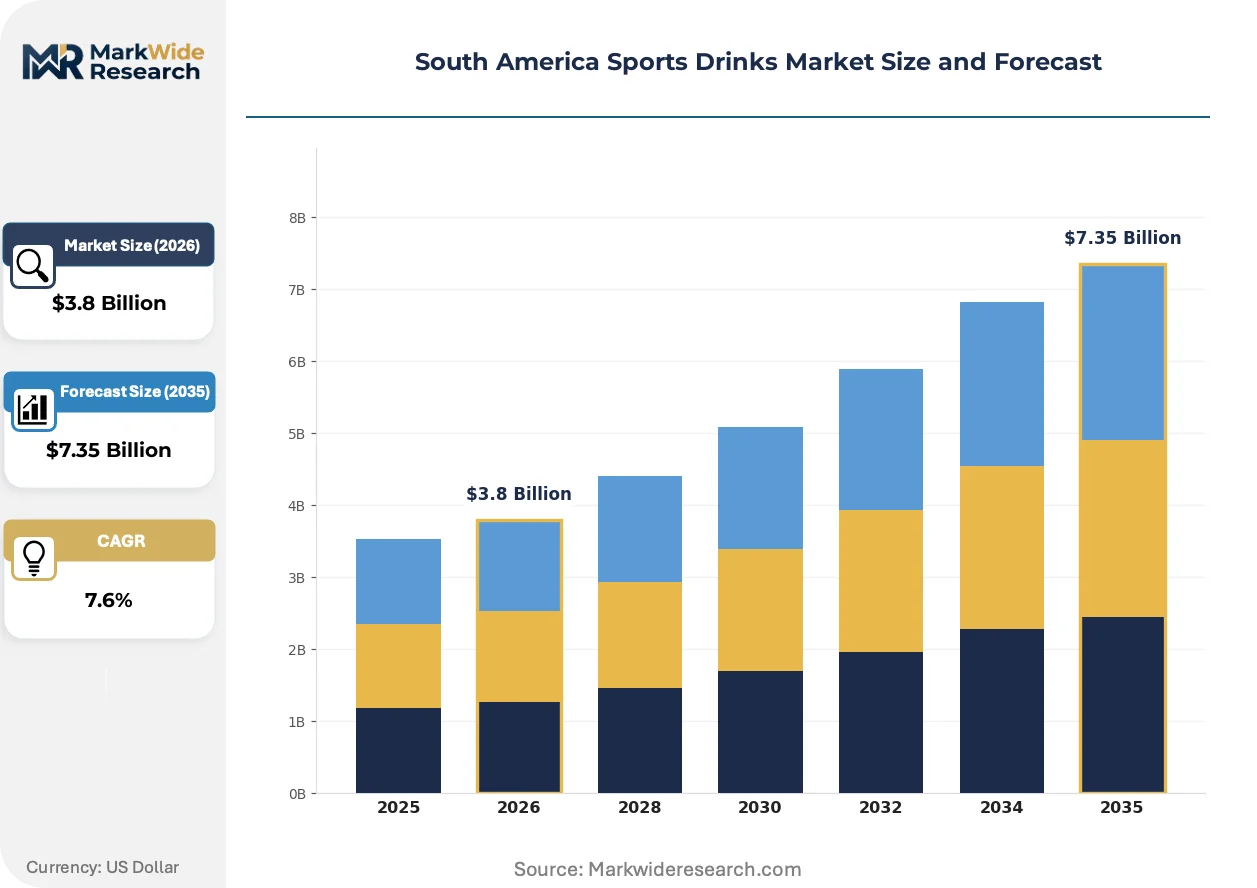
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Protein End User: Athletes, Fitness Enthusiasts, Casual Consumers, Health-conscious Individuals Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Stores Flavor: Citrus, Berry, Tropical, Cola |
| Companies Covered | PepsiCo Inc., The Coca-Cola Company, AJE Group, Grupo Petrópolis, Electrolit USA, Ambev, Genomma Lab, BodyArmor, Suntory Beverage & Food Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Sports Drinks Market Evolving Landscape
Formulation science and regulatory disclosure requirements are converging to reshape product architecture, with functional ingredient transparency emerging as the primary vector of competitive differentiation in shelf placement negotiations.
Electrolyte micro-encapsulation technology is enabling staged mineral release during extended exertion. Marathon runners and ultracyclists in Chile's Atacama Desert events are early adopters of these formats. This functionality is miniaturizing the boundary between sports drinks and specialized endurance nutrition, compressing adjacent category distinctions.
Chile's national pharmaceutical regulator is enforcing parallel beverage labeling standards that exceed Mercosur baseline requirements. Manufacturers are consolidating SKUs to reduce packaging complexity across the Andean corridor. Premium isotonic lines bear the brunt of reformulation costs as they target pharmacy and specialty retail channels.
Health-conscious individuals are scrutinizing additive declarations with greater intensity than caloric content. Supermarket buyers in São Paulo's Zona Sul are privileging shorter ingredient lists in shelf-reset negotiations. This preference shift is most visible among purchasers aged 25-34 in Brazil's highest-income postal code clusters.
South America Sports Drinks Market Segmentation
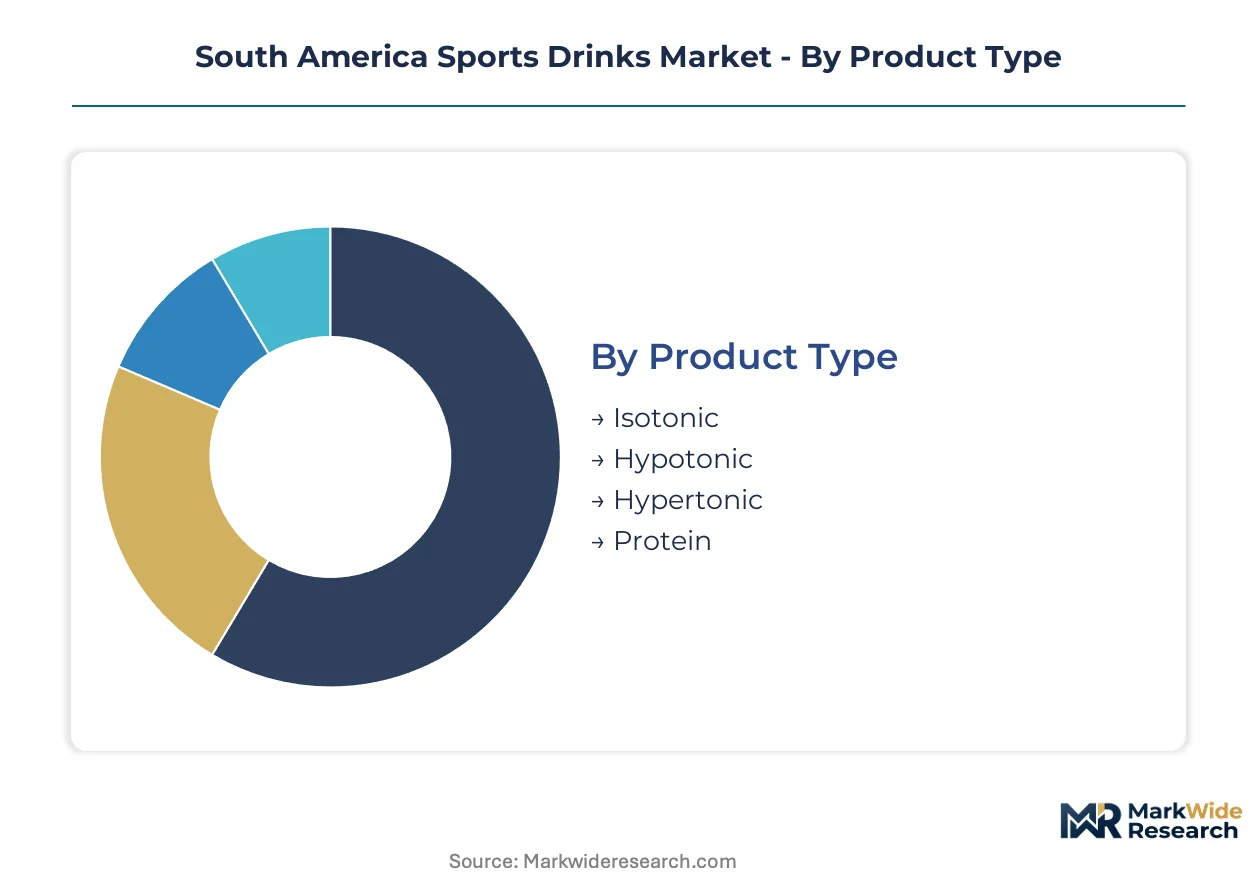
Margin capture in South America sports drinks hinges on precise alignment between osmolarity specifications and consumption occasion. Category segmentation reveals where formulation investments translate into price premiums versus volume throughput.
Product Type:
Isotonic formulations command the deepest margin pools due to plasma-matched osmolarity specifications that justify technical premiums in pharmacy and specialty channels.
- Isotonic:Formulations calibrated to 250-350 mOsm/L match human plasma osmolarity for rapid gastric emptying during exertion. Brazilian collegiate athletic programs in São Paulo state concentrate procurement around this specification, compressing competitive differentiation to flavor stability and cold-chain reliability.
- Protein:Post-workout recovery positioning carries ingredient cost premiums that manufacturers recapture through functional claims in gym-channel distribution. Curitiba and Belo Horizonte fitness center expansion is accelerating trial rates among consumers seeking meal-replacement adjacency.
- Hypotonic:Lower solute concentration targets rapid fluid absorption without carbohydrate loading.
- Hypertonic:High-energy formulations serve endurance athletes requiring concentrated carbohydrate delivery.
The dominant share belongs to Isotonic, while Protein is closing the gap fastest.
End User:
Volume concentration tracks gym infrastructure penetration, with secondary city expansion rewriting geographic demand maps.
- Fitness Enthusiasts:Gym-culture adoption in Brazil's interior states—Cuiabá, Goiânia, Campo Grande—extends addressable occasions beyond competitive athletics into occupational hydration. ANVISA-compliant electrolyte claims resonate strongly with this segment's ingredient-list scrutiny.
- Athletes:Organized sports programs maintain institutional procurement discipline around documented osmolarity specifications. Chile's Atacama Desert endurance events are incubating demand for staged-release electrolyte formats among ultracyclists and marathon runners.
- Casual Consumers:Heat-stress hydration drives impulse purchases along Brazil's federal highway retail networks.
- Health-conscious Individuals:São Paulo Zona Sul supermarket buyers privilege shorter additive declarations over caloric content.
Fitness Enthusiasts anchor volume expansion, while Athletes sustain premium pricing through technical specification adherence.
Distribution Channel:
Cold-chain capex requirements stratify channel economics, favoring incumbents with captive refrigerated fleet assets.
- Supermarkets:Refrigerated shelf-reset negotiations in São Paulo's highest-income postal codes privilege brands with transparent ingredient declarations. Buyers aged 25-34 are compressing SKU complexity through shorter-list preferences.
- Convenience Stores:Petrobras BR Distribuidora and Ipiranga networks are expanding grab-and-go capacity along Brazil's federal highway system, capturing heat-stress consumption during long-haul transport and leisure travel.
- Online Retailers:Metropolitan zone growth concentrates in São Paulo and Rio de Janeiro state markets.
- Health Stores:Pharmacy-channel placement demands exceed Mercosur baseline labeling standards.
Supermarkets control physical throughput, while Convenience Stores are gaining share fastest through highway-network integration.
Flavor:
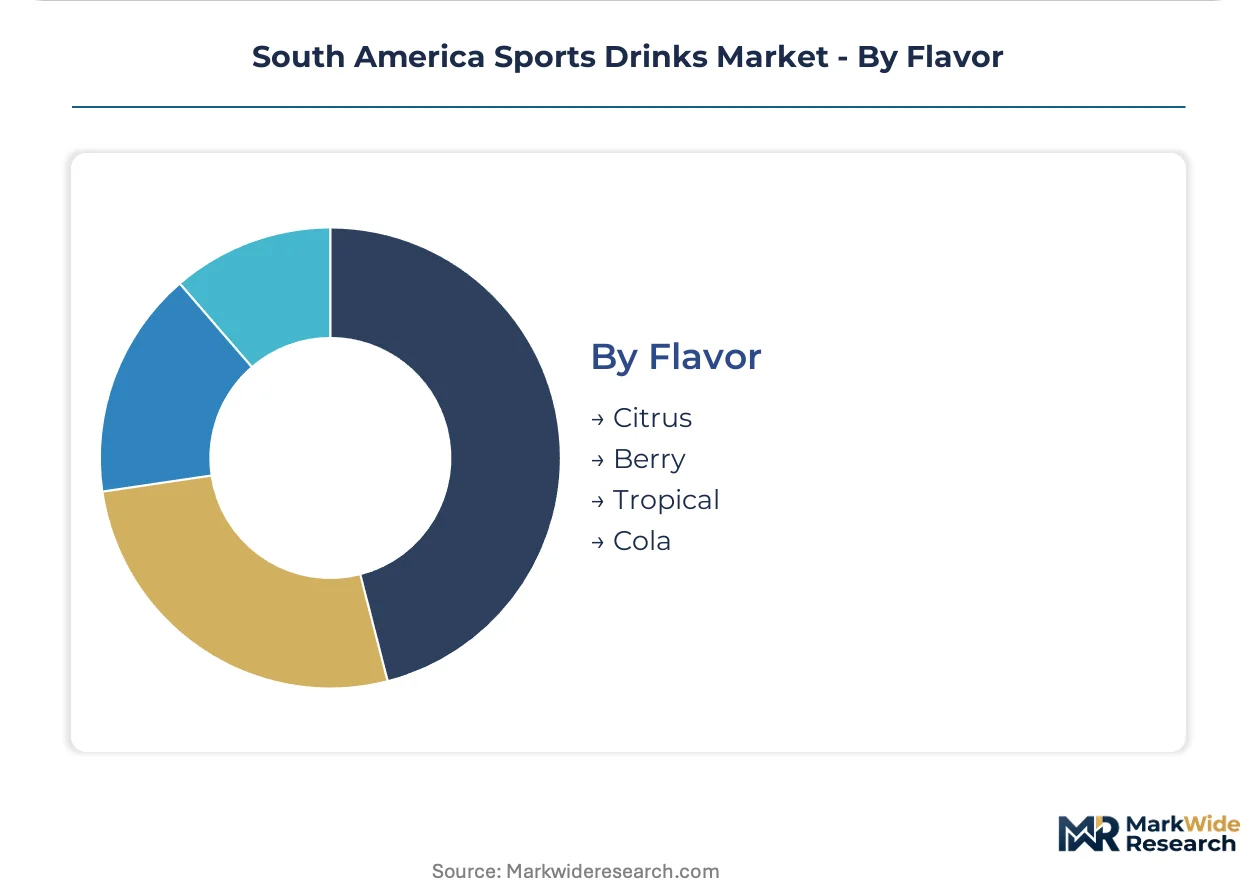
Regional taste preferences and ingredient cost structures determine formulation economics across production runs.
- Citrus:Limão and laranja profiles dominate Brazilian mass-market SKUs, leveraging local citrus supply chains for cost containment. ANVISA-compliant natural flavor claims are elevating technical barriers for synthetic alternatives.
- Berry:Açaí and mixed-berry positioning targets health-conscious positioning in specialty retail. Chilean pharmacy-channel buyers show preference concentration in this profile.
- Tropical:Maracujá and coconut-adjacent flavors compete directly with informal coconut water vendors in coastal cities.
- Cola:Legacy flavor profile retains loyalty among casual consumers seeking carbonated alternatives to conventional soft drinks.
Citrus holds the dominant share, while Berry is expanding most quickly through health-channel premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA electrolyte-labeling mandates in Brazil are compressing formulation timelines across manufacturing plants while elevating technical barriers for new entrants seeking shelf placement in the category's largest revenue corridor.
Brazil
Fitness center expansion in Curitiba, Belo Horizonte, and Porto Alegre creates first-mover positioning for sports drink brands ahead of infrastructure maturation. ANVISA governs electrolyte claim thresholds and additive permissions, forcing incumbent manufacturers to reformulate around documented specifications. São Paulo's southeastern corridor anchors volume concentration, with refrigerated distribution networks penetrating secondary cities.
Argentina
Organized sports programs maintain institutional procurement discipline around documented osmolarity specifications for collegiate athletics. The national food safety authority maintains distinct mineral-content disclosure rules that fragment compliance architectures for multinational producers. Buenos Aires metropolitan buyers privilege shorter ingredient lists in shelf-reset negotiations.
Chile
Marathon runners and ultracyclists in Atacama Desert endurance events incubate demand for staged-release electrolyte formats. The national pharmaceutical regulator enforces parallel beverage labeling standards that exceed Mercosur baseline requirements. Santiago pharmacy-channel placement demands stricter additive transparency than mass-market retail.
Peru
Price-accessible formats capture expanding consumer bases in Lima's emerging fitness culture. Informal coconut water vendors in coastal cities compete for heat-stress hydration occasions. Andean altitude training facilities drive specialized electrolyte demand among international athletic programs.
Colombia
Bogotá's gym infrastructure penetration extends addressable occasions beyond competitive athletics into occupational hydration. Cross-border regulatory divergence between Mercosur harmonization talks and national-level enforcement tightening complicates market access timelines. Medellín fitness center networks accelerate trial rates among health-conscious professionals.
South America Sports Drinks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on formulation differentiation and channel-specific positioning. The Coca-Cola Company and Ambev leverage captive bottling infrastructure and purified water supply chains to sustain distribution depth. Three archetypes dominate: multinational beverage conglomerates with captive R&D, regional specialists with mineral-sourcing advantages, and price-accessible challengers competing on format innovation. Competitive moves concentrate on refrigerated distribution capex expansion and protein-fortified portfolio diversification.
Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven archetypes with integrated bottling networks spanning Andean markets. Ambev anchors Brazilian production capacity through captive supply of purified water and mineral sourcing, representing the regional integrated leader archetype. AJE Group occupies a position within the price-accessible specialist tier across Peru and Ecuador.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Coca-Cola Company |
| AJE Group |
| Grupo Petrópolis |
| Electrolit USA |
| Ambev |
| Genomma Lab |
| BodyArmor |
| Suntory Beverage & Food Limited |
| Others |
Value Network & Pricing Analysis
Captive reverse-osmosis capacity in Brazil's southeastern corridor generates scale economies that simultaneously depress unit production costs and erect capital barriers against regional challengers seeking cold-chain parity. This concentration dynamic anchors price floors while amplifying margin volatility during drought cycles that constrain purified water feedstock.
Pricing Analysis
Long-term offtake agreements between Ambev and Brazil's purified water suppliers lock in baseline input costs, while spot-market exposure for mineral concentrates introduces formulation-cost variability. Three-tier pricing structure across premium isotonic, standard hydration, and economy dilutable formats separates pharmacy-channel positioning from highway retail. Pricing pressure stems from informal coconut water vendors in coastal cities capturing heat-stress occasions through unregulated distribution. Casual consumers along federal highway networks exhibit highest price sensitivity, while collegiate athletic programs demonstrate lowest sensitivity due to institutional procurement discipline around documented osmolarity specifications.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for citric acid and mineral concentrate shipments arriving from Argentina and Chile. Manufacturing concentration in Brazil, Argentina, and Chile draws from regional citrus supply chains, Chilean lithium-salt derivatives, and Argentine glucose-fructose syrup feedstocks. Single-source vulnerability in Brazil's southeastern purified water corridor feeds from drought-exposed reservoir systems. Distribution runs through refrigerated fleets controlled by Petrobras BR Distribuidora and Ipiranga networks, with secondary city penetration dependent on captive cold-storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA regulatory entrenchment creates defensive moats through reformulation cost barriers that favor incumbents with captive R&D infrastructure and documented electrolyte specification compliance.
For Market Incumbents: Secure mineral-sourcing contracts in Brazil's southeastern corridor before drought-cycle price spikes compress margins. Expand refrigerated distribution capacity along Curitiba-Belo Horizonte-Porto Alegre corridors ahead of gym infrastructure maturation. Threat of AJE Group price-accessible formats in Peru and Ecuador demands channel-control investment in highway retail networks. For New Entrants and Emerging Players: Post-workout protein-fortified recovery positioning in secondary Brazilian cities represents under-served white space where incumbent portfolio gaps persist. Target Curitiba and Belo Horizonte fitness center channels with functional ingredient transparency claims that resonate with ingredient-list scrutiny among 25-34 demographic buyers. Go-to-market through direct gym-channel partnerships bypasses supermarket shelf-reset negotiation barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with long-term institutional procurement contracts to collegiate athletic programs and federal highway retail networks. Five-to-ten year viability favors regional specialists with captive mineral sourcing and backward integration into purified water supply. Signal to monitor: ANVISA enforcement tightening on additive permissions that would force accelerated reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Micro-Encapsulation R&D | Staged-release technology captures ultracyclist demand in Chile's Atacama Desert endurance events. |
| Refrigerated Highway Retail Expansion | Petrobras BR Distribuidora network integration captures heat-stress consumption during long-haul transport. |
| Protein-Fortified Portfolio Diversification | Post-workout recovery positioning in Curitiba gyms expands margin pools beyond intra-workout hydration. |
| ANVISA Compliance Certification Investment | Documented electrolyte specifications secure pharmacy-channel placement exceeding Mercosur baselines. |
| Secondary City Gym-Channel Partnerships | First-mover positioning in Belo Horizonte and Porto Alegre precedes infrastructure maturation. |
Research Methodology
A spread of perspectives from beverage formulation chemists, ANVISA regulatory affairs specialists, supermarket category buyers, and fitness center procurement managers converged on the working assumptions. Primary interviews with São Paulo-based R&D directors and Chilean pharmacy-channel distributors combined with secondary validation through ANVISA disclosure filings, Brazilian customs mineral-import records, and collegiate athletic procurement databases. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Segmentation dimensions modeled include osmolarity specification tier, end-user archetype, distribution channel cold-chain requirement, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for gym infrastructure penetration rates and ANVISA compliance timeline impacts. Industry-specific inputs incorporated electrolyte claim threshold enforcement patterns and heat-stress consumption occasion expansion in Brazil's interior states.
Forecasts assume regulatory continuity in ANVISA, Chile's national pharmaceutical regulator, and Argentina's food safety authority regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Mercosur harmonization talks and national-level enforcement tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
United States Sports Drink Market