
 Europe Moringa Supplement Market | 2026-2036
Europe Moringa Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Moringa Supplement Market Intelligence
Modular dosing formats is pivoting buyer choice across the Europe Moringa Supplement Market, with single-serve sachets and stackable capsule systems displacing bulk powder jars. Grenera Nutrients Pvt. Ltd. leverages its extraction expertise to supply standardized leaf powders to European contract manufacturers. Bio Moringa Oleifera GmbH anchors its position through controlled cultivation partnerships in Mediterranean climates. Organic India Pvt. Ltd. differentiates via certified organic supply chains that satisfy stringent EU import requirements.
Moringa supplement denotes dried leaf powder, encapsulated extracts, or cold-pressed oil derived from Moringa oleifera, typically standardized to isothiocyanate and flavonoid content exceeding 10% by dry weight, serving antioxidant, anti-inflammatory, and macronutrient fortification purposes in human nutrition. Powder formulations lead volume throughput due to lower unit economics and broader food-service compatibility, while capsules capture concentrated margin pools from fitness enthusiasts seeking precise dosing. Online retail channels represent the fastest-growing distribution vector as direct-to-consumer brands bypass traditional health store markups across France and the Netherlands.
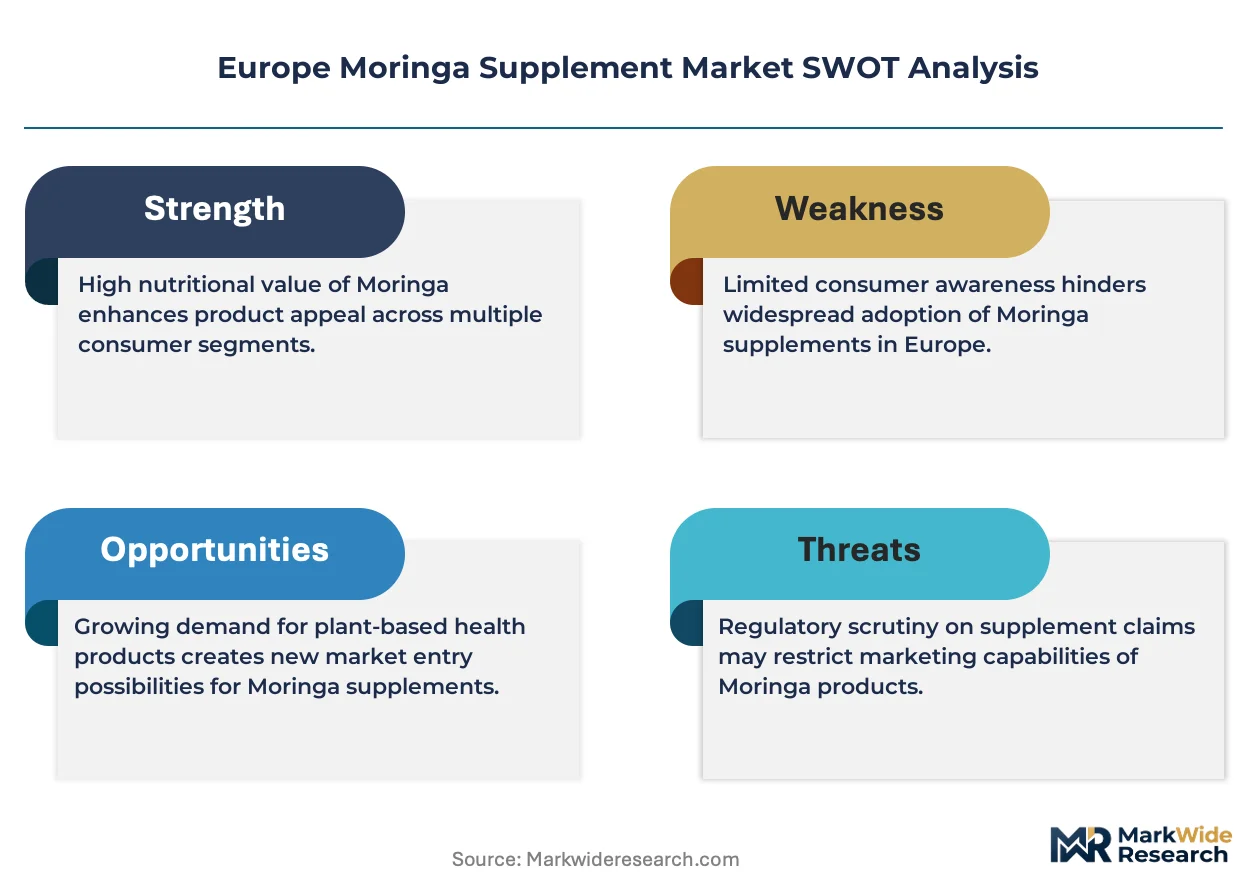
EFSA novel food assessments and EU Organic Regulation 2018/848 govern market access, with EMA pharmacovigilance frameworks increasingly scrutinizing bioactive supplement claims. REACH compliance for imported botanical extracts adds testing burdens that favor established suppliers with in-house analytical laboratories. Stakeholders must monitor evolving EFSA health claim opinions on isothiocyanates, as positive determinations would unlock pharmaceutical-adjacent positioning and reshape competitive investment priorities across the value chain.
Market Dynamics
Modular dosing formats are compressing traditional bulk powder economics across European nutraceutical channels, as single-serve sachets and stackable capsule systems displace jar-based purchasing patterns among health-conscious consumers seeking precise, portable supplementation.
Growth Catalysts
- EU Novel Food Regulation pathway clarity:Streamlined EFSA assessment procedures for Moringa oleifera leaf extracts are accelerating new entrant approvals, reducing time-to-market for standardized isothiocyanate formulations.
- Plant-based protein fortification demand:German and French food manufacturers are integrating moringa leaf powder into meat-alternative formulations, driven by clean-label sourcing requirements and amino acid completeness.
- Mediterranean cultivation partnerships:Controlled growing operations in Spain and Portugal are reducing import dependency on South Asian supply chains, improving lot-to-lot phytochemical consistency for contract manufacturers.
Market Restraints
- EFSA novel food assessment costs:Pre-market safety dossiers for new moringa-derived ingredients require toxicological studies exceeding €150,000, creating capital barriers for small-scale suppliers.
- REACH compliance burdens:Imported botanical extracts face analytical testing for residual solvents and heavy metals, favoring established European distributors with in-house laboratory infrastructure.
- Spirulina and chlorella substitution:Established microalgae supplements with longer EU market presence capture overlapping antioxidant-positioning shelf space in German and Dutch retail channels.
Strategic Opportunities
- Netherlands direct-to-consumer channel expansion:Online-native supplement brands bypass traditional health store markups through subscription models, capturing margin pools from digitally fluent urban consumers.
- EMA pharmacovigilance framework alignment:Early engagement with bioactive claim substantiation pathways positions suppliers for pharmaceutical-adjacent positioning if isothiocyanate health opinions turn favorable.
- Cold-pressed oil segment penetration:Cosmetic and functional food applications for moringa seed oil remain underdeveloped relative to leaf powder saturation, offering white-space margin capture.
Industry Challenges
- Organic certification timeline compression:EU Organic Regulation 2018/848 conversion periods for new Mediterranean cultivation sites delay certified supply availability by 24-36 months.
- Analytical chemist talent scarcity:Standardized phytochemical profiling for isothiocyanate and flavonoid content requires specialized HPLC-MS expertise that outpaces vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Moringa Supplement Market |
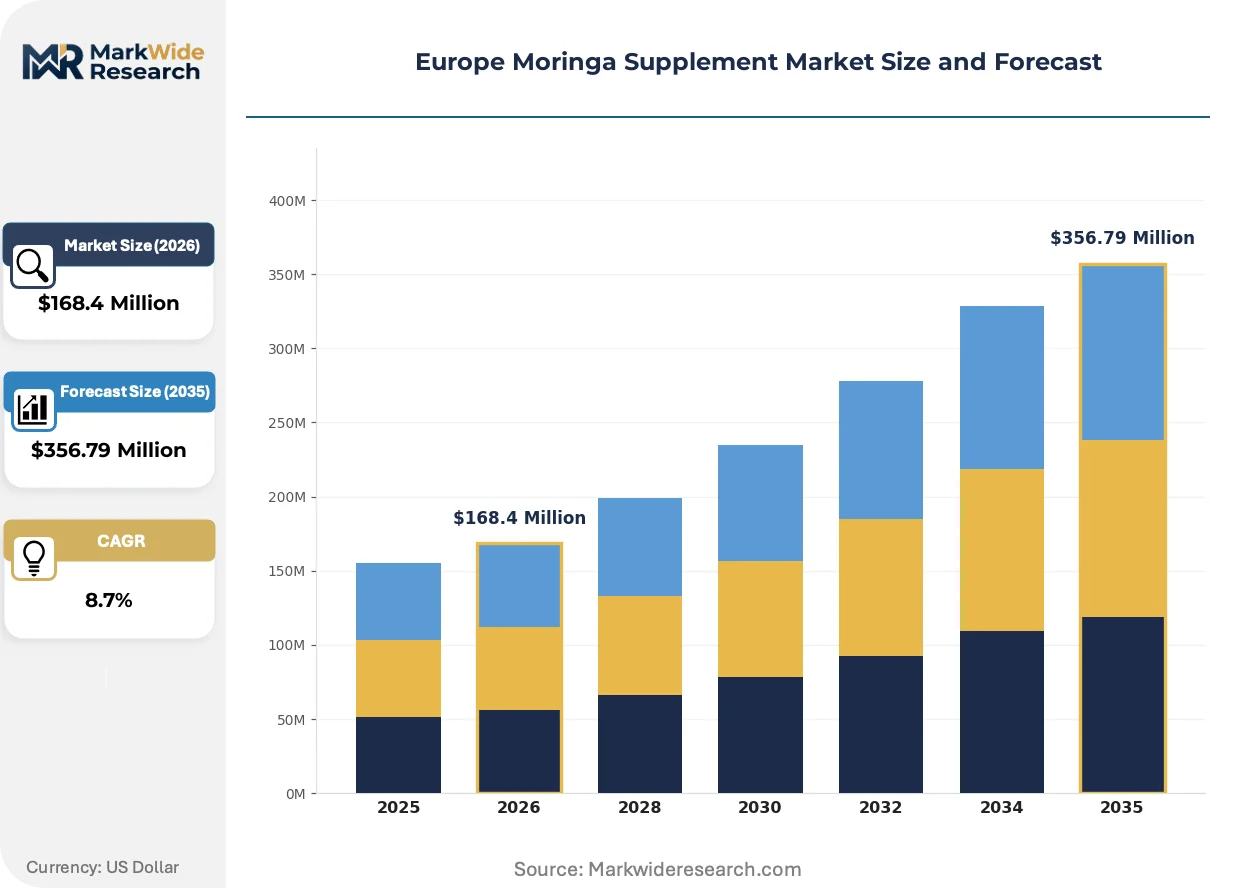
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $356.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tea, Oil End User: Fitness Enthusiasts, Health-Conscious Consumers, Nutraceutical Companies, Dietary Supplement Retailers Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Stores Form: Organic, Non-Organic, Raw, Extracted |
| Companies Covered | Earth Expo Company, Aayuritz Phytonutrients Pvt. Ltd., Organic India Pvt. Ltd., Bioaltech, Bio Moringa Oleifera GmbH, Kuli Kuli, Inc., Moringa Energy Life, The Moringa Company, Grenera Nutrients Pvt. Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Moringa Supplement Market Strategic Shifts & Innovations
European moringa supply chains are pivoting toward traceability-verified, single-origin sourcing as procurement departments impose blockchain-backed documentation requirements on Mediterranean cultivation partners.
Supercritical CO2 extraction technology is consolidating market share among premium-positioned suppliers, replacing solvent-based methods that leave residual petrochemical traces. German contract manufacturers now specify supercritical-derived extracts for clean-label capsule formulations. This shift is compressing margins for conventional extraction operators unable to justify capital equipment upgrades.
REACH enforcement for botanical imports has tightened residual solvent thresholds, forcing South Asian exporters toward third-party laboratory partnerships in Rotterdam and Hamburg. ECHA guidance documents issued in 2023 now explicitly reference moringa oleoresins within the expanded monitoring scope. Mid-sized distributors are responding by pre-positioning inventory through bonded warehousing to buffer testing delays.
Fitness enthusiasts across France and Belgium are abandoning bulk powder jars for single-serve sachets with QR-linked batch certificates. Direct-to-consumer brands capture this behavioral pivot through subscription platforms that bypass traditional pharmacy and health store channels. This channel rotation concentrates demand velocity in the Netherlands and western Germany where digital payment penetration supports frictionless recurring revenue models.
Europe Moringa Supplement Market Segmentation
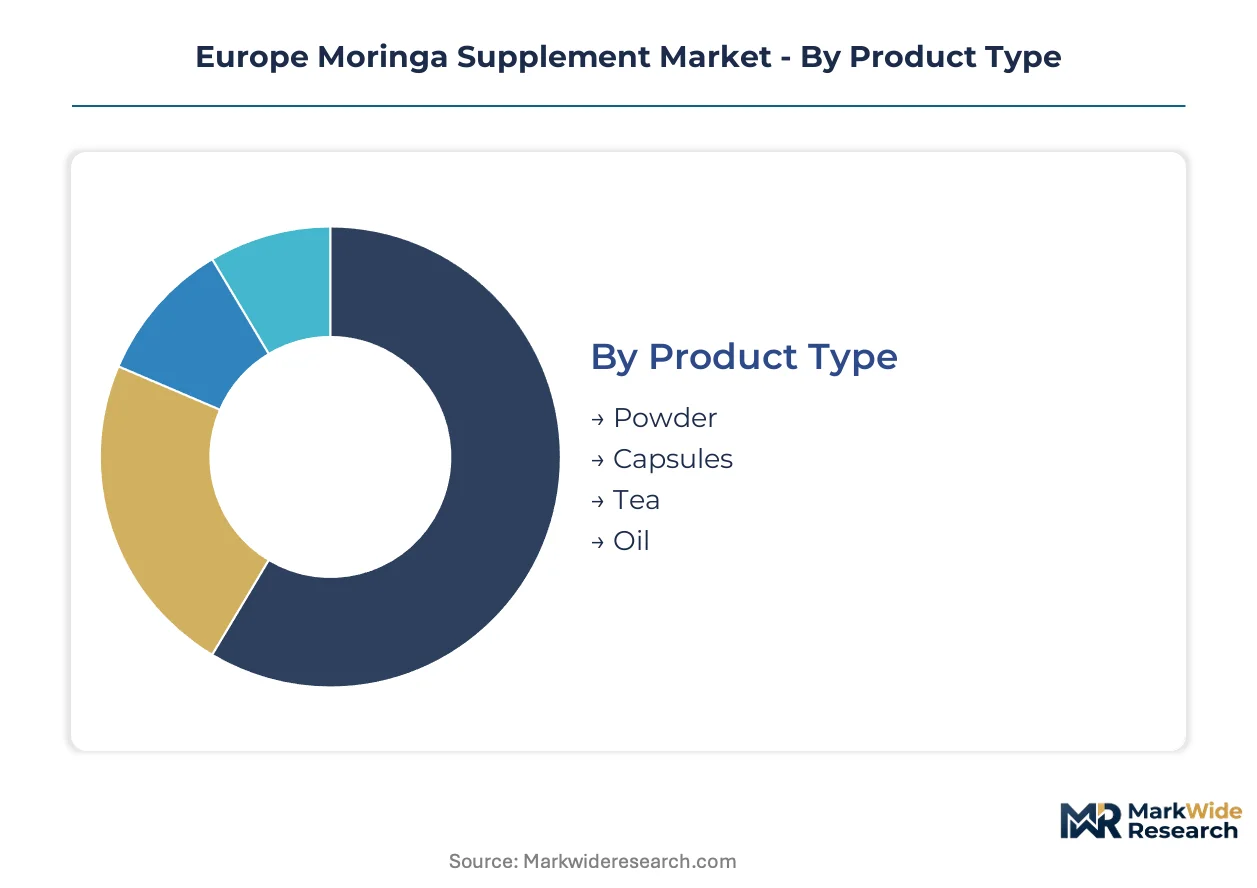
Segmentation in the Europe Moringa Supplement Market reveals how regulatory compliance costs and certification tiers fragment competitive positioning across product formats and distribution vectors. Each dimension carries distinct EFSA, EU Organic Regulation 2018/848, and REACH obligations that reshape supplier economics and buyer access patterns.
Product Type:
Powder formulations require EU Novel Food dossiers for standardized isothiocyanate claims, while oil derivatives face additional REACH registration for cosmetic-grade oleoresins entering German and French manufacturing channels.
- Powder:Dried leaf material standardized to 10%+ flavonoid and isothiocyanate content by dry weight. German health-conscious consumers drive volume through bulk organic purchases, though single-serve sachets are compressing jar-based economics in Netherlands direct-to-consumer channels.
- Capsules:Concentrated extracts in gelatin or plant-based shells enabling precise dosing. Fitness enthusiasts in France and Belgium capture concentrated margin pools through stackable capsule systems that displace bulk powder purchasing patterns.
- Tea:Whole or cut leaf preparations for infusion. Specialty health stores in Austria and Switzerland stock premium-positioned whole-leaf variants with blockchain-backed origin documentation.
- Oil:Cold-pressed seed extracts for functional food and cosmetic applications. REACH compliance for residual solvent thresholds limits South Asian import penetration into German contract manufacturing.
Powder sits at the top of the volume ranking, with capsules climbing the fastest.
End User:
Procurement patterns diverge sharply between institutional buyers demanding batch-certified phytochemical profiles and individual consumers prioritizing portability and subscription convenience.
- Fitness Enthusiasts:Precision-dosing consumers seeking stackable supplement regimens. Belgian and French gym-adjacent retail channels capture this segment through single-serve formats with QR-linked certificates.
- Health-Conscious Consumers:Organic-certified priority buyers in Germany and Austria. Specialized health stores and online subscription platforms serve this segment with Mediterranean-sourced, EFSA-compliant leaf powders.
- Nutraceutical Companies:Contract manufacturers integrating moringa into plant-based protein fortification. German and French food manufacturers demand lot-to-lot phytochemical consistency from controlled Mediterranean cultivation partnerships.
- Dietary Supplement Retailers:Multi-brand distributors managing inventory across format types. Netherlands-based online-native brands bypass traditional pharmacy markups through frictionless recurring revenue models.
Nutraceutical companies anchor procurement volume, with fitness enthusiasts expanding most quickly.
Distribution Channel:
Channel economics reflect margin compression patterns as direct-to-native brands erode traditional health store positioning through subscription velocity.
- Online Retail:Direct-to-consumer platforms with subscription-based replenishment. Netherlands and western Germany concentrate demand velocity where digital payment penetration supports recurring revenue capture.
- Health Stores:Specialized brick-and-mortar with trained staff consultation. German organic certification requirements favor established distributors with in-house analytical laboratories.
- Supermarkets:Mass-market shelf space for economy-tier powders. Clean-label positioning struggles against spirulina and chlorella with longer EU market presence.
- Specialty Stores:Curated assortments in urban wellness districts. Paris and Berlin flagship locations stock supercritical CO2-extracted capsules at premium positioning.
Online retail sits at the top of the volume ranking, with specialty stores climbing the fastest.
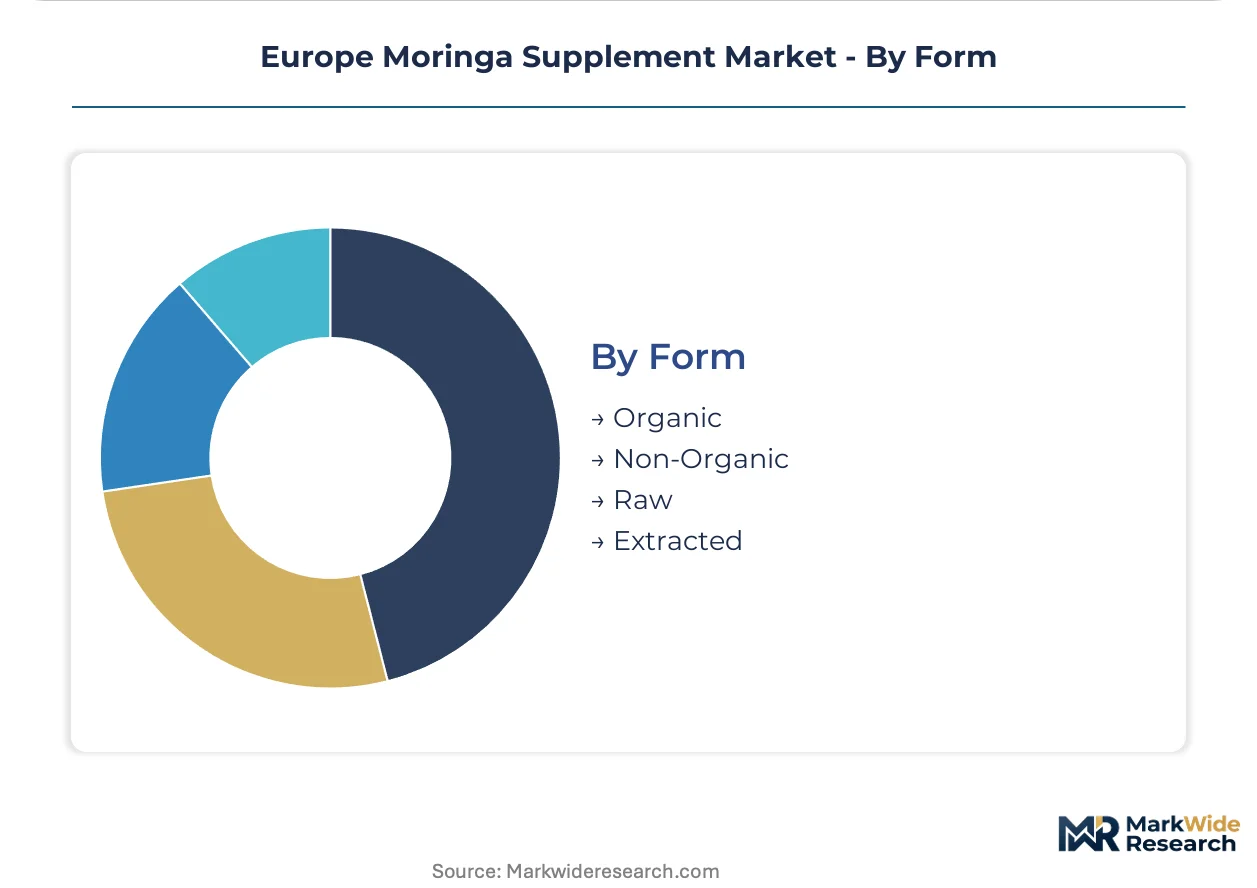
Form:
Certification tier directly determines pricing architecture and regulatory timeline, with organic conversion periods creating 24-36 month supply constraints for new Mediterranean cultivation entrants.
- Organic:EU Organic Regulation 2018/848 certified with full traceability documentation. German procurement departments impose blockchain-backed requirements on Spanish and Portuguese cultivation partners.
- Non-Organic:Conventional cultivation without certification premium. Price-sensitive volume plays in Eastern European markets with less stringent clean-label requirements.
- Raw:Minimally processed whole leaf or coarse powder. Austrian and Swiss consumers in alpine wellness corridors favor raw positioning for perceived enzymatic activity retention.
- Extracted:Solvent or supercritical CO2 concentrated actives. German contract manufacturers now specify supercritical-derived extracts to meet clean-label capsule formulations and REACH residual solvent thresholds.
Organic sits at the top of the volume ranking, with extracted forms gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moringa oleifera cultivation and processing first scaled commercially in South Asia before European nutraceutical firms established Mediterranean growing partnerships to shorten supply chains and satisfy EU organic certification requirements.
Germany
Health-conscious consumers in Bavaria and North Rhine-Westphalia drive premium organic powder adoption through specialized health stores and subscription platforms. EFSA novel food assessments govern ingredient approval for standardized isothiocyanate formulations entering German contract manufacturing. The Berlin-Brandenburg corridor hosts analytical laboratories serving REACH compliance verification for imported botanical extracts.
France
Fitness enthusiasts in Paris and Lyon pivot toward single-serve sachets with QR-linked batch certificates, displacing bulk powder purchasing patterns. ANSM pharmacovigilance frameworks scrutinize bioactive supplement claims alongside EMA guidance. The Provence-Alpes-Côte d'Azur region anchors controlled cultivation partnerships supplying lot-to-lot phytochemical consistency to French nutraceutical manufacturers.
Netherlands
Direct-to-consumer brands in the Randstad bypass traditional health store markups through frictionless recurring revenue models. EU Organic Regulation 2018/848 conversion periods delay certified supply availability from new Mediterranean entrants. Rotterdam functions as a bonded warehousing hub buffering REACH testing delays for South Asian exporters.
Spain
Andalusian growing operations reduce import dependency on South Asian supply chains for European contract manufacturers. The country's national agricultural regulator oversees organic certification timelines stretching 24-36 months for new cultivation sites. Valencia and Murcia concentrate supercritical CO2 extraction capacity serving clean-label German capsule formulations.
Belgium
Gym-adjacent retail channels in Brussels and Antwerp capture fitness-oriented demand through stackable capsule systems. ECHA guidance documents issued in 2023 explicitly reference moringa oleoresins within expanded monitoring scope. Flanders-based distributors leverage in-house laboratory infrastructure to manage residual solvent threshold compliance.
Europe Moringa Supplement Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and extraction technology vectors, with supercritical CO2-derived extracts commanding pricing separation from conventional solvent-based alternatives. The vendor base organizes into three strategic archetypes: South Asian cultivation-origin suppliers with extraction expertise, European-controlled cultivation partnerships, and direct-to-consumer brands with subscription velocity. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as mid-sized distributors pre-position inventory through bonded warehousing to buffer testing delays.
Within the cultivation-origin supplier tier, Grenera Nutrients Pvt. Ltd. and Organic India Pvt. Ltd. exemplify South Asian entities with extraction capabilities serving European contract manufacturers. Bio Moringa Oleifera GmbH occupies a position representing European-controlled cultivation partnerships in Mediterranean climates. These three anchors illustrate how geographic origin and organizational structure map to distinct margin pools and regulatory compliance burdens across the value chain.
| Leading Market Players |
|---|
| Earth Expo Company |
| Aayuritz Phytonutrients Pvt. Ltd. |
| Organic India Pvt. Ltd. |
| Bioaltech |
| Bio Moringa Oleifera GmbH |
| Kuli Kuli, Inc. |
| Moringa Energy Life |
| The Moringa Company |
| Grenera Nutrients Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Mediterranean moringa leaf spot prices, tracked through Spanish and Portuguese agricultural exchanges, cascade through three distinct certification tiers that stratify final product pricing across German and French retail channels. EFSA novel food assessment costs exceeding €150,000 per dossier compress margins for uncertified South Asian imports while amplifying pricing power for EU Organic Regulation 2018/848-compliant Mediterranean suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs European moringa supplement transactions, with supercritical CO2-extracted organic capsules commanding separation from solvent-based conventional powders. Certification grade and extraction technology serve as the primary price differentiation drivers, though subscription velocity in Netherlands direct-to-consumer channels is compressing traditional health store markups. Pricing pressure stems from spirulina and chlorella substitution in German mass-market retail, forcing margin tightening in economy-tier positioning. Nutraceutical companies exhibit lowest price sensitivity due to phytochemical consistency requirements, while Eastern European consumers in non-organic segments demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-contract-manufacturer channels handle German and French food manufacturer demand for plant-based protein fortification, while direct-to-consumer platforms serve fitness enthusiasts through subscription replenishment models. Geographic supply concentrates in Spain, Portugal, and India, with Mediterranean cultivation partnerships reducing import dependency on South Asian leaf powder sources. Raw material dependencies center on moringa oleifera leaf biomass, gelatin and plant-based capsule shells, and supercritical CO2 extraction equipment. Single-source vulnerability from concentrated South Asian monsoon-dependent harvests creates supply chain risk, compounded by REACH testing delays at Rotterdam and Hamburg port laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Moringa Supplement Market functions as a regulatory compounder, where EFSA novel food pathway clarity for standardized isothiocyanate formulations continues reshaping competitive entry economics and incumbent investment priorities.
For Market Incumbents: Anchor market position through backward integration into controlled Mediterranean cultivation partnerships that compress organic certification timelines from 36 to 24 months. Defend margin pools by pre-positioning inventory through Rotterdam bonded warehousing to buffer REACH testing delays, while accelerating supercritical CO2 extraction capacity additions in Valencia and Murcia to displace solvent-based competitors.
For New Entrants and Emerging Players: Enter via cold-pressed moringa seed oil segments for cosmetic and functional food applications, where leaf powder saturation has left white-space margin capture opportunities. Target Belgian and French gym-adjacent retail channels with single-serve sachet formats featuring QR-linked batch certificates, leveraging subscription platforms to bypass established health store distribution.
For Investors and Strategic Acquirers: Asymmetric upside sits with European-controlled cultivation partnerships possessing in-house HPLC-MS analytical capabilities and EFSA dossier submission experience. Long-term viability hinges on positioning for pharmaceutical-adjacent revenue streams should EMA pharmacovigilance frameworks issue favorable isothiocyanate health opinions. Monitor EFSA opinion publication timelines as the critical inflection signal for competitive investment priority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Capacity Expansion | Spanish and Portuguese facilities displace solvent-based competitors in German clean-label capsule supply. |
| Mediterranean Cultivation Partnership Formation | Controlled growing operations in Andalusia improve lot-to-lot phytochemical consistency for contract manufacturers. |
| EFSA Novel Food Dossier Submission | Standardized isothiocyanate formulations unlock pharmaceutical-adjacent positioning and premium pricing tiers. |
| Direct-to-Consumer Subscription Launch | Netherlands-based platforms bypass traditional health store markups through frictionless recurring revenue capture. |
| Bonded Warehousing Pre-Positioning | Rotterdam inventory buffers mitigate REACH testing delay risks for South Asian botanical imports. |
Research Approach
Multiple input streams — procurement directors at German and French nutraceutical manufacturers, analytical laboratory managers in Berlin-Brandenburg, EFSA regulatory affairs consultants, and Mediterranean cultivation operators — were reconciled against EU Organic Regulation 2018/848 certification databases, REACH compliance filings with ECHA, customs import records at Rotterdam and Hamburg, and EMA pharmacovigilance guidance documents. Bottom-up volume estimates from product-format segmentation were triangulated with top-down market sizing derived from health store and online retail channel audits.
Data-stream reconciliation across the projection horizon employed a structured analytical framework modeling product type, end user procurement pattern, distribution channel velocity, and certification tier as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA approval timeline scenarios and organic conversion period constraints. Forecast inputs included Mediterranean cultivation yield projections and supercritical CO2 extraction capacity expansion schedules.
Inputs from EFSA opinion calendars and EU Organic Regulation conversion databases were available through the study window; gaps in real-time South Asian harvest yield data introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions regarding EMA pharmacovigilance trajectory and REACH enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Global Nutraceutical Ingredients Market