
 Flavor Masking Agents Market | 2026-2036
Flavor Masking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Masking Agents Market Foresight
Multi-source procurement of botanical and synthetic masking chemistries is hardening across North American and European formulators. Sensient Technologies Corporation leverages its integrated color-and-flavor platform to supply pharmaceutical-grade bitter blockers with batch-to-batch consistency. Givaudan anchors its position through deep R&D partnerships with oral care multinationals seeking alcohol-masking solutions. Kerry Group competes by extending its taste modulation portfolio into animal nutrition, where palatability drives feed conversion metrics.
Flavor masking agents comprise functional excipients and active taste modulators engineered to suppress, dilute, or chemically block undesirable sensory perceptions—typically formulated at 0.1% to 5.0% w/w depending on substrate potency and target organoleptic profile. These agents serve primarily to ensure consumer and patient acceptance of functional ingredients that would otherwise trigger rejection reflexes. Among product types, bitter blockers command the dominant share as pharmaceutical pipelines swell with high-potency actives, while coatings represent the fastest-expanding category in pediatric and geriatric dosage formats. Within applications, food and beverages remains the mature revenue base, though animal nutrition is emerging as a concentrated margin pool where species-specific palatability commands technical premiums.
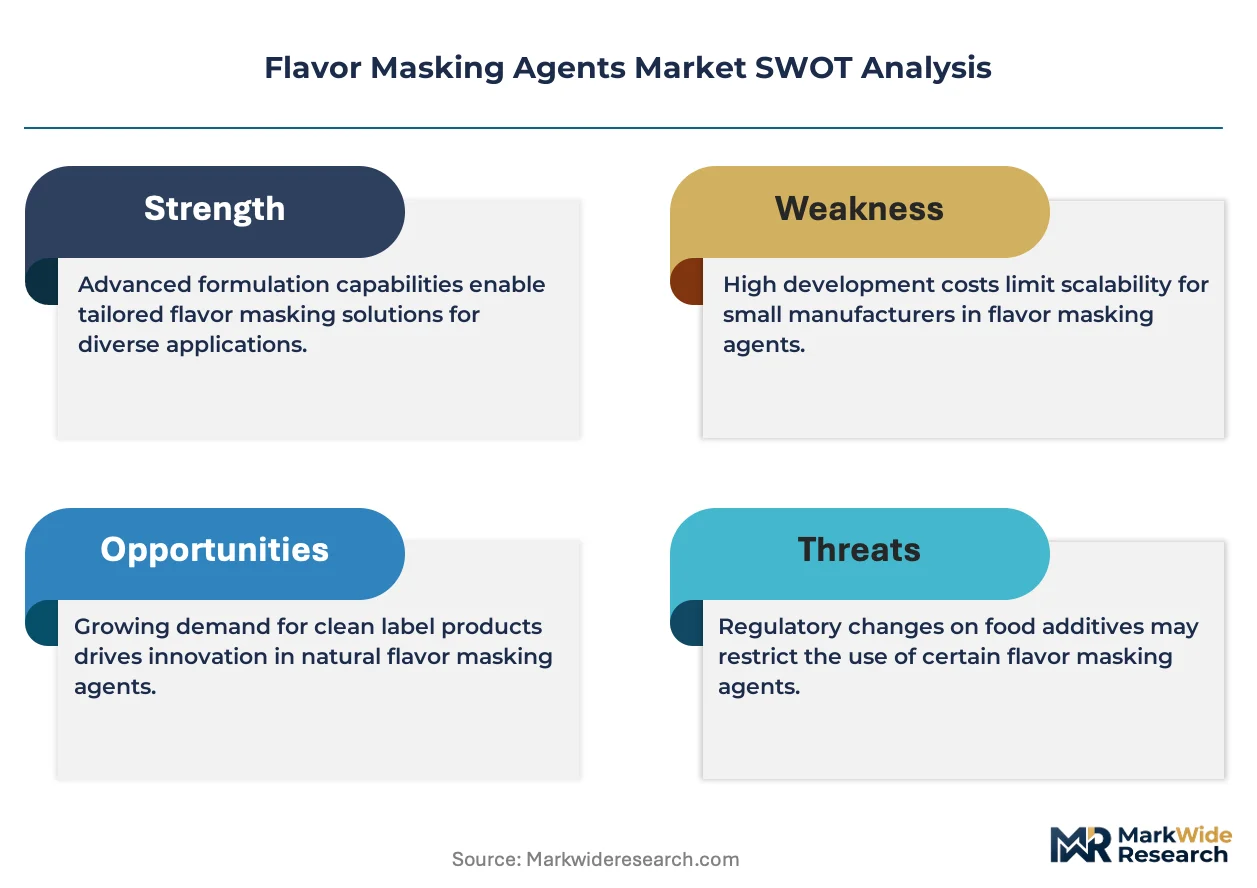
FDA excipient guidelines and EMA quality standards for orally administered drug products are tightening purity and documentation requirements for taste-masking components used in pediatric formulations. REACH registration obligations in Europe and EPA environmental release thresholds for manufacturing facilities are reshaping supplier qualification protocols and site selection decisions. Stakeholders must monitor regulatory divergence between FDA GRAS determinations and EMA novel excipient pathways when planning transatlantic product registrations.
Market Dynamics
Pharmaceutical pipelines are filling with high-potency active pharmaceutical ingredients that trigger severe bitterness, forcing formulators to embed bitter-blocking chemistries earlier in development cycles rather than retrofitting finished dosage forms.
Growth Catalysts
- EMA pediatric formulation mandates:European regulators now require taste-masking documentation for all new pediatric drug submissions, expanding the addressable excipient pool for oral disintegrating tablets.
- High-potency oncology APIs:Kinase inhibitors and nucleoside analogs with extreme bitterness profiles are entering late-phase trials, creating technical demand for next-generation bitter receptor antagonists.
- US nutraceutical onshoring:Domestic contract manufacturers are bringing flavor system production in-house to reduce lead times and protect proprietary formulations from overseas exposure.
Market Restraints
- Botanical extract volatility:Stevia and monk fruit supply from Southeast Asia faces harvest inconsistency, compressing margin predictability for natural masking systems.
- GRAS affirmation timelines:FDA's novel excipient review queue has lengthened, delaying commercialization of fermentation-derived masking peptides.
- Synthetic polymer substitution:Hydroxypropyl methylcellulose coatings are displacing some flavor-modulation demand in immediate-release tablets.
Strategic Opportunities
- Brazilian pet food premiumization:ANVISA's relaxed import rules for novel pet food ingredients are opening a concentrated margin pool for species-specific palatability systems.
- Layered-release pediatric formats:Dual-coat architectures that separate bitter core from taste-modulated shell represent white space in geriatric compliance applications.
- ISO 22000 certification arbitrage:Food-grade masking agents with pharmaceutical-grade documentation can capture price premiums across overlapping regulatory regimes.
Industry Challenges
- Cross-functional formulation expertise:Bridging sensory science, polymer chemistry, and regulatory affairs requires talent pools concentrated in Basel, Boston, and Singapore.
- Legacy equipment retrofit costs:Fluid bed coating lines designed for conventional excipients demand substantial capex to handle heat-sensitive flavor modulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Masking Agents Market |
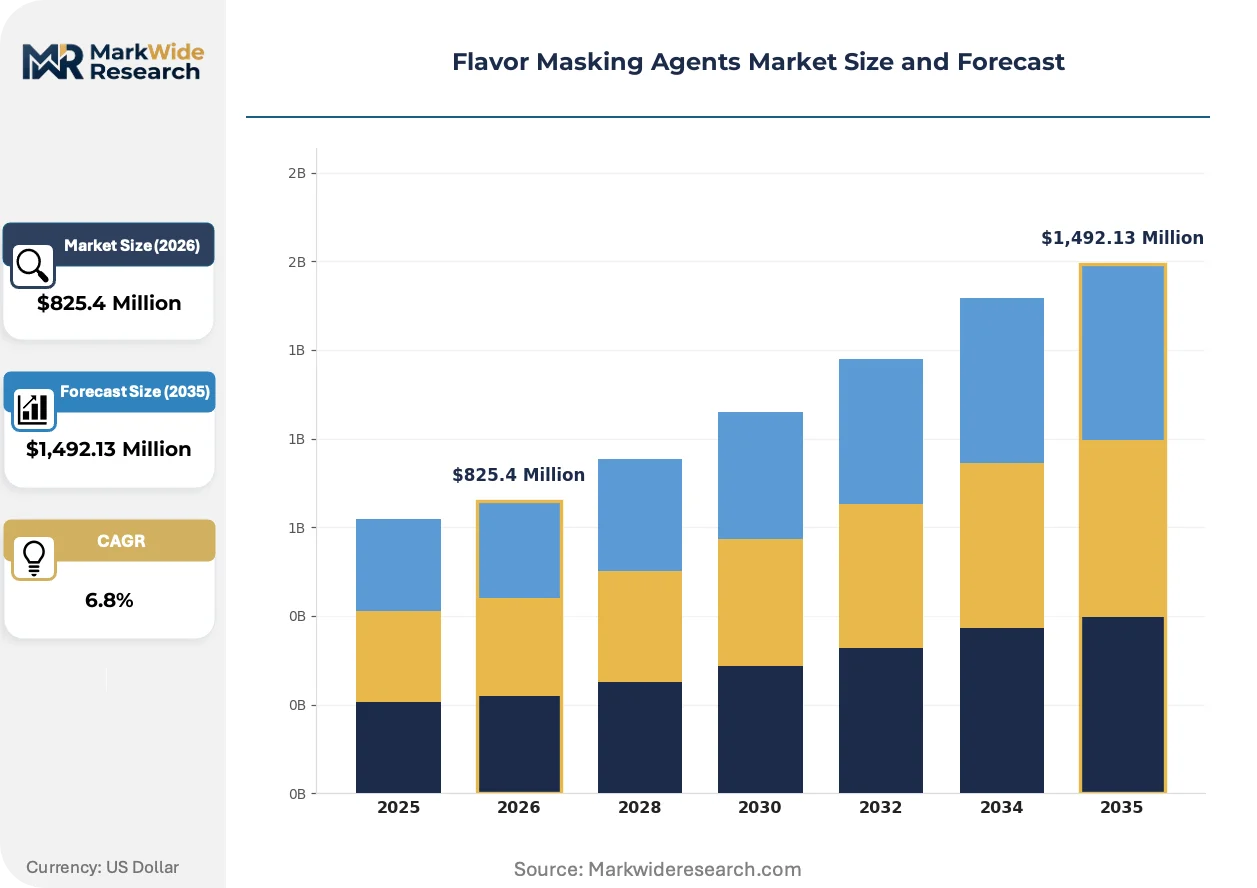
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Bitter Blockers, Acid Neutralizers, Saliva Stimulators, Coatings Application: Pharmaceuticals, Oral Care, Food & Beverages, Animal Nutrition, Personal Care Formulation Type: Powder, Liquid, Granules, Emulsions, Capsules End User: Contract Manufacturers, Nutraceutical Companies, Cosmetic Producers, Feed Manufacturers |
| Companies Covered | Sensient Technologies Corporation, Firmenich SA, Givaudan, Symrise AG, Kerry Group, International Flavors & Fragrances Inc., Tate & Lyle PLC, Archer-Daniels-Midland Co, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Masking Agents Market Shifts & Advancements
Receptor-level bitter blocking is displacing older dilution strategies, while regulatory documentation requirements are tightening around pediatric excipient safety. Procurement patterns are compressing supplier qualification timelines.
Encapsulation via complex coacervation is modularizing how pharmaceutical formulators approach multi-active bitterness. Pediatric and geriatric dosage developers are adopting these systems at accelerating rates to handle fixed-dose combinations. The technology is modularizing supply chain relationships, enabling regional excipient blenders to compete with integrated multinationals on specialized pediatric projects.
REACH registration obligations for novel polymer chemistries are extending supplier qualification timelines across European pharmaceutical value chains. Industrial consequence includes hardening procurement toward pre-registered excipient libraries rather than custom synthesis. Pediatric liquid formulations face the steepest compliance burden, driving formulators toward GRAS-affirmed botanical alternatives with existing dossiers.
Specification-driven procurement is compressing supplier onboarding from eighteen months to under six months at large pharmaceutical buyers. Direct sourcing teams are displacing traditional distributor relationships for high-volume masking chemistries. This pattern is most visible in United States contract manufacturing, where just-in-time inventory requirements favor domestic suppliers with documented batch pedigree.
Flavor Masking Agents Market Segmentation
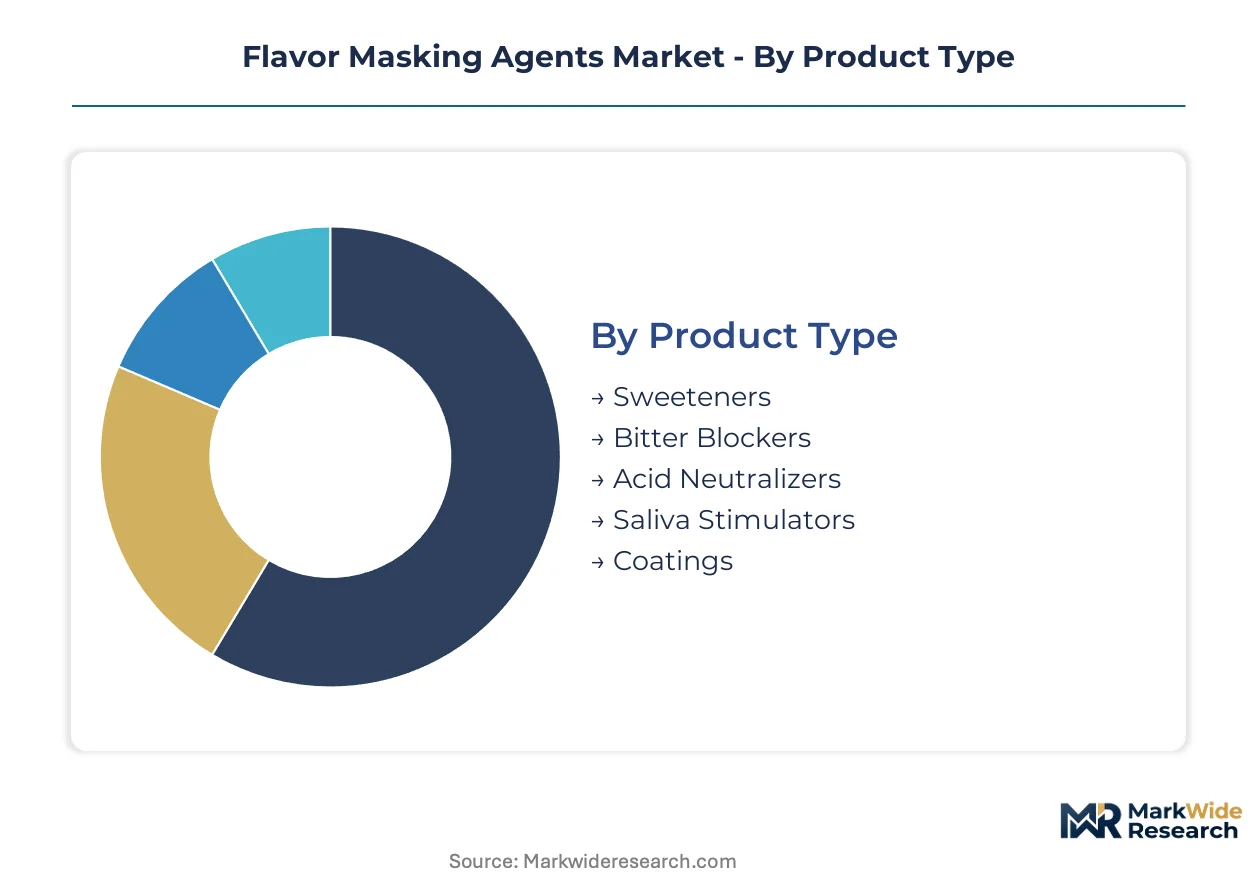
Segmentation in flavor masking agents determines procurement strategy, regulatory pathway, and margin structure. Product chemistry dictates manufacturing site selection. Application verticals shape documentation requirements and pricing power.
Product Type:
Supply concentration clusters around receptor-targeting technologies and barrier systems, with fermentation-derived and botanical extraction capabilities determining supplier tier.
- Bitter Blockers:Receptor antagonists and allosteric modulators that bind TAS2R proteins to prevent signal transduction. Pharmaceutical pipelines in Basel and Boston drive technical specifications for kinase inhibitor compatibility. EMA pediatric mandates are expanding documentation requirements for these chemistries.
- Coatings:Polymer-based barrier systems including ethylcellulose and polymethacrylate architectures that physically separate API from taste receptors. Pediatric and geriatric dosage formats in the United States are accelerating demand for rapid-disintegration coatings with modified release profiles.
- Sweeteners:High-intensity compounds including steviol glycosides and synthetic alternatives that overwhelm bitterness through competitive activation of TAS1R2/TAS1R3 receptors.
- Acid Neutralizers:Buffering salts and mineral carbonates that suppress sourness and astringency in acidic actives.
- Saliva Stimulators:Organic acids and tactile agents that enhance salivary flow to dilute and clear residual bitter compounds.
Bitter blockers absorb the bulk of installed capacity; coatings are expanding most quickly.
Application:
Cost tier stratification separates commodity food-grade applications from pharmaceutical-grade systems with full regulatory dossiers.
- Pharmaceuticals:Oral solid and liquid dosage forms requiring FDA GRAS or EMA novel excipient qualification. High-potency oncology APIs with extreme bitterness profiles are concentrating demand in Switzerland and Singapore manufacturing clusters.
- Animal Nutrition:Species-specific palatability systems for companion and livestock feed, where feed conversion metrics justify technical premiums. Brazilian pet food premiumization under ANVISA's relaxed import rules is opening concentrated margin pools.
- Food & Beverages:Mature revenue base spanning protein fortification, functional beverages, and sugar reduction applications.
- Oral Care:Alcohol and surfactant masking in mouthwash and dentifrice formulations, with Givaudan's R&D partnerships setting technical benchmarks.
- Personal Care:Bitter active masking in topical and transdermal delivery systems.
Pharmaceuticals capture the highest price premiums per kilogram; animal nutrition is climbing the fastest.
Formulation Type:
Volume concentration favors powder systems for scale manufacturing, while liquid and emulsion formats serve specialized applications requiring precise dosing.
- Powder:Dry-blended excipients for tablet compression and capsule filling, dominating high-volume pharmaceutical and food manufacturing.
- Liquid:Aqueous and solvent-based solutions for pediatric syrups and beverage applications.
- Granules:Agglomerated particles for direct compression and sachet dosing.
- Emulsions:Oil-in-water systems for lipid-soluble actives and enhanced mouthfeel modulation.
- Capsules:Pre-metered gelatin or HPMC shells containing concentrated masking agents.
Powder commands the largest production volumes; emulsions are gaining share fastest in functional beverage applications.
End User:
Customer type determines procurement sophistication, with contract manufacturers driving standardization and nutraceutical companies demanding proprietary differentiation.
- Contract Manufacturers:Pharmaceutical and food CDMOs with just-in-time inventory requirements and documented batch pedigree demands. US nutraceutical onshoring is bringing flavor system production in-house to reduce lead times.
- Nutraceutical Companies:Dietary supplement formulators seeking GRAS-affirmed botanical masking with existing dossiers for rapid market entry.
- Cosmetic Producers:Personal care manufacturers masking bitter preservatives and active ingredients.
- Feed Manufacturers:Animal nutrition compounders optimizing palatability for species-specific digestive physiology.
Contract manufacturers absorb the bulk of procurement volume; nutraceutical companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in the United States concentrate the highest procurement volumes for bitter-blocking excipients, while European regulators drive documentation standards that reshape supplier qualification protocols worldwide.
United States
Domestic nutraceutical contract manufacturers are onshoring flavor system production to compress lead times and protect proprietary formulations. FDA's evolving GRAS affirmation timelines for novel excipients are lengthening commercialization pathways for fermentation-derived masking peptides. Boston and Basel-connected manufacturing clusters in New Jersey and Massachusetts are embedding bitter blockers earlier in oncology API development cycles.
Germany
Industrial chemical conglomerates anchor European supply of pharmaceutical-grade polymer coatings for pediatric dosage formats. REACH registration obligations for novel polymer chemistries are extending supplier qualification timelines across German pharmaceutical value chains. The Rhine-Ruhr industrial corridor houses specialized excipient blenders competing with integrated multinationals on complex coacervation projects.
Switzerland
High-potency oncology API pipelines in Basel are concentrating technical demand for next-generation bitter receptor antagonists. Swissmedic quality standards for orally administered drug products are tightening purity documentation requirements for taste-masking components. The Basel-Singapore manufacturing axis is driving specification-driven procurement compression from eighteen months to under six months.
China
Domestic pharmaceutical formulators are scaling bitter blocker procurement as kinase inhibitor pipelines mature through late-phase trials. NMPA alignment with international excipient standards is accelerating dossier preparation for botanical masking alternatives. Yangtze River Delta chemical parks are expanding fermentation-derived peptide capacity to serve both domestic and export pharmaceutical markets.
Brazil
Pet food premiumization under ANVISA's relaxed import rules for novel ingredients is opening concentrated margin pools for species-specific palatability systems. Domestic feed conversion metrics justify technical premiums for flavor masking in companion animal nutrition. São Paulo-based contract manufacturers are qualifying imported excipient libraries to bypass custom synthesis delays.
Flavor Masking Agents Market Competitive Landscape
Strategic partnerships dominate the current landscape as integrated flavor houses anchor positions through R&D collaborations with oral care and pharmaceutical multinationals. The vendor base clusters around three archetypes: integrated color-and-flavor platforms, fermentation-derived specialty chemical producers, and regional excipient blenders with modular coating capabilities. Consolidation pressure is intensifying as specification-driven procurement favors suppliers with documented batch pedigree and pre-registered polymer libraries.
Among integrated platforms, Sensient Technologies Corporation and Givaudan exemplify the R&D partnership archetype, while Kerry Group occupies a position spanning taste modulation into adjacent nutrition verticals. Firmenich SA and Symrise AG represent European-centered fermentation and botanical extraction capabilities. These anchors sit within a tiered structure where pharmaceutical-grade documentation separates premium positioning from commodity food-grade supply.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Firmenich SA |
| Givaudan |
| Symrise AG |
| Kerry Group |
| International Flavors & Fragrances Inc. |
| Tate & Lyle PLC |
| Archer-Daniels-Midland Co |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
Formulation chemists with polymer science and sensory expertise cluster in Basel, Boston, and Singapore, creating labor-cost differentials that widen spreads between pharmaceutical-grade premium tiers and commodity food-grade supply. These specialized talent pools anchor pricing power for documented batch pedigree while compressing margins for undifferentiated botanical extracts.
Pricing Analysis
Service bundling separates premium-tier suppliers from commodity competitors, with regulatory dossier preparation and technical support included in pharmaceutical-grade contracts but unbundled for food-grade procurement. Pricing stratifies across pharmaceutical certification tiers, volume scale, and customization depth. Cost compression in natural masking systems is intensifying because stevia and monk fruit harvest volatility from Southeast Asia feeds raw material uncertainty. Contract manufacturers with just-in-time inventory requirements exhibit the highest price sensitivity, while oncology formulators in late-phase development show the least.
Supply Chain Analysis
Dual-sourcing mandates from large pharmaceutical buyers now require qualification of at least two suppliers for critical bitter-blocking chemistries, reshaping procurement relationships. Manufacturing concentration centers on Switzerland, Germany, and the United States for pharmaceutical-grade polymer coatings and receptor antagonists. Supply chains draw from steviol glycosides extracted in Southeast Asia, fermentation-derived peptides from Yangtze River Delta facilities, and synthetic polymer feedstocks from Rhine-Ruhr chemical parks. Single-source vulnerability persists for specialized TAS2R antagonist production. Distribution runs through regional excipient blenders and direct sourcing teams displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FDA GRAS affirmation timelines and EMA pediatric formulation mandates erect regulatory moats favoring incumbents with pre-registered excipient libraries.
For Market Incumbents: Hedge against synthetic polymer substitution by deepening fermentation-derived peptide capabilities and securing captive supply of botanical extraction capacity in Southeast Asia. Defensive consolidation through acquisition of regional excipient blenders with complex coacervation expertise protects against modularizing supply chain threats from specialized pediatric project competitors. For New Entrants and Emerging Players: Contract manufacturers serving Brazilian pet food premiumization represent the most penetrable channel partner entry point, given ANVISA's relaxed import rules and concentrated margin pools for species-specific palatability systems. Target layered-release pediatric formats with dual-coat architectures as white-space applications, leveraging ISO 22000 certification arbitrage to capture price premiums across overlapping food-grade and pharmaceutical-grade regulatory regimes. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-derived specialty chemical producers given FDA's lengthening novel excipient review queue and resulting scarcity of GRAS-affirmed masking peptides. Long-term viability over a multi-year horizon favors suppliers with documented batch pedigree and pre-registered polymer libraries. The signal to watch is specification-driven procurement compression timelines at large pharmaceutical buyers, where onboarding acceleration below six months indicates inflection toward integrated supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Investment | EMA pediatric mandates and FDA GRAS pathways create compliance moats for documented suppliers. |
| Backward Integration into Botanical Extraction | Captive stevia and monk fruit supply from Southeast Asia mitigates harvest volatility compression. |
| Complex Coacervation Capability Buildout | Modular encapsulation technology enables regional blenders to compete on specialized pediatric projects. |
| Species-Specific Palatability R&D Partnership | ANVISA's relaxed Brazilian pet food import rules open concentrated margin pools for technical premiums. |
| ISO 22000 Certification Arbitrage | Food-grade masking agents with pharmaceutical documentation capture price premiums across regulatory overlaps. |
Research Methodology
Multi-period observation of FDA GRAS affirmation timelines, EMA pediatric submission patterns, and specification-driven procurement compression anchored the trend analysis, supplemented by interviews with pharmaceutical formulation scientists, regulatory affairs leads at excipient suppliers, contract manufacturing procurement directors, and sensory science R&D heads. Secondary validation drew from FDA novel excipient review queue disclosures, EMA pediatric investigation plan databases, REACH registration filings, and SEC 10-K excipient segment disclosures. Bottom-up volume modeling across product chemistry tiers and top-down value triangulation against pharmaceutical pipeline data ensured cross-verification.
Input-output matrices mapped bitter blocker, coating, and sweetener production capacities against pharmaceutical API pipeline bitterness profiles, oncology drug development stage distributions, and regional manufacturing cluster concentrations. Segmentation dimensions spanned product receptor-targeting versus barrier-system technologies, application verticals from pediatric formulations to animal nutrition, formulation powder versus emulsion formats, and end-user procurement sophistication tiers. CAGRs were derived from regression analysis of historical excipient demand against API approval velocity and regulatory documentation requirement shifts. Forecast inputs included kinase inhibitor pipeline maturation rates and onshoring intensity metrics for US nutraceutical contract manufacturing.
Caveats apply where FDA novel excipient review queue lengthening, EMA regulatory divergence from GRAS determinations, or botanical extract harvest disruption from Southeast Asian climate patterns could materially shift the outlook. Deviation in specification-driven procurement compression timelines or REACH registration obligation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Carotenoids Pigment Market