
 Monk Fruit Sweetener Market | 2026-2036
Monk Fruit Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Monk Fruit Sweetener Market Outlook
E-commerce distribution for specialty sweeteners is reconfiguring how monk fruit products reach end consumers. Guilin Layn Natural Ingredients Corp. leverages its proximity to China's primary growing region to control raw material quality from harvest through extraction. GLG Life Tech Corp. anchors its position through intensive R&D on high-purity mogroside V formulations. Archer Daniels Midland Company extends its reach through integration with mainstream food ingredient distribution networks.
Monk fruit sweetener is a natural, zero-calorie sweetener extracted from Siraitia grosvenorii fruit, with mogroside V as the primary sweetening compound typically comprising 25-55% of commercial extracts by specification. Powder formats dominate industrial procurement due to handling efficiency and dosing precision in large-scale food manufacturing. Liquid concentrates are gaining traction in beverage applications where rapid dissolution and clean-label positioning matter most. Granulated blends occupy a mid-tier position, appealing to household consumers seeking cup-for-cup sugar replacement functionality.
The FDA's GRAS framework governs monk fruit extract approval in the United States, while China's NMPA and GB standards regulate domestic production quality and export certification. The EU's novel food status requirements for monk fruit continue to constrain market access across European member states, creating divergent regional growth trajectories. Stakeholders must monitor evolving clean-label certification standards and regional regulatory harmonization efforts to optimize geographic expansion strategies.
Market Dynamics
Raw material concentration in China's Guilin region creates supply vulnerability while beverage formulators accelerate monk fruit adoption in reduced-sugar carbonated drinks. This geographic lock-in shapes procurement strategies and extraction technology investments across the value chain.
Growth Catalysts
- Clean-label beverage mandates:North American carbonated drink manufacturers are replacing synthetic sweeteners with monk fruit extract to meet retailer clean-label requirements and consumer ingredient transparency demands.
- FDA GRAS pathway streamlining:The FDA's GRAS designation for monk fruit extract eliminates lengthy food additive petition processes, accelerating new product formulation cycles for US food and beverage companies.
- Mogroside V purification advances:High-purity extraction technologies now yield mogroside V concentrations above 50%, improving sweetness potency and reducing dosage requirements in industrial applications.
Market Restraints
- Guilin supply concentration:Over 80% of global monk fruit cultivation clusters in China's Guangxi Zhuang Autonomous Region, exposing buyers to weather, trade policy, and logistics disruptions.
- EU novel food status:Monk fruit extract remains classified as novel food across European Union member states, blocking market access and forcing manufacturers toward stevia or synthetic alternatives.
- Stevia price competition:Mature stevia supply chains and economies of scale in Latin American growing regions constrain monk fruit pricing flexibility in commodity sweetener segments.
Strategic Opportunities
- India FSSAI approval pathway:India's Food Safety and Standards Authority has yet to finalize monk fruit regulations; early movers securing approvals gain first-mover advantage in a 1.4 billion consumer market.
- Liquid concentrate beverage formats:Rapid-dissolution liquid monk fruit concentrates enable clean-label positioning in ready-to-drink teas and functional waters where powder dissolution speed limits adoption.
- Dual carbon alignment:China's MEE carbon intensity targets for agricultural processing favor monk fruit's lower cultivation carbon footprint versus cane or beet sugar, creating policy-aligned procurement incentives.
Industry Challenges
- Mogroside analytical chemist scarcity:Specialized expertise in mogroside fingerprinting and purity quantification remains concentrated among Guilin-based extraction facilities, limiting quality control capabilities at new market entrants.
- Batch-to-batch sweetness variability:Natural fruit composition fluctuations require sophisticated blending protocols and real-time Brix monitoring to maintain consistent sweetness equivalence in finished consumer products.
- Legacy formulation retrofit complexity:Sugar replacement in baked goods demands simultaneous adjustments to moisture retention, Maillard reaction kinetics, and volume yield, extending reformulation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monk Fruit Sweetener Market |
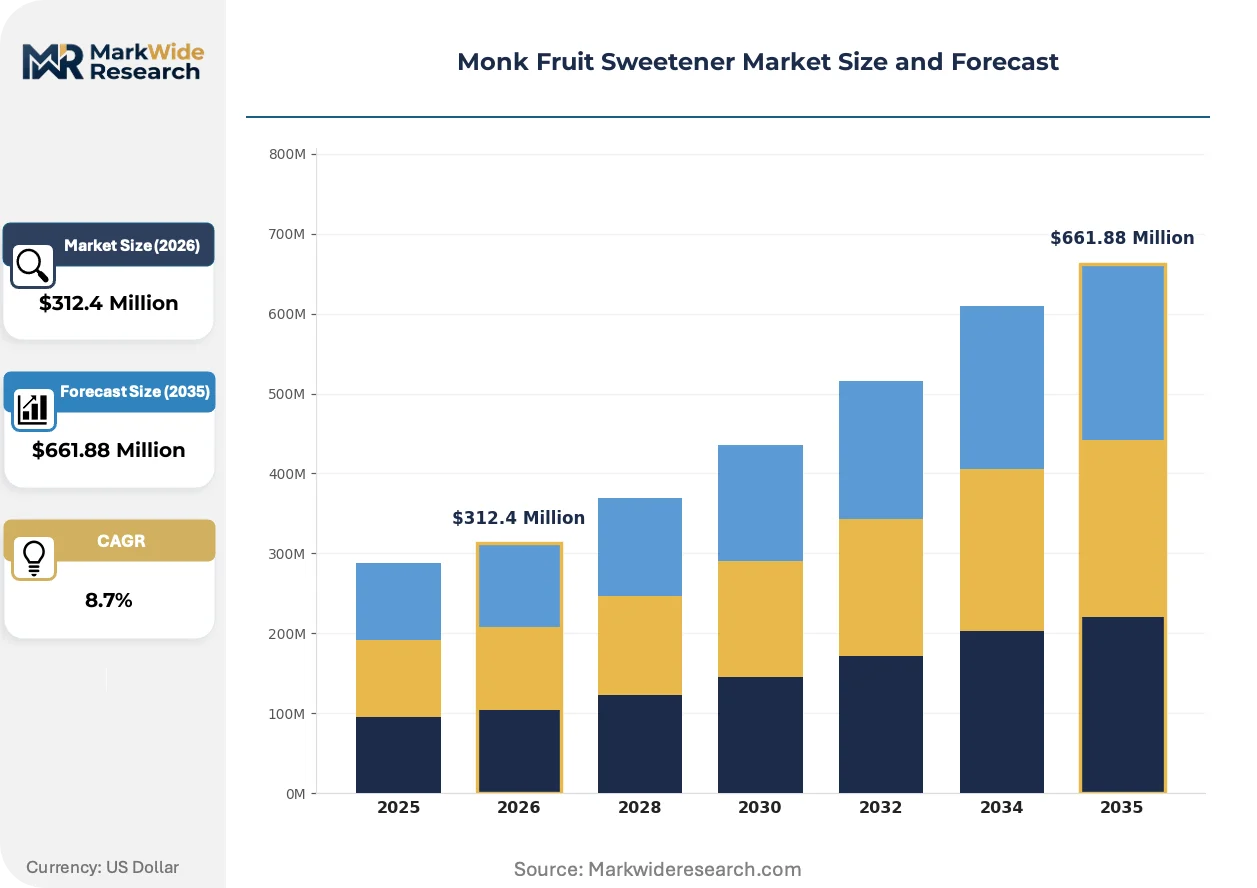
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Blend Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Households, Restaurants, Health Food Stores Distribution Channel: Online, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Guilin Layn Natural Ingredients Corp., GLG Life Tech Corp., Archer Daniels Midland Company, Firmenich SA, Steviva Brands, Tate & Lyle, Cargill, NOW Foods, Monk Fruit Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monk Fruit Sweetener Market Strategic Shifts
Extraction technology automation and regulatory pathway diversification are compressing time-to-market for monk fruit-enabled products. These forces are reshaping competitive positioning between integrated cultivators and formulation-focused ingredient suppliers.
High-performance liquid chromatography coupled with artificial intelligence-driven spectral analysis is digitizing mogroside purity verification. Third-party certification laboratories in Guangdong and California are deploying these systems to reduce analytical turnaround from weeks to hours. This compression is enabling just-in-time release protocols that reduce working capital requirements for beverage manufacturers.
China's NMPA has tightened export certification requirements for monk fruit extract under revised GB standards, mandating expanded heavy metal and pesticide residue testing. European importers now face extended documentation timelines, diverting near-term supply toward US and Southeast Asian markets. Japanese buyers are responding by accelerating domestic stevia-mogroside hybrid formulation development.
Direct-to-manufacturer e-commerce platforms are disintermediating traditional ingredient distribution channels for specialty sweeteners. North American craft beverage startups now procure monk fruit concentrates through Alibaba and specialized B2B marketplaces rather than established distributors like ADM. This channel shift is most pronounced in functional beverage segments where minimum order quantities and technical service requirements are lower.
Monk Fruit Sweetener Market Segmentation
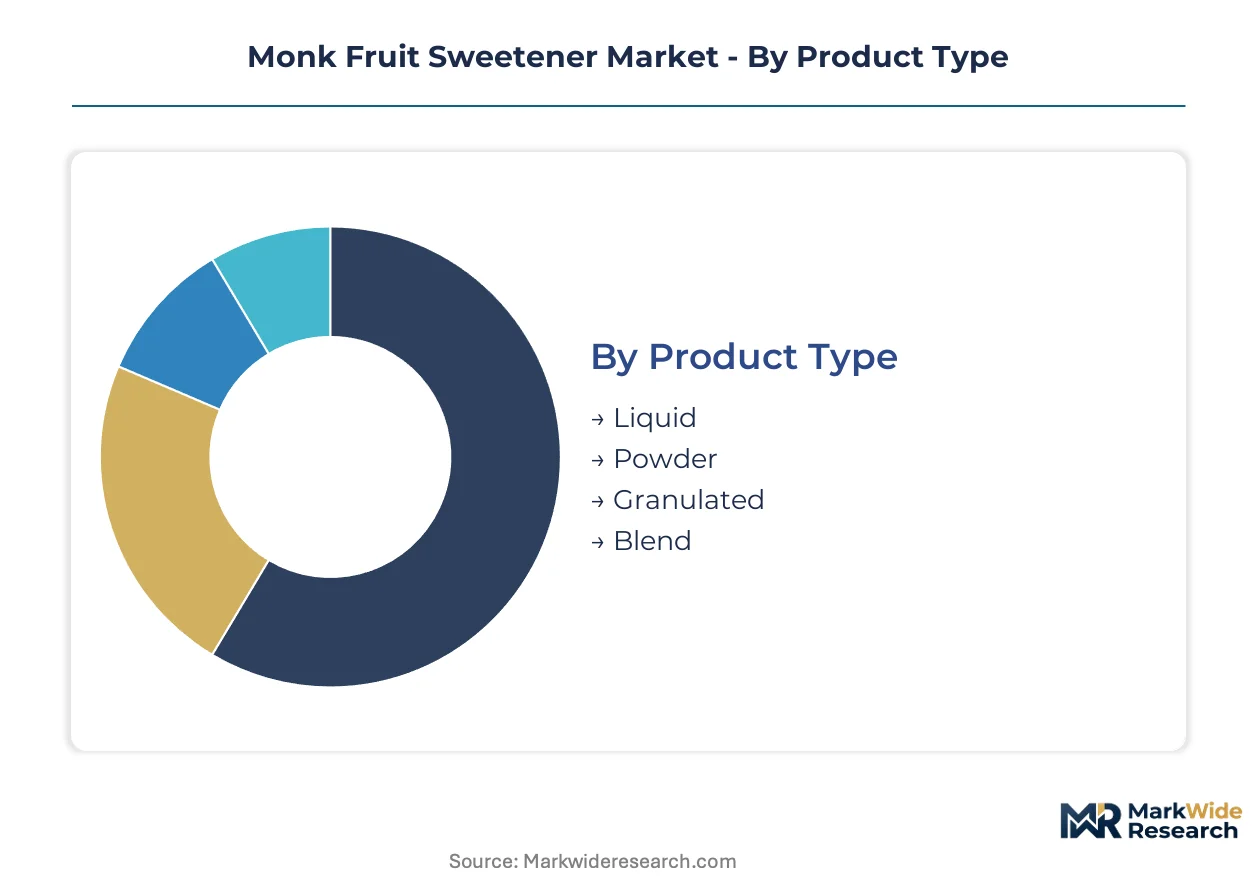
Monk fruit sweetener segmentation reveals divergent technical requirements across procurement channels. Food manufacturers prioritize dosing precision and batch consistency, while household buyers emphasize convenience and sugar-equivalence labeling.
Product Type:
After-sales service intensity varies sharply by format—liquid concentrates demand formulation troubleshooting, while powders require technical support for blending protocols.
- Powder:Industrial buyers dominate procurement of standardized extracts with mogroside V concentrations between 25% and 55%. Food manufacturers in the United States specify powder for baked goods reformulation where moisture control and Maillard reaction management require precise dosing. Powder formats lead by volume across all geographies.
- Liquid:Rapid-dissolution concentrates enable clean-label positioning in ready-to-drink teas and functional waters. Beverage formulators in North America specify liquid for carbonated drinks where powder dissolution speed creates production bottlenecks. Liquid is climbing the fastest as carbonated beverage adoption accelerates.
- Granulated:Cup-for-cup sugar replacement functionality targets household consumers seeking direct substitution in home baking.
- Blend:Monk-stevia and monk-erythritol combinations balance cost and taste profile for mid-tier food service applications.
By volume, powder leads. By growth pace, liquid is ahead.
Application:
Cost tier stratification separates premium beverage formulations from commodity bakery substitution.
- Beverages:Carbonated drink manufacturers represent the highest-value application segment, with clean-label mandates from major US retailers driving synthetic sweetener replacement. Reduced-sugar colas and flavored sparkling waters in North America specify high-purity mogroside V extracts above 50% concentration.
- Bakery:Sugar replacement in cakes and cookies demands simultaneous reformulation of moisture retention, browning kinetics, and volume yield. Commercial bakeries in China and the United States face extended development timelines due to these interdependent functional requirements.
- Dairy:Yogurt and ice cream applications leverage monk fruit's heat stability during pasteurization processes.
- Confectionery:Hard candies and chewing gums utilize monk fruit for non-cariogenic sweetness positioning in premium product lines.
Beverages command the steepest expansion trajectory; bakery maintains the largest installed base of reformulation expertise.
End User:
Customer type determines procurement scale and technical service requirements.
- Food Manufacturers:Large-scale buyers negotiate multi-year supply agreements with Guilin-based extraction facilities, requiring dedicated quality control liaison and batch certification documentation. These buyers drive specification standardization across the supply chain.
- Households:Direct-to-consumer brands emphasize granulated cup-for-cup formats with recipe conversion guidance and subscription replenishment services.
- Restaurants:Food service operators procure through broadline distributors, prioritizing cost stability over purity tier.
- Health Food Stores:Specialty retailers stock premium-positioned organic-certified extracts targeting clean-label enthusiasts.
Food manufacturers dominate procurement volume; households are expanding most quickly through e-commerce channels.
Distribution Channel:
Geography of demand shapes channel configuration, with direct procurement displacing traditional distribution in manufacturing segments.
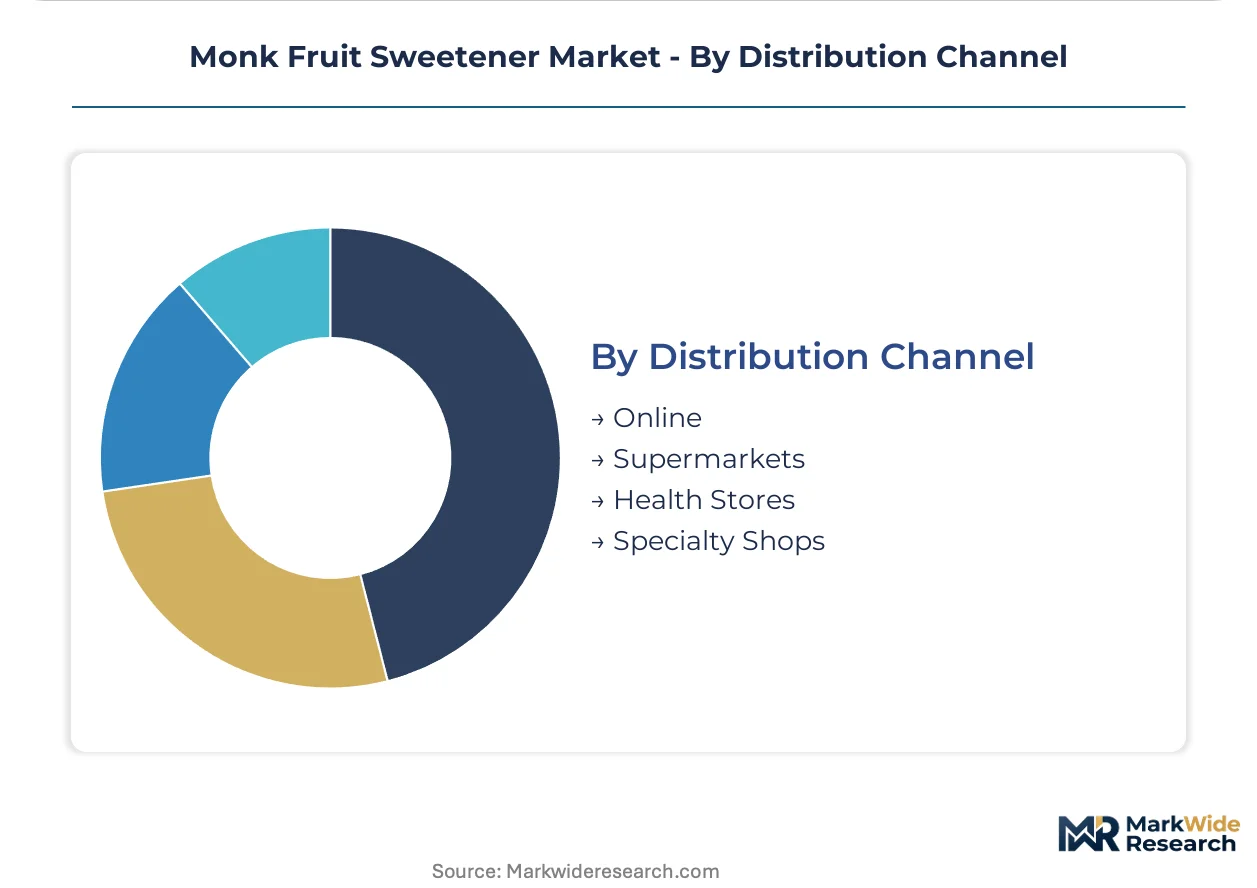
- Online:Alibaba and specialized B2B marketplaces now connect North American craft beverage startups directly to Guilin extraction facilities. This disintermediation compresses lead times and reduces minimum order thresholds for mid-scale buyers.
- Supermarkets:Mass retail placement for household granulated formats depends on slotting fee negotiations and shelf-stable packaging specifications.
- Health Stores:Specialty retail emphasizes third-party organic certification and non-GMO verification for premium positioning.
- Specialty Shops:Baker supply and restaurant service channels provide technical consultation for formulation adaptation.
Online channels are gaining share fastest; supermarkets retain the broadest household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's Guilin region where raw mogroside extraction occurs, while North American beverage formulators absorb premium markups for purified high-grade extracts. This asymmetry shapes procurement strategies and margin distribution across the value chain.
United States
Carbonated beverage manufacturers in the United States drive premium extract demand as retailers enforce clean-label mandates. The FDA's GRAS designation for monk fruit extract eliminates lengthy additive petition processes, accelerating new product launches. California-based formulation labs now specify liquid concentrates for rapid-dissolution applications in functional waters.
China
Guilin in the Guangxi Zhuang Autonomous Region hosts over 80% of global monk fruit cultivation and mogroside extraction capacity. China's NMPA tightened export certification under revised GB standards, mandating expanded heavy metal and pesticide residue testing. Layn Natural Ingredients leverages proximity to raw material sources to control quality from harvest through purification.
Japan
Japanese food manufacturers accelerate stevia-mogroside hybrid formulation development as alternative sourcing strategies. METI guidelines on clean-label positioning favor natural sweetener adoption in premium beverage segments. Osaka-based R&D facilities now blend monk fruit with native stevia varieties to reduce import dependency on Chinese extracts.
Germany
German food ingredient distributors face blocked monk fruit access due to EU novel food classification requirements. EFSA regulatory pathways remain incomplete, forcing manufacturers toward stevia or synthetic alternatives. Hamburg-based importers redirect supply toward Southeast Asian markets where regulatory barriers are lower.
India
India's FSSAI has yet to finalize monk fruit regulations, creating uncertainty for market entry. Early movers securing approvals would gain first-mover access across 1.4 billion consumers. Maharashtra-based beverage startups already source samples through Alibaba for product development ahead of formal clearance.
Monk Fruit Sweetener Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in extraction and purification. The vendor base clusters around three archetypes: integrated cultivator-extractors controlling Guilin supply, formulation-focused ingredient suppliers developing high-purity mogroside V variants, and global distributors bridging procurement gaps. Consolidation pressures favor backward integration into raw material control, while technology licensing agreements accelerate purification method diffusion.
Among integrated Chinese operators, Guilin Layn Natural Ingredients Corp. anchors the cultivator-extractor archetype through geographic concentration. GLG Life Tech Corp. occupies a position emphasizing R-intensive development of high-specification extracts. Archer Daniels Midland Company exemplifies the distribution-integrator model, leveraging mainstream food ingredient networks to extend reach beyond specialty channels.
| Leading Market Players |
|---|
| Guilin Layn Natural Ingredients Corp. |
| GLG Life Tech Corp. |
| Archer Daniels Midland Company |
| Firmenich SA |
| Steviva Brands |
| Tate & Lyle |
| Cargill |
| NOW Foods |
| Monk Fruit Corp. |
| Others |
Value Chain & Pricing Dynamics
Guilin's 80% grip on global monk fruit cultivation concentrates extraction expertise and quality control capabilities in China's Guangxi Zhuang Autonomous Region, pushing margin pools downstream toward North American beverage formulators who absorb premiums for FDA-compliant, high-purity mogroside V extracts.
Pricing Analysis
Configured-to-order pricing for customized mogroside V concentrations commands substantial premiums over standard 25-55% extract specifications. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by purity grade, organic certification status, and technical service bundling. Cost compression in standard-grade powders is intensifying because stevia supply scale advantages constrain monk fruit pricing flexibility. Mid-scale craft beverage manufacturers exhibit highest price sensitivity, while multinational carbonated drink companies prioritize batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms from Guilin-based extraction facilities to North American distributors now stretch 90-120 days, reflecting supply-chain finance facilities designed to lock in procurement relationships. Raw material sourcing draws from China's Guangxi Zhuang Autonomous Region, with secondary processing concentration in Guangdong and California. Single-source vulnerability around Guilin cultivation exposes buyers to NMPA export certification delays and weather disruption. Distribution runs through direct B2B e-commerce platforms disintermediating traditional ingredient distributors for mid-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
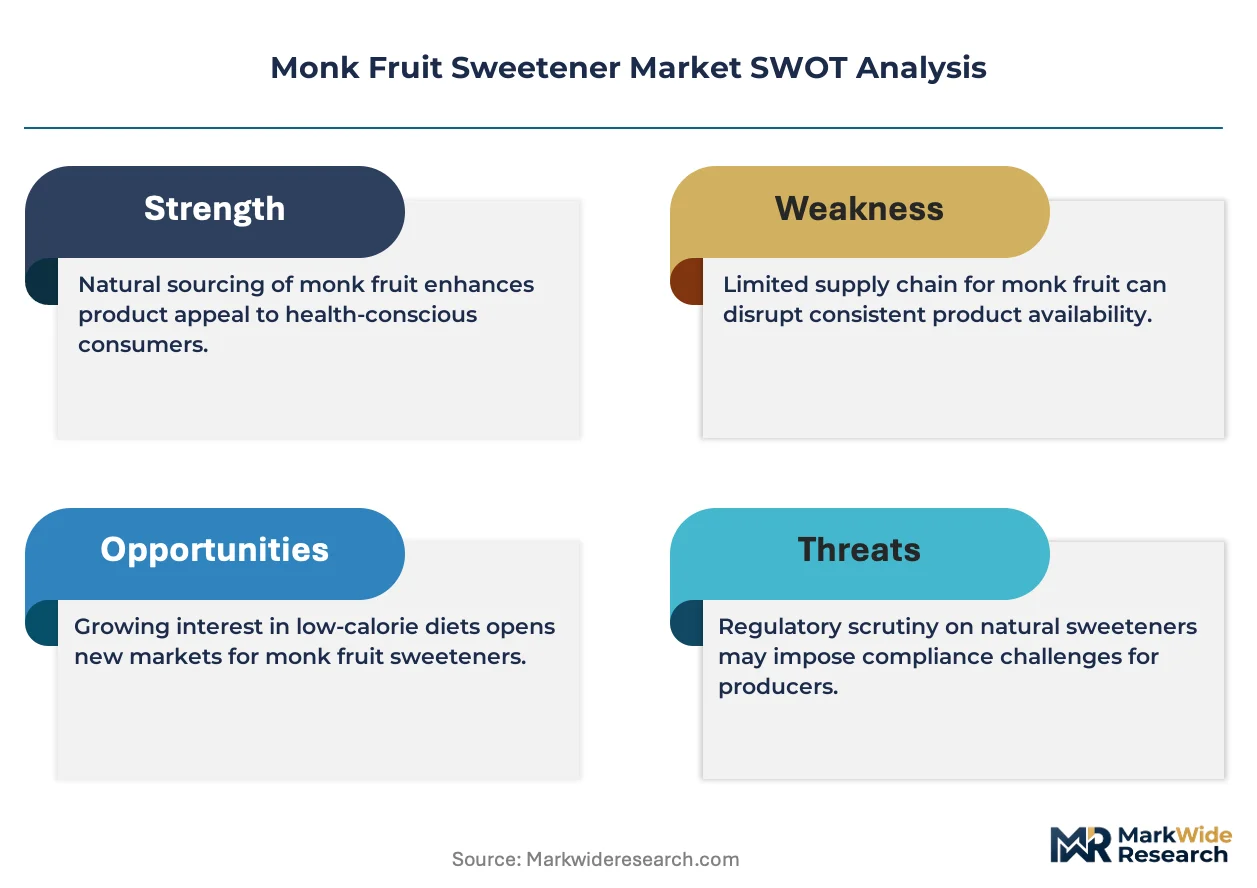
Monk fruit sweetener markets fragment across application-specific formulation requirements, with clean-label beverage mandates and regional regulatory divergence creating defendable niches for specialized suppliers.
For Market Incumbents: Entrench procurement relationships through captive supply agreements with Guilin extraction facilities, securing preferential access ahead of NMPA certification bottlenecks. Add in-house mogroside fingerprinting capabilities to reduce dependency on scarce analytical chemist expertise concentrated in China. Stevia-mogroside hybrid R&D investments represent the priority defensive lever against pure-play monk fruit commoditization.
For New Entrants and Emerging Players: India's FSSAI regulatory uncertainty offers first-mover positioning ahead of formal monk fruit approval across 1.4 billion consumers. Liquid concentrate formats for ready-to-drink functional waters present the most penetrable segment given rapid-dissolution technical requirements that powder incumbents struggle to match. Direct Alibaba procurement relationships with Guilin cultivators enable cost-competitive market entry without distributor markup.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty ingredient platforms seeking geographic expansion through monk fruit capability addition. Five-to-ten year viability hinges on EU novel food reclassification and India FSSAI approval timelines rather than near-term volume growth. Monitor EFSA regulatory pathway progress as the critical inflection signal for European market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guilin Cultivation | Captive supply secures preferential NMPA certification access and quality control from harvest through extraction. |
| High-Purity Mogroside V R&D Investment | Concentrations above 50% reduce dosage requirements and enable premium positioning in carbonated beverage formulations. |
| India FSSAI Regulatory Approval Pathway | Early clearance establishes first-mover positioning in a population-scale market currently blocked to established players. |
| Liquid Concentrate Format Development | Rapid-dissolution properties unlock clean-label positioning in functional waters where powder alternatives create production bottlenecks. |
| Direct E-Commerce Platform Launch | Alibaba and specialized B2B marketplaces disintermediate traditional distributors, compressing lead times for mid-scale craft beverage buyers. |
Study Parameters
Initial hypotheses were tested against primary input from beverage formulation chemists, extraction facility quality control managers, food ingredient procurement directors, and regulatory affairs specialists at monk fruit suppliers, then refined through secondary validation against FDA GRAS filings, NMPA export certification records, EFSA novel food applications, and customs trade data for monk fruit extract shipments. Bottom-up volume estimates from application-specific consumption patterns were triangulated against top-down market sizing from supplier revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product format, application category, purity specification tier, end-user scale, and regional regulatory cluster. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Key forecast inputs included carbonated beverage clean-label mandate adoption curves and NMPA certification timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by multinational ingredient platforms would shift outcomes through supply concentration acceleration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Fermented Sweeteners Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Molasses Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Stevia Mints Market
Sweeteners
Japan Allulose Market
Sweeteners
White Sugar Market
Sweeteners
India Cane Sugar Market
Sweeteners
Fructose Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
North America Food Sweetener Market
Sweeteners
D-Mannose Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Maltitol Market