
 Polyol Sweeteners Market | 2026-2036
Polyol Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Polyol Sweeteners Market Intelligence
Market Context
Modular sweetener systems that combine erythritol with bulking agents is expanding choice for beverage and bakery formulators seeking clean-label sugar reduction. Cargill, Incorporated leverages its integrated fermentation and corn-processing infrastructure to anchor supply security across North American and European markets. Roquette Frères sustains leadership in pharmaceutical-grade mannitol through dedicated pea-starch extraction capabilities and European manufacturing scale. Gulshan Polyols Ltd. dominates crystalline sorbitol production from its Indian base, competing on cost-advantaged feedstock access across Asian export channels.
Technical Definition and Segment Structure
Polyol sweeteners are hydrogenated carbohydrate derivatives—sorbitol, mannitol, xylitol, and erythritol—that provide bulk, sweetness, and humectancy with reduced caloric impact and minimal glycemic response, produced through catalytic hydrogenation of corresponding sugars or fermentation of glucose substrates. Erythritol leads growth trajectories due to its zero-calorie label and superior digestive tolerance, while sorbitol remains the mature volume anchor in toothpaste and sugar-free confectionery. The powder form commands premium positioning in pharmaceutical tableting and controlled-release applications, whereas liquid sorbitol occupies cost-sensitive industrial uses including resin and surfactant feedstocks.
Regulatory Framework and Outlook
The FDA governs polyol labeling through its added-sugar disclosure rules and GRAS self-affirmation pathways, while the EFSA establishes acceptable daily intakes and novel food authorizations that gate European market entry for emerging polyol variants. India's FSSAI enforces purity specifications and additive codex alignment that shape import requirements and domestic manufacturing standards for food-grade polyols. Stakeholders must monitor evolving front-of-package warning systems in Latin American and Southeast Asian jurisdictions, as these labeling regimes will determine reformulation incentives and regional demand elasticities ahead of formal regulatory harmonization.
Market Dynamics
FDA-mandated added-sugar disclosure on Nutrition Facts panels is forcing CPG manufacturers toward reformulation with bulk sweeteners that maintain mouthfeel without glycemic load, compressing the transition timeline for polyol adoption in mainstream retail categories.
Growth Catalysts
- Clean-Label Reformulation:Beverage brands in the United States are accelerating sugar-reduction timelines to meet retailer shelf-space requirements for reduced-sugar claims.
- GRAS Self-Affirmation Pathway:The FDA's streamlined food-additive clearance process reduces time-to-market for novel polyol blends targeting confectionery applications.
- Germany's Bakery Procurement:Industrial bakeries in Germany are consolidating polyol purchasing through cooperative buying arrangements that validate supply reliability at scale.
Market Restraints
- Corn Feedstock Volatility:Drought conditions in the US Midwest elevate glucose substrate costs for hydrogenation-based sorbitol production.
- Asian Supply Concentration:Crystalline sorbitol output clusters in Indian manufacturing corridors, creating single-source vulnerability for European compounders.
- Digestive Tolerance Ceiling:Erythritol's osmotic threshold limits inclusion rates in adult nutrition products without blend modification.
Strategic Opportunities
- Brazil's Functional Beverage Gap:ANVISA's pending novel-food framework for reduced-calorie sweeteners opens first-mover positioning in South America's largest processed-food market.
- Pharmaceutical-Grade Certification:USP and EP compliance for mannitol tablet production commands 40-60% price premiums over food-grade material.
- Fermentation-Convergent Bioprocessing:Microbial erythritol synthesis integrated with enzymatic purification is collapsing capital requirements for mid-scale producers.
Industry Challenges
- Specialized Hydrogenation Engineering:Catalytic reactor operation for polyol conversion requires process chemists with petrochemical or fine-chemical backgrounds, talent pools that food-grade manufacturers rarely maintain in-house.
- Multi-Jurisdiction Labeling Harmonization:Front-of-package warning systems in Mexico, Chile, and Colombia impose conflicting iconography requirements that fragment packaging runs for exported finished goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyol Sweeteners Market |
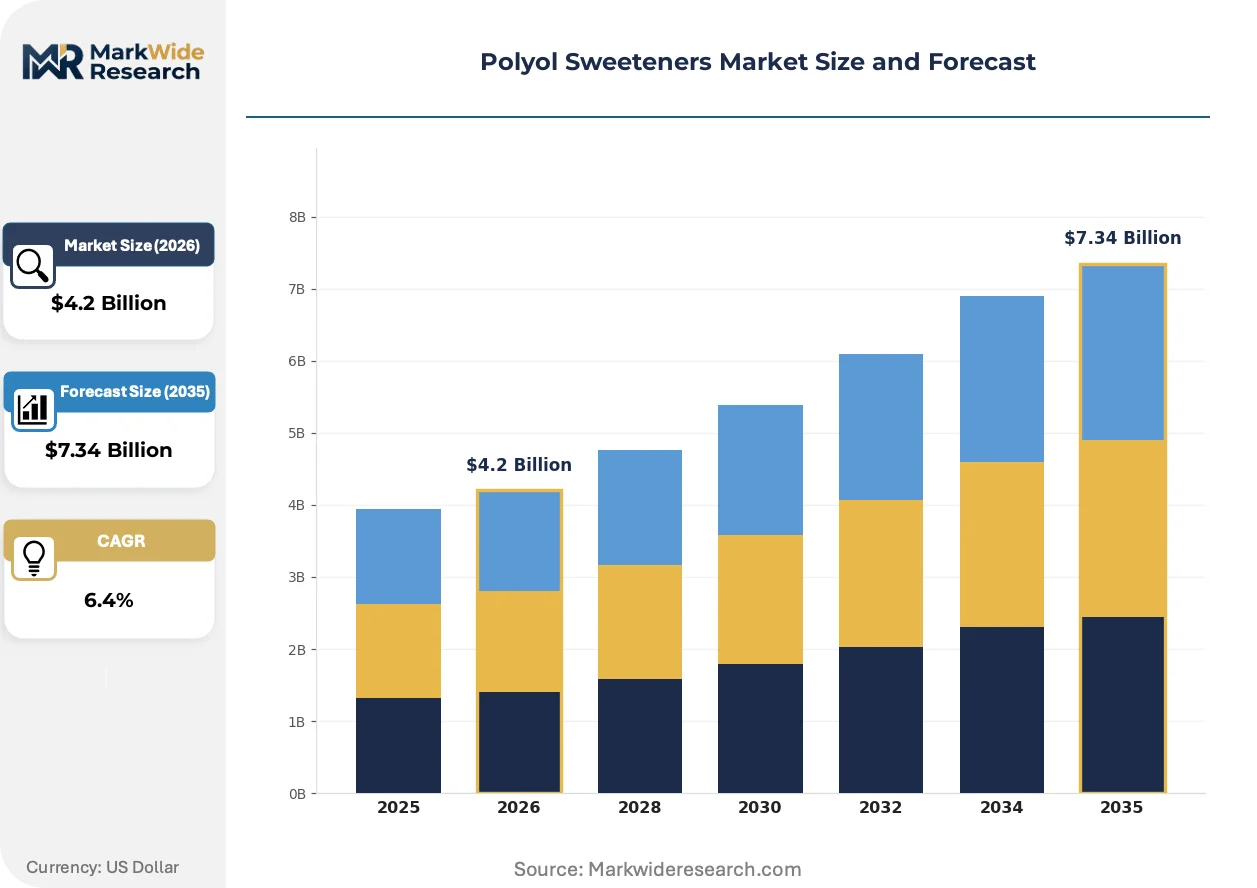
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbitol, Mannitol, Xylitol, Erythritol Application: Beverages, Bakery Products, Confectionery, Dairy Products Form: Powder, Liquid, Granulated, Crystal End User: Food Industry, Pharmaceuticals, Cosmetics, Animal Feed |
| Companies Covered | Roquette Frères, Gulshan Polyols Ltd., Cargill, Incorporated, B Food Science Co., Ltd., Sweeteners Plus, LLC, Archer Daniels Midland Company, Tereos S.A., SPI Pharma, Inc., Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyol Sweeteners Market Strategic Shifts & Innovations
Modular sweetener architectures are displacing single-ingredient substitutions as formulators seek precise control over bulking, sweetness curves, and digestive tolerance in reduced-sugar applications.
Enzymatic erythritol production from wheat-derived glucose feedstock is modularizing supply chains for European bakery compounders. Industrial biotech firms in the Netherlands and Germany are deploying continuous fermentation systems that cut batch cycle times by half. This platform is compressing minimum efficient scale thresholds and enabling regional production nodes closer to formulation facilities.
EFSA's tightened acceptable daily intake reviews for sugar alcohols are accelerating toxicological dossier preparation among specialty ingredient suppliers. The regulatory friction is elevating documentation costs for novel polyol entrants. Pharmaceutical and pediatric nutrition segments are responding by consolidating supplier relationships with established GRAS-affirmed producers.
Ingredient procurement for sugar-reduced confectionery is rotating from spot-market purchasing toward multi-year toll-manufacturing agreements. Major chocolate producers in Switzerland and Belgium are locking crystalline maltitol supply through dedicated processing lines. This contractual shift is most visible in premium positioned gifting segments where reformulation cycles span 18-24 months.
Polyol Sweeteners Market Segmentation
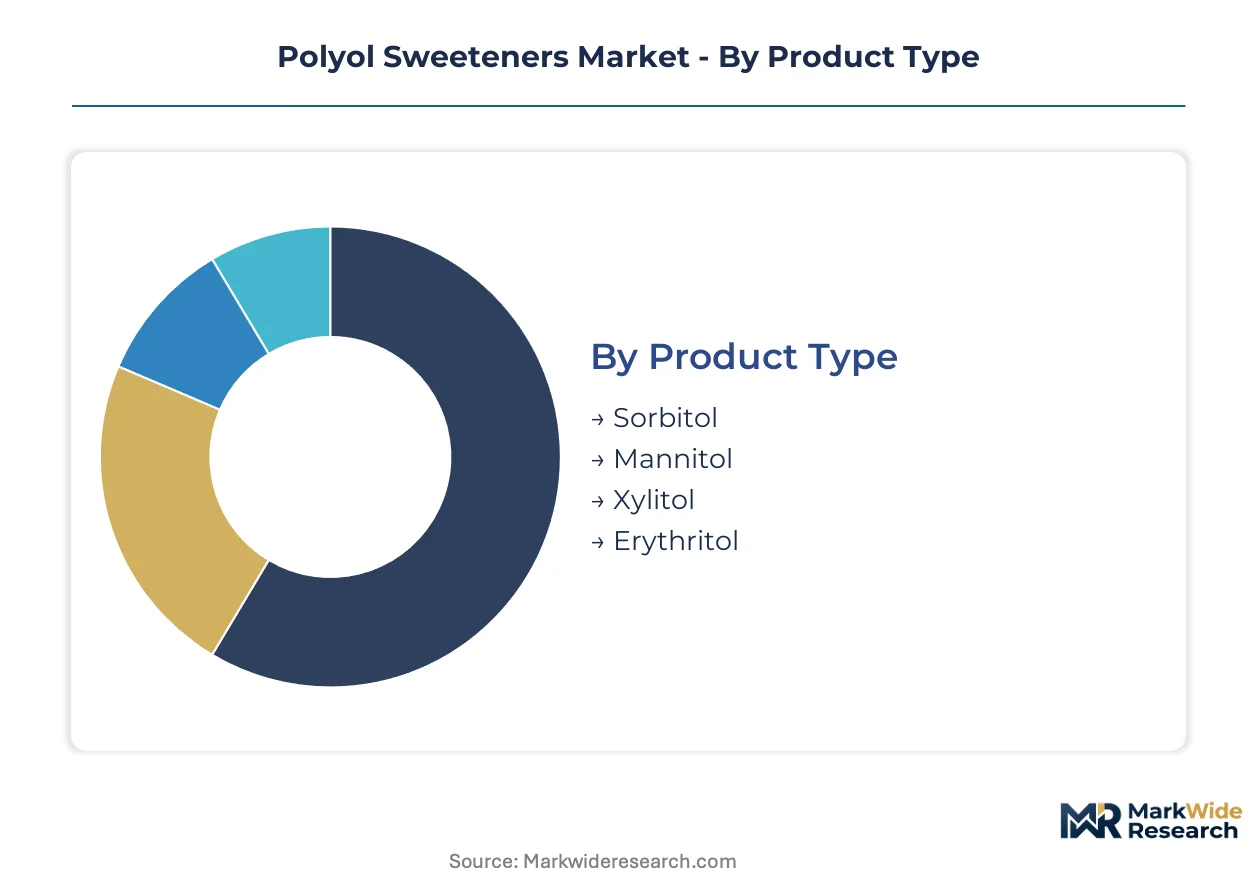
Polyol sweetener procurement patterns diverge sharply across end-use specifications, with pharmaceutical-grade purity requirements commanding fundamentally different supply relationships than commodity food-grade volumes. Formulators select hydrogenated carbohydrate derivatives based on glycemic index targets, digestive tolerance thresholds, and regional labeling regulations that vary by application.
Product Type:
Industrial buyers differentiate primarily by caloric claim eligibility and fermentation-derived versus catalytic hydrogenation sourcing credentials.
- Sorbitol:Catalytic hydrogenation of glucose yields this hexitol sugar alcohol with 2.6 kcal/g caloric density and pronounced hygroscopicity. Toothpaste manufacturers in Germany and confectionery compounders across India absorb the majority of crystalline and liquid sorbitol output respectively, with glucose feedstock cost volatility from US Midwest drought cycles compressing margin structures for hydrogenation-based producers.
- Erythritol:Fermentative production from wheat-derived glucose by Moniliella pollinis or Trichosporonoides megachiliensis generates this zero-calorie tetritol with exceptional digestive tolerance. Beverage brands in the United States and clean-label bakery innovators in the Netherlands are consolidating procurement through multi-year toll-manufacturing agreements to secure supply ahead of ANVISA's pending novel-food framework in Brazil.
- Mannitol:Pea-starch extraction followed by catalytic hydrogenation produces this hexitol with low hygroscopicity and negative heat of solution ideal for pharmaceutical tableting. Swiss and Belgian chocolate producers leverage mannitol's cooling effect in premium sugar-free gifting segments.
- Xylitol:Birch wood hydrolysate or corn cob fermentation yields this pentitol with caries-inhibiting properties recognized by dental associations. Finnish and Chinese producers dominate birch-derived and corn cob-derived supply channels respectively.
Sorbitol leads volumes today; erythritol is gaining share fastest.
Application:
Reformulation timelines and retailer shelf-space requirements create divergent urgency profiles across finished goods categories.
- Beverages:Functional drink manufacturers require low-glycemic bulk sweeteners that maintain mouthfeel without triggering FDA added-sugar disclosure thresholds. North American brands are accelerating procurement of erythritol-allulose blends to meet clean-label retailer mandates.
- Confectionery:Sugar-free chocolate and hard candy production demands precise control over cooling effects and crystallization kinetics. Swiss premium producers are locking crystalline maltitol supply through dedicated processing lines with 18-24 month reformulation cycles.
- Bakery Products:Industrial bread and pastry manufacturers prioritize humectancy and Maillard browning control. German cooperative buying arrangements are consolidating polyol procurement at scale for reduced-sugar claims.
- Dairy Products:Ice cream and yogurt applications require freezing point depression and protein stability compatibility. Formulators balance erythritol inclusion rates against osmotic tolerance thresholds in adult nutrition positioning.
Beverage procurement is accelerating most quickly; confectionery retains the highest contract durations.
Form:
Physical state determines handling infrastructure requirements and minimum order economics for downstream compounders.
- Powder:Spray-dried or milled material with specified particle size distribution for pharmaceutical tableting and instant beverage premixes. USP and EP compliance for mannitol powder commands substantial price premiums over food-grade specifications.
- Liquid:Aqueous sorbitol solutions at 70% solids concentration serve cost-sensitive industrial feedstocks including alkyd resins and surfactant production. Indian manufacturing corridors cluster crystalline sorbitol output for Asian export channels.
- Granulated:Agglomerated particles for improved flow properties in direct-compression tableting and dry beverage mixes. European bakery compounders favor granulated erythritol for reduced-dust handling.
- Crystal:Purified recrystallized material for highest purity pharmaceutical and pediatric nutrition applications. Stringent FSSAI purity specifications shape Indian import requirements for food-grade crystal grades.
Liquid sorbitol dominates tonnage movements; powder formats capture value concentration.
End User:
Regulatory oversight intensity and documentation requirements stratify supplier relationships across customer categories.
- Food Industry:CPG manufacturers navigate FDA GRAS self-affirmation and EFSA acceptable daily intake frameworks simultaneously. Front-of-package warning systems in Mexico, Chile, and Colombia impose conflicting iconography requirements that fragment packaging runs.
- Pharmaceuticals:Tablet excipient and pediatric nutrition applications demand USP, EP, and JP pharmacopeial compliance with full toxicological dossiers. EFSA's tightened ADI reviews are elevating documentation costs and consolidating supplier relationships with established GRAS-affirmed producers.
- Cosmetics:Humectant and viscosity-modifying applications in oral care and skincare tolerate broader purity ranges than ingestible grades. Toothpaste manufacturers represent mature volume anchors for sorbitol liquid and powder.
- Animal Feed:Palatability enhancement and moisture retention in pet food applications face less stringent regulatory scrutiny than human food uses. This segment absorbs lower-specification material rejected from pharmaceutical and food-grade streams.
Food industry procurement spans the widest geographic footprint; pharmaceuticals maintains the most concentrated supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The polyol sweetener industry traces its commercial origins to post-war European hydrogenation chemistry, with French and Belgian firms pioneering catalytic conversion of glucose-derived substrates into bulk sugar alcohols for confectionery and pharmaceutical applications.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia consolidate polyol procurement through cooperative buying arrangements that validate supply reliability at scale. The Federal Ministry of Food and Agriculture enforces strict additive labeling under the Lebensmittel- und Futtermittelgesetzbuch, mandating precise sugar alcohol declarations. Mannheim and Frankfurt host major compounder facilities where erythritol-maltitol blends undergo reformulation for reduced-sugar chocolate products.
United States
Functional beverage manufacturers in California and the Pacific Northwest accelerate reformulation timelines to meet retailer shelf-space requirements for clean-label sugar reduction. FDA-mandated added-sugar disclosure on Nutrition Facts panels compresses transition timelines for polyol adoption across mainstream retail categories. Cargill's integrated fermentation infrastructure in the Midwest anchors supply security for hydrogenation-based sorbitol production serving toothpaste and confectionery markets.
India
Crystalline sorbitol production concentrates in Haryana and Gujarat manufacturing corridors, competing on cost-advantaged feedstock access across Asian export channels. The Food Safety and Standards Authority of India enforces purity specifications and additive codex alignment that shape import requirements and domestic manufacturing standards. Mumbai-based distributors channel pharmaceutical-grade material toward pediatric nutrition applications with stringent documentation protocols.
Netherlands
Enzymatic erythritol production from wheat-derived glucose feedstock modularizes supply chains for European bakery compounders in the Randstad region. EFSA establishes acceptable daily intakes and novel food authorizations that gate European market entry for emerging polyol variants. Rotterdam's port infrastructure facilitates bulk liquid sorbitol transshipment toward resin and surfactant industrial users in the German Ruhr basin.
Brazil
ANVISA's pending novel-food framework for reduced-calorie sweeteners opens first-mover positioning in South America's largest processed-food market. São Paulo-based beverage formulators evaluate erythritol-allulose blends ahead of regulatory clarity expected in the coming enforcement cycle. The Southeast region's dairy and ice cream manufacturers represent latent demand for freezing point depression technologies once import protocols stabilize.
Polyol Sweeteners Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade mannitol commanding substantial price elevation over food-grade sorbitol volumes. The vendor base distributes across integrated agribusiness conglomerates, specialized fermentation houses, and regional hydrogenation specialists. Three archetypes dominate: corn-processing majors with captive glucose supply, pea-starch extractors serving pharmaceutical excipient demand, and Asian cost-competitive crystalline producers. Capacity expansion and toll-manufacturing partnerships constitute the primary competitive vectors as formulators seek supply security through dedicated processing lines.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company occupy positions that exemplify upstream control over fermentation and hydrogenation infrastructure. Roquette Frères represents the specialized pharmaceutical-grade archetype through its European manufacturing scale. Gulshan Polyols Ltd. anchors the cost-competitive Asian production cluster. These three firms collectively illustrate how feedstock access, certification depth, and regional market proximity stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Roquette Frères |
| Gulshan Polyols Ltd. |
| Cargill, Incorporated |
| B Food Science Co., Ltd. |
| Sweeteners Plus, LLC |
| Archer Daniels Midland Company |
| Tereos S.A. |
| SPI Pharma, Inc. |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade certification requirements from USP and EP are compressing supplier margins as compounders demand full toxicological dossiers, forcing hydrogenation-based producers to absorb documentation costs or cede share to fermentation specialists with cleaner label credentials.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates mannitol tablet excipients commanding substantial premiums from commodity sorbitol volumes. Price differentiation rests on certification depth and purity specifications, with USP-compliant mannitol drawing the widest spreads. Cost compression in food-grade sorbitol is intensifying because glucose feedstock volatility from US Midwest drought cycles squeezes hydrogenation margins. Industrial resin compounders exhibit highest price sensitivity, while pediatric nutrition formulators show least elasticity for certified grades.
Supply Chain Analysis
Single-source vulnerability sits with Indian crystalline sorbitol corridors in Haryana and Gujarat, where cost-advantaged feedstock access anchors Asian export flows. Production draws from corn-derived glucose in the US Midwest, wheat-derived substrates in the Netherlands, and pea-starch extraction in France. Regulatory restriction risk looms as EFSA tightens acceptable daily intake reviews, potentially gating novel polyol variants. Distribution runs through Rotterdam bulk liquid transshipment for industrial users and dedicated pharmaceutical toll-manufacturing lines for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is tilting toward pharmaceutical-grade specifications with full toxicological dossiers as EFSA scrutiny elevates documentation barriers.
For Market Incumbents: Anticipate margin compression in commodity sorbitol from Asian cost competitors by deepening certification moats around mannitol and erythritol grades. Secure captive glucose supply through backward integration into corn-processing infrastructure or long-term offtake agreements with Midwest agricultural cooperatives. Lock pharmaceutical compounders into multi-year toll-manufacturing contracts before EFSA's tightened ADI reviews consolidate supplier relationships further. For New Entrants and Emerging Players: The 40-60% price-point gap between pharmaceutical-grade mannitol and food-grade sorbitol creates entry space for mid-tier fermentation specialists with enzymatic purification capabilities. Brazil's pending ANVISA novel-food framework represents the most penetrable geography, with São Paulo beverage formulators actively evaluating erythritol-allulose blends ahead of regulatory clarity. A go-to-market angle anchored in regional production nodes near European bakery compounders bypasses established Asian supply chains. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-convergent bioprocessing firms that have collapsed capital requirements for mid-scale erythritol production. Over a multi-year holding window, consolidation will favor producers with integrated feedstock access and dual USP-EP certification depth. The inflection signal to watch is ANVISA's final novel-food rulemaking, which will unlock first-mover positioning in South America's largest processed-food market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn-processing infrastructure in the US Midwest anchors hydrogenation security against glucose price spikes. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance for mannitol commands substantial premiums over food-grade material in tablet excipient markets. |
| Regional Fermentation Node Deployment | Enzymatic erythritol production in the Netherlands and Germany cuts batch cycle times for European bakery compounders. |
| Long-Term Toll-Manufacturing Agreements | Swiss and Belgian chocolate producers lock crystalline maltitol supply through dedicated processing lines. |
| Regulatory Dossier Preparation | EFSA's tightened ADI reviews are elevating documentation costs and consolidating supplier relationships with established GRAS-affirmed producers. |
Research Approach
Multiple input streams — executive interviews with hydrogenation plant managers and pharmaceutical procurement leads, customs and trade data from Indian and European export corridors, and SEC filings from integrated agribusiness conglomerates — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from fermentation specialists in the Netherlands, pea-starch extraction operators in France, and FDA regulatory affairs consultants. Secondary validation drew from EFSA novel-food authorization databases, USP pharmacopeial standards, and FSSAI additive codex specifications.
Historical volume trajectories were cross-referenced against panel input from ingredient procurement directors to model projections across the analysis window. Segmentation dimensions included product type (sorbitol, erythritol, mannitol, xylitol), application (beverages, confectionery, bakery, pharmaceuticals), form (powder, liquid, granulated, crystal), and end-user regulatory intensity. CAGRs were derived from elasticity modeling against FDA added-sugar disclosure enforcement and EFSA acceptable daily intake revision timelines.
Caveats apply where ANVISA regulatory delays, US Midwest drought recurrence, or EFSA toxicological reassessments could materially shift the outlook. Forecasts embed assumptions around clean-label reformulation velocity and pharmaceutical certification adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Dry Molasses Market
Sweeteners
France Food Sweetener Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Sanding Sugar Market
Sweeteners
Xylose Market
Sweeteners
South Korea Allulose Market
Sweeteners
China Food Sweetener Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Floral Nectar Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Sugar Syrups Market