
 North America Stevia Market | 2026-2036
North America Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
North America Stevia Market Intelligence
A capital-intensity divergence between integrated extractors and formulation specialists is reorganizing competitive dynamics in North America stevia supply. Cargill Incorporated leverages its Midwest agricultural infrastructure to secure consistent leaf supply chains. PureCircle sustains proprietary breeding programs that yield higher rebaudioside concentrations. GLG Life Tech Corp anchors its position through backward integration into Chinese cultivation, though its North American distribution competes aggressively on purity grades.
Stevia comprises steviol glycosides extracted primarily from Stevia rebaudiana leaves, with rebaudioside A and stevioside constituting the principal sweetening compounds measured by purity percentage and bitter aftertaste threshold. Powder formulations dominate food manufacturing procurement due to shelf stability and dosing precision in baked goods and dry mixes. Liquid extracts lead growth in beverage applications where rapid dissolution and cold-process compatibility matter. The dietary supplements segment occupies a narrower but higher-margin niche, with tablet and granulated formats serving direct consumer channels where portability drives preference.
FDA GRAS notifications, USDA National Organic Program standards, and Health Canada Natural Health Product regulations collectively determine which steviol glycoside purities and extraction methods qualify for food and pharmaceutical use across North America. These frameworks create compliance thresholds that favor producers with documented supply chain traceability and third-party organic certification. Stakeholders must monitor pending EPA pesticide residue revisions for imported leaf and evolving FDA guidance on novel glycoside blends, as these will determine which extraction technologies justify capital deployment without regulatory disqualification risk.
Market Dynamics
Clean-label formulation mandates from major retail chains are compressing artificial sweetener shelf space and forcing beverage and bakery manufacturers to accelerate stevia integration timelines. This retailer-driven substitution pressure now overrides traditional cost-based procurement calculus across North American food processing.
Growth Catalysts
- FDA GRAS pathway:The FDA's streamlined notification process for high-purity steviol glycosides reduces regulatory lag for new extract entrants, enabling faster product launches in carbonated soft drinks and sports beverages.
- USDA Organic seal penetration:Dual-certified organic stevia extracts command placement premiums in natural channel retail, with California and Texas distribution hubs prioritizing certified suppliers for private-label lines.
- Enzymatic bioconversion:Novel enzymatic processes that transform low-grade stevioside into high-rebaudioside concentrates are lowering purity-grade production costs for mid-tier extractors.
Market Restraints
- Chinese leaf supply dominance:Over 80% of raw stevia leaf enters North America through Chinese cultivation corridors, exposing processors to phytosanitary inspection delays and tariff volatility.
- Bitter aftertaste threshold:Rebaudioside A formulations above 97% purity remain necessary for clean taste profiles, constraining cost-down options for mass-market beverage applications.
- Monk fruit extract substitution:Mogroside V from monk fruit competes directly in premium zero-sugar positioning, particularly in West Coast functional beverage clusters where label novelty drives trial.
Strategic Opportunities
- Mexico beverage manufacturing expansion:Mexican bottling corridors serving Latin American export markets present underpenetrated demand for stevia-sweetened regional soda formulations.
- Health Canada Natural Health Product designation:Stevia tablet and granulated formats qualifying under NHP regulations access pharmacy and practitioner channels with higher margin structures than conventional food retail.
- Precision fermentation convergence:Microbial production of steviol glycosides via engineered yeast strains promises to decouple supply from agricultural leaf cycles, though regulatory novelty creates approval timeline uncertainty.
Industry Challenges
- Organic certification timeline compression:USDA National Organic Program transition periods for conventional-to-organic leaf sourcing extend 36 months, straining working capital for suppliers pivoting to certified production.
- Extraction equipment specialization:Supercritical CO2 and membrane filtration systems for high-purity rebaudioside isolation require capital deployment that mid-scale processors struggle to finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Stevia Market |
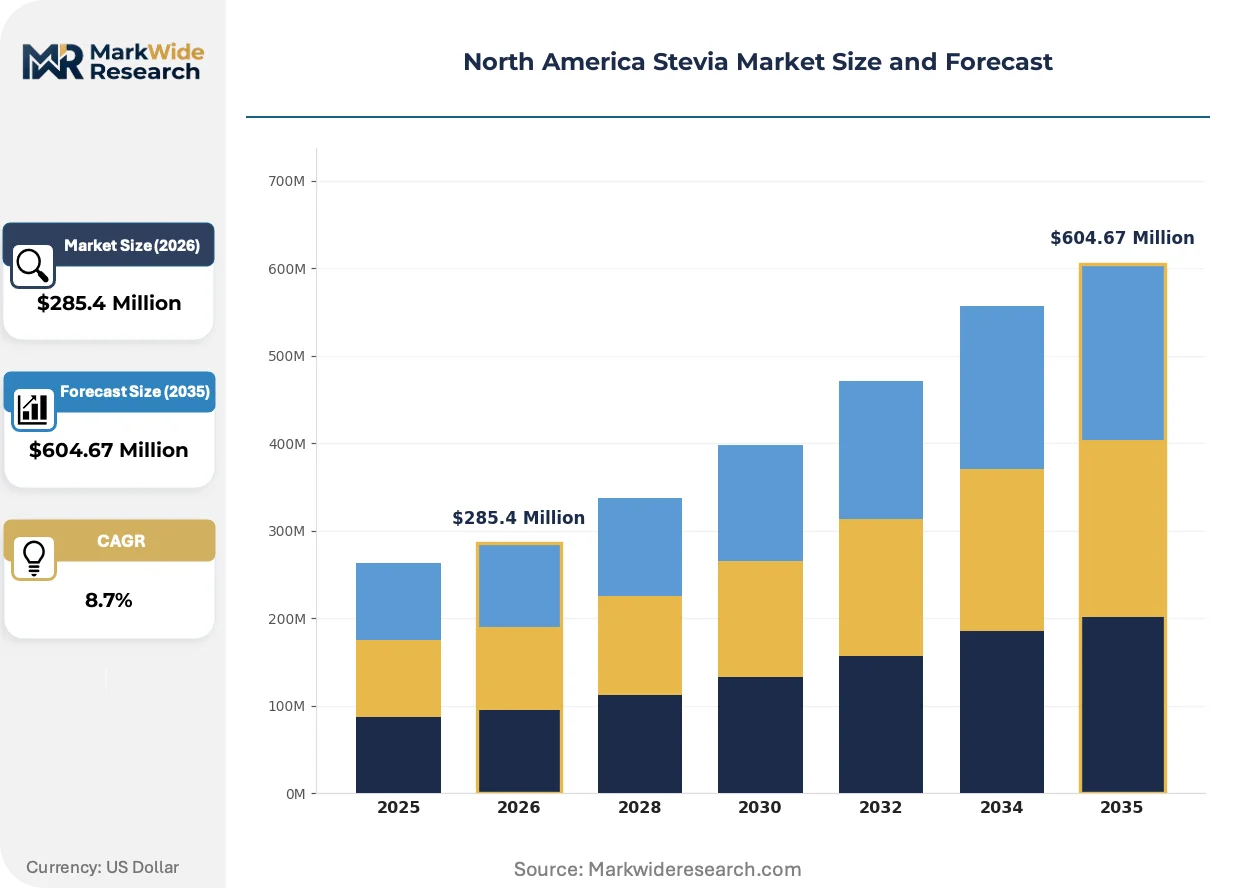
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granulated, Tablets Application: Food & Beverages, Pharmaceuticals, Personal Care, Dietary Supplements Customer Type: Direct Consumers, Retail Outlets, Food Manufacturers, Beverage Companies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | PureCircle, GLG Life Tech Corp, Cargill Incorporated, Stevia Corp, Evolva Holding SA, Ingredion Incorporated, Archer Daniels Midland Company, PepsiCo Inc, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Stevia Market Strategic Shifts & Innovations
Bioconversion technologies and enzymatic glycoside modification are destabilizing traditional extraction economics, while regulatory clarity on novel production methods lags technical capability. These forces are compressing incumbent advantage windows and opening entry paths for biotechnology-enabled competitors.
Enzymatic glycoside modification is fragmenting conventional extraction value chains by enabling processors to upgrade lower-grade stevioside into premium rebaudioside D and M variants without leaf-dependent cultivation. Beverage formulators in California and Texas are piloting these modified glycosides for cleaner taste profiles in cold-brew coffee and flavored waters. The technology is fragmenting procurement patterns as manufacturers diversify away from single-source leaf supply contracts toward enzyme-supplier partnerships.
Health Canada's pending guidance on novel steviol glycoside production methods will determine which precision fermentation and bioconversion outputs qualify for Natural Health Product designation. The regulatory uncertainty is freezing capital commitment from biotechnology entrants awaiting pathway clarity. Dietary supplement manufacturers are most exposed, as their tablet and granulated format strategies depend on NHP-compliant ingredient sourcing that conventional extraction currently satisfies.
Direct-procurement relationships between beverage multinationals and stevia extractors are displacing traditional ingredient distributor intermediaries in high-volume contract negotiations. Formulation specialists at major bottlers now specify purity grades and glycoside blends directly, compressing margin capture for regional distributors. This disintermediation is most visible in Texas and California, where clean-label processing clusters concentrate procurement decision-making among a tight buyer set.
North America Stevia Market Segmentation
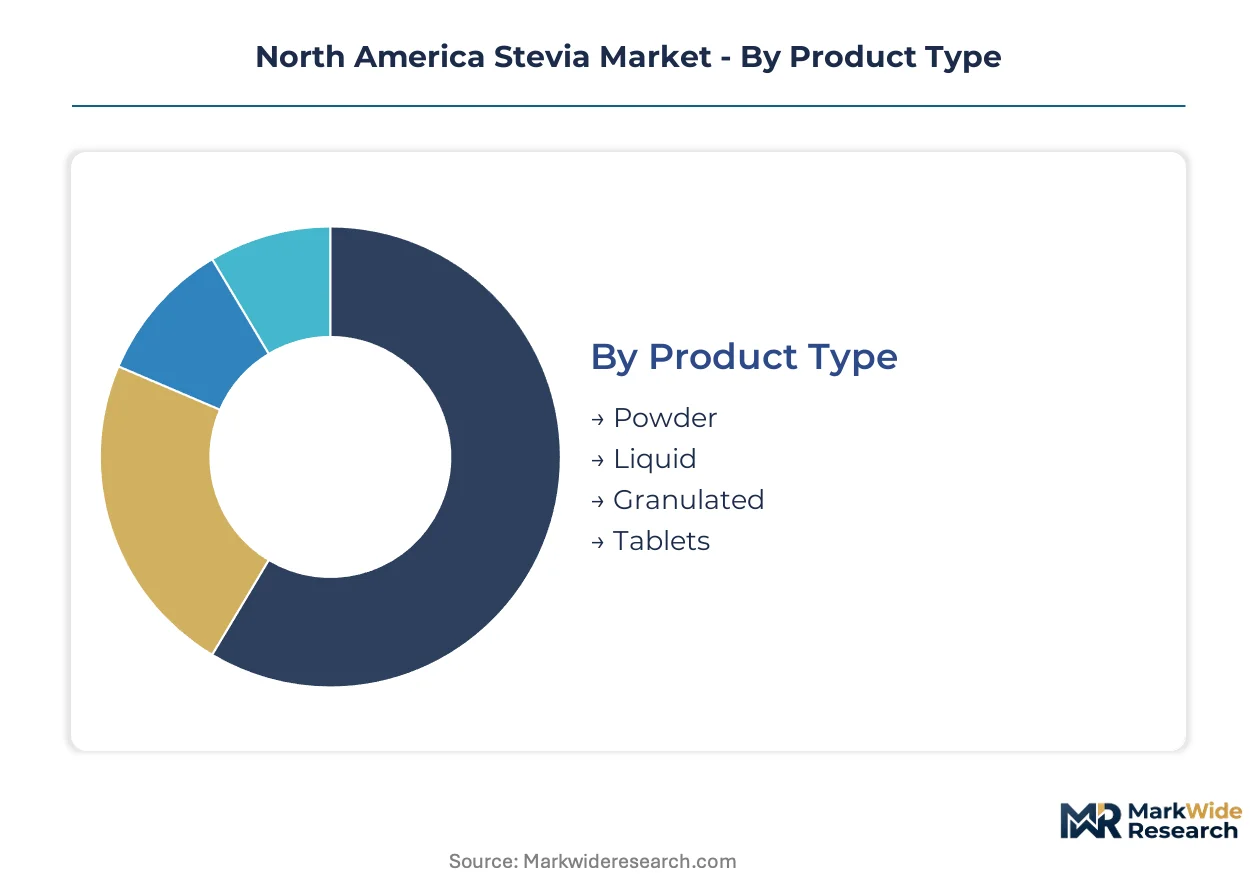
Stevia procurement patterns diverge sharply across product formats and end-use channels, with regulatory thresholds determining which segments qualify for food-grade versus pharmaceutical-grade applications. Understanding these divides reveals where margin pools concentrate and which customer relationships command pricing power.
Product Type:
FDA GRAS notifications for high-purity steviol glycosides apply differentially across physical formats, with powder and liquid extracts facing distinct stability testing requirements for beverage versus baked good applications.
- Powder:Dry crystalline formulations with standardized rebaudioside A content between 95% and 99% purity dominate commercial bakery and dry mix manufacturing. Texas and California food processing clusters drive bulk procurement due to shelf stability and precise dosing in high-temperature applications.
- Liquid:Aqueous or alcohol-based extracts with rapid cold-water dissolution properties lead adoption in beverage manufacturing. Mexican bottling corridors serving Latin American export markets are expanding procurement of liquid formats for zero-sugar regional soda formulations.
- Granulated:Bulking-agent blends with maltodextrin or erythritol carriers suit tabletop sweetener retail packaging.
- Tablets:Compressed formats with defined dissolution profiles target dietary supplement channels requiring Health Canada NHP compliance.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Cost tier differentiation separates mass-market food and beverage adoption from premium pharmaceutical and supplement positioning, with certification requirements widening the procurement gap between tiers.
- Food & Beverages:Carbonated soft drinks, sports beverages, baked goods, and condiments constitute the volume anchor. Clean-label mandates from major retail chains are compressing artificial sweetener shelf space and forcing accelerated stevia integration timelines across North American processing.
- Dietary Supplements:Tablet and granulated formats serving direct consumer channels command higher margins than conventional food retail. Health Canada Natural Health Product designation unlocks pharmacy and practitioner channels with superior pricing structures.
- Pharmaceuticals:Excipient and active sweetener applications require documented supply chain traceability for FDA compliance.
- Personal Care:Toothpaste and cosmetic formulations utilize stevia for non-cariogenic sweetness with minimal regulatory burden.
Food and Beverages captures the dominant volume position; Dietary Supplements is expanding most quickly on margin contribution.
Customer Type:
Procurement concentration among beverage multinationals is displacing traditional ingredient distributor intermediaries, with direct-specification relationships now governing high-volume contract negotiations.
- Beverage Companies:Major bottlers in Texas and California now specify purity grades and glycoside blends directly with extractors, compressing margin capture for regional distributors. Formulation specialists demand rebaudioside A formulations above 97% purity for clean taste profiles in mass-market applications.
- Food Manufacturers:Bakery and dry mix processors prioritize powder formats with consistent dosing precision and thermal stability.
- Retail Outlets:Private-label lines at natural channel retailers prioritize dual-certified organic stevia extracts for placement premiums.
- Direct Consumers:Individual purchasers through e-commerce and health food stores favor portable tablet and granulated formats.
Beverage Companies direct the largest procurement volumes; Food Manufacturers are gaining share fastest on clean-label reformulation mandates.
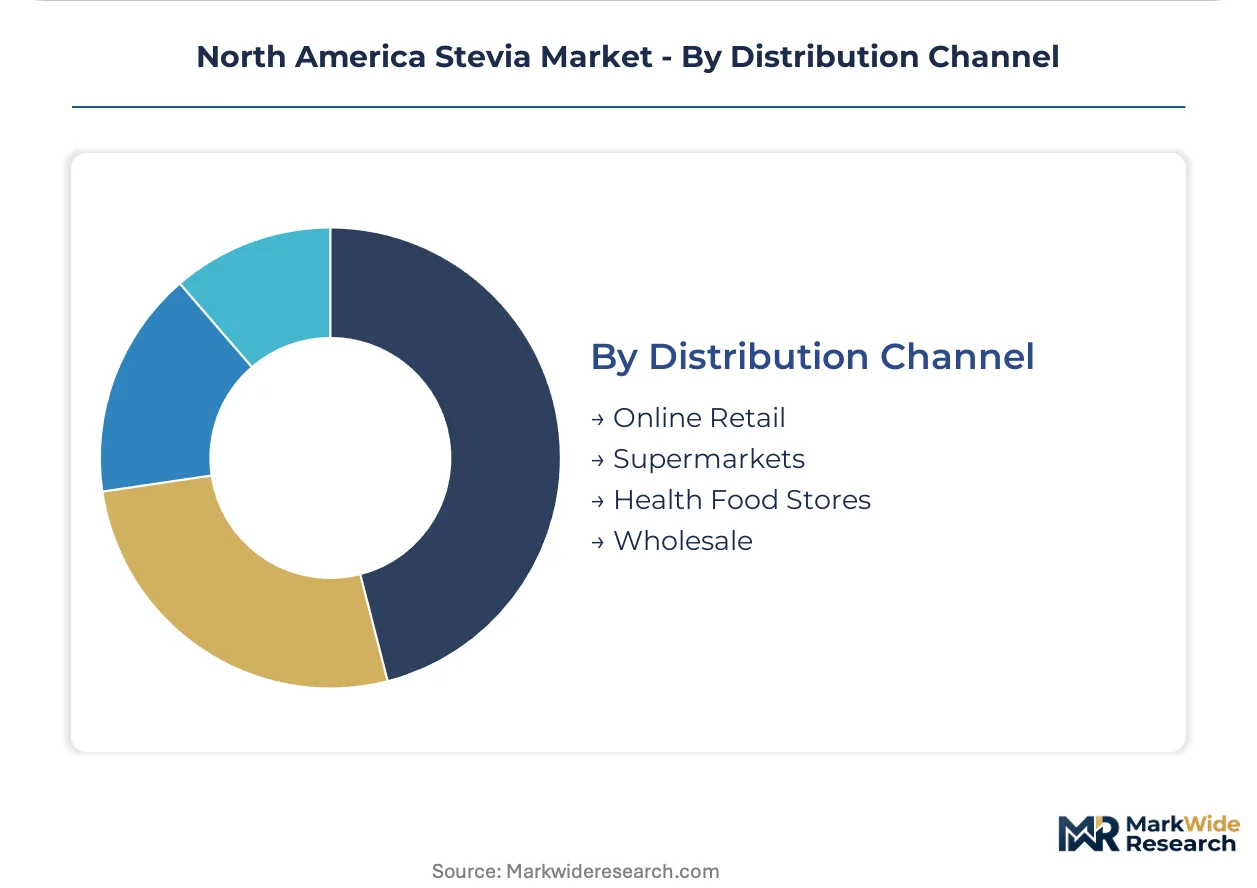
Distribution Channel:
Geographic clustering of clean-label processing capacity in California and Texas shapes channel preference, with proximity to formulation centers determining logistics economics.
- Wholesale:Bulk extract shipments to food and beverage manufacturing clusters dominate volume flow. Direct-procurement relationships between multinationals and extractors are restructuring traditional distributor roles in high-volume negotiations.
- Online Retail:Direct-to-consumer tablet and granulated formats are climbing fastest as supplement purchasers prioritize convenience and subscription replenishment.
- Supermarkets:Mass retail placement of tabletop sweeteners competes on price with artificial alternatives.
- Health Food Stores:Natural channel retailers command placement premiums for USDA Organic seal-bearing products.
Wholesale manages the dominant throughput position; Online Retail is climbing fastest on consumer format preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas processing corridors, while Mexican manufacturing clusters capture volume growth on export-facing beverage contracts. This asymmetry reflects divergent regulatory burdens and clean-label procurement intensity across the three North American markets.
United States
Beverage multinationals in Texas and California now specify stevia purity grades directly with extractors, bypassing traditional distributors. FDA GRAS notifications for high-purity steviol glycosides streamline new product launches in carbonated soft drinks. The California clean-label processing cluster drives bulk procurement of organic-certified extracts for private-label retail lines.
Mexico
Bottling corridors serving Latin American export markets are expanding stevia-sweetened regional soda formulations at pace. Mexican processors face fewer organic certification hurdles than US counterparts, enabling faster formulation pivots. The Bajío Region and Mexico City Metro concentrate contract manufacturing capacity for zero-sugar beverage exports.
Canada
Health Canada Natural Health Product designation unlocks pharmacy and practitioner channels for tablet and granulated formats. Canadian supplement manufacturers command premium margins over conventional food retail through NHP-compliant sourcing. Ontario and Quebec house the dominant dietary supplement processing infrastructure for North American distribution.
North America Stevia Market Key Industry Players
Concentration sits with integrated agricultural processors and specialized extraction technology firms. The vendor base organizes around three strategic archetypes: Midwest agricultural conglomerates with captive leaf supply, biotechnology-enabled glycoside modifiers, and Asia-anchored suppliers with North American distribution arms. Dominant competitive moves include backward integration into cultivation corridors and enzymatic bioconversion partnerships that upgrade lower-grade stevioside into premium rebaudioside variants.
Among North America-anchored processors, Cargill Incorporated, PureCircle, and GLG Life Tech Corp occupy distinct positioning tiers. Cargill leverages Midwest agricultural infrastructure for consistent supply security. PureCircle sustains proprietary breeding programs yielding higher rebaudioside concentrations. GLG Life Tech Corp anchors its position through upstream control over Chinese cultivation, competing aggressively on purity grades in North American distribution.
| Leading Market Players |
|---|
| PureCircle |
| GLG Life Tech Corp |
| Cargill Incorporated |
| Stevia Corp |
| Evolva Holding SA |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| PepsiCo Inc |
| Tate & Lyle |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between beverage multinationals and integrated extractors lock in both supply access and price visibility across the North American stevia value chain, insulating processors from Chinese leaf spot-market volatility while committing buyers to minimum volume thresholds.
Pricing Analysis
The customization-premium spread between configured-to-order glycoside blends and standard rebaudioside A extracts runs wide in North American procurement. Three-tier pricing structure across premium, standard, and economy levels reflects purity percentage and organic certification status under USDA National Organic Program standards. Cost compression in standard-grade powder formats is intensifying because enzymatic bioconversion upgrades lower-grade stevioside into premium rebaudioside variants. Mass-market beverage manufacturers exhibit highest price sensitivity, while dietary supplement brands purchasing NHP-compliant tablet formats accept premium positioning.
Supply Chain Analysis
Chinese cultivation corridors anchoring raw leaf supply create a chokepoint that exposes North American processors to phytosanitary inspection delays and tariff volatility. Over 80% of raw stevia leaf enters the region through Chinese growing regions, with extraction equipment and enzymatic bioconversion enzymes drawing from German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in the agricultural tier, where no alternative leaf supply base matches Chinese scale. Distribution runs through direct-procurement relationships between beverage multinationals and extractors, displacing traditional ingredient distributor intermediaries in high-volume negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America stevia market sits at an inflection where enzymatic glycoside modification and precision fermentation technologies threaten to decouple supply from agricultural cycles, creating high-growth disruption potential contingent on FDA and Health Canada regulatory clarity.
For Market Incumbents: Compound defensive positioning through backward integration into Mexican cultivation corridors and accelerated enzymatic bioconversion partnerships that upgrade lower-grade stevioside. The threat of precision fermentation entrants producing steviol glycosides via engineered yeast strains demands preemptive capacity locking. Certification investment in USDA Organic and Health Canada NHP compliance creates switching-cost barriers.
For New Entrants and Emerging Players: Lead with biotechnology-enabled production methods targeting the dietary supplements segment, where NHP-compliant tablet and granulated formats command premium margins over conventional food retail. The most penetrable white space sits in precision fermentation outputs awaiting regulatory pathway clarity. A go-to-market angle anchored to supply security narratives—decoupled from Chinese leaf cycles—resonates with risk-conscious procurement officers at beverage multinationals.
For Investors and Strategic Acquirers: Biotechnology-enabled extraction specialists with proven enzymatic glycoside modification capabilities represent the priority acquisition archetype for portfolio exposure to clean-label sweetener disruption. Long-term viability over the coming decade hinges on regulatory approval timelines for novel production methods. The signal to watch is Health Canada's pending guidance on precision fermentation outputs qualifying for Natural Health Product designation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Partnership | Transforms low-grade stevioside into premium rebaudioside D and M variants, reducing leaf dependency. |
| Backward Integration into Cultivation | Cargill's Midwest agricultural infrastructure secures consistent supply security against Chinese volatility. |
| Dual Organic-NHP Certification Investment | Unlocks placement premiums in California natural channel retail and Canadian pharmacy channels. |
| Direct-Procurement Relationship Expansion | Beverage multinationals in Texas and California now specify purity grades directly with extractors. |
| Precision Fermentation Scale-Up | Microbial production via engineered yeast promises to decouple supply from agricultural leaf cycles. |
Research Approach
The analysis maps stevia extraction technologies, glycoside format categories, and end-use application segments, each validated through formulation specialists at beverage multinationals, procurement leads at food manufacturers, regulatory affairs directors, and extraction technology providers. Primary interviews with these stakeholders combined with secondary validation against FDA GRAS notifications, USDA National Organic Program standards, Health Canada Natural Health Product regulations, and trade flow data. Bottom-up volume modeling and top-down market sizing triangulate to consistent outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type (powder, liquid, granulated, tablet), application (food and beverages, dietary supplements, pharmaceuticals, personal care), and customer type (beverage companies, food manufacturers, retail outlets, direct consumers). CAGRs derive from segment-level growth trajectory analysis incorporating enzymatic bioconversion adoption curves and regulatory approval timeline assumptions for novel production methods.
The analysis sits within stated boundaries; outcomes outside FDA and Health Canada regulatory clarity on precision fermentation would require recalibration. Forecasts reflect assumptions on enzymatic technology adoption rates and Chinese leaf supply stability. Practitioners should keep alternative scenarios live as biotechnology regulatory pathways and EPA pesticide residue revisions for imported leaf evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Agave Nectar Market
Sweeteners
China Food Sweetener Market
Sweeteners
Sugar Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Coconut Sugar Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Rice Syrup Market
Sweeteners
Saccharin Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Steviol Glycoside Market