
 Existent Gum Steam Generator Market | 2026-2036
Existent Gum Steam Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Existent Gum Steam Generator Market Foresight
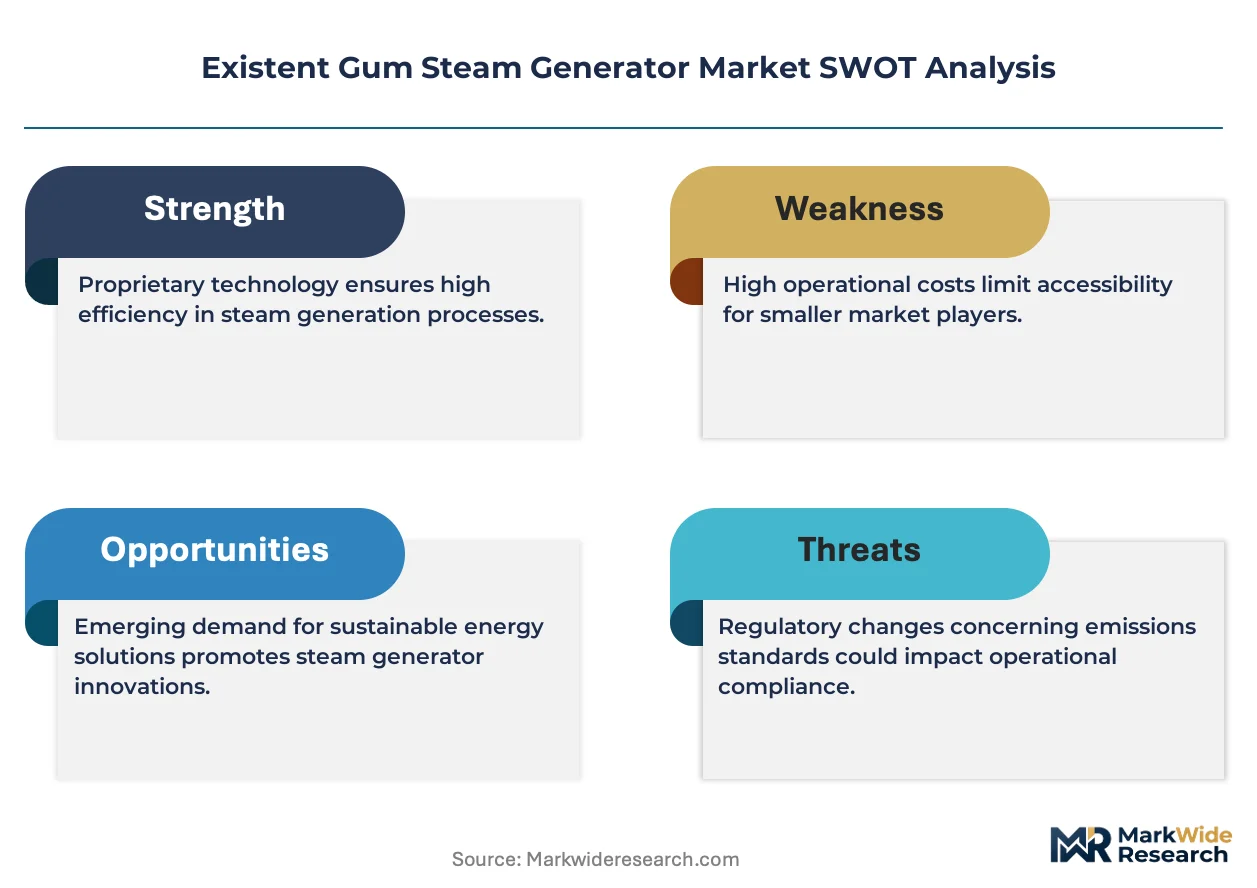
EPA Tier 3 gasoline sulfur standards is restructuring compliance investment across downstream testing laboratories. Anton Paar GmbH leverages its precision instrumentation heritage to dominate European calibration workflows. Koehler Instrument Company Inc. anchors North American refinery relationships through ASTM-method-aligned product portfolios. PAC LP competes on turnaround speed, sustaining service contracts with integrated oil majors.
An existent gum steam generator produces saturated steam at controlled pressure and temperature to accelerate gum deposit formation in hydrocarbon samples, enabling quantitative measurement of oxidation stability per ASTM D381 and ISO 6246 protocols. Electric-heated units dominate laboratory deployments due to thermal precision and elimination of combustion byproducts, while modular installations gain traction among mobile testing contractors seeking rapid site redeployment. Indirect steam generation technology leads in chemical and pulp paper end uses where process contamination risks mandate separation between heat source and working fluid.
FDA Good Laboratory Practice standards govern data integrity in fuel-quality testing workflows, while OSHA Process Safety Management rules constrain steam system design pressures in chemical plant installations. BIS certification requirements in India and GB standards in China create divergent product qualification pathways for exporters. Stakeholders must monitor evolving sulfur-content thresholds in automotive fuel specifications and calibrate generator procurement against regional testing-volume forecasts rather than headline capacity additions.
Market Dynamics
EPA Tier 3 sulfur-content testing mandates are forcing Gulf Coast refineries to accelerate laboratory instrumentation procurement, concentrating demand around ASTM D381-compliant steam generation systems. This regulatory pressure is restructuring equipment vendor relationships toward method-aligned service contracts.
Growth Catalysts
- Electric-heated thermal precision:Laboratory operators favor electric units for elimination of combustion byproducts and repeatable temperature control during oxidation stability testing.
- EPA Tier 3 gasoline sulfur standards:Downstream testing laboratories in petroleum refining corridors must upgrade gum measurement capabilities to meet phased compliance deadlines.
- Houston-Lake Charles refinery cluster:Concentrated downstream processing capacity in Texas and Louisiana generates sustained procurement volume for calibration-grade steam generators.
Market Restraints
- Stainless steel alloy cost volatility:Steam chamber fabrication depends on corrosion-resistant grades whose commodity pricing fluctuates with nickel supply disruptions.
- European calibration workflow concentration:Precision instrumentation expertise clusters with established vendors, limiting new entrant access to method-certified reference laboratories.
- Indirect steam generation thermal inefficiency:Heat exchanger architectures required for chemical plant contamination avoidance impose higher energy operating costs than direct-fired alternatives.
Strategic Opportunities
- Mobile testing contractor redeployment:Modular generator architectures enable rapid site relocation for field-based fuel quality verification services.
- India BIS certification pathway:Divergent product qualification requirements create first-mover advantage for exporters establishing local calibration partnerships.
- Pulp paper process contamination protocols:Indirect steam technology addresses heat-source separation mandates in chemical processing applications beyond petroleum testing.
Industry Challenges
- ASTM method certification timelines:New product qualification requires extended interlaboratory validation cycles that delay revenue recognition.
- Legacy steam system integration:Refurbishment projects demand mechanical compatibility with existing sample preparation workflows and data management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Existent Gum Steam Generator Market |
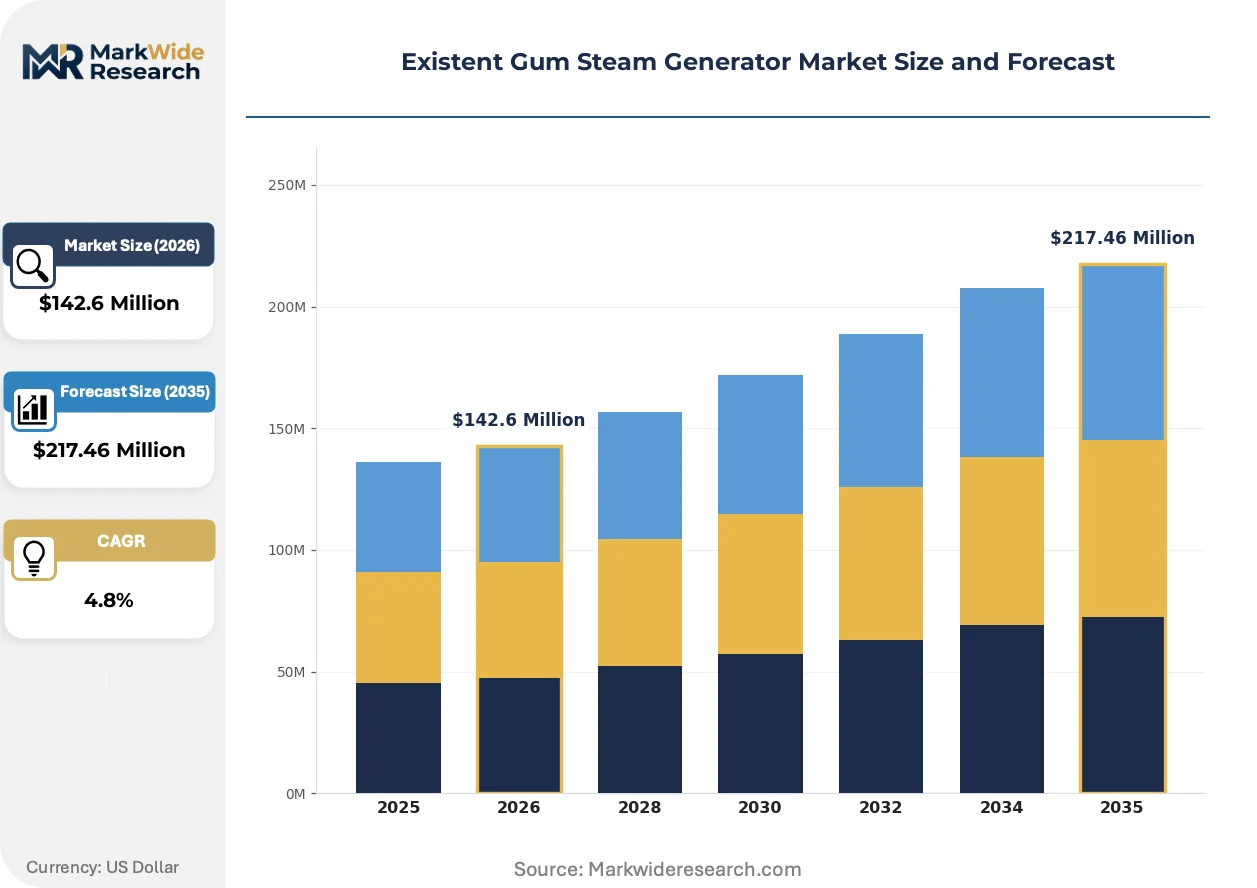
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $217.46 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Oil, Biomass Technology: Direct, Indirect, Modular, Hybrid End User: Food Processing, Textile, Chemical, Pulp & Paper Installation: Custom, Portable, Fixed, Compact |
| Companies Covered | Labtron Equipment Ltd, Koehler Instrument Company Inc., Anton Paar GmbH, Huazheng Electric Manufacturing (Baoding) Co., Ltd, Tanaka Scientific Limited, Shenzhen Kethink Electronic Co., Ltd., PAC LP, General Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Existent Gum Steam Generator Market Shifts & Advancements
Steam generator architecture is pivoting toward thermal precision and deployment flexibility as laboratory operators and field contractors diverge in operational priorities. Equipment vendors must now support two distinct performance specifications from shared component platforms.
Electric resistance heating is absorbing market preference in laboratory deployments due to its elimination of combustion variables and sub-degree temperature stability. Petroleum testing laboratories in EPA-regulated jurisdictions are adopting these units fastest, consolidating procurement around vendors with embedded ASTM method expertise. This thermal architecture is absorbing share from gas-fired alternatives by simplifying compliance documentation and reducing ventilation infrastructure requirements.
OSHA Process Safety Management rules are constraining steam system design pressures in chemical plant installations, forcing engineering reviews of relief valve configurations and pressure vessel certifications. Equipment manufacturers must now document hazard analysis protocols to secure placement in regulated facilities. Chemical end-users are responding by specifying indirect generation architectures that isolate heat sources from working fluids, accepting thermal efficiency trade-offs for regulatory coverage.
Service unbundling is separating hardware procurement from calibration maintenance contracts among integrated oil majors. Turnaround speed guarantees now determine vendor selection more than capital equipment pricing, compressing switching costs for testing laboratories. This preference shift is most visible in the Gulf Coast refinery corridor, where extended downtime penalties exceed annual service expenditure multiples.
Existent Gum Steam Generator Market Segmentation
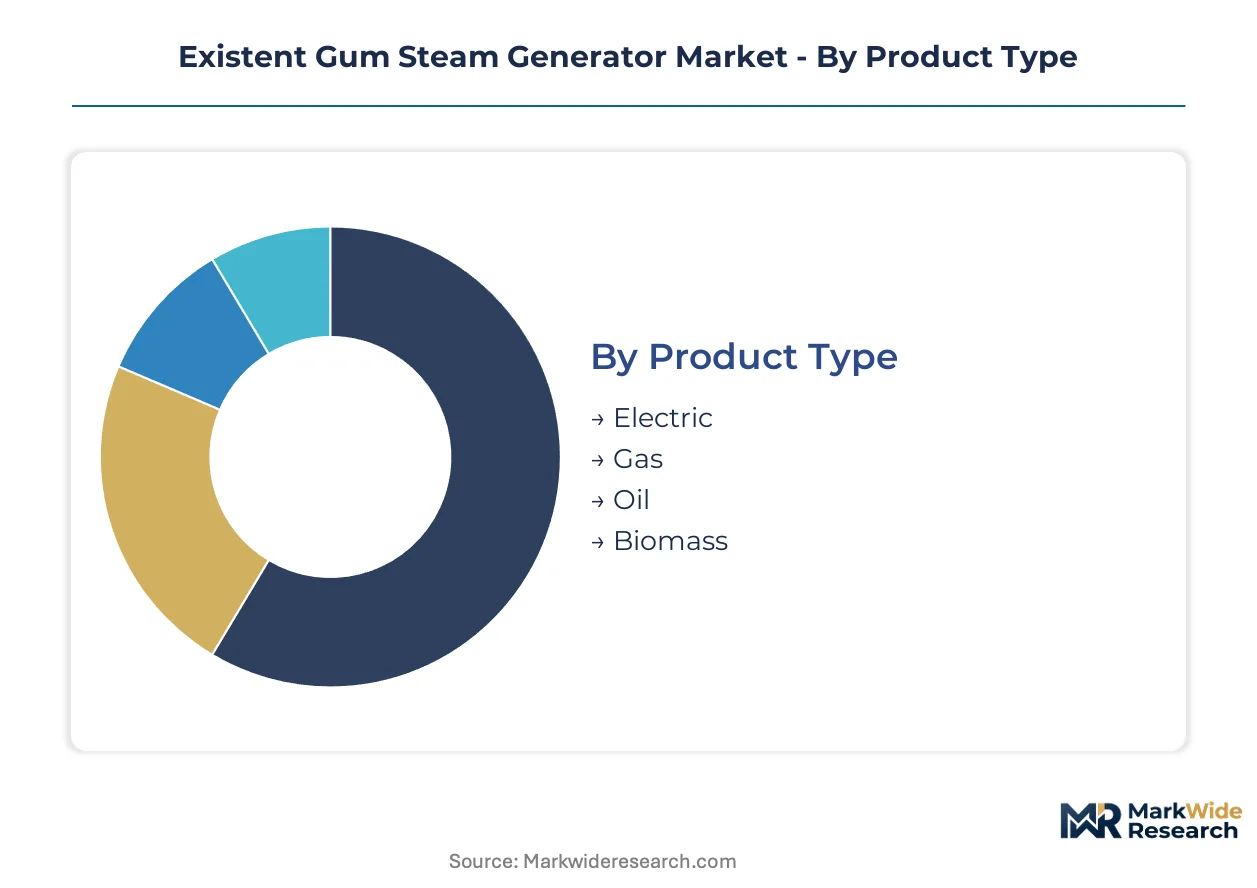
Steam generator procurement splits sharply between precision laboratory applications and industrial process integration, with each use case demanding incompatible performance specifications. Vendors must configure thermal architectures, pressure ratings, and mobility features around these divergent operational contexts rather than pursuing universal platform designs.
Product Type:
Customization intensity varies from standardized electric units to engineered biomass systems requiring fuel-handling integration.
- Electric:Resistance heating elements deliver sub-degree temperature stability and eliminate combustion byproducts, making these units dominant in ASTM D381-compliant petroleum testing laboratories where ventilation infrastructure is limited. Gulf Coast refineries in Texas and Louisiana concentrate procurement here due to EPA Tier 3 sulfur-content testing mandates.
- Gas:Natural gas-fired burners achieve faster ramp rates for high-throughput industrial applications, though they require exhaust management and flame safeguard systems that complicate laboratory deployments. Chemical plants in regulated jurisdictions favor these where OSHA Process Safety Management rules permit direct-fired architectures.
- Oil:Diesel or fuel-oil combustion suits remote field operations lacking pipeline gas infrastructure, common among mobile testing contractors serving distributed refinery sites.
- Biomass:Solid-fuel gasification systems demand custom fuel-feed mechanisms and ash-handling subsystems, limiting adoption to pulp and paper facilities with captive biomass supply chains.
Leading the category by volume: Electric. Growing fastest: Modular gas configurations for field redeployment.
Technology:
Heat transfer architecture determines regulatory compliance scope and thermal efficiency trade-offs across end-use verticals.
- Direct:Flame or resistance element contacts working fluid directly, maximizing thermal efficiency but requiring contamination-tolerant applications. Petroleum testing workflows accept this architecture where ASTM D381 protocols specify saturated steam injection into hydrocarbon samples without purity constraints.
- Indirect:Heat exchanger isolation separates heat source from working fluid, mandatory in chemical and pulp paper applications where process contamination risks override efficiency priorities. FDA Good Laboratory Practice standards in fuel-quality testing also favor this architecture for data integrity assurance.
- Modular:Skid-mounted subsystems enable rapid site relocation without permanent installation, addressing mobile testing contractor demand for field-based fuel quality verification.
- Hybrid:Dual-mode systems switch between direct and indirect operation based on application requirements, commanding premium pricing for multi-use laboratory facilities.
Indirect systems anchor chemical plant procurement. Modular architectures are expanding most quickly among testing service providers.
End User:
Process contamination tolerance and steam purity requirements segment demand across manufacturing verticals.
- Food Processing:FDA-mandated clean steam specifications require stainless steel construction and separation of heat sources from edible product contact surfaces, favoring indirect generation architectures with documented material certifications.
- Textile:Finishing and dyeing operations consume saturated steam at moderate pressures, with direct-fired gas units dominating where exhaust ventilation is available and thermal efficiency drives operating economics.
- Chemical:OSHA Process Safety Management constraints on pressure vessel design and relief valve configurations favor indirect systems with documented hazard analysis protocols.
- Pulp & Paper:Process steam for digester and drying operations integrates with chemical recovery systems, with biomass co-firing common in integrated mills seeking energy cost reduction.
Chemical sector procurement leads by installed base. Food processing applications are climbing the fastest on regulatory compliance upgrades.
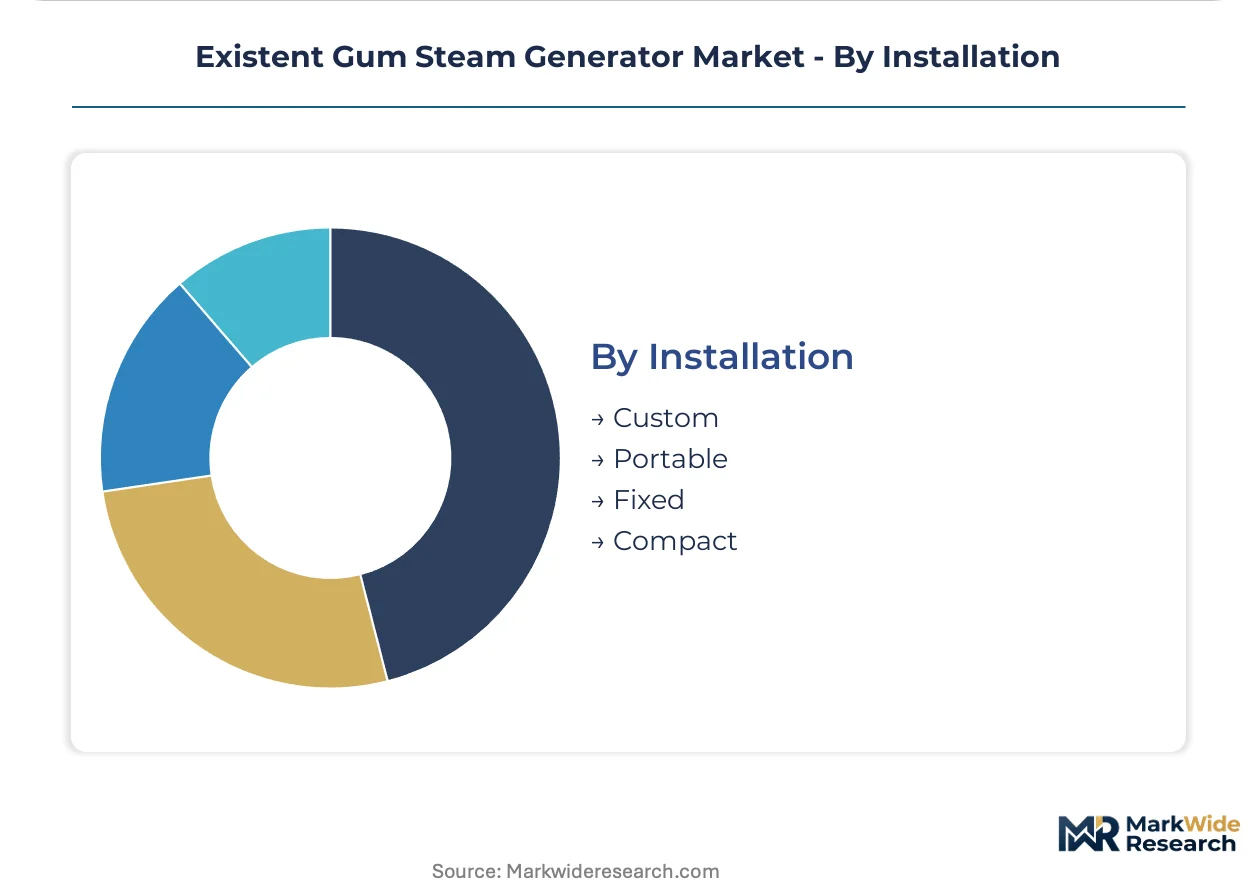
Installation:
Mobility requirements and site permanence split procurement between engineered infrastructure and rapid-deployment assets.
- Custom:Engineered-to-order systems integrate with existing sample preparation workflows and data management infrastructure, common in legacy refinery laboratory refurbishment projects where mechanical compatibility constraints dominate specification.
- Portable:Trailer or skid-mounted units with quick-connect utilities enable same-day relocation between field sites, serving mobile testing contractors in the Houston-Lake Charles corridor where turnaround speed guarantees determine vendor selection.
- Fixed:Permanent foundation-mounted installations with dedicated utility connections anchor central laboratory facilities with predictable testing volumes.
- Compact:Reduced-footprint designs fit constrained laboratory spaces or satellite testing locations, sacrificing throughput for spatial efficiency.
Fixed installations retain the largest installed base. Portable configurations are gaining share fastest on service unbundling trends among integrated oil majors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones along the Arabian Gulf concentrate petrochemical testing infrastructure investment, with sulfur-content compliance mandates reshaping procurement patterns across downstream processing corridors.
United States
EPA Tier 3 gasoline sulfur standards drive laboratory instrumentation upgrades across Gulf Coast refineries. OSHA Process Safety Management rules constrain steam system design pressures in chemical plant installations. The Houston-Lake Charles corridor generates sustained procurement volume for ASTM D381-compliant calibration-grade steam generators.
Germany
Precision instrumentation heritage clusters around established calibration workflow vendors serving European petroleum testing laboratories. REACH chemical safety regulations influence material certification requirements for steam chamber fabrication. Industrial testing facilities in North Rhine-Westphalia anchor demand for method-aligned equipment procurement.
China
GB standards create divergent product qualification pathways for domestic and export-oriented equipment manufacturers. The national petroleum regulator mandates fuel quality testing protocols that align with evolving automotive sulfur-content thresholds. Yangtze River Delta refineries concentrate procurement of modular steam generation systems for oxidation stability measurement.
India
BIS certification requirements establish first-mover advantages for exporters establishing local calibration partnerships. The Bureau of Indian Standards governs fuel testing equipment specifications for downstream petroleum facilities. Maharashtra and Gujarat host the densest clusters of refinery laboratory refurbishment projects requiring ASTM-method-aligned steam generators.
Saudi Arabia
Dual carbon goals and downstream diversification programs accelerate laboratory infrastructure investment across integrated oil majors. The national standards body aligns fuel quality testing protocols with international sulfur-content specifications. Eastern Province petrochemical complexes concentrate demand for portable steam generation systems enabling field-based fuel verification services.
Existent Gum Steam Generator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct procurement tiers. The vendor base separates into method-certified precision instrumentation houses, regional fabrication specialists, and integrated energy technology conglomerates. Three strategic archetypes dominate: ASTM-aligned calibration workflow vendors, modular equipment fabricators serving mobile contractors, and process safety-focused chemical plant suppliers. Competitive moves concentrate on strategic partnerships with reference laboratories and geographic expansion through local certification pathways.
Among European precision instrumentation specialists, Anton Paar GmbH exemplifies the method-certified calibration workflow archetype. Koehler Instrument Company Inc. and PAC LP represent North American vendors anchoring refinery relationships through ASTM-method-aligned service contracts. Chinese fabricators including Huazheng Electric Manufacturing (Baoding) Co., Ltd occupy positions within the regional equipment supply tier serving domestic petroleum testing infrastructure expansion.
| Leading Market Players |
|---|
| Labtron Equipment Ltd |
| Koehler Instrument Company Inc. |
| Anton Paar GmbH |
| Huazheng Electric Manufacturing (Baoding) Co., Ltd |
| Tanaka Scientific Limited |
| Shenzhen Kethink Electronic Co., Ltd. |
| PAC LP |
| General Electric |
| Siemens |
| Others |
Supply & Pricing Matrix
Nickel price volatility on the London Metal Exchange cascades through stainless steel alloy procurement into three distinct equipment pricing tiers, with corrosion-resistant steam chamber fabrication costs determining vendor margins across ASTM-certified laboratory systems and non-certified industrial deployments.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate expedited ASTM D381-compliant systems from standard-order production slots, while spot inventory discounts attract price-sensitive mobile testing contractors in the Houston-Lake Charles corridor. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and after-sales bundling intensity. Cost compression in economy-tier electric units is intensifying because Chinese fabricators are absorbing nickel alloy fluctuations through volume scale. Refinery laboratories show least price sensitivity due to EPA Tier 3 compliance deadlines; mobile contractors exhibit highest sensitivity as service unbundling compresses capital equipment budgets.
Supply Chain Analysis
Freight cost differentials between containerized ocean lanes and air cargo for precision instrumentation widen procurement timing windows for European calibration workflow vendors serving North American refineries. Manufacturing concentrates in Germany, China, and the United States, with precision instrumentation heritage anchoring German output and cost-optimized fabrication feeding from Chinese Yangtze River Delta clusters. Supply chains rest on nickel alloy plate, ceramic heating elements, and pressure vessel certification services. Single-source vulnerability concentrates in ASTM reference material suppliers for method certification. Distribution runs through authorized calibration service partners rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in precision heating element fabrication prop pricing power for vendors with captive component sourcing, while nickel alloy volatility compresses margins for spot-market-dependent fabricators.
For Market Incumbents: Extend ASTM method certification coverage into modular portable architectures before emerging Chinese fabricators secure BIS pathway advantages in India. Vertical integration into ceramic heating element production insulates margin pressure from supply shocks. Channel control through exclusive calibration service partnerships locks refinery relationships against PAC LP turnaround-speed competition. For New Entrants and Emerging Players: EPA Tier 3 in the United States opens a window for field-deployable modular systems targeting mobile testing contractors in Texas and Louisiana. White-space concentrates in portable configurations for rapid site redeployment and in BIS-certified economy-tier units for Maharashtra and Gujarat refinery refurbishment. Go-to-market through local calibration partnerships bypasses entrenched European vendor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision instrumentation specialists with embedded ASTM expertise in Germany and the United States. Long-term viability hinges on regulatory compliance service revenue streams outlasting capital equipment replacement cycles. Watch for sulfur-content threshold tightening announcements as inflection indicators for laboratory instrumentation refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Ceramic resistance element captive production insulates margin pressure from nickel volatility and supply disruption. |
| Modular Architecture Development | Skid-mounted subsystems capture mobile contractor demand in the Houston-Lake Charles refinery corridor. |
| BIS Certification Pathway Investment | Early compliance with Indian Bureau of Standards creates first-mover positioning in Maharashtra and Gujarat refurbishment. |
| Calibration Service Unbundling | Turnaround-speed guarantees secure integrated oil major contracts beyond capital equipment pricing competition. |
| Indirect Generation Technology Expansion | Heat exchanger architectures address OSHA Process Safety Management constraints in chemical plant installations. |
Research Methodology
Document review covered ASTM method specifications, EPA regulatory filings, and BIS equipment standards, complemented by interviews with laboratory instrumentation procurement managers, refinery maintenance directors, calibration service technicians, and ceramic heating element suppliers. Secondary validation drew from customs trade data, petroleum refinery capacity databases, and SEC filings of diversified energy technology conglomerates. Bottom-up equipment shipment analysis triangulated against top-down refinery laboratory capital expenditure estimates.
Unit volume and value projections across the analysis window segmented by product type, technology architecture, end-use vertical, and installation mobility. Modeled dimensions included electric versus gas-fired thermal systems, direct versus indirect heat transfer, and fixed versus portable deployment. CAGRs derived from regression against historical refinery laboratory instrumentation cycles and sulfur-content regulatory phase-in schedules. Forecast inputs incorporated nickel price trajectory assumptions and ASTM method revision timelines.
The model assumes a particular technology adoption path; alternative pathways for hybrid direct-indirect steam generation would alter the outlook if multi-use laboratory facilities accelerate procurement. Forecasts reflect assumptions about EPA Tier 3 compliance deadlines holding and nickel alloy supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Telecom Power Rental Market
Power
Flue Gas Desulfurization Unit Market
Power
Asia-Pacific Package Substation Market
Power
Nigeria Power Market
Power
Angola Power EPC Market
Power
Solar Plants Controllers Market
Power
Global Hydraulic Turbine Market
Power
Sudan Power Market
Power
Modified Sine Wave Home Inverters Market
Power
Statcom Market
Power
Italy Power EPC Market
Power
Malaysia Power EPC Market
Power
Asia-Pacific Microturbine Market
Power
Germany Solar Inverter Market
Power
Distributed Buoyancy Modules Market
Power
LNG Power Barge Market