
 Telecom Power Rental Market | 2026-2036
Telecom Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Power Rental Market Insights
Asian genset manufacturers is rebalancing regional inventory toward modular diesel units rated 51-200 kVA as tower densification accelerates. Aggreko leverages its containerized power fleet to dominate remote-site deployments across island geographies. Cummins sustains technology leadership through integrated alternator-engine packages optimized for telecom load profiles. Caterpillar competes on service density, embedding technician networks within key infrastructure corridors.
Telecom power rental denotes temporary or contracted supply of electrical generation and storage equipment to telecommunications infrastructure operators, typically involving diesel or gas reciprocating engines, battery energy storage systems, or photovoltaic inverters configured for 48V DC or 400V AC output with automatic transfer switching. The primary purpose is ensuring continuous network availability during grid outages, planned maintenance, or capacity augmentation without capital-intensive permanent installations. Diesel generators retain the largest equipment-type share due to established fuel logistics and immediate-start reliability, though battery systems represent the fastest-growing category as lithium-ion costs decline and tower operators prioritize emission reductions. Above-200 kVA units command premium rental rates but serve a narrower addressable market concentrated at data center interconnect points and broadcast transmission hubs.
FCC equipment authorization rules govern electromagnetic compatibility for power electronics deployed near radio access networks in the United States, while EPA Tier 4 emission standards elevate compliance costs for diesel rental fleets operating domestically. India's CEA technical standards for distributed generation equipment and the EU F-Gas Regulation restricting fluorinated coolant use in generator cooling systems collectively reshape equipment procurement specifications across major markets. Stakeholders must monitor evolving carbon-border adjustment mechanisms and local air-quality mandates that threaten to strand conventional diesel assets before technical end-of-life.
Market Dynamics
5G network densification is compressing site deployment timelines across archipelago geographies where grid extension proves economically unviable, forcing rental providers to reposition containerized power assets closer to demand clusters.
Growth Catalysts
- India's CEA technical standards:Mandatory diesel generator backup for critical telecom infrastructure under Department of Telecommunications rules creates recurring rental demand as tower operators seek compliant equipment without capital outlay.
- Island-based tower deployments:Indonesia's archipelago geography necessitates decentralized power solutions where submarine cable grid extension costs exceed $3 million per kilometer across Nusa Tenggara and Maluku provinces.
- Lithium-ion battery integration:Declining cell costs enable hybrid rental configurations that reduce fuel logistics burden while satisfying tightening emission norms in urban deployment zones.
Market Restraints
- Diesel fuel price volatility:Brent crude fluctuations directly compress rental margin structures since fuel pass-through clauses lag spot market movements by 30-60 days in contracted tower agreements.
- EPA Tier 4 compliance burden:Exhaust after-treatment systems add 15-20% capital cost to domestic rental fleets while requiring specialized technician training unavailable in secondary US markets.
- Grid reliability improvement:Vietnam and Thailand transmission infrastructure investments threaten to displace backup power rental at peripheral sites where commercial power interruptions previously justified contracted generation.
Strategic Opportunities
- Philippine island electrification gaps:The archipelago's 7,600+ islands contain over 2,000 tower sites beyond reliable grid reach where modular solar-diesel hybrid rentals command premium day-rates.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated coolants in generator thermal management systems create replacement demand for compliant rental equipment ahead of asset end-of-life.
- Edge data center interconnection:5G baseband unit aggregation at tower base camps requires above-200 kVA rental units with 48V DC output compatibility currently undersupplied in Southeast Asian markets.
Industry Challenges
- Certification timeline compression:FCC equipment authorization for electromagnetic compatibility near radio access networks requires 8-14 week approval cycles that mismatch urgent site deployment schedules.
- Technician density gaps:Specialized alternator-engine diagnostics expertise concentrates in Jakarta and Manila while remote Sumatra and Mindanao deployments face 72-hour mean time to repair.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Power Rental Market |
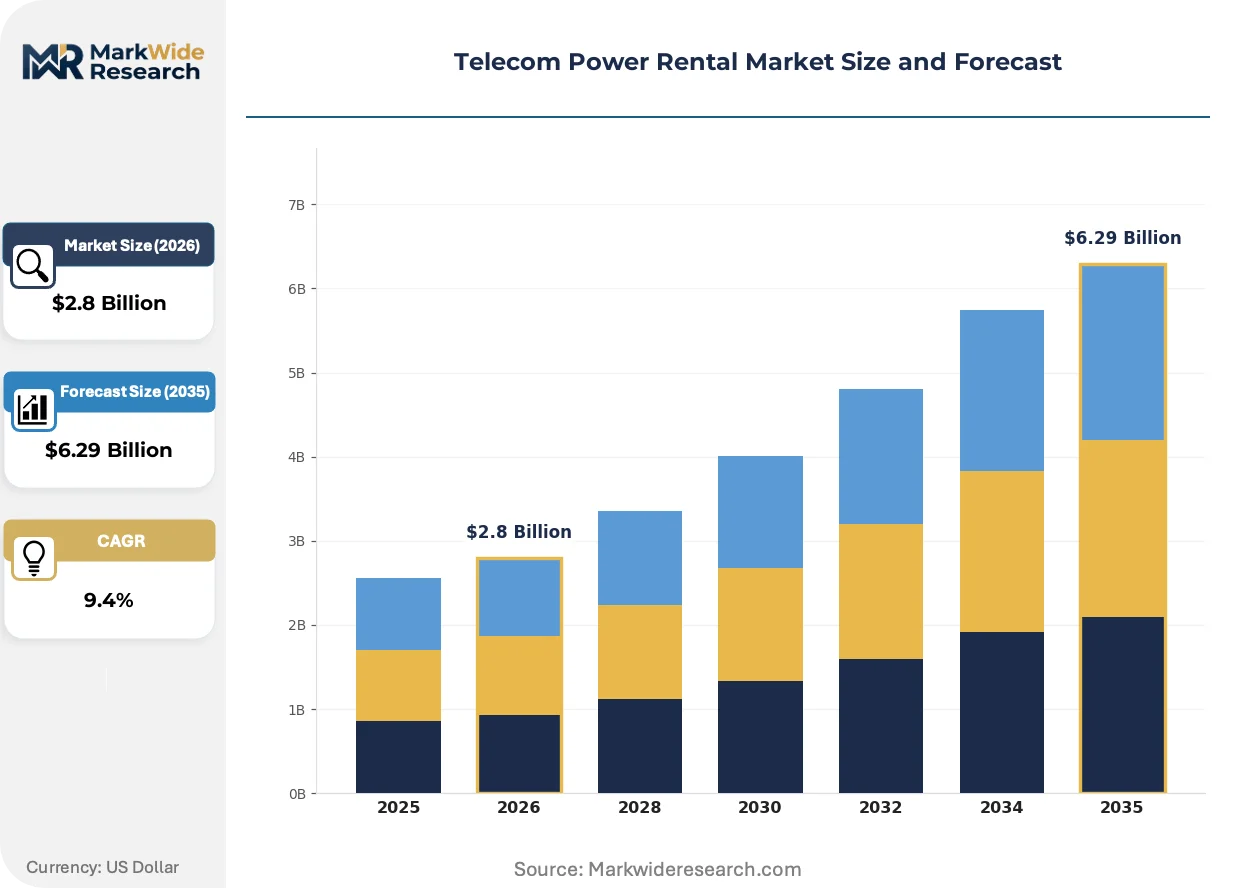
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: Up to 50 kVA, 51-100 kVA, 101-200 kVA, Above 200 kVA Equipment Type: Diesel Generators, Gas Generators, Battery Systems, Solar Inverters Application: Network Backup, Emergency Power, Maintenance Support, Event Connectivity End User: Mobile Network Operators, Internet Service Providers, Data Centers, Broadcast Stations |
| Companies Covered | Aggreko, United Rentals, Cummins, Caterpillar, Generac Power Systems, Atlas Copco, APR Energy, Kohler, HIMOINSA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Power Rental Market Trends and Innovations
Equipment architecture is pivoting toward containerized modular configurations that separate power generation from distribution electronics, enabling rapid redeployment across dispersed tower portfolios without civil works.
Containerized battery energy storage systems are consolidating telecom power rental product architecture by integrating lithium-ion racks, thermal management, and 48V DC rectification within standard shipping dimensions. Aggreko and regional competitors deploy these units across Indonesian island chains where barge-accessible equipment eliminates on-site assembly. This consolidation compresses deployment timelines from weeks to days while reducing site preparation costs by eliminating concrete pad requirements.
India's Bureau of Indian Standards emission norms for stationary diesel engines are tightening particulate matter limits to 0.3 g/kWh for gensets above 75 kVA, forcing rental fleet refresh cycles. The CEA mandates automatic transfer switching compliance that disqualifies aging mechanical governor units from new tower contracts. Tier-1 rental providers respond by accelerating equipment turnover toward electronically controlled common-rail injection systems that satisfy both emission and grid-code requirements.
Site-as-a-service procurement models are fragmenting traditional equipment rental into unbundled power availability contracts where tower operators pay per kWh delivered rather than daily hire rates. This restructuring shifts operational risk to rental providers who must now guarantee 99.99% uptime across fuel logistics, maintenance, and equipment replacement. The model concentrates in Indian urban markets where Bharti Infratel and American Tower seek to convert fixed costs to variable expenditure structures aligned with tenancy revenue volatility.
Telecom Power Rental Market Segmentation
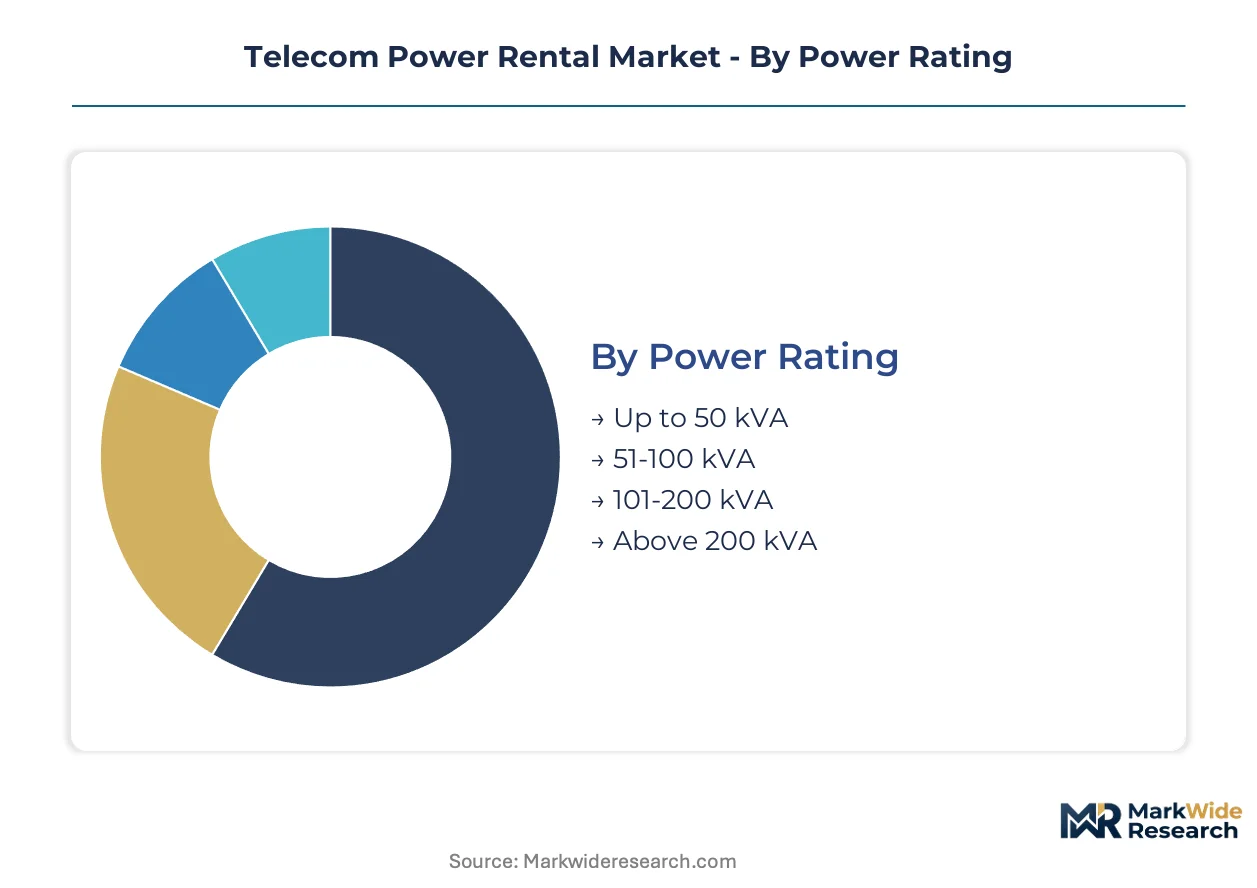
Telecom power rental segmentation reflects divergent technical requirements across deployment scenarios, from remote island towers requiring containerized diesel units to urban 5G densification favoring battery hybrid configurations. Equipment specification, power rating, and end-use application collectively determine rental contract structures and service level agreements.
Power Rating:
Power rating segmentation tracks the shift from centralized macro-site backup toward distributed small-cell power provisioning as 5G architecture fragments energy demand.
- Up to 50 kVA:Compact single-phase or three-phase units serve distributed antenna systems and small-cell clusters where space constraints dominate site design. Demand concentrates in Indonesian urban corridors where sidewalk-mounted 5G nodes require whisper-quiet operation below residential noise ordinances.
- 51-100 kVA:Represents the workhorse rental class for macro tower backup across Southeast Asian archipelago deployments. Fleet utilization rates run highest in this bracket as mobile network operators standardize on modular containerized units that barge-transport between island sites without recalibration.
- 101-200 kVA:Mid-range three-phase systems address broadcast transmission hubs and aggregation points where multiple tenant loads stack. Indian tower companies specify this bracket for multi-operator shared infrastructure under CEA grid-code compliance mandates.
- Above 200 kVA:High-capacity synchronized paralleling sets serve data center interconnect points and submarine cable landing stations. Premium day-rates reflect specialized technician requirements and fuel logistics complexity at these critical nodes.
51-100 kVA leads on scale; Battery-integrated configurations in the 51-100 kVA bracket gain share fastest as hybrid architectures displace pure diesel.
Equipment Type:
Rental fleet composition tracks fuel logistics feasibility and emission compliance trajectories across operating geographies.
- Diesel Generators:Reciprocating engine sets with automatic transfer switching remain the default rental solution for immediate-start reliability. Fleet investment concentrates in India where Bureau of Indian Standards particulate limits force turnover toward common-rail electronic injection systems.
- Gas Generators:Natural gas and LPG units penetrate urban markets with established pipeline distribution. Singapore and Bangkok deployments favor this equipment type where local air-quality mandates restrict diesel runtime hours.
- Battery Systems:Lithium-ion rack configurations with integrated rectification and thermal management represent the steepest expansion trajectory. Containerized BESS units from Aggreko and regional competitors dominate Indonesian island chains where barge access eliminates on-site assembly.
- Solar Inverters:Photovoltaic power conversion equipment configured for 48V DC telecom bus architecture. Philippine archipelago deployments combine these with diesel hybrids where solar irradiance exceeds 5 kWh per square meter daily.
Diesel generators lead on scale; Battery systems lead on momentum.
Application:
Application segmentation mirrors the operational rhythm of telecom infrastructure — continuous standby, intermittent emergency, scheduled maintenance, and temporary surge.
- Network Backup:Automatic standby power for grid-failure scenarios defines core rental demand. Contracts specify 10-second start requirements under Indian Department of Telecommunications mandates for critical infrastructure.
- Emergency Power:Rapid-deployment rental for natural disaster recovery and grid collapse scenarios. Typhoon corridors across the Philippines and Vietnam drive seasonal demand spikes with 24-hour mobilization clauses.
- Maintenance Support:Temporary replacement generation during permanent equipment overhaul or emission retrofit. Indian CEA compliance deadlines accelerate this segment as aging mechanical-governor units face disqualification.
- Event Connectivity:Pop-up network capacity for festivals, elections, and disaster response coordination. Premium pricing reflects short-duration contracts with guaranteed fuel resupply logistics.
Network backup leads on scale; Maintenance support expands most quickly amid regulatory fleet refresh cycles.
End User:
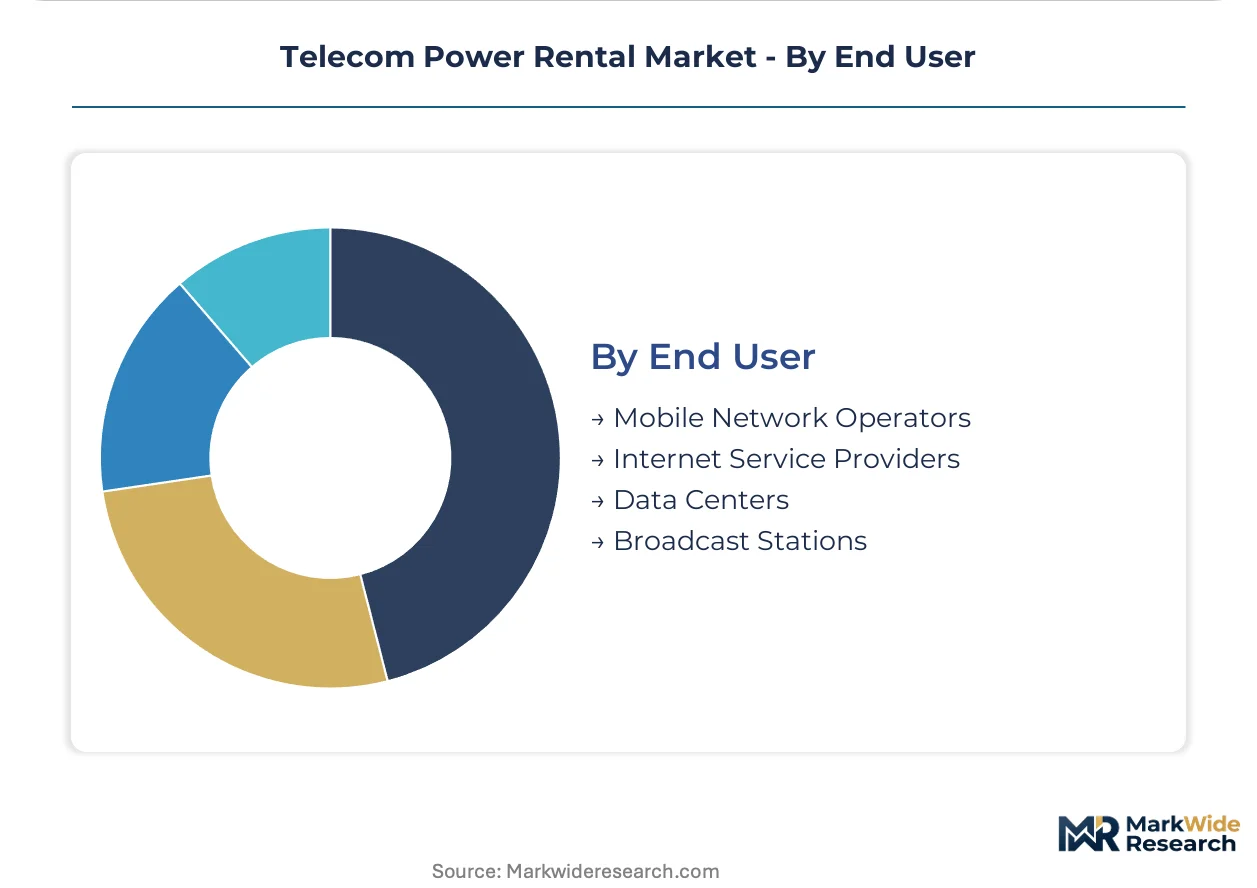
End-user segmentation captures divergent procurement sophistication — from capital-constrained tower operators to uptime-obsessed data center operators.
- Mobile Network Operators:Dominant rental demand source as 5G rollout compresses site deployment timelines. Indonesian operators XL Axiata and Telkomsel drive containerized power contracts across Nusa Tenggara and Maluku provinces.
- Internet Service Providers:Fixed-wireless and fiber-backhaul providers with intermittent backup requirements. Smaller fleet footprints favor spot rental over long-term contracted generation.
- Data Centers:Edge computing facilities at tower base camps require above-200 kVA units with 48V DC output compatibility. This segment commands strictest uptime guarantees with 99.99% availability penalties.
- Broadcast Stations:Television and radio transmission hubs with regulatory continuity obligations. Terrestrial broadcast backup in India and the Philippines maintains steady demand for synchronized generator sets.
Mobile network operators lead on scale; Data centers lead on contract value per kilowatt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing rental fleet investment toward jurisdictions where emission compliance costs remain manageable relative to revenue per kilowatt-hour. Equipment providers migrate modular diesel assets from EPA Tier 4 jurisdictions toward Asian markets with phased compliance timelines.
United States
FCC equipment authorization rules govern electromagnetic compatibility for power electronics deployed near radio access networks, while EPA Tier 4 emission standards elevate compliance costs for diesel rental fleets. California's CARB regulations impose additional nitrogen oxide limits that accelerate hybrid battery adoption in Los Angeles and San Diego corridor deployments.
India
The Department of Telecommunications mandates diesel generator backup for all critical telecom infrastructure under CEA technical standards, creating recurring rental demand. Bureau of Indian Standards particulate matter limits of 0.3 g/kWh for gensets above 75 kVA force fleet turnover toward common-rail electronic injection systems in Maharashtra and Gujarat tower clusters.
Indonesia
Island-based tower deployments across Nusa Tenggara and Maluku provinces necessitate decentralized power solutions where submarine cable grid extension costs exceed viable thresholds. PLN grid reliability gaps in the archipelago geography drive containerized power contracts, with Jakarta-based logistics hubs supporting barge-accessible equipment redeployment.
Philippines
The archipelago's 7,600+ islands contain over 2,000 tower sites beyond reliable grid reach, commanding premium day-rates for modular solar-diesel hybrid rentals. Typhoon corridors across Luzon and Visayas drive seasonal emergency power demand spikes with 24-hour mobilization clauses, while Manila-based technician networks face 72-hour mean time to repair for remote Mindanao deployments.
Germany
EU F-Gas Regulation restrictions on fluorinated coolants in generator thermal management systems create replacement demand for compliant rental equipment. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate gas generator deployments where pipeline distribution supports urban air-quality mandates restricting diesel runtime hours.
Telecom Power Rental Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-hybrid configurations and site-as-a-service procurement models. The market structure reflects moderate consolidation among containerized power specialists competing against diversified industrial equipment lessors. Three archetypes dominate: integrated engine-alternator manufacturers with captive rental divisions, independent power rental specialists with logistics-intensive fleet operations, and regional equipment lessors with localized technician density. Competitive moves center on fleet refresh cycles toward emission-compliant equipment and strategic partnerships with tower operators for long-term contracted generation.
Within the logistics-intensive specialist tier, Aggreko and APR Energy exemplify containerized power fleet operators with archipelago-deployment capabilities. Among integrated engine manufacturers with rental divisions, Cummins and Caterpillar anchor positions through alternator-engine packaging and service network density. Generac Power Systems occupies a position bridging residential backup expertise toward commercial telecom applications.
| Leading Market Players |
|---|
| Aggreko |
| United Rentals |
| Cummins |
| Caterpillar |
| Generac Power Systems |
| Atlas Copco |
| APR Energy |
| Kohler |
| HIMOINSA |
| Others |
Pricing and Supply Chain Analysis
Containerized battery-diesel hybrid architectures are compressing capital recovery timelines while redistributing manufacturing leverage toward integrated power-electronics assemblers in China and South Korea. This technological pivot simultaneously elevates upfront equipment costs and concentrates supplier bargaining power among lithium-ion cell producers, reshaping how rental providers structure long-term tower contracts.
Pricing Analysis
Distributor margins on diesel genset rentals absorb 12-18% of end-customer rates before fleet operators capture residual value. Three-tier pricing structure across premium emission-compliant, standard mechanical-governor, and economy refurbished equipment reflects Bureau of Indian Standards certification tiers and EPA Tier 4 compliance status. Cost compression in the standard tier is intensifying because Indonesian tower operators are consolidating procurement volumes under multi-year framework agreements. Mobile network operators exhibit highest price sensitivity due to tenancy revenue volatility, while data center interconnect customers accept premium rates for 99.99% uptime guarantees.
Supply Chain Analysis
Refurbishment and redeployment flows for containerized power units create circular value streams that extend asset life cycles across dispersed archipelago deployments. Manufacturing concentration rests on China for lithium-ion cells, India for alternator-engine assembly, and Germany for precision thermal management components. Rare earth magnet dependencies for high-efficiency alternators and copper winding supplies from Chilean concentrate introduce commodity price volatility exposure. Distribution runs through Jakarta and Manila logistics hubs that barge-transport modular units to island tower sites, with PLN grid reliability gaps sustaining demand pull.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecom power rental functions as a regulatory compounder where India's CEA grid-code mandates and tightening Bureau of Indian Standards emission limits generate recurring fleet refresh demand regardless of macro cycles.
For Market Incumbents: Anticipate displacement risk from pure-battery rental entrants by accelerating hybrid fleet turnover toward common-rail electronic injection systems that satisfy both Indian CEA mandates and Indonesian archipelago fuel logistics constraints. Defensive consolidation should target regional lessors with established barge-accessible logistics networks in Nusa Tenggara and Maluku provinces. For New Entrants and Emerging Players: Enter via Philippine island electrification gaps where over 2,000 tower sites beyond reliable grid reach command premium day-rates for solar-diesel hybrid configurations. The most penetrable white-space sits in 51-100 kVA battery-integrated rentals for Indonesian 5G densification, with site-as-a-service procurement models offering direct bypass of incumbent fleet scale advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among diversified industrial equipment lessors with underutilized technician networks in secondary Southeast Asian markets. Long-term viability hinges on regulatory compliance trajectory rather than commodity cycle timing, with acquisition targets favoring containerized power specialists over engine-manufacturing captives. Monitor India's CEA enforcement intensity and EU F-Gas Regulation phase-down timelines as inflection indicators for stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Emission Compliance Refresh | Accelerates turnover toward Bureau of Indian Standards 0.3 g/kWh particulate limits in Maharashtra tower clusters. |
| Containerized Hybrid System Deployment | Compresses Indonesian island site activation timelines from weeks to days via barge-accessible lithium-ion integration. |
| Site-as-a-Service Procurement Pivot | Converts Bharti Infratel and American Tower fixed costs to variable expenditure aligned with tenancy revenue volatility. |
| Technician Network Density Expansion | Closes 72-hour mean time to repair gaps in remote Sumatra and Mindanao deployments through localized alternator-engine diagnostics. |
| Submarine Cable Landing Station Positioning | Captures premium above-200 kVA rental rates at Philippine and Indonesian critical node infrastructure. |
Research Methodology
Bottom-up tower operator demand modeling reconciled against top-down rental fleet capacity tracking forms the analytical core of this study. Primary interviews with mobile network operator infrastructure heads, tower company procurement directors, diesel genset fleet managers, lithium-ion system integrators, and PLN grid planning officers were validated against secondary sources including TRAI infrastructure reports, CEA technical standards filings, PLN electrification statistics, and customs records for generator set imports into Indonesia and the Philippines.
Input-output matrices mapping power rating segments against equipment type penetration rates and application intensity coefficients generate volume and value estimates across the projection horizon. Segmentation dimensions encompass power rating tier, fuel source architecture, deployment geography grid reliability class, and end-user procurement sophistication. CAGRs derive from equipment replacement cycle analysis and regulatory mandate compliance deadlines, with diesel-to-battery substitution elasticity and island logistics cost inflation as industry-specific forecast inputs.
Inputs from tower operator procurement databases and rental fleet registries were available through the study window; gaps in real-time fuel logistics cost data introduce uncertainty bands around archipelago deployment margin estimates. Practitioners should monitor India's CEA enforcement actions, Indonesian PLN grid extension announcements, and lithium-ion cell price indices for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Italy Power Market
Power
Single-Phase Microinverter Market
Power
Digital Power Utility Market
Power
Sudan Power Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Solar Plants Controllers Market
Power
Norway Power Market
Power
Argentina Power Market
Power
Asia-Pacific Microturbine Market
Power
Mexico Power Market
Power
Equatorial Guinea Power Market
Power
North America CHP Market
Power
HVDC Capacitor Market
Power
Kuwait Power Market
Power
Europe Power Purchase Agreement Market
Power
United States Power Market