
 Global Nizatidine Market | 2026-2036
Global Nizatidine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nizatidine Market Foresight
REACH compliance for pharmaceutical impurities is pivoting the cost-of-entry calculus for nizatidine manufacturers seeking European market access. Eli Lilly and Company anchors its historical brand equity in prescription H2 antagonist therapy through sustained manufacturing partnerships. Glenmark Pharmaceuticals leverages its generic portfolio depth to compete across oral suspension and tablet formats in emerging markets. Dr. Reddy's Laboratories specializes in API-to-finished-dosage integration, controlling cost structures across nizatidine supply chains.
Nizatidine is a histamine H2 receptor antagonist with the chemical formula C12H21N5O2S2, functioning through competitive inhibition of gastric acid secretion at the parietal cell level. The compound exhibits rapid absorption with peak plasma concentrations occurring within one to three hours post-administration, making it clinically effective for managing gastric acid-related disorders. Tablet formulations dominate current revenue pools due to established reimbursement pathways and patient compliance familiarity, while oral suspension formats are gaining traction in pediatric and geriatric therapy areas where swallowing difficulties limit solid-dose adoption. The gastroesophageal reflux disease therapy segment leads prescription volumes, though peptic ulcer applications retain stronger margin profiles in hospital settings.
The FDA enforces bioequivalence standards for generic nizatidine through its Office of Generic Drugs, while the EMA's Committee for Medicinal Products for Human Use governs centralized marketing authorizations across EU member states. India's CDSCO mandates stability testing and dissolution profile documentation for domestic nizatidine manufacturers under Schedule M of the Drugs and Cosmetics Rules. Stakeholders must monitor evolving pharmacovigilance requirements for H2 antagonists, as regulatory scrutiny of long-term acid suppression therapy safety intensifies across multiple jurisdictions.
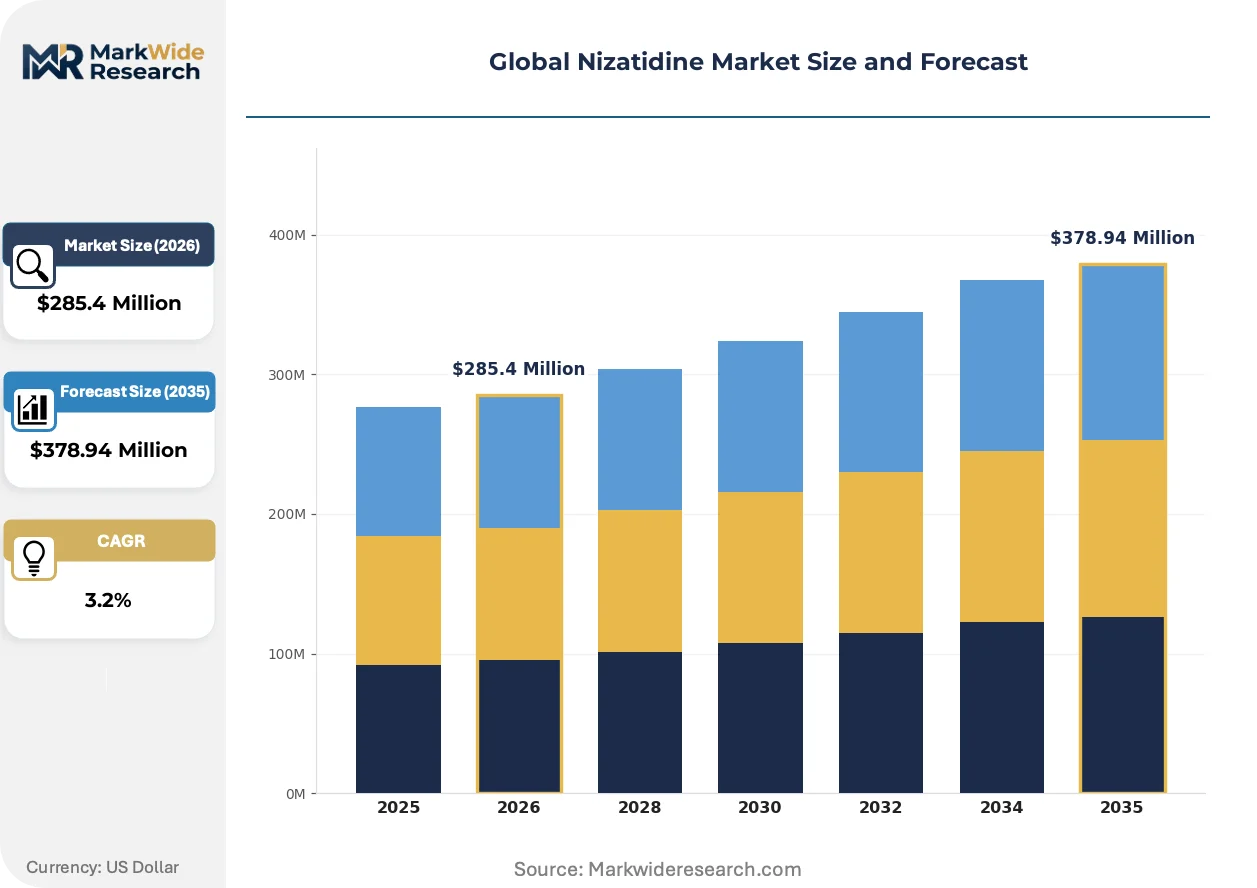
Market Dynamics
Hospital formulary standardization around H2 receptor antagonist protocols is compressing procurement cycles and elevating bioequivalence documentation burdens for nizatidine suppliers seeking institutional contracts.
Growth Catalysts
- India's CDSCO Schedule M compliance:Domestic manufacturers leveraging stability testing documentation to secure government health program tenders are expanding nizatidine access across public hospital networks.
- Geriatric swallowing difficulty prevalence:Oral suspension formulations are capturing therapy areas where solid-dose adherence fails, particularly in long-term care facilities managing polypharmacy regimens.
- EMA centralized marketing authorization pathways:Streamlined EU-wide approvals for generic H2 antagonists are reducing time-to-market for nizatidine producers meeting REACH pharmaceutical impurity standards.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Asian manufacturing zones create vulnerability to regional production disruptions.
- Proton pump inhibitor substitution:Omeprazole and esomeprazole formulations continue displacing nizatidine in first-line GERD therapy protocols at major health systems.
- FDA bioequivalence study costs:Elevated clinical trial documentation requirements for generic H2 antagonists are raising fixed cost barriers for mid-scale manufacturers.
Strategic Opportunities
- Pediatric GERD therapy gaps:Weight-based dosing protocols for nizatidine oral suspension remain underdeveloped in Southeast Asian markets, creating first-mover potential for formulation specialists.
- Hospital acid suppression protocol bundling:Integrated supply contracts combining nizatidine with endoscopy preparation kits are penetrating Japanese tertiary care centers.
- Indian PLI scheme pharmaceutical manufacturing:Production-linked incentive structures for bulk drug production are attracting capital toward domestic nizatidine API capacity expansion.
Industry Challenges
- Pharmacovigilance reporting systems:Long-term acid suppression safety monitoring requirements across FDA and EMA jurisdictions are demanding specialized adverse event data infrastructure investments.
- Dissolution profile standardization:Variability in nizatidine tablet dissolution testing methodologies between CDSCO and FDA guidelines complicates multi-territory filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nizatidine Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $378.94 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Oral Suspension, Injectable Therapy Area: Gastroesophageal Reflux Disease, Peptic Ulcer, Zollinger-Ellison Syndrome, Non-Ulcer Dyspepsia, Erosive Esophagitis End User: Hospitals, Ambulatory Surgical Centers, Retail Pharmacies, Clinical Laboratories, Specialty Clinics Distribution Channel: Hospital Pharmacies, Online Pharmacies, Wholesale Distributors, Drugstores |
| Companies Covered | Flynn Pharma, Eli Lilly and Company, Glenmark Pharmaceuticals, Weightech (Hunan) Pharmaceutical, Strides Pharma Science, Dr. Reddy's Laboratories, MedChemExpress, Hengdian Group, Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nizatidine Market Shifts & Advancements
Continuous manufacturing technologies and real-time release testing protocols are reshaping nizatidine production economics while regulatory convergence on nitrosamine impurity limits is forcing reformulation investments across oral solid dose lines.
Hot-melt extrusion technology for nizatidine solid dispersions is absorbing capital from traditional wet granulation investments as manufacturers seek bioavailability enhancement without solvent-based processing. European contract development organizations are adopting these platforms at accelerated rates to meet EMA quality-by-design expectations. The shift is absorbing smaller batch manufacturers unable to justify equipment retrofit costs, consolidating production among scaled facilities.
REACH pharmaceutical impurity thresholds for nitrosamine content are tightening across European supply chains, forcing nizatidine API producers to implement secondary purification steps or switch starting material sources. The ECHA regulatory pressure is elevating compliance expenditures for manufacturers serving EU member states. Generic suppliers with captive API production are responding faster than those dependent on merchant API markets.
Hospital procurement consolidation through group purchasing organizations is compressing vendor panels and extending contract durations for nizatidine suppliers. Traditional distributor relationships in North American institutional channels are giving way to direct manufacturer-health system agreements with price transparency requirements. The restructuring is most visible in United States integrated delivery networks standardizing acid suppression formularies across multi-hospital systems.
Global Nizatidine Market Segmentation
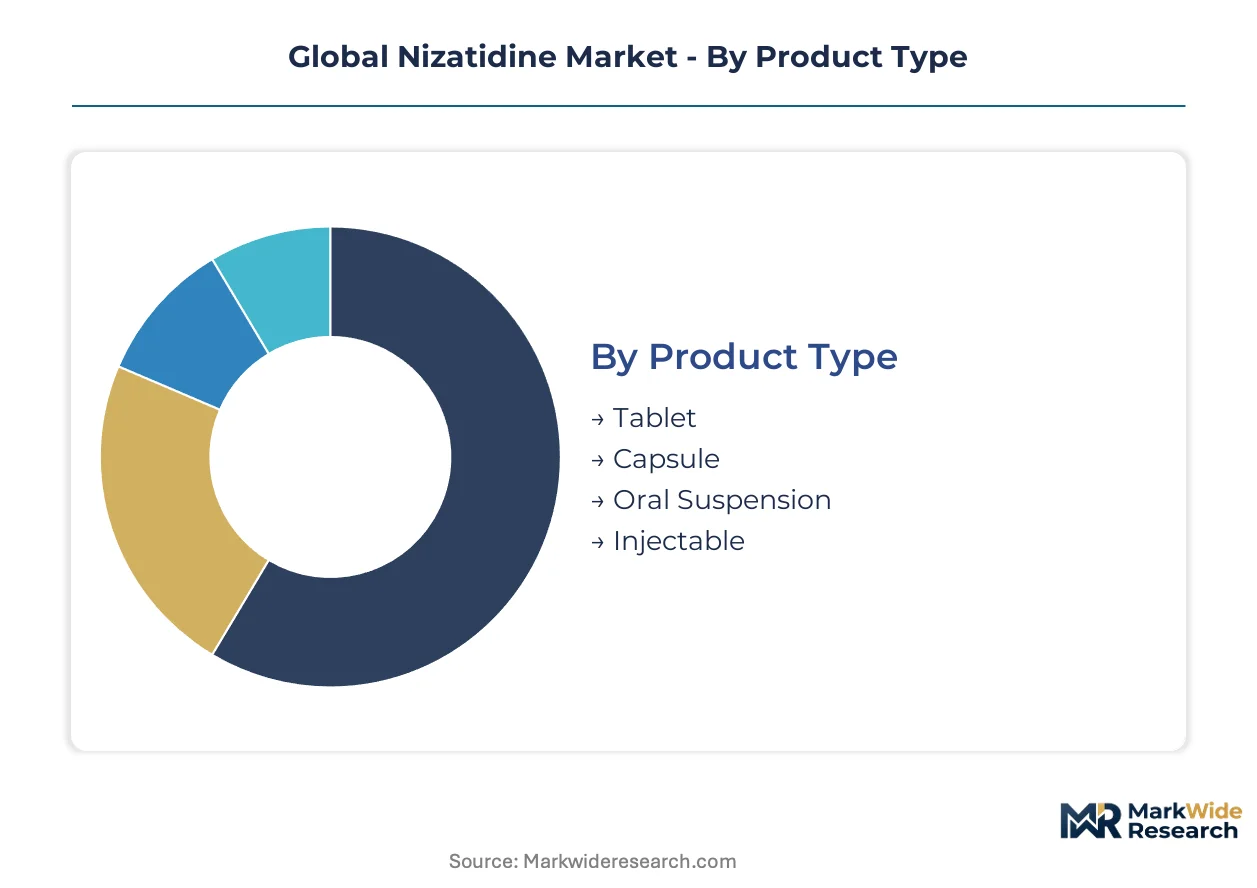
Nizatidine market segmentation reveals distinct competitive dynamics across formulation types, therapeutic applications, and procurement channels. Each dimension carries unique margin profiles and regulatory burdens that reshape supplier positioning across institutional and retail environments.
Product Type:
Volume concentration tilts toward solid oral formats, while premium pricing clusters in specialized delivery systems requiring bioequivalence documentation.
- Tablet:Compressed nizatidine formulations with standardized dissolution profiles dominate hospital procurement tenders. CDSCO Schedule M compliance requirements in India favor tablet manufacturers with documented stability testing, locking in government contract access.
- Oral Suspension:Liquid formulations with weight-based dosing flexibility command premium positioning in pediatric and geriatric therapy areas. Long-term care facilities across Japan and Germany are expanding oral suspension procurement where swallowing difficulties compromise solid-dose adherence.
- Capsule:Gelatin-encased nizatidine offers gastric acid protection with faster disintegration than tablets. Retail pharmacy channels in Brazil and Mexico stock capsule formats for outpatient GERD management.
- Injectable:Intravenous nizatidine for perioperative acid suppression occupies niche hospital use. ICU departments in tertiary care centers deploy injectable formulations when oral intake is contraindicated.
Today's leader: Tablet. Tomorrow's challenger: Oral Suspension.
Therapy Area:
Application-driven demand splits between high-volume chronic conditions and acute intervention protocols with stronger reimbursement rates.
- Gastroesophageal Reflux Disease:Chronic acid reflux management represents the largest prescription volume pool. Hospital formularies in the United States standardize nizatidine for step-down therapy following proton pump inhibitor courses.
- Peptic Ulcer:Gastric and duodenal ulcer treatment retains superior margin profiles in institutional settings. Japanese tertiary care centers bundle nizatidine with endoscopy preparation kits for bleeding ulcer protocols.
- Zollinger-Ellison Syndrome:Rare gastrinoma-related hyperacidosis requires high-dose H2 antagonist therapy. Specialty clinics in Germany and Switzerland manage these patients through compounded nizatidine formulations.
- Non-Ulcer Dyspepsia:Functional dyspepsia without structural pathology drives outpatient prescriptions. Retail pharmacies across India's tier-2 cities dispense generic nizatidine for symptom relief.
- Erosive Esophagitis:Mucosal damage from acid exposure demands sustained acid suppression. EMA centralized marketing authorizations facilitate EU-wide nizatidine distribution for erosive esophagitis regimens.
Gastroesophageal Reflux Disease commands current volumes. Peptic Ulcer offers the steepest expansion trajectory in hospital procurement consolidation.
End User:
Customer-type concentration reflects reimbursement pathway complexity, with institutional buyers demanding bioequivalence documentation and retail channels prioritizing price accessibility.
- Hospitals:Integrated delivery networks standardize acid suppression formularies across multi-hospital systems. Group purchasing organizations in North America compress vendor panels for nizatidine suppliers.
- Retail Pharmacies:Community pharmacy chains stock generic nizatidine for chronic GERD maintenance. India's domestic producers supply branded and generic tablets to retail networks serving government health program beneficiaries.
- Ambulatory Surgical Centers:Outpatient procedural facilities require perioperative acid suppression for aspiration prophylaxis. ASC procurement cycles favor single-source nizatidine contracts with predictable supply continuity.
- Specialty Clinics:Gastroenterology-focused practices manage complex acid-related disorders. REACH compliance documentation influences European specialty clinic supplier selection for nizatidine oral suspensions.
- Clinical Laboratories:Research and diagnostic facilities utilize nizatidine reference standards. API quality from Dr. Reddy's Laboratories supports laboratory-grade nizatidine requirements.
Hospitals anchor procurement volume. Specialty Clinics represent the fastest-climbing segment as precision dosing protocols expand.
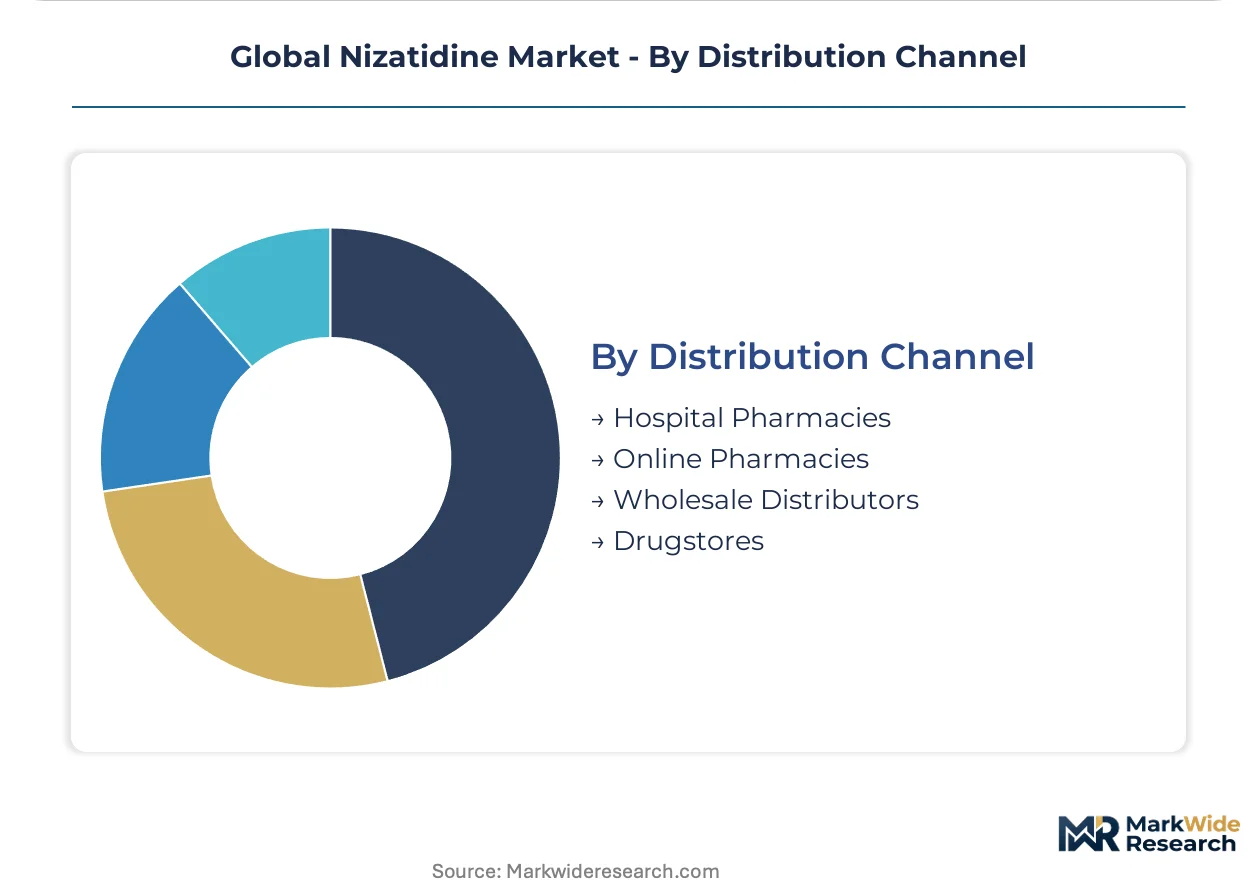
Distribution Channel:
Channel structure determines price transparency and contract duration, with direct manufacturer agreements displacing traditional distributor relationships in institutional segments.
- Hospital Pharmacies:Captive dispensing operations within health systems control nizatidine formulary placement. Direct manufacturer agreements with price transparency requirements are restructuring United States institutional channels.
- Wholesale Distributors:Regional pharmaceutical wholesalers maintain inventory buffers for retail pharmacy networks. Indian wholesale channels bridge domestic API producers with finished dosage form distribution.
- Online Pharmacies:E-commerce platforms enable patient-direct nizatidine procurement with prescription verification. Brazil's ANVISA regulates online pharmacy nizatidine sales through licensed dispenser requirements.
- Drugstores:Traditional brick-and-mortar retail maintains OTC-accessible nizatidine positioning where regulations permit. Southeast Asian drugstore chains stock oral suspension formats for pediatric GERD therapy gaps.
Hospital Pharmacies dominate contract value. Online Pharmacies are gaining share fastest as prescription digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturing talent clusters in India, the United States, Germany, Japan, and China anchor nizatidine production capacity and regulatory expertise across distinct compliance environments.
United States
Hospital formulary standardization drives institutional procurement of H2 antagonists through integrated delivery networks. FDA bioequivalence documentation requirements for generic nizatidine elevate compliance costs for manufacturers seeking group purchasing organization contracts. New Jersey and Pennsylvania host concentrated pharmaceutical manufacturing infrastructure serving domestic acid suppression therapy demand.
Germany
Geriatric swallowing difficulty prevalence expands oral suspension procurement across long-term care facilities and specialty clinics. EMA centralized marketing authorization pathways streamline EU-wide nizatidine distribution for producers meeting REACH pharmaceutical impurity thresholds. The Rhine-Main pharmaceutical cluster maintains active formulation development for histamine receptor antagonist therapies.
India
Domestic API-to-finished-dosage integration controls cost structures for government health program tenders supplying public hospital networks. CDSCO Schedule M mandates stability testing and dissolution profile documentation under the Drugs and Cosmetics Rules. Hyderabad and Mumbai manufacturing corridors concentrate nizatidine bulk drug production capacity serving both domestic and export markets.
Japan
Hospital acid suppression protocol bundling penetrates tertiary care centers combining nizatidine with endoscopy preparation kits. PMDA pharmacovigilance requirements demand specialized adverse event data infrastructure for long-term acid suppression therapy monitoring. The Kansai region maintains formulation expertise in oral suspension development for pediatric and geriatric dosing flexibility.
China
Contract development organizations adopt continuous manufacturing technologies and real-time release testing protocols for nizatidine solid dose production. NMPA bioequivalence standards for generic H2 antagonists align with international regulatory convergence on nitrosamine impurity limits. Zhejiang and Jiangsu provinces concentrate API synthesis capacity serving global pharmaceutical supply chains.
Global Nizatidine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across nizatidine manufacturing tiers, creating a fragmented vendor base segmented by vertical scope and geographic reach. The competitive structure stratifies between integrated API-to-formulation producers and finished-dosage specialists dependent on merchant active pharmaceutical ingredient markets. Three archetypes dominate: diversified pharmaceutical conglomerates with captive API production, mid-scale generic specialists leveraging formulation flexibility, and regional contract manufacturers serving localized tender markets. Capacity expansion and strategic partnerships constitute the primary competitive vectors as manufacturers respond to tightening regulatory documentation requirements.
Among diversified pharmaceutical conglomerates, Eli Lilly and Company anchors historical brand equity in prescription H2 antagonist therapy through sustained manufacturing partnerships. Glenmark Pharmaceuticals occupies a position exemplifying generic portfolio depth across oral suspension and tablet formats in emerging markets. Dr. Reddy's Laboratories represents API-to-finished-dosage integration archetypes controlling cost structures across nizatidine supply chains.
| Leading Market Players |
|---|
| Flynn Pharma |
| Eli Lilly and Company |
| Glenmark Pharmaceuticals |
| Weightech (Hunan) Pharmaceutical |
| Strides Pharma Science |
| Dr. Reddy's Laboratories |
| MedChemExpress |
| Hengdian Group |
| Mylan N.V. |
| Others |
Supply & Pricing Matrix
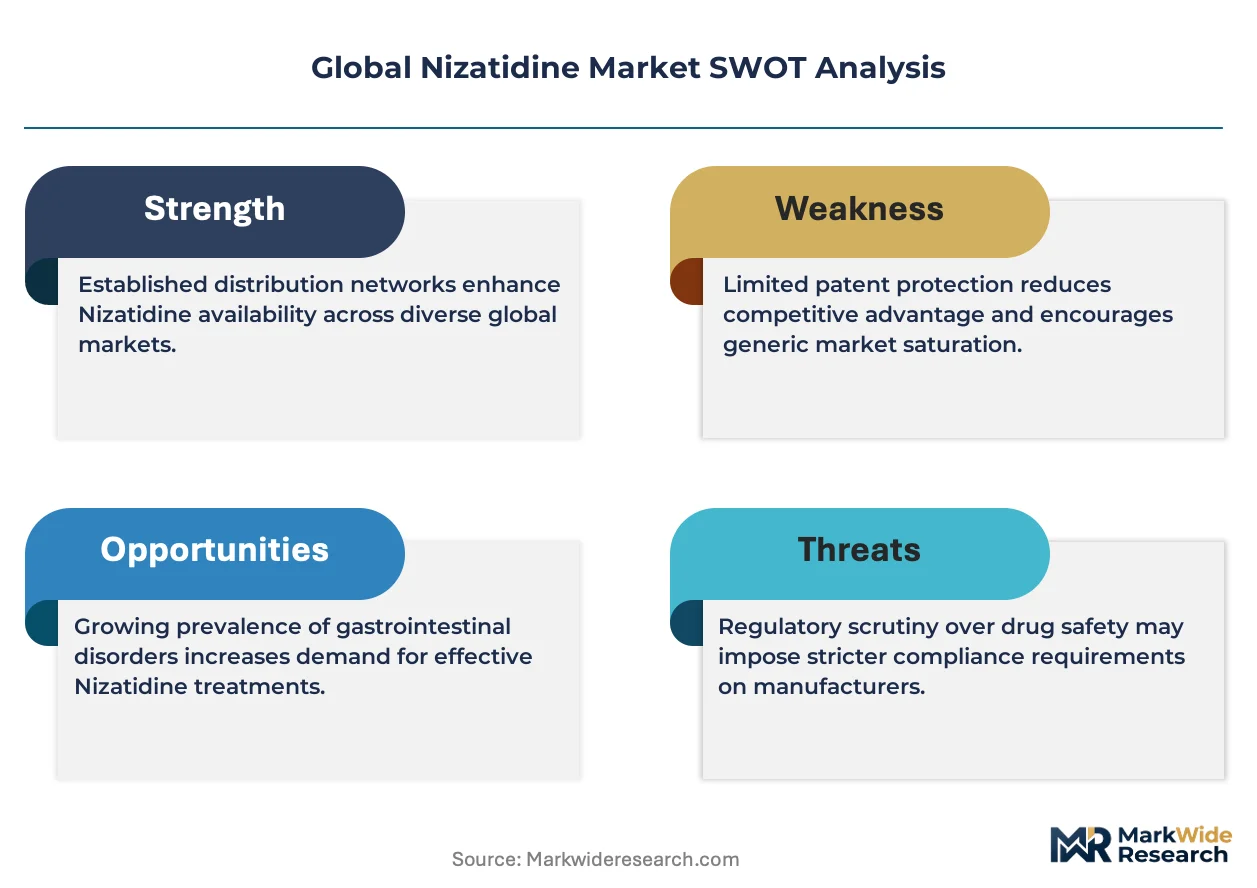
Group purchasing organizations in North American hospital networks dictate contract structures that compress nizatidine supplier margins through multi-year bundled agreements with price transparency mandates. This buyer concentration forces manufacturers toward volume-scaled production economics while penalizing smaller batch operators unable to absorb bioequivalence documentation costs.
Pricing Analysis
Bundled hospital procurement contracts dominate institutional nizatidine purchasing, while unbundled retail pharmacy transactions sustain spot-market flexibility for generic tablet formats. Three-tier pricing structure across premium oral suspensions, standard tablets, and economy generic capsules reflects formulation complexity and certification grade differentiation. Cost compression in economy tablet tiers intensifies because Indian domestic producers flood government tender markets with Schedule M-compliant supply. Retail pharmacy chains exhibit highest price sensitivity, whereas Japanese tertiary care centers accepting bundled endoscopy kit contracts demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
API synthesis for nizatidine rests on concentrated manufacturing corridors in India, China, and select United States facilities with captive production capabilities. Key inputs include histamine derivative precursors, sulfur-containing coupling agents, and specialized purification resins. Single-source vulnerability pervades merchant API markets where formulation specialists lack backward integration into bulk drug manufacturing. Distribution runs through regional pharmaceutical wholesalers serving retail networks, while direct manufacturer agreements increasingly penetrate hospital pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA nitrosamine impurity thresholds and FDA bioequivalence mandates continuously elevate compliance investment requirements, structurally advantaging scaled manufacturers with captive API production.
For Market Incumbents: Deploy hot-melt extrusion technology adoption to solidify bioavailability advantages as EMA quality-by-design expectations tighten. Consolidate formulation capacity in Hyderabad and Mumbai corridors to exploit Indian PLI scheme incentives for bulk drug production. Proton pump inhibitor substitution in first-line GERD protocols represents the primary demand threat requiring defensive positioning through pediatric and geriatric oral suspension specialization. For New Entrants and Emerging Players: Enter via Southeast Asian pediatric GERD therapy gaps where weight-based dosing protocols remain underdeveloped and first-mover formulation specialists capture premium positioning. Target long-term care facility networks in Germany and Japan where swallowing difficulty prevalence sustains oral suspension demand outside hospital formulary standardization. Pursue contract development organization partnerships with European facilities adopting continuous manufacturing platforms to bypass capital-intensive equipment retrofit barriers. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with captive API production represent the most active acquirer category in this space, seeking to extend vertical control over nizatidine supply chains. Acquisition targets should display API-to-finished-dosage integration or specialized pediatric formulation capabilities with EMA REACH compliance documentation. Watch FDA pharmacovigilance guidance evolution for long-term acid suppression therapy as the critical inflection signal determining H2 antagonist class viability against proton pump inhibitor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Extrusion Technology Adoption | Enables bioavailability enhancement without solvent-based processing for EMA quality-by-design compliance. |
| Indian PLI Scheme Capacity Expansion | Attracts capital toward domestic API production serving government health program tender requirements. |
| Pediatric Oral Suspension Development | Captures therapy gaps in Southeast Asian markets with weight-based dosing protocol specialization. |
| REACH Nitrosamine Compliance Investment | Forces secondary purification steps or starting material switches for EU market access maintenance. |
| Hospital Bundled Contract Penetration | Combines nizatidine with endoscopy preparation kits in Japanese tertiary care standardization. |
Research Methodology
Coverage spans North America, Europe, India, Japan, and China, with primary inputs from each region combined with secondary validation. The research incorporates interviews with regulatory affairs leads at generic manufacturers, hospital procurement managers overseeing acid suppression formulary placement, CDSCO compliance officers, and GPO contracts administrators. Secondary sources include FDA Office of Generic Drugs filings, EMA centralized marketing authorization databases, CDSCO Schedule M stability testing records, and Indian government health program tender documentation. Bottom-up volume estimates triangulate against top-down market sizing across formulation types.
Rate-of-change decomposition separates volume drivers from value drivers across the projection horizon. The analytical framework models segmentation dimensions including dosage form, therapy area, end-user type, and regional regulatory cluster. CAGR derivation incorporates patient population epidemiology, formulary placement probability, and generic substitution elasticity. Industry-specific forecast inputs encompass bioequivalence study completion rates and nitrosamine impurity testing adoption curves.
The model holds under stable regulatory enforcement intensity; deviation in FDA pharmacovigilance mandate expansion or EMA nitrosamine threshold tightening would shift volume trajectories. Forecasts reflect assumptions regarding hospital procurement consolidation pace and proton pump inhibitor displacement rates in GERD protocols. A small set of named triggers warrants ongoing watch: CDSCO Schedule M enforcement intensity, Japanese PMDA long-term acid suppression safety monitoring requirements, and Indian PLI scheme disbursement velocity for bulk drug production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Periodontal Therapeutics Market