
 Adapalene Market | 2026-2036
Adapalene Market Size, Share, and Industry Trends Forecast 2026-2036
Adapalene Market Outlook
The capital-intensity divergence between large pharmaceutical manufacturers and mid-size generic producers is unwinding competitive dynamics in adapalene supply. Galderma Laboratories leverages its vertically integrated dermatology platform to sustain premium positioning across gel and cream formulations. Teva Pharmaceutical Industries anchors its presence through aggressive generic penetration, while Glenmark Pharmaceuticals specializes in emerging market distribution where price sensitivity dominates purchasing decisions.
Adapalene is a third-generation synthetic retinoid, chemically classified as a naphthoic acid derivative with a molecular weight of 412.53 g/mol, formulated for topical application in concentrations ranging from 0.1% to 0.3% to modulate keratinocyte differentiation and comedogenesis. Its primary commercial purpose centers on acne vulgaris treatment, where it reduces microcomedone formation through selective retinoic acid receptor-gamma binding. Gel formulations dominate volume due to superior patient compliance in humid climates and younger demographics, while prescription-grade adapalene retains margin concentration despite OTC expansion. Online pharmacies represent the fastest-growing distribution vector as telehealth platforms normalize remote dermatology consultations.
FDA OTC monograph reforms and EMA pharmacovigilance requirements for topical retinoids jointly shape product labeling, pregnancy warning standards, and market entry timelines across developed economies. The EPA monitors manufacturing discharge protocols for retinoid synthesis facilities, adding compliance layers to active pharmaceutical ingredient production. Stakeholders must monitor how regulatory divergence between prescription and OTC pathways reshapes portfolio allocation and geographic prioritization.
Market Dynamics
The FDA's 2016 OTC conversion pathway for adapalene 0.1% gel has permanently altered competitive entry economics, eroding prescription gatekeeping while forcing incumbents to defend margin through formulation differentiation and channel control.
Growth Catalysts
- Telehealth normalization:Remote dermatology platforms in the United States are expanding prescription access beyond traditional clinic footprints, accelerating patient acquisition for topical retinoid therapies.
- REACH authorization harmonization:Streamlined chemical safety dossiers across EU member states are reducing time-to-market for adapalene-containing cosmetics and dermocosmetics.
- Humid climate demand concentration:Southeast Asian markets are driving volume preference for gel formulations over cream variants due to patient compliance advantages in tropical conditions.
Market Restraints
- Isotretinoin substitution pressure:Oral retinoid therapy for severe acne is capturing refractory cases that might otherwise escalate to prescription-strength adapalene 0.3%.
- API supply geographic concentration:Active pharmaceutical ingredient synthesis for naphthoic acid derivatives clusters in select East Asian manufacturing zones, creating single-source vulnerability.
- FDA pregnancy category friction:Retained teratogenicity warnings and iPLEDGE-adjacent counseling requirements limit pharmacy automation and self-selection velocity.
Strategic Opportunities
- India dermocosmetic channel expansion:CDSCO's streamlined cosmetic-drug hybrid classification is enabling adapalene inclusion in over-the-counter skincare lines targeting pigmentation and aging.
- Combination therapy protocols:Fixed-dose adapalene-benzoyl peroxide formulations are capturing protocol-driven prescribing in institutional dermatology settings.
- Subscription pharmacy models:Direct-to-consumer platforms are bypassing traditional wholesale distribution, capturing recurring revenue through automated refill algorithms.
Industry Challenges
- Photostability formulation expertise scarcity:Retinoid degradation chemistry requires specialized analytical capabilities that contract development organizations struggle to staff at scale.
- Cross-border pharmacovigilance integration:EMA's expanded adverse event reporting for topical retinoids demands harmonized data infrastructure across multi-national trial programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adapalene Market |
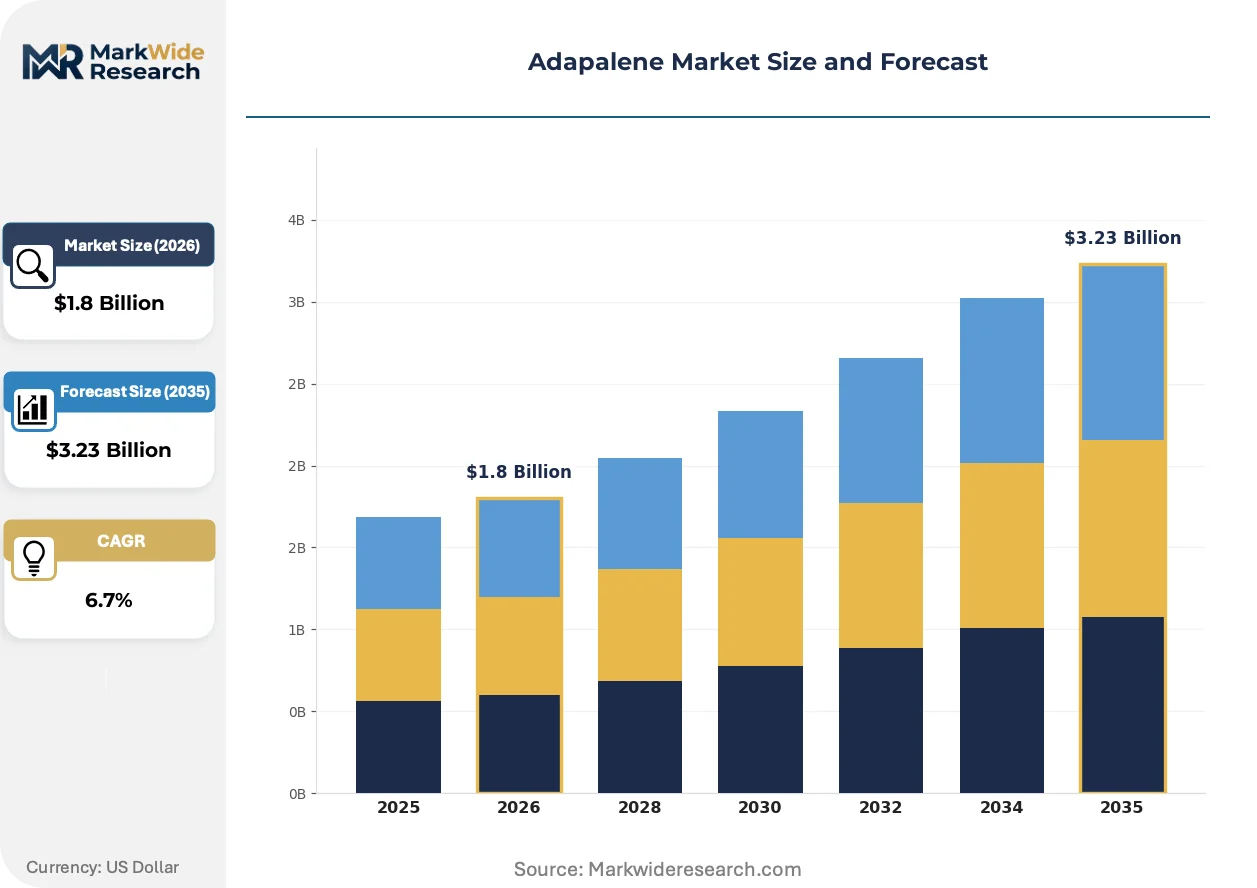
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Cream, Lotion, Solution End User: Dermatology Clinics, Hospitals, Retail Pharmacies, Online Pharmacies Formulation Type: Prescription, Over-the-Counter, Topical, Combination Distribution Channel: Direct Sales, Wholesalers, E-Commerce, Distributors |
| Companies Covered | Galderma Laboratories, Teva Pharmaceutical Industries, Johnson & Johnson, Sandoz, Glenmark Pharmaceuticals, Sun Pharmaceutical, Bausch Health, Mylan, Zydus Cadila, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adapalene Market Strategic Shifts
Formulation science and distribution architecture are diverging from legacy dermatology commercial models, creating asymmetric advantage for players controlling both polymer chemistry and patient data infrastructure.
Microencapsulated retinoid delivery systems are fragmenting conventional efficacy-permeability tradeoffs in topical acne therapy. Galderma and specialty generic houses are embedding adapalene within lipid-shell matrices to reduce irritation profiles and enable daytime wear. This technology is compressing the historical gel-versus-cream segmentation by delivering cream tolerability with gel cosmetic elegance.
EMA's 2023 revision to cosmetic ingredient safety assessment guidelines is tightening concentration thresholds for retinoid-class compounds in borderline products. Manufacturers must now submit extended dermal absorption data for adapalene concentrations above 0.05% in cosmetic formulations. French and German national competent authorities are enforcing these standards most aggressively, delaying market entry for non-compliant skincare lines.
Patient-initiated therapy selection is displacing physician-directed prescribing for mild-to-moderate acne. United States consumers are self-diagnosing through algorithmic skin assessment tools and purchasing adapalene through Amazon Pharmacy and CVS digital channels. This behavior concentrates in suburban markets with limited dermatologist density, where convenience overrides insurance-mediated cost differentials.
Adapalene Market Segmentation
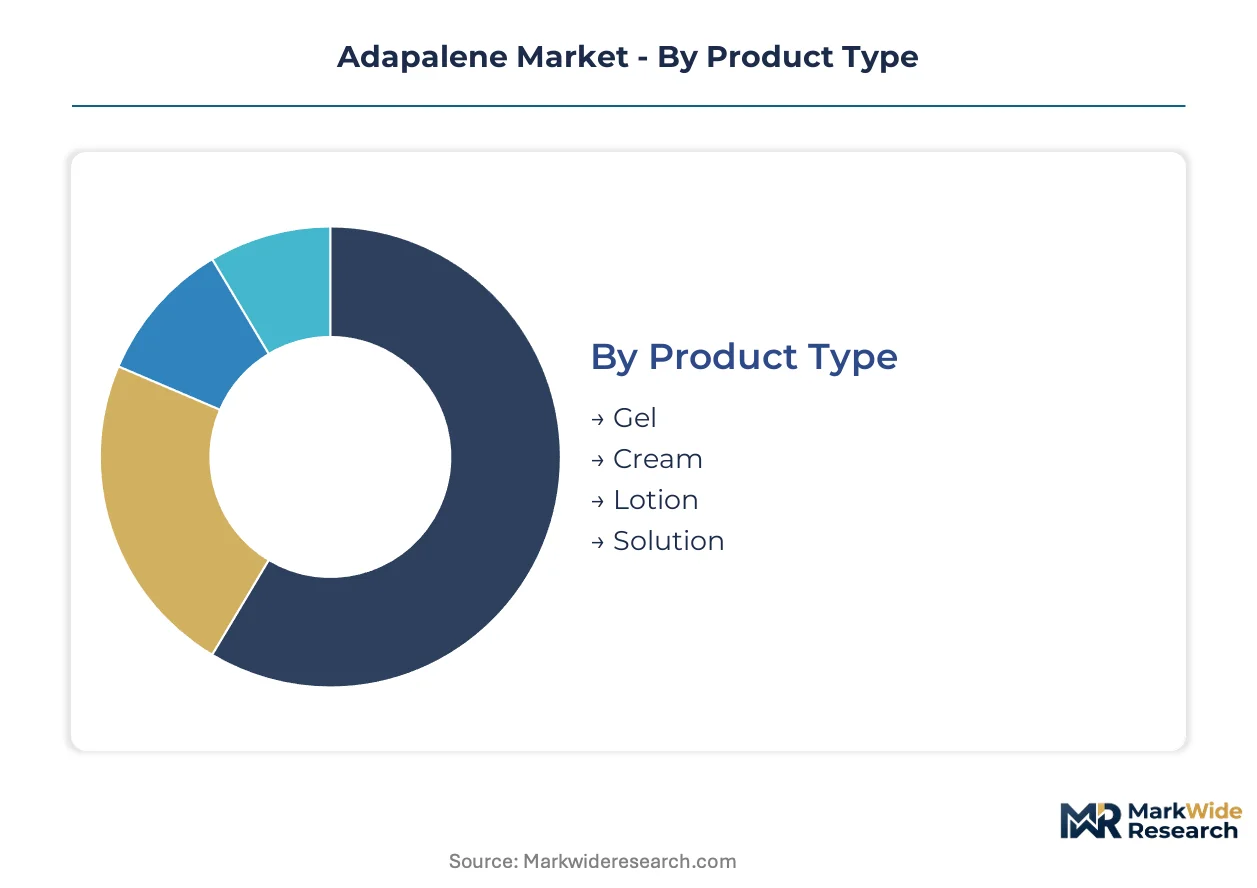
Adapalene's commercial architecture fragments across formulation chemistry, patient access pathways, and procurement infrastructure. Each segmentation axis reveals distinct margin profiles and competitive moats that determine where pharmaceutical manufacturers allocate R&D and sales resources.
Product Type:
Gel formulations flow through humid-climate dermatology clinics and Southeast Asian retail channels, while cream variants concentrate in temperate-zone hospital formularies where tolerability drives protocol selection.
- Gel:Hydrous carbomer-based matrices suspend 0.1% or 0.3% adapalene with rapid drying kinetics suited to tropical climates. Demand clusters in Southeast Asian markets and younger demographics where cosmetic elegance overrides insurance coverage gaps.
- Cream:Emollient-stabilized oil-in-water formulations reduce transepidermal water loss and irritation incidence. Hospital procurement in Germany and France favors this vehicle for combination therapy protocols requiring prolonged contact time.
- Lotion:Fluid emulsion systems enable scalp and trunk application beyond facial acne. Prescription compounding pharmacies in the United States stock this format for off-label keratosis pilaris management.
- Solution:Hydroalcoholic vehicles deliver rapid penetration for oily skin phenotypes. Limited commercial presence reflects photostability challenges and patient preference for gel cosmetic feel.
Gel dominates installed base. Cream is where expansion concentrates as microencapsulation technologies compress tolerability differentials.
End User:
Procurement authority and reimbursement architecture determine which patient touchpoints capture adapalene volume, with telehealth platforms disrupting traditional clinic gatekeeping.
- Dermatology Clinics:Institutional prescribing anchors premium 0.3% prescription volumes and fixed-dose combination protocols. Galderma's Epiduo franchise concentrates here through protocol-driven adoption in academic medical centers.
- Hospitals:Formulary committees control access for severe or refractory cases requiring specialist oversight. German Krankenhaus procurement favors cream vehicles for inpatient acne management.
- Retail Pharmacies:OTC 0.1% gel conversion has shifted volume toward CVS, Walgreens, and Boots storefronts where pharmacist counseling substitutes for physician diagnosis. Pregnancy warning signage requirements vary by state and national jurisdiction.
- Online Pharmacies:Amazon Pharmacy, Ro Health, and Hims platforms bypass traditional wholesale distribution through automated refill algorithms. This channel is expanding most quickly in suburban United States markets with dermatologist access deficits.
Retail pharmacies dominate installed base. Online pharmacies are where expansion concentrates.
Formulation Type:
Regulatory pathway classification determines labeling obligations, distribution restrictions, and margin structure across the adapalene portfolio.
- Prescription:0.3% concentration and combination products require physician authorization and carry teratogenicity warnings. FDA REMS-adjacent counseling requirements limit pharmacy automation velocity.
- Over-the-Counter:FDA's 2016 monograph approval for 0.1% gel removed prescription gatekeeping. CVS and Walgreens shelf placement competes with benzoyl peroxide and salicylic acid alternatives.
- Topical:Monotherapy formulations dominate volume but face substitution pressure from oral isotretinoin for severe cases. EMA pharmacovigilance requirements mandate extended adverse event reporting.
- Combination:Fixed-dose adapalene-benzoyl peroxide products capture protocol-driven institutional prescribing. Manufacturing complexity and API stability requirements create formulation expertise barriers.
Prescription dominates installed base. Over-the-Counter is where expansion concentrates.
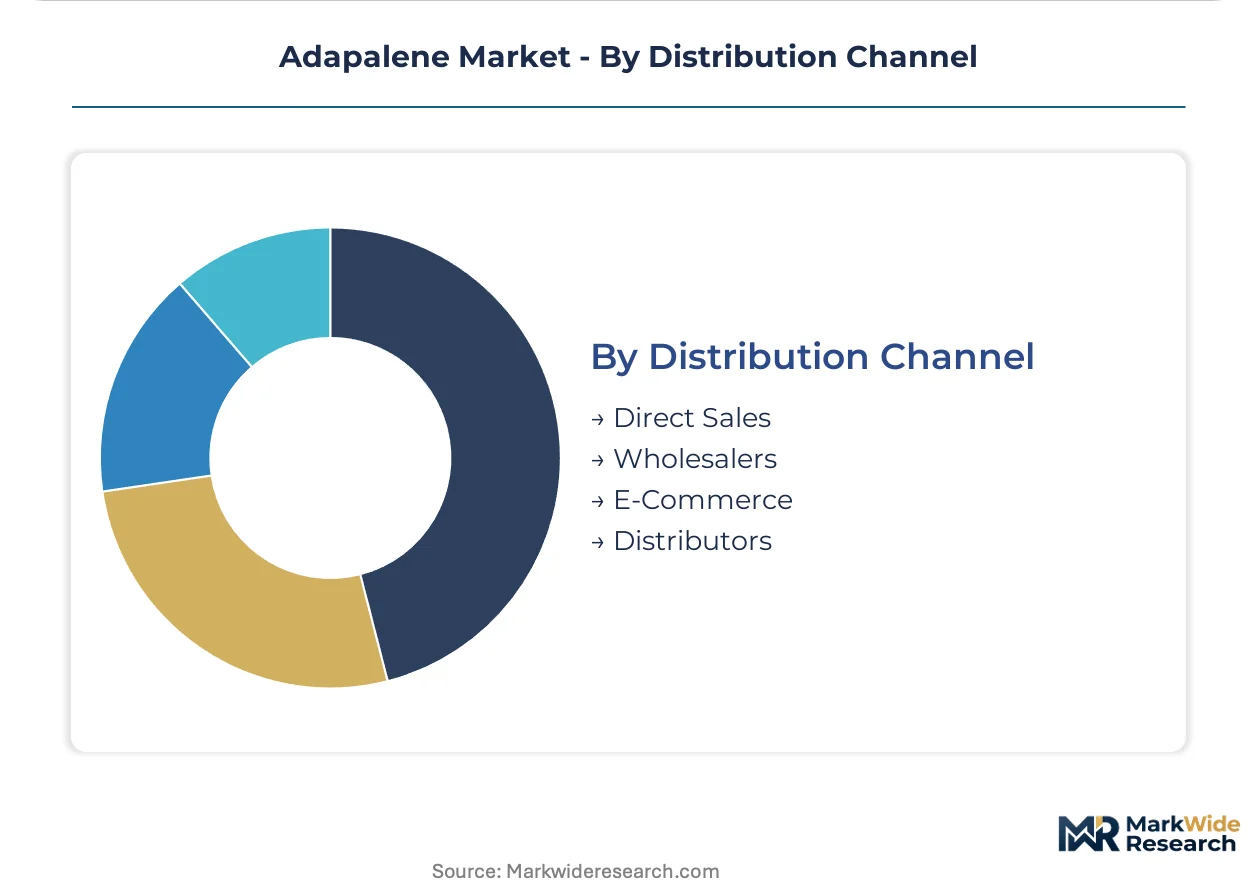
Distribution Channel:
Supply chain configuration determines geographic reach, inventory carrying costs, and patient acquisition economics for adapalene manufacturers.
- Direct Sales:Galderma deploys dedicated dermatology salesforces to academic medical centers and large clinic networks. Relationship depth sustains premium positioning against generic erosion.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health aggregate demand for retail pharmacy fulfillment. Inventory concentration creates working capital intensity for manufacturers.
- E-Commerce:Amazon Pharmacy, Dermstore, and brand-direct subscription models capture recurring revenue through automated replenishment. This channel is gaining share fastest in direct-to-consumer skincare segments.
- Distributors:Regional pharmaceutical distributors serve emerging markets where cold-chain requirements and import licensing fragment logistics. Price sensitivity in India and Brazil concentrates volume in economy-tier generics.
Wholesalers dominate installed base. E-Commerce is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for adapalene varies sharply across geographies. United States consumers absorb premium pricing for branded formulations, while Indian and Brazilian buyers gravitate toward economy-tier generics. European markets occupy a middle ground where reimbursement status determines access velocity.
United States
Telehealth platforms and direct-to-consumer pharmacy models accelerate patient acquisition beyond traditional dermatology clinic footprints. FDA's 2016 OTC monograph conversion for 0.1% gel removed prescription gatekeeping, shifting volume toward CVS, Walgreens, and Amazon Pharmacy channels. Suburban markets with limited dermatologist density concentrate self-directed purchasing behavior.
Germany
Hospital formulary committees favor cream vehicles for inpatient acne management and combination therapy protocols. EMA pharmacovigilance requirements mandate extended adverse event reporting for topical retinoids, tightening compliance obligations. The Rhine-Ruhr industrial corridor hosts API synthesis facilities serving European formulation manufacturers.
India
Price sensitivity dominates purchasing decisions as patients bypass prescription channels for over-the-counter dermocosmetic alternatives. CDSCO's streamlined cosmetic-drug hybrid classification enables adapalene inclusion in skincare lines targeting pigmentation and aging. Mumbai and Ahmedabad anchor generic manufacturing clusters supplying domestic and export markets.
Brazil
Humid climate conditions drive gel formulation preference among younger demographics seeking cosmetic elegance. ANVISA regulates topical retinoid concentrations and labeling requirements, creating entry barriers for non-compliant imports. São Paulo's pharmaceutical distribution infrastructure serves as the regional logistics hub for Latin American markets.
Japan
PMDA oversight maintains strict concentration limits and pregnancy warning standards for retinoid-class compounds. Microencapsulation technologies gain traction among manufacturers seeking to reduce irritation profiles and enable daytime wear. Osaka-based formulation specialists supply polymer chemistry expertise to regional skincare brands.
Adapalene Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in adapalene supply. The market structures around vertically integrated dermatology specialists, aggressive generic penetrators, and emerging-market distribution specialists. Three archetypes dominate: premium-formulation innovators, high-volume generic manufacturers, and region-anchored distributors. Competitive moves concentrate on formulation differentiation through microencapsulation chemistry and channel control via direct-to-consumer platforms.
Within the premium-formulation tier, Galderma Laboratories occupies a position exemplifying dermatology-focused vertical integration. Among generic penetrators, Teva Pharmaceutical Industries and Sandoz represent archetypes of scale-driven cost leadership. Glenmark Pharmaceuticals sits within the emerging-market specialist tier, anchoring distribution capabilities where price sensitivity shapes procurement decisions.
| Leading Market Players |
|---|
| Galderma Laboratories |
| Teva Pharmaceutical Industries |
| Johnson & Johnson |
| Sandoz |
| Glenmark Pharmaceuticals |
| Sun Pharmaceutical |
| Bausch Health |
| Mylan |
| Zydus Cadila |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between East Asian API manufacturers and European formulation houses lock in both naphthoic acid derivative supply access and multi-year price visibility for adapalene gel and cream production. These arrangements insulate branded players from spot-market volatility while exposing generic manufacturers to raw material cost swings.
Pricing Analysis
Subscription pharmacy refill programs drive lifetime value beyond the initial OTC gel purchase. Three-tier pricing structure across premium, standard, and economy levels separates Galderma's microencapsulated formulations from Teva's generic 0.1% gel and Indian private-label alternatives. Pricing pressure stems from isotretinoin substitution for severe acne cases. Hospital procurement committees in Germany exhibit lowest price sensitivity; retail pharmacy shoppers in India exhibit highest.
Supply Chain Analysis
Inventory lead times for naphthoic acid derivatives stretch to six months due to batch synthesis complexity and analytical release protocols. Active pharmaceutical ingredient production clusters in China, India, and South Korea. Formulation depends on carbomer polymers, emollient bases, and lipid-shell matrices for microencapsulation. Single-source vulnerability concentrates in select East Asian manufacturing zones for retinoid synthesis intermediates. Distribution runs through McKesson and AmerisourceBergen for United States retail pharmacy fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adapalene's service-attach opportunity centers on automated subscription refill algorithms, which expand recurring revenue faster than one-time prescription or OTC transactions. Direct-to-consumer platforms capture patient data infrastructure that feeds formulation development and targeted marketing.
For Market Incumbents: Consolidate formulation expertise barriers around microencapsulation chemistry and photostability analytics to defend against generic erosion. Acquire or partner with telehealth platforms to control patient acquisition channels. Lock in API supply through backward integration into East Asian synthesis facilities or captive offtake agreements. For New Entrants and Emerging Players: Lead with dermocosmetic positioning in India's CDSCO-hybrid regulatory pathway, where adapalene inclusion in anti-aging skincare lines faces lower entry barriers than prescription channels. Target suburban United States markets with dermatologist access deficits through Amazon Pharmacy and Hims-style subscription models. Emphasize algorithmic skin assessment tools for patient self-diagnosis. For Investors and Strategic Acquirers: Specialty contract development organizations with retinoid formulation capabilities represent the most attractive acquisition archetype, given scarcity of photostability expertise and polymer chemistry talent. Monitor FDA pregnancy warning standard revisions as the critical inflection signal for pharmacy automation velocity and OTC self-selection economics.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables daytime wear formulations that compress gel-cream segmentation for humid climate markets. |
| Telehealth Platform Partnership | Captures suburban patient acquisition beyond traditional dermatology clinic footprints. |
| API Synthesis Facility Acquisition | Secures captive supply of naphthoic acid derivatives against East Asian concentration risk. |
| Subscription Pharmacy Infrastructure | Builds recurring revenue through automated refill algorithms and patient data capture. |
| CDSCO Cosmetic-Drug Hybrid Registration | Unlocks India's dermocosmetic channel for adapalene inclusion in anti-aging skincare lines. |
Study Parameters
Desk research of FDA OTC monograph filings, EMA pharmacovigilance databases, and CDSCO cosmetic-drug classification precedents preceded structured interviews with dermatology clinic procurement directors, generic pharmaceutical manufacturing executives, and telehealth platform operations leads. Secondary validation drew from formulary databases, hospital procurement records, and e-commerce channel transaction data. Bottom-up patient volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Variance decomposition across formulation type, end-user channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and price elasticity assumptions. Forecast inputs included telehealth adoption curves, OTC conversion velocity, and microencapsulation technology penetration rates.
Forecasts assume regulatory continuity in FDA OTC pathways and EMA retinoid safety standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Mtor Inhibitors Market